
 Global Tunneling and Rock Drilling Equipment Market | 2026-2036
Global Tunneling and Rock Drilling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tunneling and Rock Drilling Equipment Market Analysis
The buyer base for tunneling and rock drilling equipment is broadening beyond traditional state-owned contractors to include private infrastructure funds and specialized urban transit consortiums. Komatsu Ltd leverages its integrated powertrain manufacturing to serve hybrid-electric tunnel boring machine demand across Japanese and Southeast Asian projects. Sandvik AB anchors its position through captive supply of hardened drill steels and automated drilling control systems for hard-rock mining applications. Herrenknecht AG specializes in large-diameter TBM customization for subaqueous and high-pressure geology conditions.
Global tunneling and rock drilling equipment encompasses mechanized excavation and penetration machinery engineered to cut, bore, and blast through rock and soil matrices, typically operating at cutterhead torques exceeding 5,000 kNm and thrust forces above 100,000 kN for large-diameter TBMs. The primary industrial purpose centers on creating stable underground passages for transportation, resource extraction, and utility corridors with minimal surface disruption. Tunnel Boring Machines command the dominant value share given capital intensity and project-specific engineering, while Drilling Rigs in the mining end-user segment represent the fastest-growing category as copper and critical mineral exploration deepens. Electric technology within the technology dimension is capturing expanding share as tunnel ventilation constraints and underground emissions regulations tighten operational requirements for diesel alternatives.
The US EPA and OSHA impose stringent underground diesel particulate limits and confined-space safety protocols that elevate equipment compliance costs and filter technology specifications. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive shape refrigerant choices in TBM conditioning systems and overall equipment certification pathways for European deployment. China's GB standards and MIIT equipment certification govern domestic procurement and create non-tariff entry barriers for foreign suppliers. Stakeholders must monitor how accelerating electrification mandates across multiple regulatory jurisdictions reshape R&D allocation and supplier qualification timelines for contract eligibility.
Market Dynamics
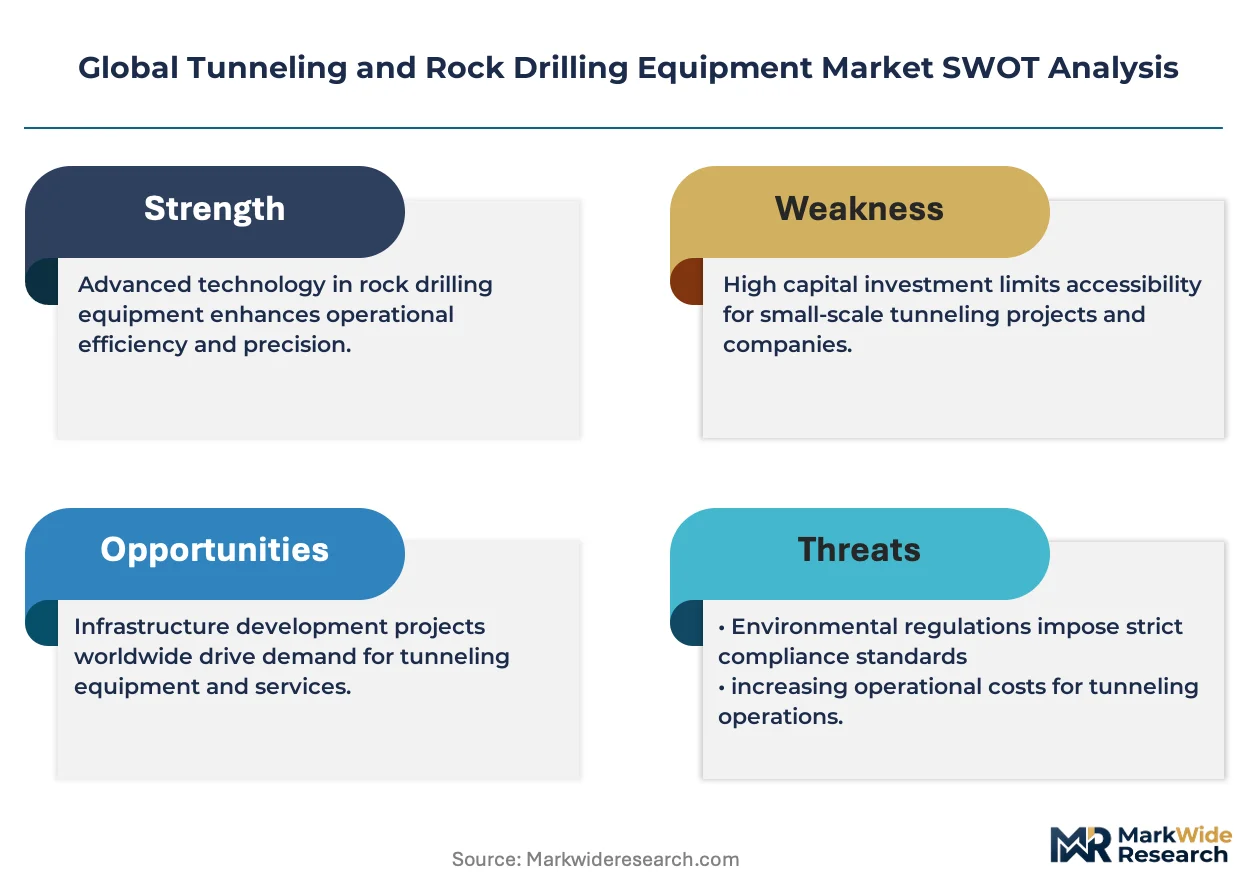
The tunneling and rock drilling equipment sector is undergoing a fundamental powertrain transition as electrification mandates from the EPA and EU F-Gas Regulation force diesel displacement in underground environments. This regulatory pressure is compressing equipment replacement cycles and redrawing supplier qualification criteria across procurement offices.
Growth Catalysts
- Urban Metro Expansion:Underground transit corridors in congested metropolitan zones are accelerating TBM deployment timelines. China's high-speed rail tunnel projects and India's Himalayan hydropower schemes concentrate equipment demand.
- Critical Mineral Exploration:Copper and battery metal extraction is deepening hard-rock mining operations. Automated drilling control systems are penetrating frontier deposits previously deemed uneconomical.
- EU F-Gas Regulation:Refrigerant phase-down mandates in TBM conditioning systems are forcing equipment refresh cycles. European tunnel ventilation standards are tightening permissible diesel particulate thresholds underground.
Market Restraints
- Hardened Steel Supply Concentration:Drill steel production clusters in select European and Asian metallurgical centers. Geopolitical friction threatens seamless alloy supply for consumable tooling.
- Project Finance Fragility:Large-diameter TBM procurement requires multi-year capital commitments. Infrastructure fund liquidity constraints delay contract awards during rate volatility.
- Technical Limitation in High-Pressure Geology:Subaqueous tunneling faces cutterhead seal reliability thresholds. Water ingress risks elevate insurance and contingency costs for underwater segments.
Strategic Opportunities
- Hybrid-Electric Architecture:Battery-tethered TBMs converge with regenerative braking systems. Japanese and Southeast Asian projects are piloting reduced-ventilation tunnel segments.
- Service Contract Unbundling:Predictive maintenance analytics separate from equipment sale. Mining operators in Chile and Peru are trialing telemetry-based component replacement.
- CE Marking Pathway Acceleration:EU Machinery Directive compliance automation reduces certification timelines. Modular TBM designs enable faster European market entry for non-EU suppliers.
Industry Challenges
- TBM Operator Skill Scarcity:Cutterhead torque management and steering geology interpretation require specialized training. Workforce pipelines lag equipment complexity advances.
- Cross-Border Certification Friction:China's GB standards and MIIT equipment certification create non-tariff barriers. Foreign suppliers face duplicated testing for domestic procurement eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tunneling and Rock Drilling Equipment Market |
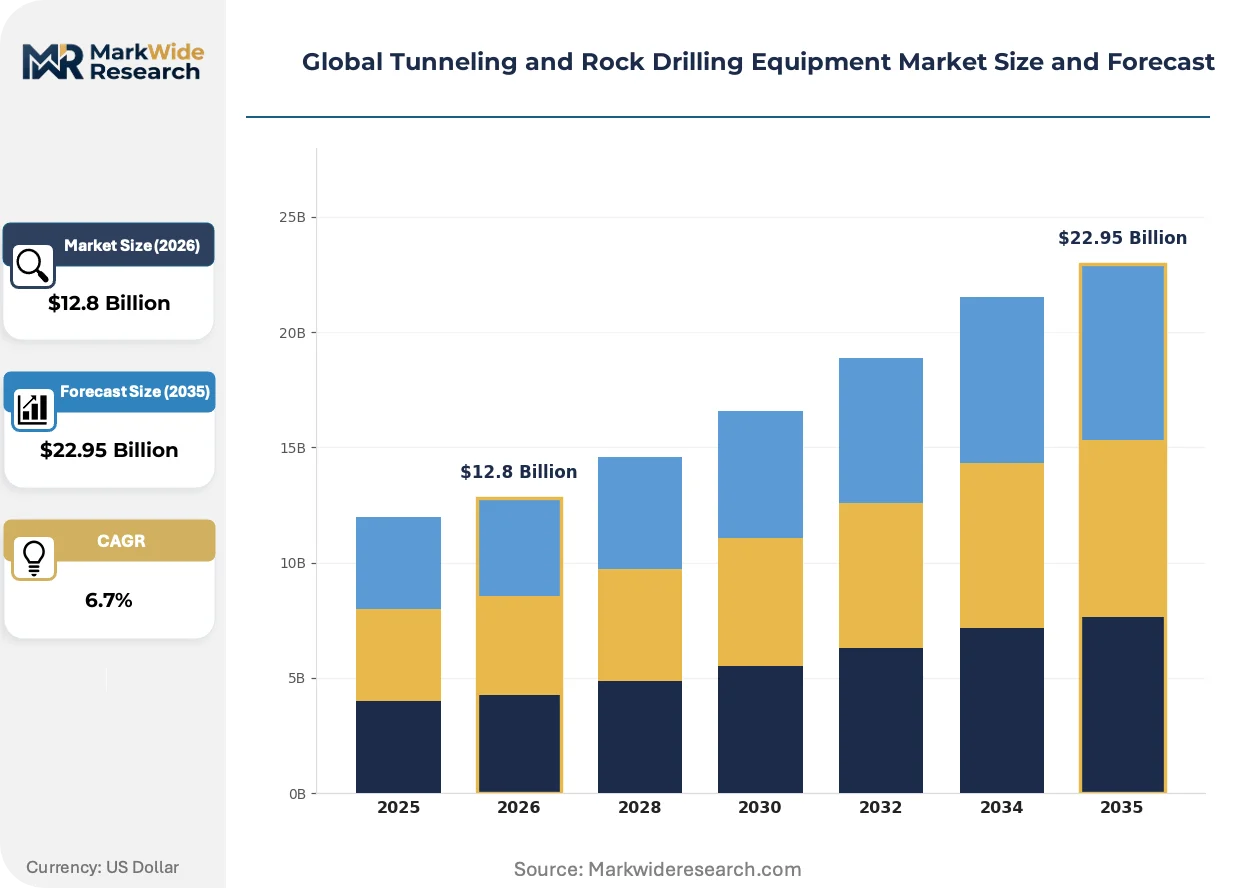
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Tunnel Boring Machines, Continuous Miners, Roadheaders, Drilling Rigs End User: Construction, Mining, Oil & Gas, Utility Services Technology: Mechanical, Hydraulic, Pneumatic, Electric Operation Mode: Automated, Semi-Automated, Manual, Remote-Controlled |
| Companies Covered | Komatsu Ltd, Hitachi Construction Machinery Co Ltd, Atlas Copco AB, SANY Group Co Ltd, China Railway Engineering Equipment Group Co Ltd, Sandvik AB, Herrenknecht AG, Epiroc AB, Caterpillar Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tunneling and Rock Drilling Equipment Market Emerging Trajectories
Electrification architectures and automated drilling intelligence are compressing operational parameters across underground construction and resource extraction. Equipment specifications now prioritize emissions compliance and remote operability alongside mechanical performance metrics.
Regenerative energy capture systems in hybrid-electric TBMs are rewriting underground power management. Mining contractors in Scandinavia and alpine tunneling consortia are deploying these systems to reduce ventilation infrastructure requirements. The technology is compressing total project energy footprints while extending permissible operating depths before atmospheric constraints trigger.
The EU F-Gas Regulation and EPA diesel particulate limits are tightening refrigerant and exhaust specifications simultaneously. Equipment manufacturers must redesign thermal management and powertrain architectures within compressed development windows. Underground metro projects in Germany and California are imposing dual compliance as baseline bid eligibility.
Consortium-based procurement is fragmenting traditional state-contractor relationships. Private infrastructure funds and specialized urban transit vehicles are displacing single-source government awards in Australia and Canada. This pattern concentrates specification influence with financial sponsors who prioritize asset lifecycle cost over initial capital outlay.
Global Tunneling and Rock Drilling Equipment Market Segmentation
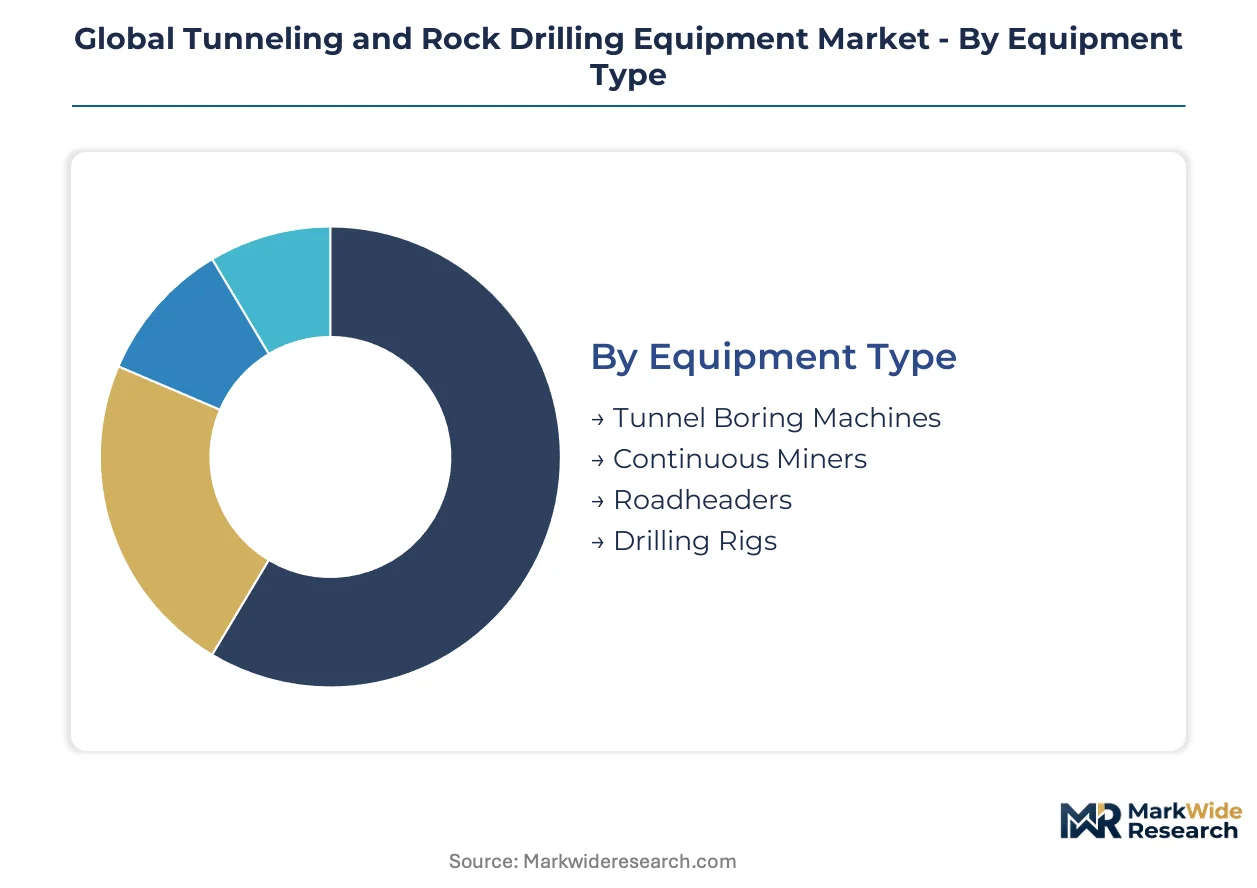
Segmentation in tunneling and rock drilling equipment reveals how capital allocation, regulatory pressure, and geology complexity fragment procurement specifications. Equipment buyers balance mechanical performance against ventilation constraints and automation readiness across project portfolios.
Equipment Type:
Standalone systems dominate high-capital project deployments, while embedded cutting heads integrate into continuous production lines in mining operations.
- Tunnel Boring Machines:Large-diameter cutterheads exceeding 5,000 kNm torque operate as self-contained excavation systems. China's high-speed rail tunnel projects and subaqueous metro corridors in Japan concentrate procurement of customized TBM architectures with high-pressure seal specifications.
- Drilling Rigs:Automated drilling control systems penetrate hard-rock deposits at depths previously uneconomical. Copper and battery metal exploration in Chile and Peru drives fastest-category expansion as frontier deposits attract capital.
- Continuous Miners:Integrated cutting-loading-haulage systems serve underground coal and soft-rock operations. South African and Australian longwall operations standardize on these embedded production units.
- Roadheaders:Boom-mounted cutting heads excel in variable geology with immediate ground support requirements. Urban utility tunneling in Germany and Switzerland specifies these for mixed-face conditions.
Tunnel Boring Machines lead volumes today; Drilling Rigs are gaining share fastest.
End User:
Cost tier stratification separates project-financed mega-infrastructure from operational-expense mining fleets and utility maintenance budgets.
- Construction:Metro expansion and rail tunnel projects command multi-year capital commitments with consortium-based procurement. Underground transit corridors in congested metropolitan zones accelerate replacement cycles.
- Mining:Hard-rock extraction operations prioritize consumable tooling supply security and predictive maintenance contracts. Copper exploration deepening in Himalayan corridors and Andean deposits concentrates equipment demand.
- Oil & Gas:Directional drilling and cavern storage applications require pressure-rated systems. Salt dome storage projects in the US Gulf Coast and European LNG facilities specify hardened steel specifications.
- Utility Services:Water, sewer, and power cable tunneling operates on municipal procurement cycles with compressed lead times. Urban renewal programs in Australia and Canada fragment traditional state-contractor relationships.
Construction dominates absolute spend; Mining shows steepest expansion trajectory.
Technology:
Maturity curves separate proven mechanical architectures from emerging electric powertrains facing compressed regulatory compliance windows.
- Electric:Battery-tethered and cable-electric systems eliminate diesel particulate emissions in confined underground spaces. EU F-Gas Regulation and EPA underground emissions standards accelerate displacement of combustion powertrains.
- Hydraulic:High-pressure fluid systems deliver precise force control for cutterhead steering and drill feed mechanisms. Established installed base in hard-rock mining maintains segment presence despite electrification pressure.
- Mechanical:Direct-drive cutterheads and rotary drilling systems persist in standardized geology applications. Lower capital cost sustains relevance in developing market procurement.
- Pneumatic:Compressed-air drilling systems serve explosive atmospheres and remote maintenance scenarios. Niche utility in gassy mine environments and temporary construction access.
Hydraulic systems anchor current installed base; Electric is climbing the fastest.
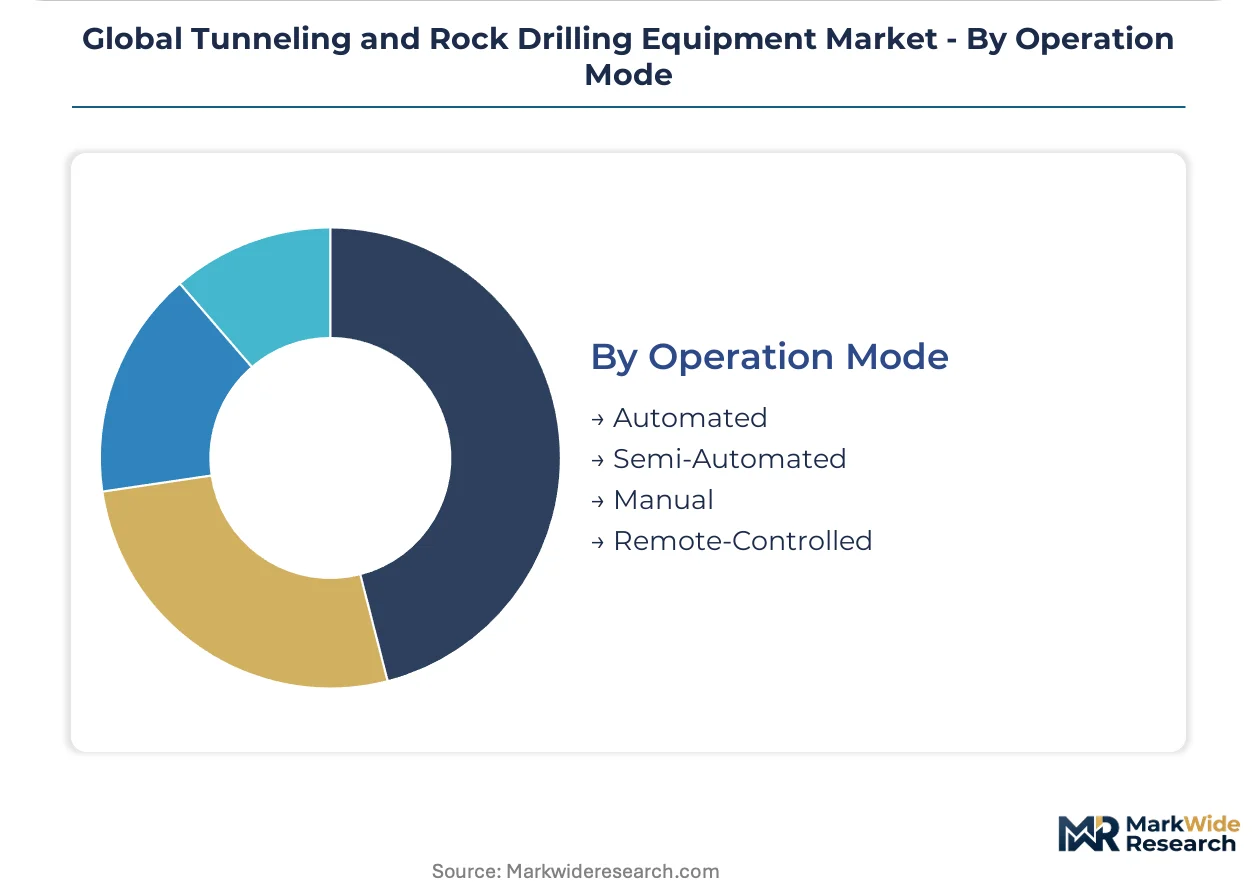
Operation Mode:
Customer type differentiation separates autonomous fleet operators from contractor labor models and specialized remote-service providers.
- Automated:Closed-loop steering and cutterhead torque management reduce operator skill dependency. Scandinavian mining contractors deploy these systems to offset workforce pipeline gaps.
- Remote-Controlled:Telerobotic operation removes personnel from hazardous face conditions and unstable ground zones. Subaqueous tunneling and high-pressure geology segments specify these for water ingress risk mitigation.
- Semi-Automated:Operator-supervised automation balances productivity gains with geological interpretation requirements. Japanese and Southeast Asian projects pilot these for reduced-ventilation tunnel segments.
- Manual:Direct operator control persists in small-diameter drilling and maintenance applications. Lower technology cost sustains presence in fragmented contractor markets.
Semi-Automated systems hold plurality share; Automated is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates high-speed rail tunnel procurement while India accelerates Himalayan hydropower equipment orders. Divergent regulatory timelines between EPA diesel mandates and EU F-Gas phase-downs are compressing supplier certification windows across both markets.
China
High-speed rail tunnel projects and urban metro corridors drive equipment procurement at scale. MIIT equipment certification and GB standards govern domestic procurement eligibility. Yangtze River Delta manufacturing clusters supply cutterhead assemblies for domestic and Southeast Asian deployment.
India
Himalayan hydropower schemes and urban transit expansion concentrate demand in hard-rock geology applications. CEA technical standards and BIS certification requirements shape equipment import protocols. Mumbai-Delhi metro corridors accelerate TBM deployment timelines with consortium-based financing.
Germany
Subaqueous tunneling projects and alpine transit corridors demand high-pressure seal specifications. EU F-Gas Regulation and CE marking under the Machinery Directive condition refrigerant choices in TBM thermal systems. Ruhr industrial basin clusters anchor hardened steel tooling production for European consumption.
United States
EPA underground diesel particulate limits and OSHA confined-space protocols elevate filter technology specifications. Salt dome storage projects along the Gulf Coast and California metro expansion drive pressure-rated system demand. Pacific Northwest hydropower tunnels specify remote-operated drilling architectures.
Australia
Copper and critical mineral exploration in Western Australia deepens hard-rock mining operations. State-level mining safety regulations and federal environmental approvals compress project timelines. Perth-based contractor consortia pilot telemetry-based predictive maintenance contracts for frontier deposits.
Global Tunneling and Rock Drilling Equipment Market Vendor Landscape
German and Japanese producers anchor one tier; Chinese state-affiliated fabricators hold volume positions in domestic procurement. The vendor base stratifies across integrated powertrain manufacturers, specialized TBM engineering houses, and consumable tooling suppliers. Three archetypes dominate: hybrid-electric system integrators, hard-rock drilling automation specialists, and large-diameter customization engineers. Competitive moves center on captive supply of hardened alloys and accelerated CE marking pathway automation.
Among Japanese integrated manufacturers, Komatsu Ltd represents hybrid-electric powertrain convergence for reduced-ventilation tunnel segments. German engineering specialists Herrenknecht AG occupy a position in large-diameter TBM customization for subaqueous and high-pressure geology. Swedish tooling and automation group Sandvik AB exemplifies the consumable supply and drilling control systems archetype for hard-rock mining applications.
| Leading Market Players |
|---|
| Komatsu Ltd |
| Hitachi Construction Machinery Co Ltd |
| Atlas Copco AB |
| SANY Group Co Ltd |
| China Railway Engineering Equipment Group Co Ltd |
| Sandvik AB |
| Herrenknecht AG |
| Epiroc AB |
| Caterpillar Inc |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation refrigerant phase-down mandates are forcing equipment refresh cycles that compress supplier lead times and elevate certification-grade pricing premiums for compliant TBM thermal systems. Buyers now bundle electrification specifications with procurement contracts, compelling manufacturers to absorb powertrain redesign costs or cede share to hybrid-electric specialists.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for cutterhead assemblies and standard TBM subsystems. Project-based contract pricing dominates mega-infrastructure procurement, with differentiation driven by CE marking compliance tier and captive hardened steel supply. Cost compression in economy-tier mechanical-drive equipment is intensifying because Chinese state-affiliated fabricators leverage domestic GB certification to bypass import duties. Mining contractors in Chile and Peru exhibit highest price sensitivity due to commodity cycle exposure, while subaqueous metro consortia in Japan tolerate premium positioning for high-pressure seal reliability.
Supply Chain Analysis
Dual-sourcing requirements from European tunneling consortia and Australian mining operators mandate multi-supplier qualification for hardened drill steels and cutterhead components. Geographic concentration centers on Germany's Ruhr industrial basin for alloy tooling, China's Jiangsu province for hydraulic powertrain assemblies, and Sweden for automated drilling control systems. Raw material dependencies draw from high-grade tungsten carbide deposits, specialty steel alloys, and rare-earth elements for electric motor magnets. Single-source vulnerability persists in subaqueous seal engineering expertise. Distribution runs through OEM-direct channels for large-diameter TBMs and authorized dealer networks for mining rig aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through divergent electrification compliance costs: EPA diesel retrofit mandates impose steeper operational penalties on US fleet operators than EU F-Gas thermal system redesigns, creating margin capture opportunities for hybrid-electric suppliers with dual-certification capability.
For Market Incumbents: Acquire captive hardened steel production capacity to secure consumable tooling supply against alloy price volatility and geopolitical friction. Komatsu Ltd and Sandvik AB should expand MIIT certification investment for Chinese procurement eligibility as domestic fabricators capture high-speed rail tunnel share. Prioritize backward integration into battery powertrain assembly to defend margin position from emerging electric specialists. For New Entrants and Emerging Players: Premium-to-economy price gaps in mid-scale drilling rig categories create entry space for automated semi-electric architectures. Target Chilean and Peruvian copper exploration contractors with telemetry-based predictive maintenance bundling. Pursue white-label CE marking pathway acceleration services for non-EU TBM fabricators seeking European metro contract eligibility. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid-electric powertrain integrators possessing dual EPA-EU certification capability and established service contract revenue streams. Long-term viability over a five-to-ten year window favors suppliers with backward integration into cutterhead metallurgy and regenerative braking intellectual property. Monitor EPA diesel particulate threshold tightening announcements as inflection signal for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardened Steel Production | Captive alloy supply secures consumable tooling margins against European metallurgical center concentration risk. |
| Dual EPA-EU Certification Investment | Compliance with divergent emissions standards unlocks metro procurement in California and Germany simultaneously. |
| Predictive Maintenance Service Unbundling | Telemetry-based component replacement contracts generate recurring revenue from Chilean mining operators. |
| Hybrid-Electric Powertrain Platform Standardization | Modular battery-tethered architectures reduce ventilation infrastructure costs for Japanese tunnel segments. |
| CE Marking Pathway Automation | Accelerated Machinery Directive compliance reduces certification timelines for Chinese TBM market entry. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged tunnel project engineers, mining maintenance directors, OEM procurement teams at Komatsu Ltd and Herrenknecht AG, aftermarket service heads, and infrastructure fund investment officers. Secondary validation drew from EPA enforcement databases, EU F-Gas Regulation implementation reports, MIIT equipment certification registries, and customs trade data for cutterhead assembly imports. Bottom-up project pipeline aggregation and top-down equipment replacement cycle modeling were triangulated against regional regulatory timeline announcements.
Historical reference periods anchored the projection horizon to documented replacement cycles following prior emissions standard implementations. The analytical framework segmented by equipment type, end-user industry, powertrain technology, and operation mode autonomy level across the modeling period. CAGRs were derived from equipment unit deployment rates and capital expenditure commitments. Industry-specific forecast inputs incorporated high-speed rail tunnel project announcements from China's National Railway Administration and Himalayan hydropower scheme approvals from India's Central Electricity Authority.
The model assumes a particular technology adoption path; alternative pathways for battery-electric TBM penetration would alter the outlook if solid-state battery commercialization accelerates ahead of base-case assumptions. Deviation in EPA diesel particulate enforcement intensity or EU F-Gas refrigerant phase-down timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Horizontal Shaft Impact Crusher Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Global Dozers Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Rock Duster Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Drill Pipe Market