
 Stone Crushing Equipment Market | 2026-2036
Stone Crushing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Crushing Equipment Market Analysis
Aftermarket service contracts encompassing remote diagnostics, wear-part replenishment, and uptime guarantees is shifting how capital equipment economics get evaluated at the point of sale. Sandvik AB leverages its digital fleet-management platform to lock in multi-year maintenance subscriptions alongside crusher deliveries. Komatsu Ltd. anchors its position through backward integration into proprietary hybrid-drive powertrains that cut fuel consumption in quarry cycles. Eagle Crusher Company Inc. specializes in portable, closed-circuit configurations that dominate North American demolition-site contracting.
Stone crushing equipment encompasses machinery engineered to fracture mineral feedstock through compressive, impact, or gyratory force, typically processing material from 500 mm down to sub-50 mm gradations for downstream aggregate use. Jaw crushers deploy a fixed and swing plate to generate crushing pressure, while cone crushers utilize an eccentrically rotating mantle within a concave bowl to achieve finer reduction ratios for asphalt and concrete specification. Jaw crusher installations retain the largest installed base across quarry operations, though cone crusher demand is accelerating fastest where railway ballast and manufactured-sand specifications tighten. Recycling applications now pull dedicated impact crusher configurations as demolition contractors seek to process reinforced concrete on-site rather than haul to fixed plants.
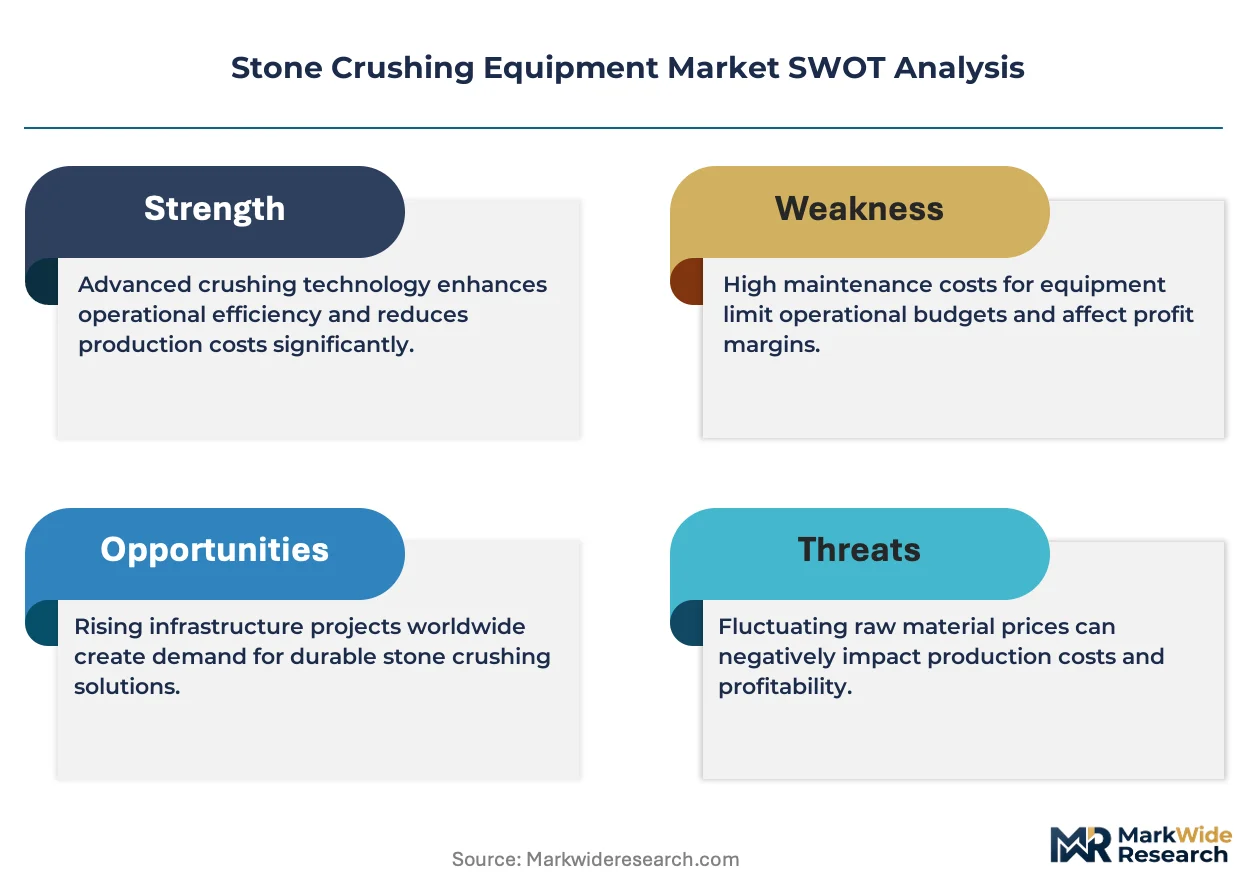
OSHA crystalline silica rules and EPA National Ambient Air Quality Standards are forcing quarry operators to retrofit dust-suppression enclosures or replace older open-chassis models. CE marking under the EU Machinery Directive and forthcoming F-Gas Regulation constraints on mobile equipment refrigerants are reshaping import eligibility for non-European OEMs. Stakeholders must weigh total cost of ownership against upfront capital outlay as regulatory compliance layers compound operational complexity across equipment lifecycles.
Market Dynamics
Quarry operators face a structural inflection where dust-emission compliance costs now rival capital depreciation in total equipment lifecycle economics, compressing replacement cycles and favoring enclosed, sensor-integrated crushing systems over open-chassis legacy installations.
Growth Catalysts
- India National Highway Development:The Bharatmala Pariyojana program is pulling premium-capacity jaw and cone crushers into quarry clusters surrounding Mumbai, Delhi, and Bangalore as contractors race to meet aggregate deadlines for expressway segments.
- EU F-Gas Regulation Phase-Down:Mobile crushing equipment refrigerant constraints are accelerating fleet turnover toward electric-hybrid drive trains that eliminate high-GWP cooling systems entirely from portable units.
- Urban Demolition Waste Streams:Municipalities in São Paulo, Lagos, and Jakarta are mandating on-site concrete processing for decommissioned infrastructure, creating dedicated demand for compact impact crusher configurations with magnetic rebar separation.
Market Restraints
- High-Alloy Wear Part Dependence:Manganese steel liner plates and chromium carbide blow bars face concentrated supply from South African and Australian foundries, exposing operators to freight cost volatility and extended lead times.
- OSHA Silica Compliance Retrofit Burden:Crystalline silica exposure limits force open-pit quarries to install enclosed operator cabins, negative-pressure dust suppression, and real-time particulate monitoring—capital layers that extend payback periods on older crusher assets.
- Stationary Plant Substitution:Centralized mega-quarries with rail-linked distribution networks in Germany and Japan are displacing distributed mobile crushing for large-scale infrastructure projects, compressing demand for portable units in mature markets.
Strategic Opportunities
- Vietnam Infrastructure Build-Out:The North-South Expressway and Long Thanh International Airport are creating first-mover positions for OEMs establishing localized assembly and parts distribution in Ho Chi Minh City industrial zones.
- Remote Diagnostics Convergence:Telematics platforms integrating vibration analysis, oil contamination sensing, and predictive wear modeling are enabling subscription-based uptime guarantees that transform capital sales into recurring revenue streams.
- EU Green Deal Carbon Border Adjustments:Embodied carbon tracking requirements for imported construction materials will favor domestic aggregate production, stimulating crusher demand in quarry-deficit regions like the Netherlands and Belgium.
Industry Challenges
- Mechatronics Skill Scarcity:Maintenance technicians fluent in both hydraulic systems and PLC-controlled automation are concentrated in Western European and North American labor pools, constraining fleet utilization rates in African and Southeast Asian operations.
- CE Marking Certification Timelines:EU Machinery Directive conformity assessment for new crusher designs requires third-party noise and vibration testing that extends product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Crushing Equipment Market |
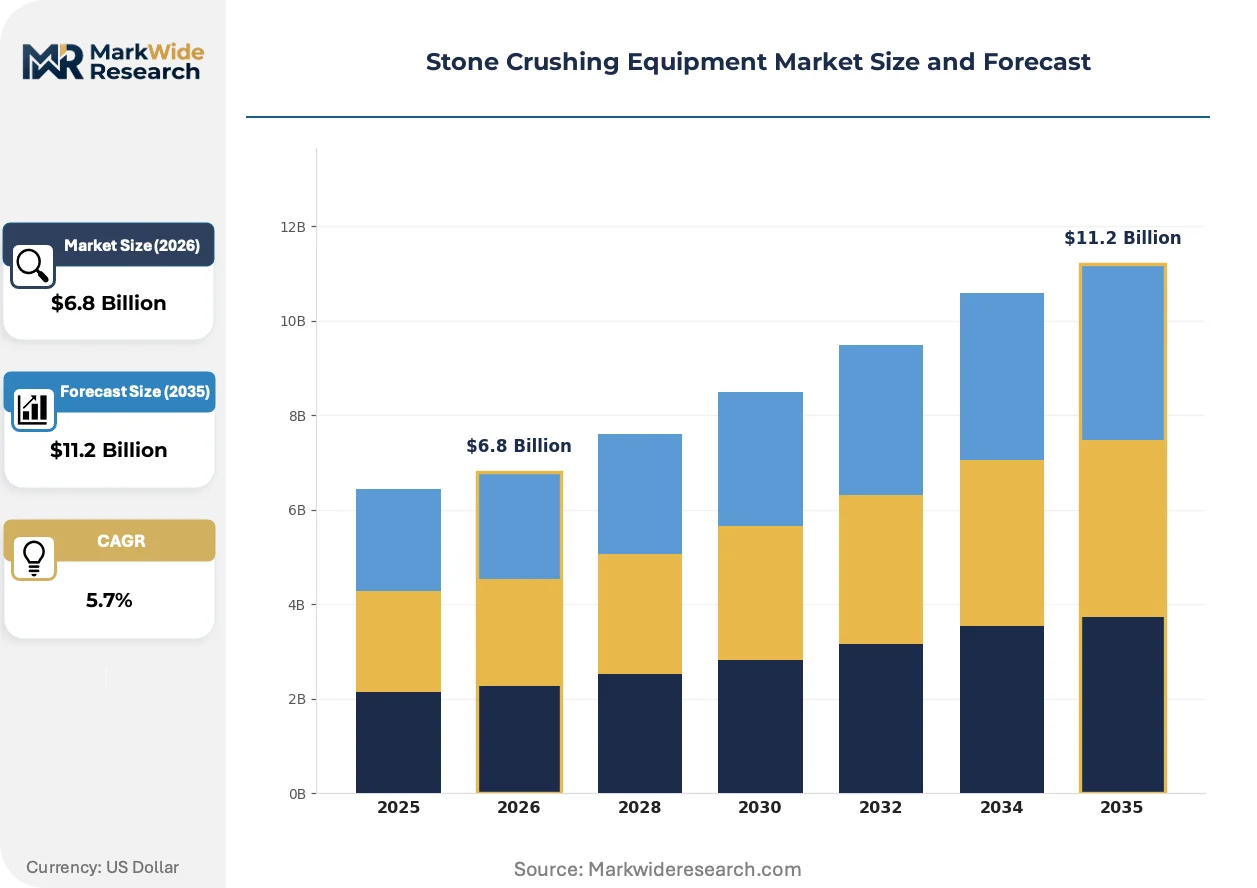
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jaw Crusher, Cone Crusher, Impact Crusher, Gyratory Crusher Application: Construction, Mining, Demolition, Recycling End User: Quarries, Contractors, Mining Companies, Recycling Facilities Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Metso Corporation, Sandvik AB, Terex Corporation, Caterpillar Inc., Komatsu Ltd., Astec Industries, Eagle Crusher Company Inc., Thyssenkrupp AG, Weir Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Crushing Equipment Market Emerging Trajectories
Digital fleet management and predictive maintenance architectures are compressing the traditional boundaries between equipment sale and aftermarket service, reshaping how operators evaluate total cost of ownership against upfront capital outlay.
Machine vision-guided feed control is automating crusher gap adjustment in real time based on incoming rock fragmentation analysis. Large-scale limestone quarries in Spain and Turkey are retrofitting existing cone crushers with camera arrays and hydraulic positioning actuators. This retrofit path is automating throughput optimization that previously required manual operator intervention every shift change.
EPA National Ambient Air Quality Standards and state-level implementation plans are tightening particulate matter thresholds for quarry operations across the United States. Non-attainment designations in California's San Joaquin Valley and Pennsylvania's Lehigh Valley are forcing operators to replace pre-2015 diesel crushers with Tier 4 Final or electric-powered units. California Air Resources Board enforcement actions are accelerating the scrappage of older open-chassis models in favor of enclosed, filtered configurations.
Service contract unbundling is fragmenting the traditional bundled maintenance model that dominated quarry equipment procurement for decades. Infrastructure contractors in Australia's Pilbara region and Chile's Atacama Desert are negotiating standalone remote monitoring subscriptions separate from physical parts supply. This purchasing pattern shift is most visible in remote mining camps where fly-in-fly-out labor costs make predictive downtime avoidance more valuable than traditional preventive maintenance schedules.
Stone Crushing Equipment Market Segmentation
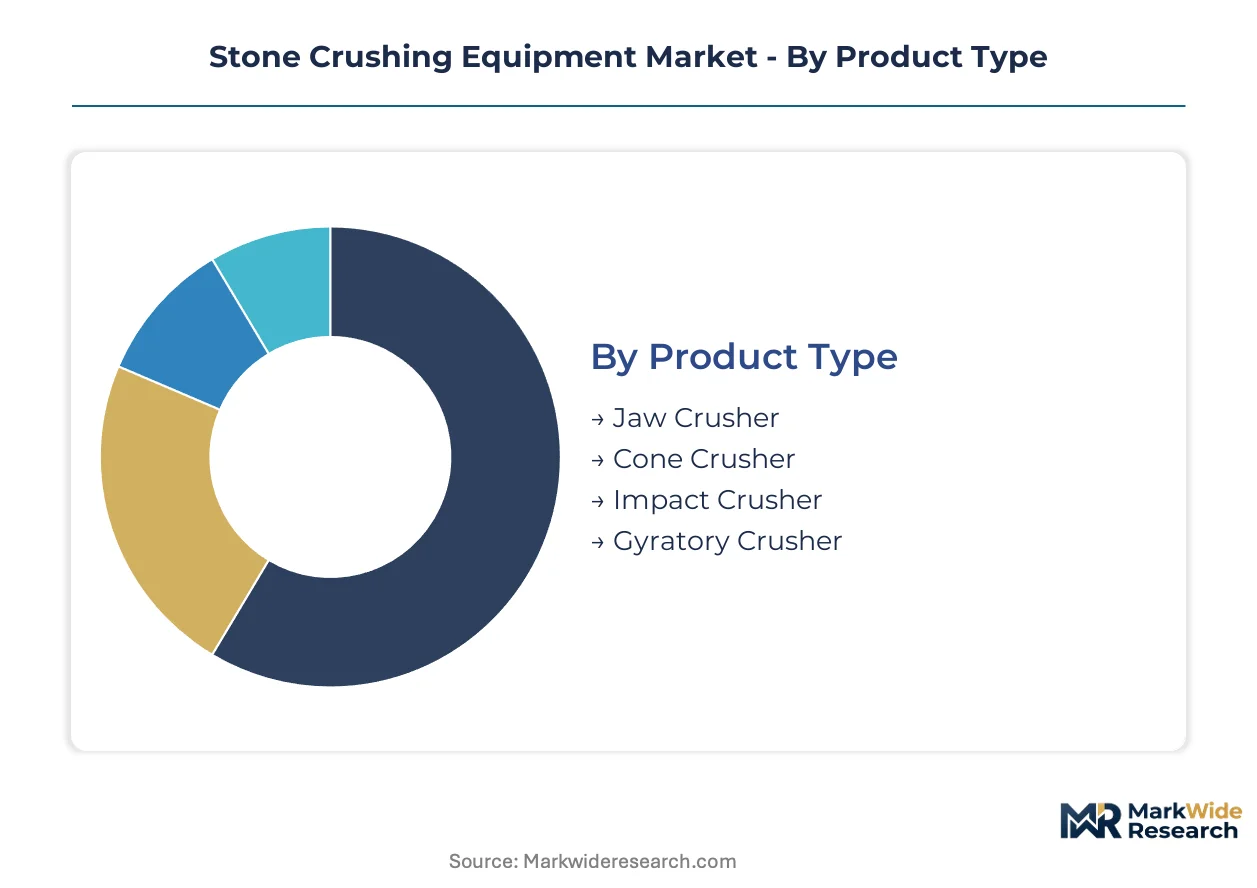
Equipment specification and procurement patterns diverge sharply across quarry operators, demolition contractors, and mining houses, with each end-use imposing distinct duty-cycle demands on liner wear rates and automation requirements. Segmentation reveals where capital deployment concentrates and where aftermarket service contracts generate recurring revenue streams.
Product Type:
Supply concentration in manganese steel foundries and proprietary crushing chamber designs locks OEM margins into specific mechanical configurations, with wear-part backward integration separating integrated suppliers from assembly-dependent competitors.
- Jaw Crusher:Fixed and swing plates generate compressive fracture force for primary reduction of 500 mm feedstock down to 100-150 mm gradations. Quarry clusters near Mumbai, Delhi, and Bangalore are pulling premium-capacity units under India's Bharatmala Pariyojana highway program, with contractors prioritizing enclosed, sensor-integrated models over open-chassis legacy installations to meet tightening dust-emission standards.
- Cone Crusher:Eccentrically rotating mantles within concave bowls achieve finer reduction ratios for asphalt and concrete specification. Railway ballast and manufactured-sand tightening specifications are accelerating demand fastest where real-time gap adjustment via machine vision is automating throughput optimization in Spanish and Turkish limestone quarries.
- Impact Crusher:Rotor blow bars deliver high-velocity impact fracture for softer, abrasive feedstocks and recycling applications with magnetic rebar separation.
- Gyratory Crusher:Massive conical crushing heads process ultra-high tonnages in deep-pit copper and iron ore operations requiring continuous duty cycles.
Today's leader: Jaw Crusher. Tomorrow's challenger: Cone Crusher.
Application:
Cost tier stratification separates premium enclosed automation from economy open-chassis models, with regulatory compliance layers compounding operational complexity and extending payback calculations.
- Construction:Highway, dam, and building foundation projects specify graded aggregate for concrete batching and asphalt paving, with India's national infrastructure build-out dominating current order books.
- Mining:Deep-pit copper, iron ore, and gold operations demand 24/7 duty cycles with automated feed control and predictive wear monitoring to minimize fly-in-fly-out labor costs in remote camps.
- Demolition:Urban decommissioning mandates in São Paulo, Lagos, and Jakarta require compact, portable impact configurations with enclosed dust suppression and magnetic rebar separation for on-site concrete processing.
- Recycling:Dedicated C&D waste streams and reclaimed asphalt pavement processing favor closed-circuit portable units with real-time particulate monitoring to satisfy EPA and OSHA crystalline silica exposure limits.
Construction commands current volume. Demolition offers the steepest expansion trajectory as municipal processing mandates proliferate across emerging-market megacities.
End User:
Customer type determines procurement sophistication, with mining houses negotiating predictive maintenance subscriptions while independent contractors prioritize upfront capital flexibility.
- Quarries:Long-life limestone and granite operations amortize capital over 15-20 year horizons, favoring enclosed, Tier 4 Final or electric-hybrid units to preempt CARB enforcement actions and EPA non-attainment designations.
- Contractors:Project-based infrastructure builders in Australia's Pilbara and Chile's Atacama Desert unbundle service contracts, purchasing standalone remote monitoring separate from physical parts supply to optimize fly-in-fly-out labor economics.
- Mining Companies:Integrated majors demand fleet-management platforms with vibration analysis, oil contamination sensing, and uptime guarantees that transform capital sales into multi-year recurring revenue.
- Recycling Facilities:Municipal and private C&D processors face OSHA silica compliance retrofit burdens, forcing replacement of pre-2015 diesel units with filtered, enclosed configurations.
Quarries anchor installed base economics. Mining companies are concentrating fastest around subscription-based uptime guarantee models.
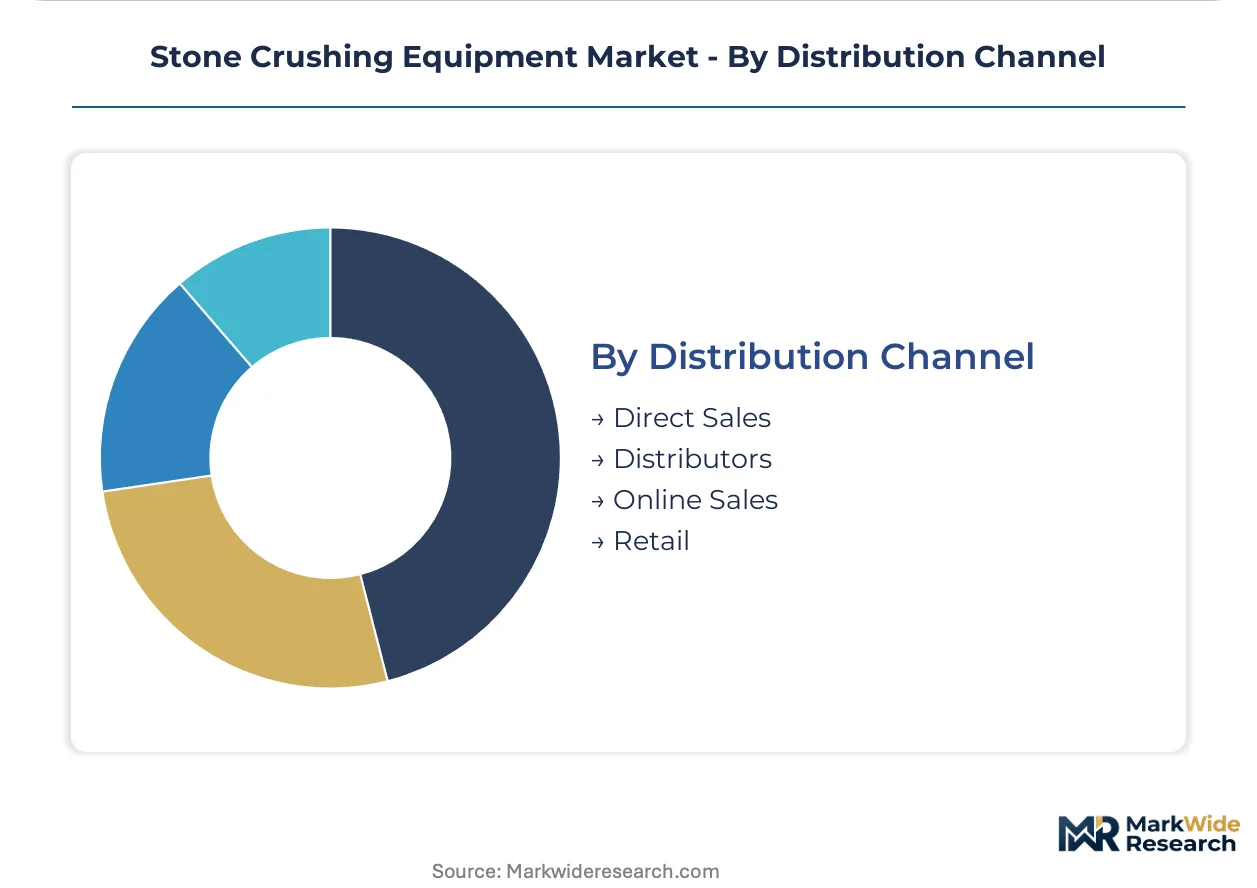
Distribution Channel:
Maturity gradients separate established direct-sales relationships in mature markets from distributor-dependent penetration in emerging economies where localized assembly and parts distribution determine competitive positioning.
- Direct Sales:OEM field engineers configure crushing chambers and automation packages for mega-quarry and mining house accounts, embedding multi-year aftermarket subscriptions at point of sale.
- Distributors:Authorized dealer networks dominate Vietnam's Ho Chi Minh City industrial zones and India's secondary cities, providing localized parts inventory and field service capability where OEM direct presence remains thin.
- Online Sales:Wear-part replenishment and remote diagnostics subscriptions migrate to digital platforms, though capital equipment transactions remain relationship-intensive.
- Retail:Limited to small-scale mobile crusher rentals and consumable spare parts for independent demolition contractors.
Direct sales capture premium-margin automation packages. Distributor networks are expanding fastest where first-mover localization investments open emerging-market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where dust-emission compliance costs remain below European thresholds, drawing mobile crusher assembly into Vietnam and India while legacy quarry clusters in Germany and Japan consolidate around mega-plant rail distribution.
United States
California Air Resources Board enforcement actions and EPA non-attainment designations in the San Joaquin Valley are scrapping pre-2015 diesel crushers. Pennsylvania's Lehigh Valley operators retrofit enclosed, Tier 4 Final units to meet crystalline silica limits. Eagle Crusher Company Inc. anchors portable closed-circuit supply for demolition contractors across the Great Lakes and Southeast.
Germany
Centralized mega-quarries with rail-linked distribution networks displace distributed mobile crushing for Autobahn maintenance and wind-farm foundation projects. CE marking under the EU Machinery Directive and F-Gas Regulation phase-down accelerate electric-hybrid fleet turnover. The Rhineland-Palatinate limestone belt concentrates enclosed, sensor-integrated gyratory installations.
India
The Bharatmala Pariyojana national highway program pulls premium-capacity jaw and cone crushers into quarry clusters surrounding Mumbai, Delhi, and Bangalore. BIS certification requirements and state-level pollution control board enforcement tighten dust-emission standards. Contractors in Maharashtra and Karnataka prioritize mobile units for urban demolition waste processing.
Vietnam
The North-South Expressway and Long Thanh International Airport create first-mover positions for OEMs establishing localized assembly in Ho Chi Minh City industrial zones. Vietnamese quarry operators import Tier 3 diesel crushers from Chinese fabricators while awaiting domestic electric-hybrid availability. Distributor networks dominate parts supply in secondary cities.
Brazil
Municipal mandates in São Paulo require on-site concrete processing for decommissioned infrastructure, driving compact impact crusher demand with magnetic rebar separation. ANVISA occupational exposure limits and state environmental agency enforcement push retrofit of dust-suppression enclosures. The Minas Gerais iron ore belt sustains 24/7 gyratory duty cycles for export concentrate production.
Stone Crushing Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated majors capturing multi-year aftermarket subscriptions while regional fabricators compete on upfront capital flexibility. The vendor base concentrates in Nordic and Japanese engineering groups with backward integration into wear-part foundries and hybrid-drive powertrains. Three archetypes dominate: full-lifecycle solution providers bundling telematics and uptime guarantees; portable configuration specialists serving demolition contractors; and scale-driven mining equipment houses. Competitive moves center on M&A to secure manganese steel supply and strategic partnerships to localize assembly in Vietnam and India.
Among the integrated engineering groups, Metso Corporation and Sandvik AB exemplify the full-lifecycle archetype through digital fleet-management platforms and predictive maintenance subscriptions. Komatsu Ltd. anchors the Japanese tier with proprietary hybrid-drive integration. These three occupy positions where capital equipment economics transform into recurring revenue through remote diagnostics and wear-part replenishment contracts.
| Leading Market Players |
|---|
| Metso Corporation |
| Sandvik AB |
| Terex Corporation |
| Caterpillar Inc. |
| Komatsu Ltd. |
| Astec Industries |
| Eagle Crusher Company Inc. |
| Thyssenkrupp AG |
| Weir Group |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down requirements gate qualified supply for electric-hybrid crushing units and premium-tier pricing access, compressing margins for OEMs without backward integration into proprietary drive systems while elevating price floors for compliant configurations.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for standard-tier mobile units as localized assembly reduces landed cost differentials. Three-tier pricing structure across premium automation, standard enclosed, and economy open-chassis levels separates buyers by compliance urgency. Cost compression in economy tiers intensifies because Chinese fabricators flood secondary markets with Tier 3 diesel configurations. Independent contractors in emerging markets exhibit highest price sensitivity, while mining houses prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Manganese steel liner plate supply rests on South African and Australian foundries, with chromium carbide blow bar production concentrated in Nordic engineering groups. High-alloy wear parts, hydraulic positioning actuators, and machine vision sensor arrays constitute critical component dependencies. Single-source vulnerability in manganese ore processing exposes operators to freight cost volatility and extended replenishment cycles. Distribution runs through authorized dealer networks in emerging markets and direct OEM field engineering for mega-quarry accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stone crushing equipment procurement functions as a geographic-arbitrage play where dust-emission compliance costs in Germany and Japan run triple those in Vietnam, redirecting mobile assembly investments toward Southeast Asian industrial zones.
For Market Incumbents: Hedge against South African foundry supply disruption by cultivating secondary manganese steel sources in Australia and India. Anchor premium positioning through captive hybrid-drive production that eliminates F-Gas refrigerant exposure entirely. Defend installed base economics by embedding multi-year remote diagnostics subscriptions at point of sale, locking out independent service providers. For New Entrants and Emerging Players: Distributor partnerships in Vietnam's Ho Chi Minh City industrial zones open first-mover positioning ahead of domestic electric-hybrid availability. Target compact impact crusher configurations for São Paulo demolition contractors facing municipal on-site processing mandates. Pursue unbundled remote monitoring subscriptions as the most penetrable service segment, separating predictive analytics from physical parts supply. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking backward integration into wear-part foundries or telematics platforms. Long-term viability over the next decade hinges on recurring revenue transformation from capital sales to aftermarket subscriptions. Watch CE marking certification timeline extensions as the inflection signal indicating regulatory barrier elevation that favors scaled incumbents over assembly-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wear-Part Foundries | Captive manganese steel supply insulates margins from South African freight volatility and secures liner plate availability for premium crusher deliveries. |
| Hybrid-Drive Powertrain Development | Proprietary electric-hybrid systems eliminate F-Gas refrigerant constraints entirely, unlocking EU market access ahead of phase-down deadlines. |
| Remote Diagnostics Platform Launch | Predictive maintenance subscriptions transform capital equipment economics into recurring revenue streams with multi-year uptime guarantees. |
| Localized Assembly in Vietnam | Ho Chi Minh City industrial zone presence captures North-South Expressway and Long Thanh Airport aggregate demand with reduced landed costs. |
| Machine Vision Feed Control Integration | Real-time rock fragmentation analysis automates crusher gap adjustment, differentiating throughput optimization in Spanish and Turkish limestone quarries. |
Methodological Framework
Bottom-up quarry operator modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, aftermarket service heads, and infrastructure procurement officers at contractors across India's Bharatmala program, Australia's Pilbara region, and Chile's Atacama Desert informed demand-side assumptions. Secondary validation drew from customs and trade data, SEC 10-K filings of listed equipment manufacturers, EU Machinery Directive conformity assessment databases, and state-level pollution control board enforcement records in Maharashtra and Karnataka.
Input-output matrices connect installed base depreciation schedules, replacement cycle compression from OSHA silica compliance, and regional infrastructure project pipelines to unit demand across the projection horizon. Segmentation dimensions modeled include product type, application duty cycle, end-user procurement sophistication, and distribution channel maturity. CAGRs derive from regression analysis against historical quarry equipment capex and correlation with aggregate consumption intensity in construction and mining end-uses. Forecast inputs incorporate BIS certification timeline trajectories and F-Gas Regulation phase-down implementation pacing.
Revisions become necessary when EU Green Deal carbon border adjustments accelerate, South African foundry supply disruptions materialize, or municipal demolition processing mandates proliferate beyond São Paulo, Lagos, and Jakarta. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure program funding continuity. A small set of triggers—CE marking timeline extensions, manganese ore export restrictions, and hybrid-drive battery supply constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Mining Drill Market