
 Mobile Blasting Systems Market | 2026-2036
Mobile Blasting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Blasting Systems Market Analytics
Buyer concentration across North American shipyard contractors is realigning procurement patterns toward fleet-standardized mobile units. Clemco Industries Corp. leverages its distributor network to sustain aftermarket parts revenue across fragmented contractor bases. Graco Inc. competes through fluid handling integration that anchors its position in wet blasting system supply. Empire Abrasive Equipment specializes in custom-engineered solutions that differentiate its portfolio from commoditized conventional units.
Mobile blasting systems are self-propelled or towable abrasive projection machines that operate at pressures between 90 and 150 psi using steel grit, aluminum oxide, or garnet media to strip coatings and prepare substrates for recoating. Portable Systems dominate current revenue flows due to lower capital barriers for small and mid-sized contractors, while Automated Solutions capture expanding margin pools in aerospace MRO facilities where repeatability requirements exceed manual precision. Wet Blasting technology leads growth trajectories as EPA effluent regulations tighten discharge permissions for dry abrasive operations near waterways.
OSHA enforces permissible exposure limits for respirable crystalline silica that force contractors toward closed-loop recovery systems and alternative media formulations. EPA National Emission Standards for Hazardous Air Pollutants constrain open-air blasting practices in coastal zones, redirecting demand toward contained mobile units with vacuum recovery. Stakeholders must monitor evolving state-level environmental variances that fragment equipment certification requirements across multi-state contractor fleets.
Market Dynamics
OSHA silica exposure limits and EPA emissions standards are compressing operational flexibility for contractors, forcing capital redeployment toward closed-loop recovery systems and wet blasting technologies that contain airborne particulates.
Growth Catalysts
- Heritage Infrastructure Rehabilitation:Germany's industrial restoration sector requires precision surface preparation for protected structures, sustaining demand for low-pressure precision units.
- REACH Chemical Restrictions:Alternative media formulations free of hazardous substances gain preference as traditional abrasives face authorization hurdles.
- Shipyard Maintenance Expansion:South Korean naval and commercial vessel programs are scaling portable abrasive deployment across multiple drydock facilities.
Market Restraints
- Abrasive Media Cost Volatility:Garnet and aluminum oxide supply concentrates in Australian and Chinese mining operations, exposing contractors to freight and tariff fluctuations.
- Technical Limitation in Confined Spaces:Vacuum recovery systems struggle with airflow dynamics in tank interiors and double-hull compartments, restricting application scope.
- Substitution Threat from Laser Ablation:Aerospace MRO facilities in France and Germany are piloting laser coating removal for delicate substrates, displacing abrasive methods on select airframe sections.
Strategic Opportunities
- Underpenetrated Coastal Restoration:Netherlands and Belgium harbor infrastructure programs lack standardized mobile blasting protocols, creating first-mover positioning for equipment suppliers.
- Technology Convergence:Integration of robotic positioning systems with wet blasting units enables repeatable surface profiles for offshore wind turbine foundations.
- CSRD Reporting Requirements:EU corporate sustainability disclosure mandates push industrial asset owners toward documented environmental performance, favoring suppliers with certified low-emission equipment.
Industry Challenges
- Certification Timeline Compression:EPA NESHAP variances across state boundaries force multi-state contractors to maintain redundant equipment configurations or absorb compliance delays.
- Integration Complexity with Legacy Compressed Air Infrastructure:Older shipyard and fabrication facilities operate at inconsistent pressure ratings, requiring custom manifold adaptations for modern blasting units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Blasting Systems Market |
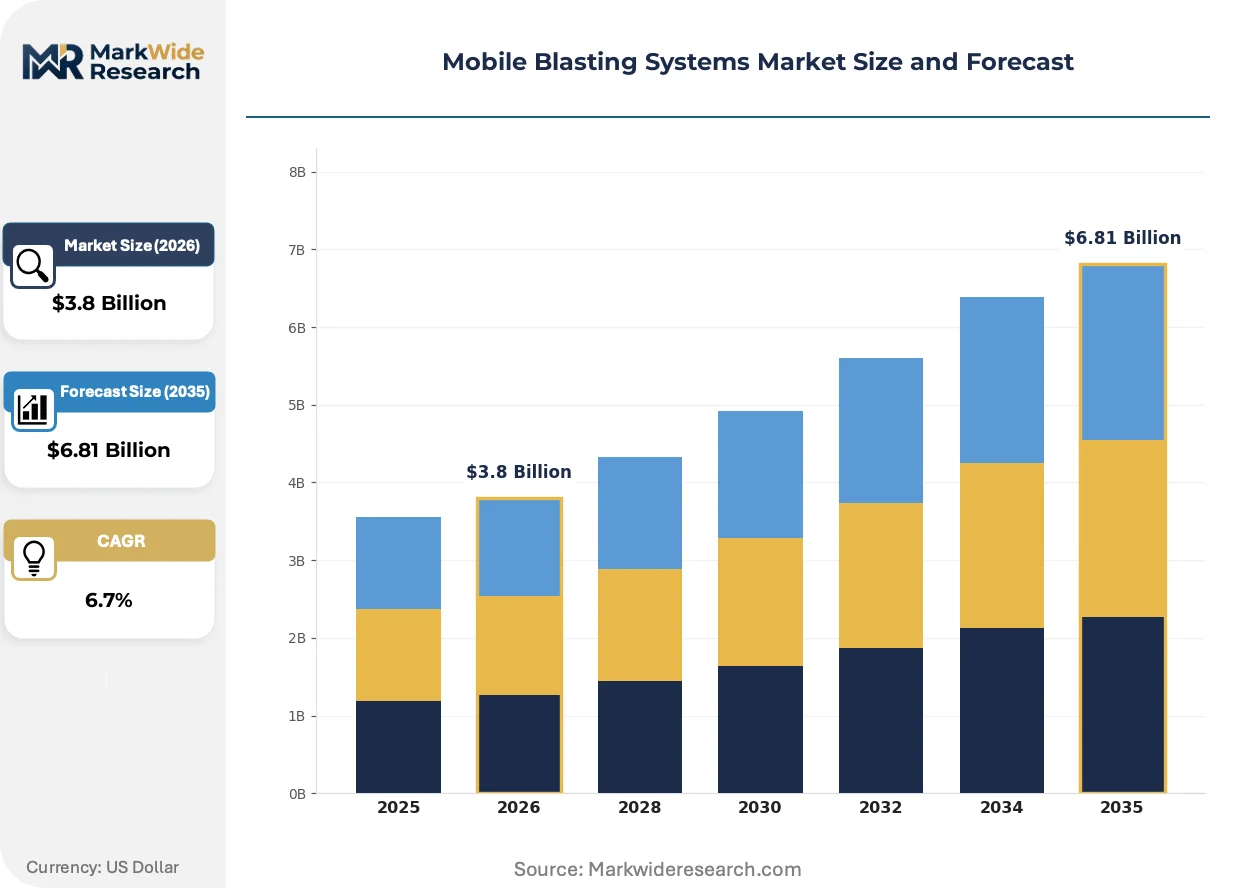
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Robotic Blasters, Conventional Units, Automated Solutions Application: Surface Preparation, Paint Removal, Abrasive Cleaning, Concrete Restoration End User: Construction, Manufacturing, Aerospace, Automotive Technology: Wet Blasting, Dry Blasting, Eco-friendly Methods, High-Pressure Systems |
| Companies Covered | Clemco Industries Corp., Airblast B.V., Empire Abrasive Equipment, Graco Inc., Guyson Corporation, AB SHOT TECNICS, CB Sabbiatrici, Burwell Technologies, Kramer Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Blasting Systems Market Evolving Landscape
Wet blasting technology is compressing the competitive window for dry abrasive systems as regulatory discharge permissions tighten near waterways and coastal industrial zones.
Closed-loop water reclamation is decentralizing equipment deployment patterns for contractors serving marine and infrastructure clients. Harbor maintenance divisions in Rotterdam and Hamburg are adopting self-contained wet blasting trailers that eliminate external water hookup requirements. This capability is compressing mobilization timelines and expanding addressable project sites for fleet operators.
EPA National Emission Standards for Hazardous Air Pollutants are constraining open-air dry blasting in US coastal zones. Contractors in Gulf Coast shipyards face permit denials for traditional operations, redirecting capital toward contained mobile units with integrated vacuum recovery. Wet blasting system suppliers are capturing displaced demand as buyers prioritize regulatory compliance over equipment familiarity.
Service unbundling is fragmenting traditional equipment-plus-consumables relationships in the contractor base. Large shipyard operators in South Korea and Germany are separating abrasive procurement from equipment leasing, forcing suppliers to compete on pure hardware performance rather than bundled media contracts. This shift is compressing margins for distributors historically anchored to consumable revenue streams.
Mobile Blasting Systems Market Segmentation
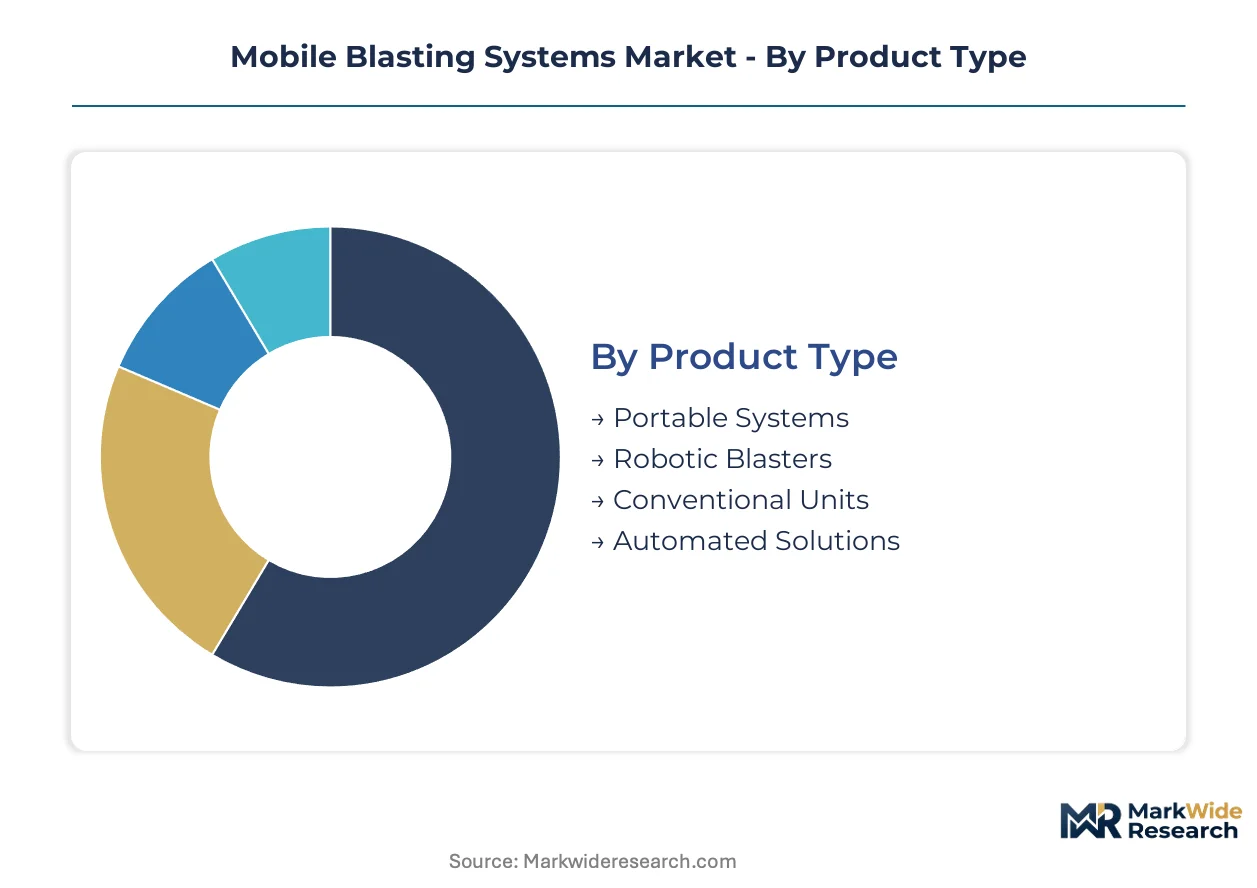
Equipment configuration in mobile blasting systems varies sharply by operational scale and substrate complexity. Contractors face divergent capital thresholds and regulatory constraints across product categories, while application specialization determines media selection and recovery system requirements.
Product Type:
Supply concentrates in portable system manufacturing, with fabrication clusters serving small-contractor demand across fragmented regional markets.
- Portable Systems:Towable or skid-mounted units operating at 90-150 psi with manual nozzle control dominate contractor fleet composition. South Korean shipyard maintenance programs are scaling portable abrasive deployment across multiple drydock facilities, driving fleet standardization among regional contractors.
- Automated Solutions:Programmable blast cabinets with robotic nozzle positioning deliver repeatable surface profiles for precision substrates. Aerospace MRO facilities in France and Germany are piloting these systems for delicate airframe sections where manual precision falls short of repeatability requirements.
- Robotic Blasters:Articulated arm systems integrated with vision guidance for complex geometry processing.
- Conventional Units:Fixed-installation pressure vessels with manual operation for high-volume production environments.
Today's leader: Portable Systems. Tomorrow's challenger: Automated Solutions.
Application:
Cost tiers separate high-precision heritage work from commodity coating removal, with margin structures varying by substrate sensitivity and regulatory oversight intensity.
- Surface Preparation:Profiling substrates to specified roughness parameters for coating adhesion, typically using angular abrasives at controlled pressures. Germany's industrial restoration sector requires precision surface preparation for protected structures, sustaining demand for low-pressure precision units with documented environmental performance.
- Paint Removal:Stripping existing coatings from metal, concrete, or composite substrates without substrate damage. Netherlands and Belgium harbor infrastructure programs lack standardized mobile blasting protocols, creating positioning opportunities for suppliers serving coastal restoration contractors.
- Abrasive Cleaning:Removing oxidation, scale, or contamination from industrial equipment and structural components.
- Concrete Restoration:Exposing aggregate and repairing deteriorated concrete surfaces in infrastructure rehabilitation.
Surface Preparation commands premium pricing. Paint Removal offers volume expansion.
End User:
Customer type determines procurement sophistication, with aerospace and automotive buyers imposing certification requirements that exclude commodity equipment suppliers.
- Construction:General contractors and specialty trades performing surface preparation for infrastructure, commercial, and residential projects. EPA NESHAP constraints on open-air dry blasting in US coastal zones are redirecting Gulf Coast contractor capital toward contained mobile units with vacuum recovery.
- Aerospace:MRO facilities and OEM production lines requiring precision surface treatment for airframe, engine, and component finishing. Laser ablation pilots in France and Germany are displacing abrasive methods on select delicate substrates, compressing the addressable scope for traditional blasting in this segment.
- Manufacturing:Industrial production facilities performing in-house surface treatment for fabricated metal products.
- Automotive:Vehicle production and refurbishment operations requiring paint stripping and surface profiling.
Construction absorbs unit volume. Aerospace defines performance standards.
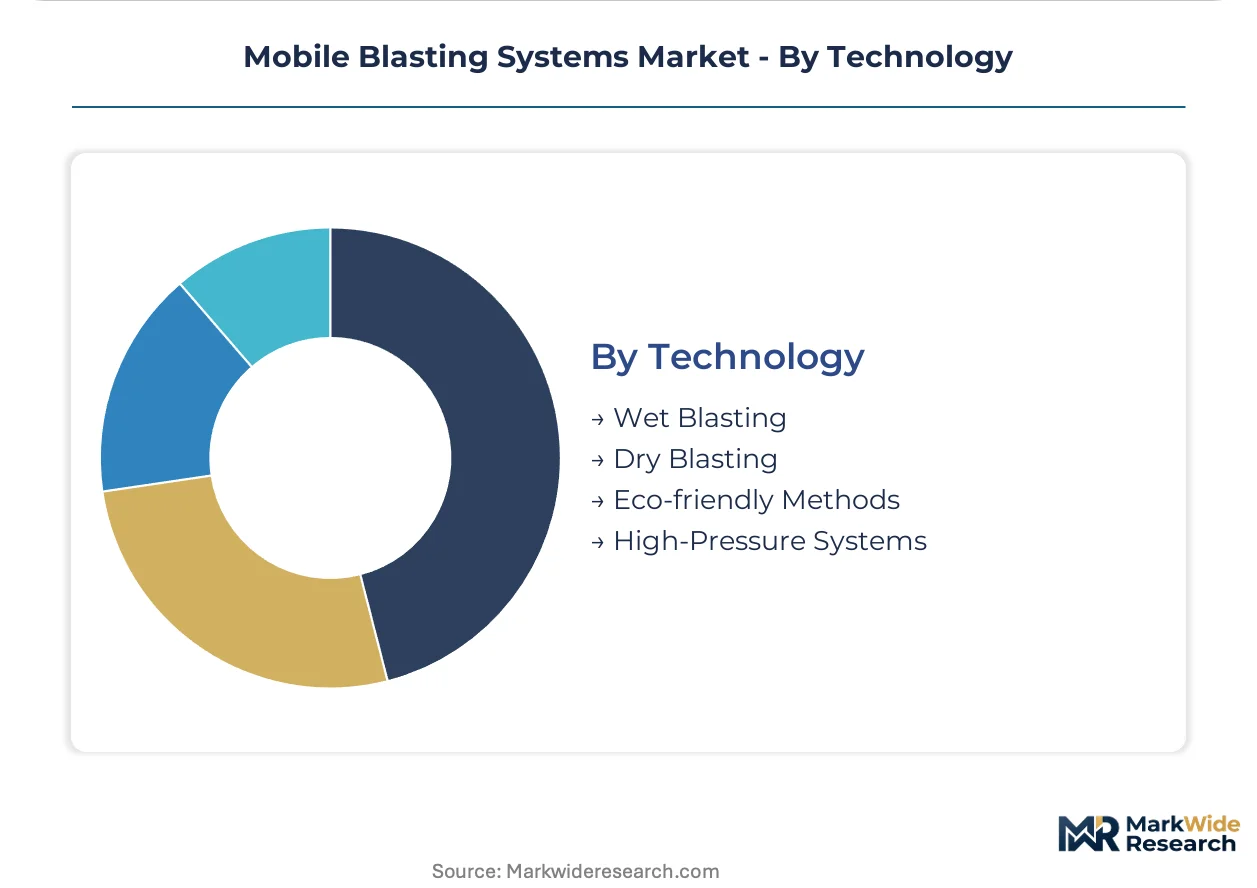
Technology:
Maturity curves diverge sharply, with wet blasting climbing fastest as discharge regulations tighten while dry blasting confronts permit restrictions in environmentally sensitive zones.
- Wet Blasting:Water-injected abrasive streams that suppress airborne particulates and enable discharge containment through closed-loop reclamation. Harbor maintenance divisions in Rotterdam and Hamburg are adopting self-contained wet blasting trailers that eliminate external water hookup requirements, compressing mobilization timelines.
- Eco-friendly Methods:Media and process formulations engineered to eliminate hazardous substance release and minimize waste generation. REACH chemical restrictions are accelerating preference for alternative media free of authorization hurdles, favoring equipment compatible with biodegradable and recyclable abrasives.
- Dry Blasting:Traditional pneumatic abrasive projection without liquid injection, facing permit denials in coastal industrial zones.
- High-Pressure Systems:Ultra-high-pressure waterjet and abrasive waterjet technologies for precision material removal.
Wet Blasting is gaining share fastest. Eco-friendly Methods are climbing the fastest as regulatory authorization timelines extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's heritage infrastructure rehabilitation sustains premium equipment demand while South Korean shipyard maintenance programs scale portable abrasive deployment across multiple drydock facilities, revealing divergent regional specialization patterns.
United States
Gulf Coast shipyard contractors face EPA NESHAP permit denials for open-air dry blasting operations. OSHA silica exposure limits force capital redeployment toward contained mobile units with vacuum recovery systems. Houston and Mobile industrial clusters redirect procurement toward wet blasting technologies that satisfy discharge constraints.
Germany
Industrial restoration of protected structures requires precision surface preparation with documented environmental performance. REACH chemical restrictions accelerate preference for alternative media free of authorization hurdles. Ruhr Valley heritage projects and Bavarian manufacturing facilities sustain demand for low-pressure precision units.
South Korea
Naval and commercial vessel maintenance programs scale portable abrasive deployment across Geoje and Ulsan drydock facilities. National shipbuilding competitiveness initiatives support fleet standardization among regional contractors. Busan harbor infrastructure contractors compress mobilization timelines through self-contained wet blasting trailers.
Netherlands
Harbor maintenance divisions in Rotterdam adopt closed-loop water reclamation systems that eliminate external water hookup requirements. EU CSRD reporting requirements push industrial asset owners toward documented environmental performance. Delta region coastal restoration programs lack standardized mobile blasting protocols, creating equipment positioning opportunities.
France
Aerospace MRO facilities in Toulouse and Paris pilot laser coating removal for delicate airframe sections, compressing addressable scope for traditional abrasive methods. ANSM equipment certification timelines constrain multi-site contractor operations. Occitanie aerospace cluster demands repeatable surface profiles that exceed manual precision capabilities.
Mobile Blasting Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented regional markets. The vendor base separates into three strategic archetypes: fluid handling integrators, abrasive equipment pure-plays, and custom-engineered solution providers. Consolidation pressure concentrates among mid-scale fabricators serving commodity coating removal segments. Dominant competitive moves include geographic expansion through distributor networks and technology licensing for wet blasting system integration.
Within the established equipment tier, Clemco Industries Corp. and Graco Inc. exemplify divergent strategic positioning—Clemco sustaining aftermarket parts revenue through distributor network density, Graco anchoring wet blasting supply through fluid handling integration. Empire Abrasive Equipment occupies a position within the custom-engineered specialist archetype, differentiating from commoditized conventional units through application-specific configurations. These three companies represent the structural spectrum from scale-driven distribution to precision-focused engineering.
| Leading Market Players |
|---|
| Clemco Industries Corp. |
| Airblast B.V. |
| Empire Abrasive Equipment |
| Graco Inc. |
| Guyson Corporation |
| AB SHOT TECNICS |
| CB Sabbiatrici |
| Burwell Technologies |
| Kramer Industries Inc. |
| Others |
Value Network & Pricing Analysis
Garnet price indices from Australian mining operations cascade through equipment manufacturing tiers, compressing margins for mid-scale fabricators while premium wet blasting system suppliers maintain pricing power through closed-loop technology differentiation.
Pricing Analysis
Capacity additions in Chinese aluminum oxide processing are reshaping price floors for standard abrasive media, forcing equipment suppliers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade and after-sales service bundling, with EPA-compliant wet blasting units commanding premium positioning. Cost compression in portable system tiers intensifies because South Korean shipyard contractors negotiate fleet-scale procurement. Small and mid-sized contractors exhibit highest price sensitivity, while aerospace MRO facilities prioritize repeatability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Gulf Coast shipyard operators mandate multi-supplier qualification for pressure vessel components and vacuum recovery systems. Manufacturing concentrates in Germany, South Korea, and the United States for precision fabrication, while garnet and aluminum oxide feedstock draws from Australian and Chinese mining operations. Supply chain risk centers on tariff exposure for abrasive media imports. Distribution runs through regional distributor networks anchored by aftermarket parts and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA silica exposure limits and EPA NESHAP constraints continuously redirect contractor capital toward compliant equipment categories.
For Market Incumbents: Lock in distributor channel control across fragmented North American contractor bases to defend against fluid handling integrators encroaching on wet blasting supply. Prioritize certification investment for closed-loop recovery systems before state-level EPA variances fragment equipment requirements further. Backward integration into alternative media formulations hedges against REACH authorization hurdles.
For New Entrants and Emerging Players: Heritage infrastructure contractors in Germany's Ruhr Valley represent an underserved buyer archetype requiring precision low-pressure units with documented environmental performance. Coastal restoration programs in the Netherlands and Belgium lack standardized mobile blasting protocols, creating first-mover positioning. A technology licensing go-to-market angle with established fluid handling suppliers accelerates wet blasting system penetration.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fabricators serving commodity coating removal segments face margin compression from unbundled service relationships. Long-term viability favors custom-engineered solution providers with aerospace and heritage infrastructure certification depth. Watch laser ablation pilot adoption in French aerospace MRO facilities as inflection indicator for abrasive method displacement scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recovery System Certification | EPA NESHAP compliance secures permit access for Gulf Coast shipyard contractors. |
| Alternative Media Formulation Development | REACH-compliant abrasives bypass authorization hurdles in German restoration projects. |
| Robotic Positioning Integration | Vision-guided automation captures aerospace repeatability requirements exceeding manual precision. |
| Self-Contained Wet Blasting Trailer Deployment | Rotterdam harbor maintenance divisions compress mobilization timelines through water independence. |
| Distributor Network Density Expansion | Aftermarket parts revenue sustains incumbent positioning across fragmented contractor bases. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with maintenance directors at shipyard facilities, procurement leads at aerospace MRO operations, plant engineers in heritage restoration contractors, and aftermarket service heads at equipment distributors. Secondary validation draws from EPA NESHAP filings, OSHA enforcement data, ECHA REACH authorization databases, and customs trade records for abrasive media flows. Bottom-up equipment shipment analysis triangulates against top-down contractor capital expenditure patterns.
Granularity-level modeling disaggregates revenue across product type, application, technology, and end-use dimensions, with additional segmentation by regional regulatory cluster and fleet size tier. CAGRs derive from equipment replacement cycle analysis and regulatory compliance-driven upgrade timelines across the projection horizon. Wet blasting adoption curves and laser ablation pilot expansion serve as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automated solutions and aerospace end-use data carry tighter precision than fragmented portable system deployment in small-contractor markets. Forecasts reflect assumptions around EPA state-level variance trajectories and REACH authorization timelines. Deviation in OSHA enforcement intensity or laser ablation cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Locomotive Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Smart Mining Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Mining Drill Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Pin Drilling Unit Market