
 Mining Equipment Parts and Attachments Market | 2026-2036
Mining Equipment Parts and Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Equipment Parts and Attachments Market Analysis
Dealer and aftermarket channel control is fragmenting as OEMs build direct-to-mine-site service networks while independent distributors fight for inventory access. Komatsu leverages its global parts distribution centers to sustain long-term service contracts with tier-one miners. Sandvik competes through technology leadership in automated drilling tool systems. Caterpillar anchors North American demand with its remanufactured component programs and captive distribution.
Mining equipment parts and attachments encompass replaceable and bolt-on components engineered to OEM specifications for excavation, comminution, and material transport machinery, typically fabricated from high-manganese steel, chromium carbide overlays, or tungsten-carbide inserts to withstand abrasive wear and cyclic loading above 50,000 psi. These components restore machine availability, extend capital equipment life, and maintain production rates in continuous mining environments. Hydraulic hammers and buckets carry the largest installed base and replacement revenue pools, while automated technology segments attract the fastest-growing capital allocation as mines pursue operator-reduced drilling and loading cycles. Electromechanical systems remain mature in underground haulage but face displacement risk from hydraulic hybrids in hard-rock applications.
EPA Tier 4 Final and EU Stage V emissions standards are reshaping demand for rebuilt engine blocks and aftertreatment-compatible hydraulic packages, while China's MEE enforces dual carbon goals that restrict remanufacturing permits for high-emission component categories. Australia's national mine safety frameworks and Chile's SERNAGEOMIN operational standards further dictate inspection intervals and certified replacement protocols for structural attachments. Stakeholders must weigh regulatory compliance costs against the capital savings of extended rebuild programs when sourcing critical wear components.
Market Dynamics
Underground mining contractors are compressing replacement cycles for wear components as emissions thresholds tighten across Australia, China, and Chile, forcing simultaneous investment in rebuilt engines and certified hydraulic systems.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V standards:These emissions frameworks are accelerating demand for aftertreatment-compatible hydraulic packages and rebuilt engine blocks in North American and European surface mining fleets.
- Pilbara iron ore operations:Western Australia's high-volume, low-grade extraction intensity generates continuous demand for high-manganese steel ground-engaging tools and bucket attachments.
- Tungsten-carbide insert technology:Advanced cutting tool materials are extending bit life in hard-rock drilling applications, reducing downtime in Chile's copper belt maintenance hubs.
Market Restraints
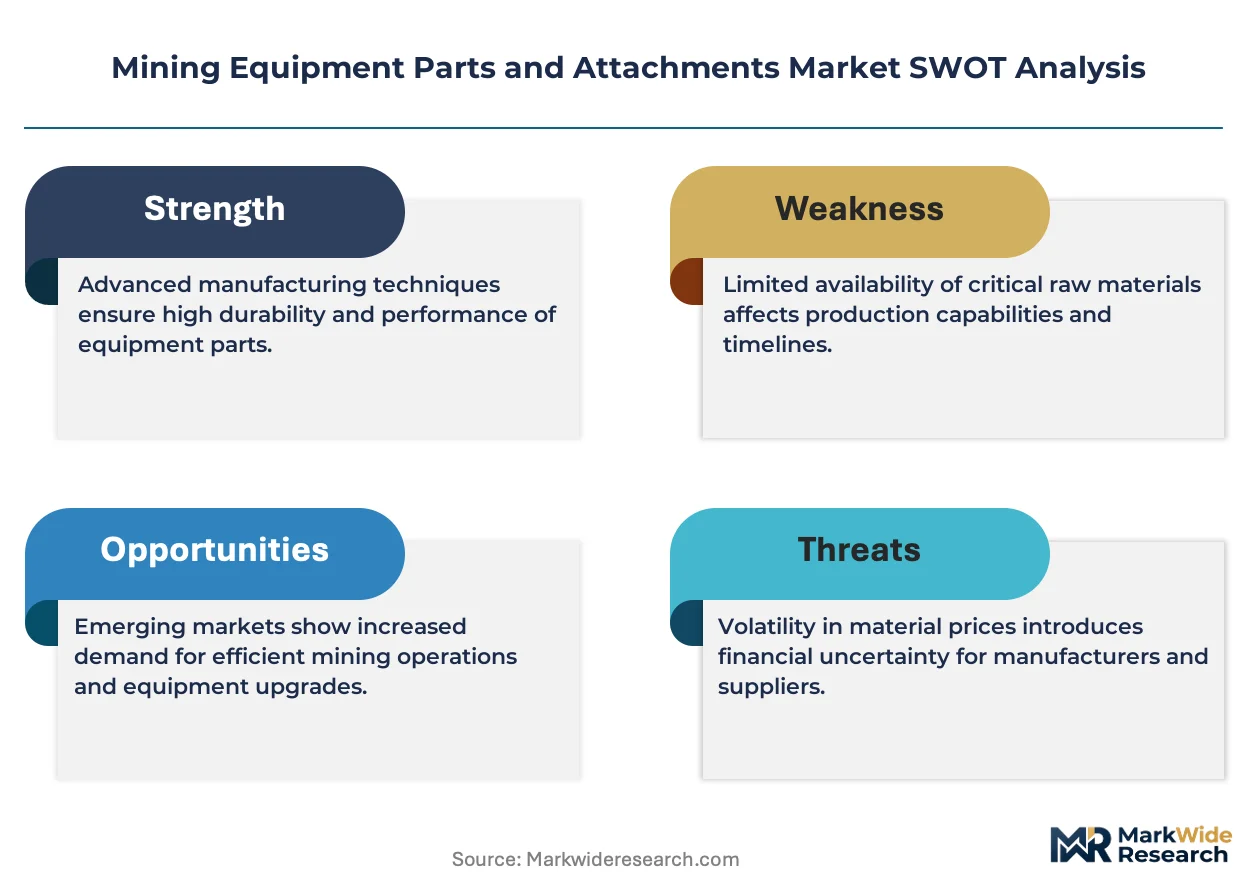
- Chromium carbide overlay supply concentration:Specialty steel fabrication capacity clusters in select East Asian foundries, exposing buyers to alloy price volatility and extended lead times.
- China's MEE dual carbon enforcement:Beijing's remanufacturing permit restrictions for high-emission component categories limit rebuild program expansion for imported machinery fleets.
- Hydraulic hybrid substitution threat:Electromechanical underground haulage systems face displacement from hydraulic-electric hybrid drivetrains in hard-rock loading applications.
Strategic Opportunities
- Automated drilling tool systems:Technology convergence between sensor-embedded bits and autonomous rig control creates premium pricing power for precision wear monitoring solutions.
- Direct-to-mine-site service networks:OEM bypass of traditional dealer channels opens captive parts revenue streams at tier-one operations in Western Australia and Chile.
- Australia's diesel particulate regulations:Tightened thresholds for rebuilt engines create certified replacement protocol demand for underground contractor fleets.
Industry Challenges
- GB standards compliance timeline:China's non-road mobile machinery certification delays create inventory mismatches for hydraulic system suppliers serving cross-border equipment fleets.
- Integration complexity with legacy hydraulic architectures:Aftertreatment retrofits for pre-Tier 4 engine blocks require bespoke plumbing packages that fragment service technician training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Equipment Parts and Attachments Market |
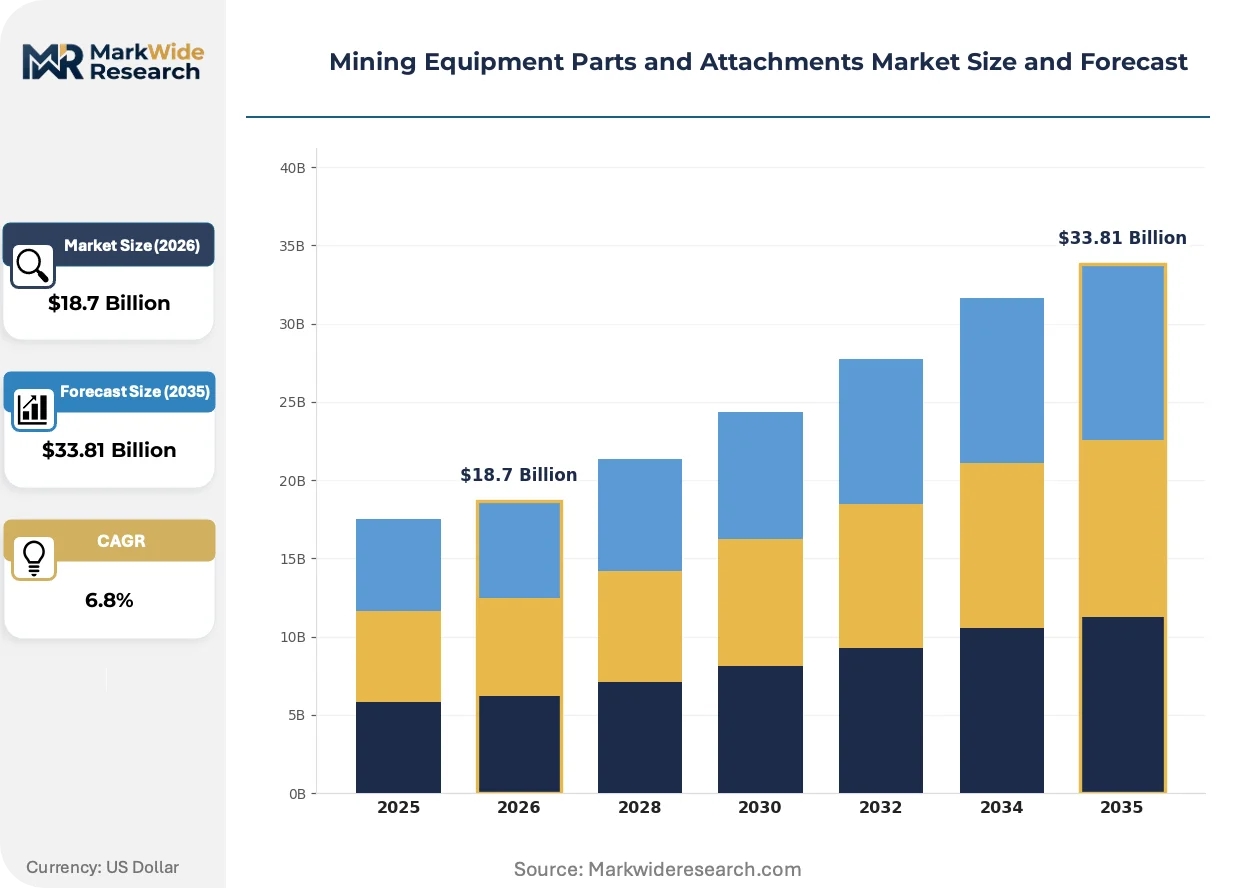
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Hammers, Buckets, Attachments, Drilling Tools Application: Excavation, Material Handling, Blasting, Rock Drilling End User: Mining Operators, Contractors, OEMs, Service Providers Technology: Electromechanical, Hydraulic, Pneumatic, Automated |
| Companies Covered | Komatsu, Atlas Copco, Metso Corporation, Terex Corporation, FLSmidth & Co., Sandvik, Hitachi Construction Machinery, Timken Global, Caterpillar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Equipment Parts and Attachments Market Emerging Trajectories
Technology migration across materials science, emissions compliance, and procurement architecture is restructuring how mining operators source, certify, and deploy replacement components.
High-manganese steel ground-engaging tools are migrating from conventional austenitic grades to work-hardening alloy formulations with embedded carbide precipitates. Tier-one Pilbara operators are adopting these advanced metallurgies for loader bucket lips and dozer blades. The technology is migrating from premium OEM captive supply toward independent aftermarket fabricators certified to SERNAGEOMIN operational standards.
China's GB 36886-2018 non-road diesel emissions framework and Australia's national mine safety frameworks are synchronizing inspection intervals for structural attachments across hard-rock and coal extraction modes. Rebuilt engine blocks must now carry traceable remanufacturing documentation to satisfy both MEE dual carbon goals and diesel particulate thresholds. Underground contractors in Chile's copper belt are consolidating supplier qualification lists to reduce compliance audit burden.
After-sales service unbundling is fragmenting long-term maintenance contracts into component-specific performance agreements. Tier-one miners now negotiate separate terms for hydraulic hammer rebuilds, bucket attachment replacement, and automated drilling tool refresh cycles. Western Australian iron ore operations lead this disaggregation, pressuring traditional dealer networks to specialize or exit.
Mining Equipment Parts and Attachments Market Segmentation
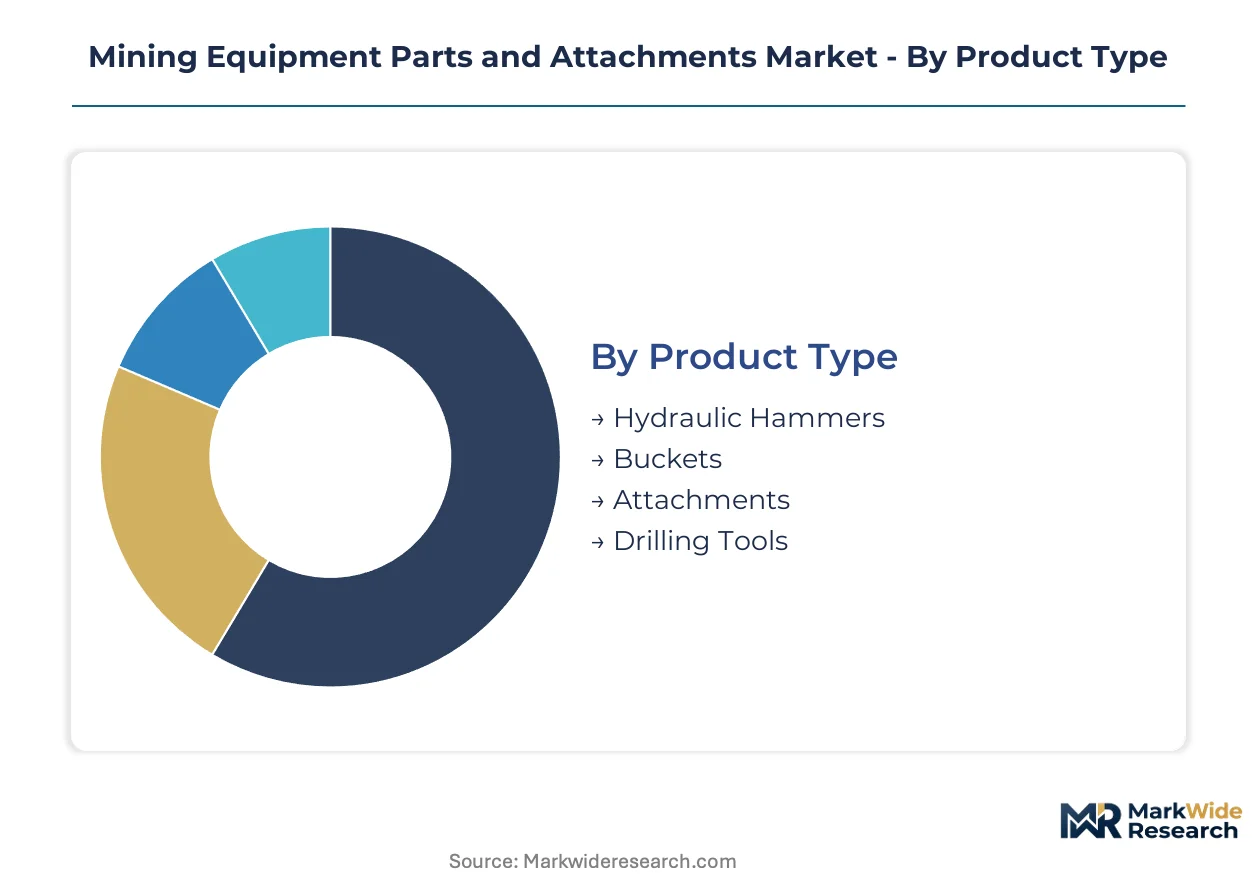
Component replacement cycles vary dramatically across mining equipment categories, with some segments turning over in months while others endure years of cyclic loading. Understanding these velocity differences shapes inventory positioning and service contract structures for suppliers serving continuous extraction environments.
Product Type:
Hydraulic hammers and buckets rotate through mine sites on compressed schedules dictated by abrasive wear rates, while drilling tools and general attachments follow extended replacement timelines tied to ore hardness and operating intensity.
- Hydraulic Hammers:Fabricated from high-manganese steel with chromium carbide overlays, these components withstand impact forces exceeding 50,000 psi in hard-rock breaking applications. Pilbara iron ore operations in Western Australia generate concentrated demand as operators prioritize machine availability over extended rebuild intervals.
- Buckets:Ground-engaging tools fabricated with tungsten-carbide inserts and work-hardening alloy formulations extend lip life in loader and excavator applications. Chile's copper belt maintenance hubs drive specification upgrades as SERNAGEOMIN operational standards mandate certified replacement protocols for structural attachments.
- Attachments:Bolt-on components including rippers, thumbs, and couplers engineered to OEM specifications for multipurpose machinery deployment.
- Drilling Tools:Sensor-embedded bits and automated tool systems capturing premium pricing through precision wear monitoring and autonomous rig integration.
Buckets anchor the volume base while drilling tools gain share at the steepest rate.
Application:
Cost tier stratification separates high-volume material handling from precision blasting and rock drilling applications requiring specialized metallurgy and certification.
- Excavation:Continuous loading and digging operations in surface and underground environments subject ground-engaging tools to abrasive wear and cyclic fatigue.
- Material Handling:High-volume transport and transfer applications dominating replacement part consumption across Pilbara iron ore and Chilean copper operations.
- Blasting:Drill-and-blast cycles requiring consumable bits and rods with tungsten-carbide cutting structures optimized for specific rock hardness profiles.
- Rock Drilling:Automated drilling tool systems integrating sensor technology for real-time wear monitoring and autonomous rig control in hard-rock extraction.
Material handling commands the largest installed base expenditure while rock drilling exhibits the steepest technology premium expansion.
End User:
Customer type determines procurement architecture, with tier-one miners consolidating direct OEM relationships while contractors fragment across independent distribution channels.
- Mining Operators:Tier-one extraction companies negotiating component-specific performance agreements and captive parts revenue streams through direct-to-mine-site service networks.
- Contractors:Underground and surface mining service providers compressing replacement cycles for wear components as emissions thresholds tighten across Australia, China, and Chile.
- OEMs:Original equipment manufacturers leveraging global parts distribution centers to sustain long-term service contracts and remanufactured component programs.
- Service Providers:Independent rebuild specialists and aftermarket fabricators competing for inventory access as dealer channel control fragments.
Mining operators concentrate procurement volume while contractors generate the most fragmented sourcing patterns.
Technology:
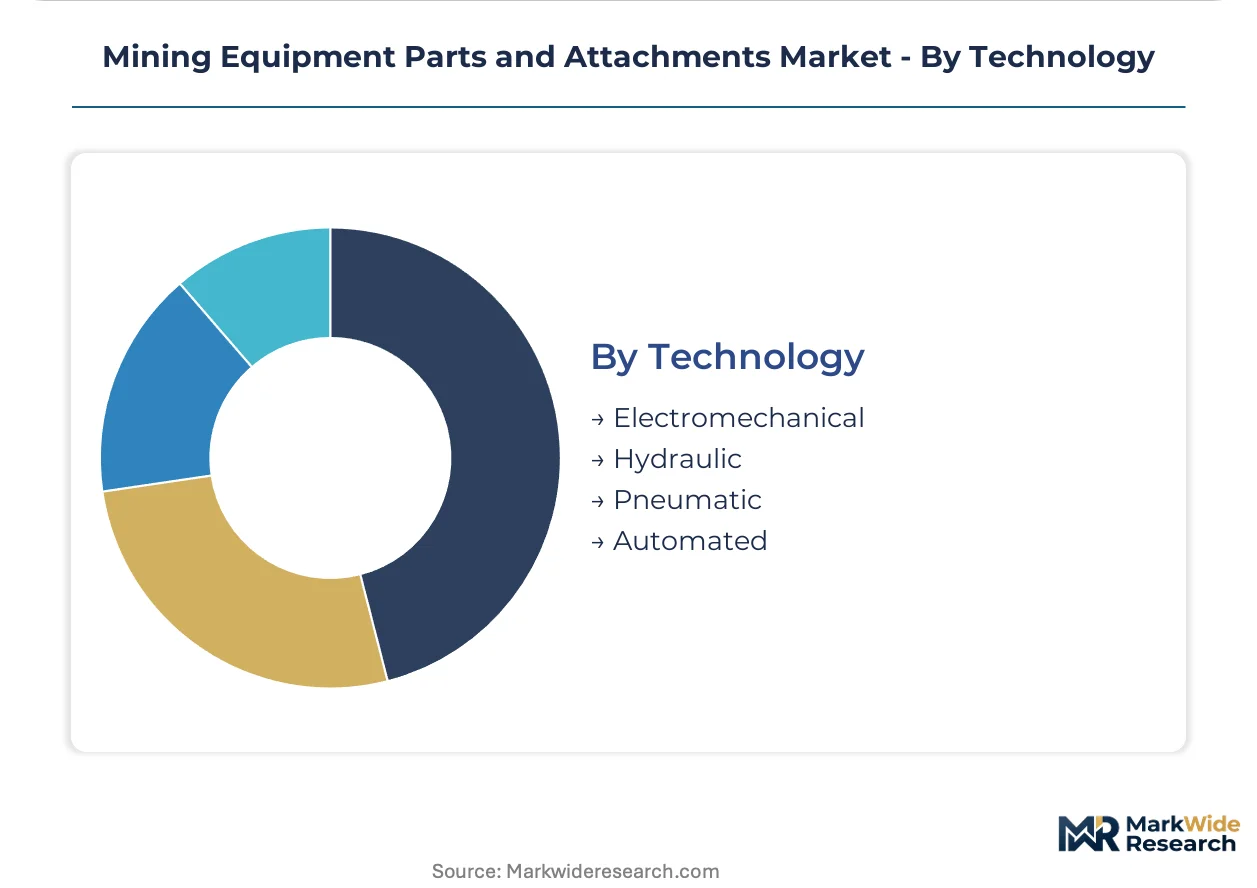
Maturity gradients separate established electromechanical and hydraulic systems from emerging automated platforms displacing operator-dependent drilling and loading cycles.
- Electromechanical:Mature drivetrain systems in underground haulage facing displacement risk from hydraulic-electric hybrid alternatives in hard-rock loading applications.
- Hydraulic:Dominant power transmission architecture for hammers, buckets, and attachments, now requiring aftertreatment-compatible packages under EPA Tier 4 Final and EU Stage V standards.
- Pneumatic:Compressed-air systems retaining niche deployment in specific drilling and breaking applications with lower power density requirements.
- Automated:Sensor-embedded tool systems and autonomous rig control technology attracting the fastest-growing capital allocation as mines pursue operator-reduced extraction cycles.
Hydraulic systems retain the broadest installed base while automated platforms climb the fastest in new capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western Australia's Pilbara iron ore belt while Chilean copper maintenance hubs face margin compression from SERNAGEOMIN certification costs. This asymmetry shapes procurement architecture across the mining equipment parts and attachments value chain.
Australia
Pilbara iron ore operations drive continuous demand for high-manganese steel ground-engaging tools and bucket attachments. The country's diesel particulate regulations tighten emissions thresholds for rebuilt engines and hydraulic systems used in underground contractor fleets. Perth anchors distribution networks serving tier-one miners with direct-to-mine-site service capabilities.
Chile
Copper belt maintenance hubs generate specification upgrades for certified replacement protocols on structural attachments. SERNAGEOMIN operational standards mandate inspection intervals and documentation for rebuilt components in hard-rock extraction. Antofagasta and Santiago concentrate supplier qualification activities as contractors consolidate vendor lists to reduce compliance audit burden.
China
GB standards for non-road mobile machinery enforce dual carbon goals that restrict remanufacturing permits for high-emission component categories. The MEE's certification delays create inventory mismatches for hydraulic system suppliers serving cross-border equipment fleets. Foundries in select East Asian clusters dominate chromium carbide overlay fabrication capacity.
United States
Surface mining fleets accelerate demand for aftertreatment-compatible hydraulic packages under EPA Tier 4 Final standards. Remanufactured component programs anchor North American demand through captive distribution networks. Appalachian coal regions and Southwest copper operations concentrate rebuild specialist activities.
Brazil
Iron ore and bauxite extraction in Minas Gerais and Pará states sustains replacement part consumption for material handling equipment. ANVISA-aligned safety protocols intersect with mining operational standards for structural attachment inspections. São Paulo-based service providers compete for independent aftermarket fabricator certification.
Mining Equipment Parts and Attachments Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply positions. The vendor base clusters around three strategic archetypes: global OEMs with captive distribution networks, technology-forward drilling system specialists, and independent aftermarket fabricators competing on alloy formulation access. Consolidation pressures favor scale players with global parts distribution center footprints, while regional specialists defend positions through SERNAGEOMIN and Australian certification proximity.
Among the named players, Komatsu and Caterpillar exemplify platform integrators with established direct-to-mine-site service networks, while Sandvik occupies a technology leadership position in automated drilling tool systems. These three anchors represent divergent competitive vectors: captive distribution scale, remanufactured component program depth, and precision wear monitoring integration respectively.
| Leading Market Players |
|---|
| Komatsu |
| Atlas Copco |
| Metso Corporation |
| Terex Corporation |
| FLSmidth & Co. |
| Sandvik |
| Hitachi Construction Machinery |
| Timken Global |
| Caterpillar |
| Others |
Supply Flow & Price Mechanics
East Asian foundry clusters in Jiangsu and Shandong provinces control chromium carbide overlay fabrication capacity, translating alloy price volatility into uneven pricing power across hydraulic hammer and bucket attachment tiers. This concentration forces buyers to absorb premium markups during supply squeezes or accept extended lead times that compress mine site availability.
Pricing Analysis
Configured-to-order pricing for sensor-embedded drilling tools commands spreads exceeding standard catalog offerings by certification tier and metallurgical grade. The dominant structure runs contract-based long-term offtake agreements tying volume commitments to SERNAGEOMIN-certified replacement protocols. Price differentiation centers on tungsten-carbide insert quality and after-sales telemetry bundling. Cost compression in standard-grade ground-engaging tools is intensifying as independent fabricators gain Australian certification access. Tier-one mining operators exhibit lowest price sensitivity due to uptime guarantees, while underground contractors face acute pressure on rebuild program budgets.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk planning for rebuilt engine block and hydraulic package suppliers. Fabrication capacity concentrates in China, South Korea, and select Indian specialty steel foundries. Production draws from high-manganese steel billet, tungsten-carbide powder, and chromium carbide wire feedstock. Single-source vulnerability persists in automated drilling tool sensor modules. Distribution runs through OEM captive networks and independent aftermarket channels serving Pilbara and Chilean copper belt maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated drilling tool systems and emissions-compliant hydraulic architectures are disrupting procurement patterns across tier-one mining operations, with EPA Tier 4 Final and Australia's diesel particulate regulations accelerating technology refresh cycles.
For Market Incumbents: Insulate captive parts revenue through direct-to-mine-site service network expansion in Western Australia and Chile, while deepening backward integration into high-manganese steel alloy formulation to offset chromium carbide overlay supply concentration. Hydraulic-electric hybrid drivetrains threaten electromechanical haulage incumbents; certification investment in MEE-compliant remanufacturing protocols defends rebuild program margins against permit restrictions. For New Entrants and Emerging Players: Mid-market automated drilling tool refurbishment services in Chile's Antofagasta maintenance corridor represent the most penetrable entry point, with SERNAGEOMIN certification proximity as the qualifying barrier. Independent aftermarket fabricators certified to Australian national mine safety frameworks capture share from dealer channel fragmentation. Go-to-market execution should anchor on performance-based wear monitoring subscriptions rather than transactional component sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated platform specialists with sensor-embedded bit portfolios and autonomous rig integration capabilities. Long-term viability over the coming decade rests on displacement of operator-dependent drilling cycles and emissions-compliant hydraulic system penetration. Acquisition target archetypes include certified rebuild specialists with captive alloy supply and telemetry-enabled wear monitoring developers. Watch EPA Tier 4 Final enforcement consistency as the inflection signal for aftermarket revenue mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Mine-Site Service Network Expansion | Komatsu and Caterpillar bypass dealer channels to capture tier-one Pilbara and Chilean copper belt parts revenue streams. |
| Automated Drilling Tool System Development | Sandvik leverages sensor-embedded bit technology to command premium pricing through precision wear monitoring integration. |
| Remanufacturing Certification Investment | Suppliers secure MEE dual carbon permits and Australian diesel particulate compliance to defend rebuild program margins. |
| High-Manganese Steel Alloy Backward Integration | OEMs reduce chromium carbide overlay supply concentration risk through captive foundry capacity in East Asian clusters. |
| Telemetry-Enabled Performance Contracting | After-sales unbundling shifts revenue from component transactions to outcome-based availability guarantees. |
Methodological Framework
A spread of perspectives from maintenance directors at tier-one mining operators, OEM procurement teams, aftermarket service heads, and hydraulic system rebuild specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Caterpillar and Komatsu, Australian TGA-equivalent mining safety framework documentation, Chilean SERNAGEOMIN operational standards, and Chinese MEE remanufacturing permit registries. Bottom-up segment sizing across hydraulic hammers, buckets, attachments, and drilling tools triangulated with top-down equipment fleet analysis.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application intensity, end-user procurement architecture, and technology maturity gradient. CAGRs were derived from replacement cycle compression rates and capital allocation shifts toward automated platforms. Industry-specific forecast inputs incorporated ore hardness profiles in Chile's copper belt and Pilbara iron ore extraction intensity metrics.
Practitioners should monitor EPA Tier 4 Final enforcement delays, MEE dual carbon permit expansion or contraction, and tungsten-carbide insert technology migration rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mining Drill Bits Market