
 Titanium Sponge for Aerospace and Defense Market | 2026-2036
Titanium Sponge for Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Sponge for Aerospace and Defense Market Intelligence
Long-term supply agreements with integrated material traceability services are shifting procurement focus from transactional spot buys to strategic partnerships. VSMPO-AVISMA Corporation leverages its significant production scale and vertical integration to secure major contracts with global aircraft manufacturers. TIMET (Titanium Metals Corporation) specializes in high-purity aerospace-grade sponge for critical structural components, while Toho Titanium Co., Ltd. differentiates through its advanced refining processes.
Titanium sponge is a porous, high-purity form of titanium metal, typically produced via the Kroll process through the magnesium reduction of titanium tetrachloride. This intermediate material serves as the essential precursor for producing the titanium ingots and alloys used in high-performance aerospace and defense applications. Aerospace Grade sponge commands a premium due to its required purity levels, often exceeding 99.7%. Demand is concentrated in applications like aircraft frames and spacecraft components, where superior strength-to-weight ratio is paramount.
Material qualification and supply chain traceability are governed by stringent standards from bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). Compliance with quality management specifications such as ISO 9001 and AS9100 is a prerequisite for market entry, dictating production process control. Suppliers must continually navigate evolving geopolitical trade policies and invest in energy-efficient production methods to maintain long-term competitiveness.
Market Dynamics
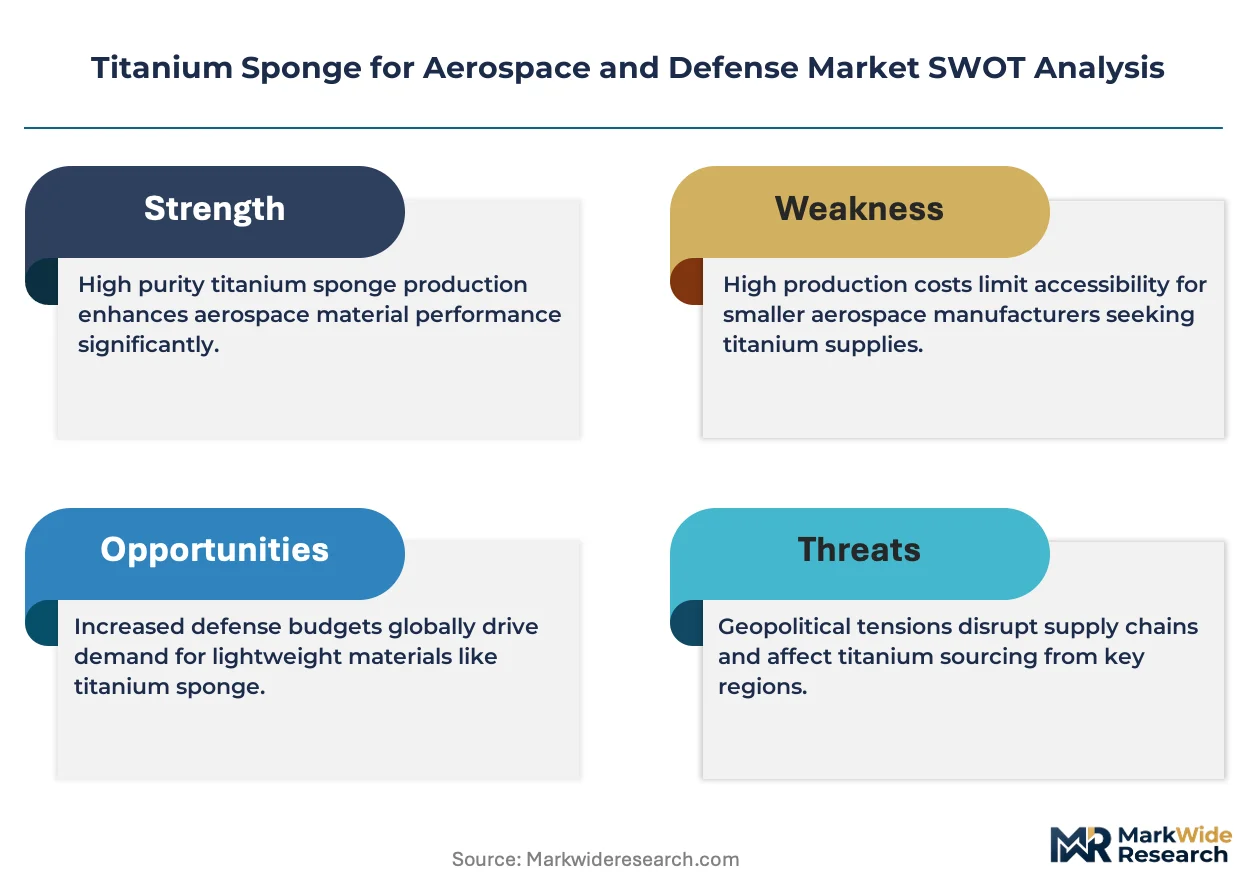
The market's central dynamic is the geopolitical friction between highly concentrated production capacity in China and the aerospace and defense sector's demand for secure, traceable supply chains. This tension influences all material qualification and procurement strategies.
Growth Catalysts
- Next-Generation Platforms:Demand from new military aircraft programs and hypersonic missile systems requires materials with higher purity and performance specifications, driving consumption of premium-grade sponge.
- Supply Chain Security Policies:US and European defense procurement regulations increasingly prioritize sourcing from allied nations, creating demand for non-Chinese sponge and reinforcing regional supply chains.
- Commercial Space Expansion:The rapid growth of commercial satellite constellations and deep space exploration missions by entities like NASA creates a new, non-cyclical demand source for lightweight structural components.
Market Restraints
- Energy-Intensive Production:The Kroll process is extremely energy-intensive, making sponge production costs highly sensitive to regional electricity price volatility and carbon pricing policies.
- Geopolitical Supply Risk:Heavy reliance on Chinese production creates significant supply chain vulnerability for Western defense contractors, subject to export controls or trade disputes.
- Stringent Qualification Cycles:The lengthy and costly material qualification processes mandated by bodies like the FAA and EASA create high barriers to entry for new suppliers.
Strategic Opportunities
- Additive Manufacturing Feedstock:Developing titanium powders directly from sponge or via novel processes for 3D printing opens a high-value market for complex, near-net-shape aerospace components.
- Alternative Production Geographies:Strategic investment in new sponge production facilities in North America or allied nations like Japan can capture demand from buyers seeking to diversify away from China.
- Closed-Loop Recycling Systems:Establishing certified systems to recycle titanium scrap back into high-purity sponge offers a path to reduce energy consumption and reliance on virgin material.
Industry Challenges
- High Capital-Expenditure Barriers:Constructing new, compliant Kroll process facilities requires immense upfront capital investment and long construction timelines, deterring new market entrants.
- Specialized Workforce Scarcity:A shortage of metallurgists and process engineers with experience in high-purity titanium production hinders capacity expansion and process optimization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Sponge for Aerospace and Defense Market |
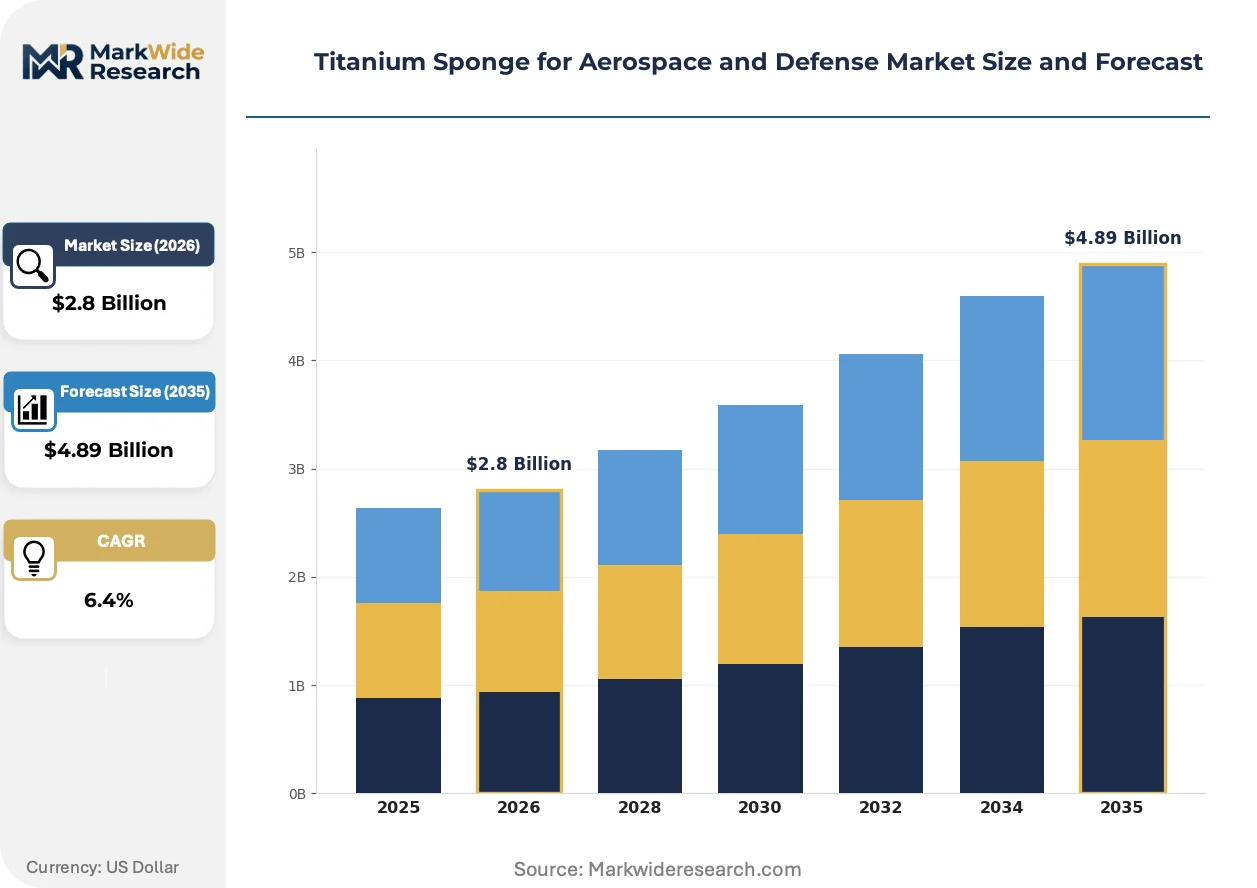
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Grade, Military Grade, Aerospace Grade, Industrial Grade Application: Aircraft Frames, Missile Systems, Spacecraft Components, Naval Equipment, Satellite Structures End User: Aircraft Manufacturers, Defense Contractors, Space Agencies, Shipbuilders, Research Institutions Technology: Vacuum Distillation, Kroll Process, Electron Beam Melting, Plasma Arc Melting |
| Companies Covered | Allegheny Technologies Incorporated, Baoji Titanium Industry Co., Ltd., VSMPO-AVISMA Corporation, Chaoyang Jinda Titanium Industry, Advanced Metallurgical Group N.V., Toho Titanium Co., Ltd., TIMET (Titanium Metals Corporation), Zunyi Titanium Co., Ltd., OSAKA Titanium Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Sponge for Aerospace and Defense Market Strategic Shifts & Innovations
Innovations in production and supply chain management are transforming the competitive landscape. The industry is moving toward more efficient, data-driven processes to meet stringent quality demands and navigate geopolitical supply risks.
Novel production methods, such as alternative reduction processes, offer a path to create high-purity titanium with a lower energy footprint. Specialty alloy producers and defense research agencies are exploring these technologies for bespoke applications. This shift is decentralizing production capability away from massive, geographically concentrated Kroll facilities toward smaller, potentially more localized operations.
Stricter regulatory enforcement by the FAA and EASA on complete material traceability is compelling suppliers to adopt digital tracking systems. These mandates require auditable proof of origin from the initial sponge batch through every processing step. The entire aerospace supply chain is most affected, with ingot melters and forgers investing heavily in compliance software to maintain market access.
Buyer behavior is pivoting from transactional spot buys toward strategic, long-term agreements for sponge supply. These partnerships often include integrated services like vendor-managed inventory and shared risk on price volatility, displacing the role of traditional commodity brokers. This procurement pattern is most visible with major aircraft manufacturers in North America and Europe.
Titanium Sponge for Aerospace and Defense Market Segmentation
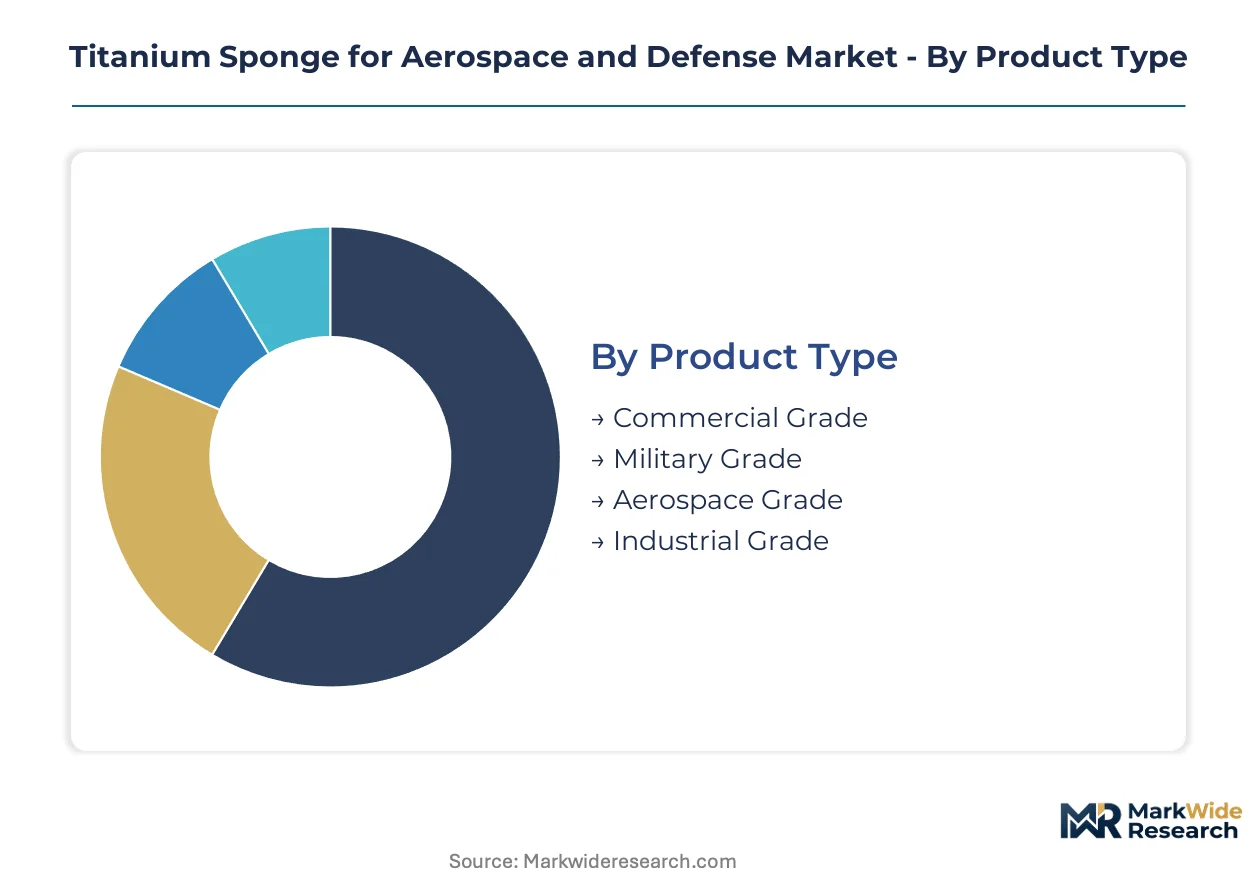
Understanding the segmentation within the titanium sponge market for aerospace and defense clarifies the diverse material requirements and procurement strategies. Each segment reflects distinct performance specifications, application demands, and end-user priorities, shaping the competitive landscape.
Product Type:
The upgrade and replacement cycles for aerospace and defense platforms heavily influence the specifications for various titanium sponge product types.
- Aerospace Grade:This product type exceeds 99.7% purity, serving as the essential precursor for critical structural components in aircraft frames and spacecraft. Stringent certification by bodies like the FAA and EASA drives demand for this premium material, particularly in US and European manufacturing.
- Military Grade:Tailored for specific alloy compositions, this grade meets the demanding requirements of missile systems and naval equipment, offering superior strength-to-weight ratios and ballistic resistance. Defense procurement regulations in allied nations primarily drive consumption for these specialized applications.
- Commercial Grade:Standard purity levels characterize this grade, suitable for less critical aerospace structures or industrial applications that benefit from titanium's inherent corrosion resistance.
- Industrial Grade:This grade finds use in general industrial sectors requiring titanium's strength and chemical inertness, outside of direct high-performance aerospace or defense component manufacturing.
Volume placements concentrate in Commercial Grade; the faster expansion belongs to Aerospace Grade.
Application:
The value chain for titanium sponge production extends through diverse applications, each requiring specific material properties and processing.
- Aircraft Frames:This application demands substantial volumes of high-purity titanium alloys, crucial for achieving structural integrity and significant weight reduction in both commercial and military aircraft. Major global aircraft manufacturers, including those in North America and Europe, drive this demand.
- Spacecraft Components:Advanced titanium alloys are critical for propulsion systems, structural elements, and thermal management within deep space probes and orbital vehicles. Entities like NASA and commercial space companies in the US are key drivers for this specialized, high-performance material.
- Missile Systems:Titanium integrates into lightweight airframes and engine components for advanced defense programs, directly enhancing speed, maneuverability, and overall performance.
- Naval Equipment:Titanium is employed in submarine hulls, propulsion components, and other marine structures due to its exceptional corrosion resistance and high strength in saltwater environments.
- Satellite Structures:Communication and observation satellite platforms utilize titanium for its low density and high strength, which are essential for minimizing launch mass and ensuring long-term operational reliability.
Aircraft Frames currently represent the largest application area; however, Spacecraft Components are gaining share fastest.
End User:
Supply concentration and procurement strategies are heavily influenced by the specific needs and regulatory environments of various end-user segments.
- Aircraft Manufacturers:These entities procure titanium sponge for conversion into ingots and alloys, forming primary structures and engine components for both commercial and military aircraft programs. Companies like Boeing and Airbus are significant consumers.
- Defense Contractors:They utilize titanium sponge for advanced weaponry, armored vehicles, and critical defense platforms, adhering to strict government procurement regulations and national security protocols. Major US defense contractors are primary buyers.
- Space Agencies:Ultra-high purity titanium is essential for mission-critical components in rockets, satellites, and exploration vehicles, with performance and reliability overriding cost considerations.
- Shipbuilders:This segment employs titanium for specialized naval vessels and marine applications where unparalleled corrosion resistance and strength are paramount, particularly in submarine construction.
- Research Institutions:These organizations consume smaller quantities of titanium sponge for material science studies, alloy development, and prototyping next-generation aerospace and defense technologies.
Demand concentration remains highest among Aircraft Manufacturers; however, Space Agencies exhibit significant growth in specialized material requirements.
Technology:
The maturity and innovation cycles within titanium sponge production technologies directly impact purity, energy efficiency, and overall production costs.
- Kroll Process:This remains the dominant industrial method for producing titanium sponge, involving the magnesium reduction of titanium tetrachloride, characterized by its high energy consumption. China is the primary global producer utilizing this established technology.
- Vacuum Distillation:Often applied as a post-Kroll purification step, this technology removes residual magnesium and magnesium chloride, significantly enhancing the purity of titanium sponge. This process is crucial for meeting stringent aerospace material specifications.
- Electron Beam Melting:This advanced refining technology processes titanium sponge into high-purity ingots, effectively removing interstitial impurities and creating homogeneous alloys for demanding aerospace applications.
- Plasma Arc Melting:An alternative refining process for titanium, offering advantages in melting scrap and producing specialized alloys with precisely controlled chemistries for high-performance defense applications.
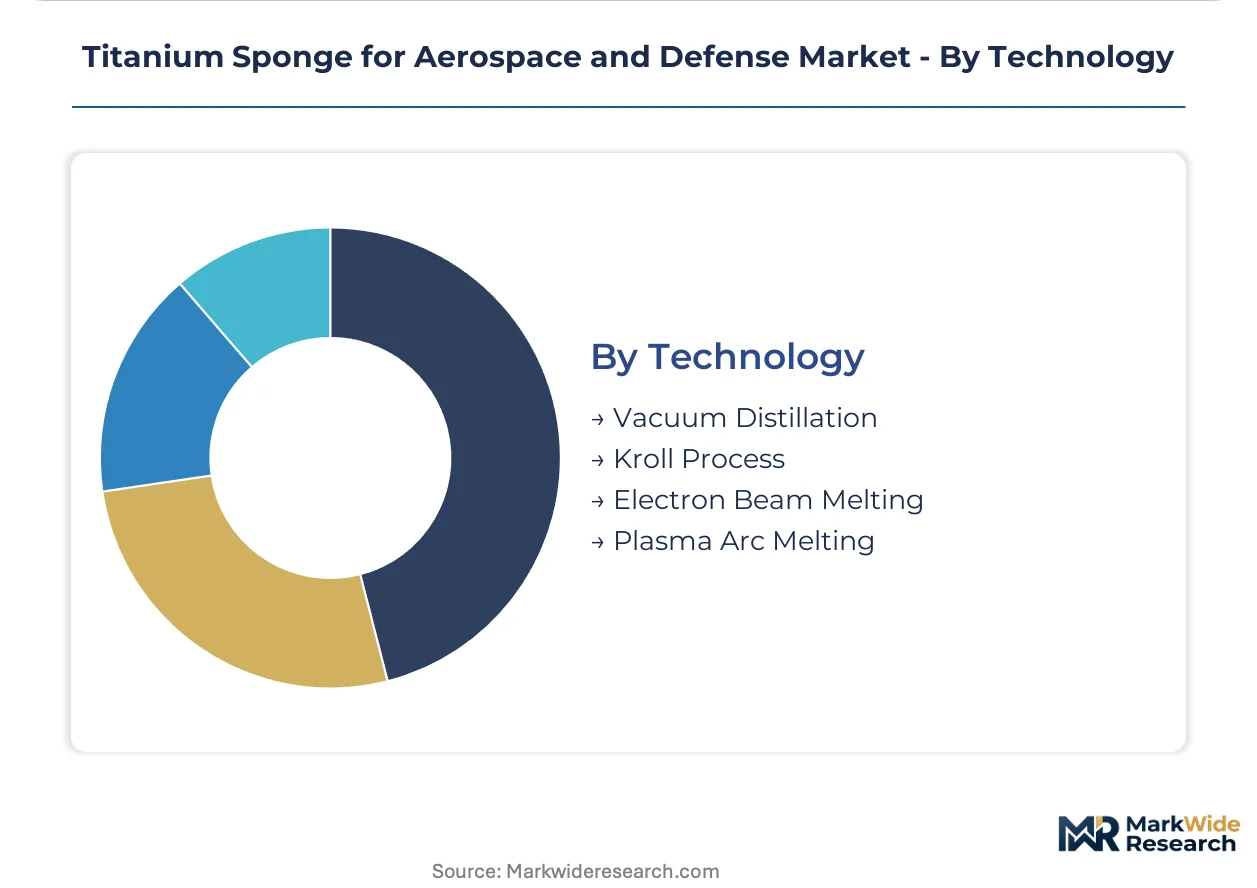
The Kroll Process accounts for the vast majority of current production volume; however, Electron Beam Melting is critical for high-purity alloy development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for titanium sponge in aerospace and defense is shaped by the tension between highly concentrated production capacity in China and the Western aerospace sector's demand for secure, traceable supply chains. This dynamic drives strategic investments and procurement shifts globally. Key regions prioritize either production dominance or supply chain resilience.
United States
The United States drives significant demand for premium titanium sponge, fueled by next-generation military aircraft programs and the expanding commercial space sector. US defense procurement regulations, such as the Buy American Act, increasingly prioritize domestic or allied nation sourcing. Aerospace clusters in Seattle and Southern California lead in consuming high-purity titanium for critical airframe and spacecraft components.
China
China dominates global titanium sponge production, supported by strategic state-backed industrial policies aimed at securing material independence. The country's dual carbon goals influence energy-intensive Kroll process operations, pushing for efficiency improvements. Industrial hubs like Baoji are central to titanium sponge manufacturing, supplying both domestic and international markets under evolving export controls.
France
France represents a major European consumer of aerospace-grade titanium sponge, primarily for Airbus production lines and national defense initiatives. EASA certification mandates stringent material quality and traceability, influencing procurement from trusted suppliers. Toulouse serves as a critical aerospace manufacturing hub, integrating titanium alloys into both commercial and military aircraft structures.
Japan
Japan focuses on high-purity titanium sponge production and advanced refining processes, leveraging METI support for material science innovation. The country's aerospace sector demands specialized alloys for domestic aircraft programs and components supplied to global manufacturers. Osaka Titanium Technologies exemplifies Japan's commitment to high-quality material output, catering to stringent aerospace specifications.
Germany
Germany's aerospace and defense industries require high-quality titanium sponge for Airbus components and sophisticated defense platforms. AS9100 quality management specifications are a prerequisite for suppliers, ensuring robust production process control. Hamburg, a significant aerospace center, utilizes advanced titanium alloys for structural integrity and weight reduction in aircraft manufacturing.
Titanium Sponge for Aerospace and Defense Market Key Industry Players
Top-tier vendors anchor large-scale Kroll process production, while specialized players focus on high-purity refining for aerospace applications. The market structure exhibits concentration among a few global giants and fragmentation among regional processors. Strategic archetypes include vertically integrated producers, pure-play sponge refiners, and niche alloy developers. Capacity expansion in allied nations and technology licensing for novel production methods represent dominant competitive moves.
Among vertically integrated producers, VSMPO-AVISMA Corporation exemplifies large-scale production and significant market influence. TIMET (Titanium Metals Corporation) represents a specialist in high-purity aerospace-grade sponge, crucial for critical structural components. Toho Titanium Co., Ltd. occupies a position among innovators, differentiating through its advanced refining processes for demanding applications. These entities collectively shape the global supply dynamics.
| Leading Market Players |
|---|
| Allegheny Technologies Incorporated |
| Baoji Titanium Industry Co., Ltd. |
| VSMPO-AVISMA Corporation |
| Chaoyang Jinda Titanium Industry |
| Advanced Metallurgical Group N.V. |
| Toho Titanium Co., Ltd. |
| TIMET (Titanium Metals Corporation) |
| Zunyi Titanium Co., Ltd. |
| OSAKA Titanium Technologies Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Innovations in the Kroll process simultaneously reshape cost economics and influence supply concentration within the titanium sponge market. Energy-intensive production remains a significant cost driver, while geopolitical tensions increasingly prioritize secure supply chains over lowest-cost sourcing.
Pricing Analysis
Cost-down pressure on commercial-grade sponge accelerates because Chinese producers dominate this segment with scaled output. The dominant pricing model involves contract-based long-term offtake agreements for aerospace and defense grades, supplemented by some transactional spot buys for commercial applications. Price differentiation stems from purity levels, with aerospace-grade sponge commanding premiums due to stringent FAA and EASA certification. Vertical integration by major players like VSMPO-AVISMA Corporation also influences pricing. Space Agencies exhibit the least price sensitivity due to mission-critical performance demands, while commercial-grade buyers remain most sensitive.
Supply Chain Analysis
Titanium sponge supply rests heavily on China, which accounts for the vast majority of global production capacity, creating a geopolitical risk for Western buyers. Key raw material dependencies include titanium tetrachloride and magnesium, both essential for the Kroll process. This heavy reliance on Chinese production generates significant single-source vulnerability for Western defense contractors. The distribution model primarily involves direct, long-term agreements between sponge producers and major aircraft manufacturers or defense contractors, with a smaller role for commodity brokers in less critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cost-of-compliance story, with stringent FAA and EASA certification creating a significant barrier-to-entry moat for compliant players.
For Market Incumbents: Lock in long-term supply agreements with global aircraft manufacturers to secure demand against geopolitical supply risks. Invest in energy-efficient Kroll process innovations to mitigate rising electricity costs and carbon pricing policies. Deepen vertical integration into ingot and alloy production to control material quality and enhance supply chain traceability. Focus R&D on novel reduction methods to reduce reliance on the traditional Kroll process.
For New Entrants and Emerging Players: Capture white-space opportunities in additive manufacturing feedstock development for complex aerospace components. Target the specialized high-purity aerospace-grade segment, focusing on non-Chinese supply to address Western defense procurement regulations. Establish strategic partnerships with North American and European defense contractors, offering certified closed-loop recycling systems as a sustainable go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized high-purity refiners and novel technology developers in allied nations. Long-term viability is strong due to persistent aerospace and defense demand, coupled with increasing geopolitical pressure for diversified supply. Acquisition targets include regional producers in North America or Japan with advanced refining capabilities. A key signal to watch is the announcement of new Kroll process facilities or alternative reduction technology investments outside of China.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Allied Nations | Diversifies supply away from China, enhancing supply chain security for Western aerospace and defense. |
| Long-term Supply Agreements with OEMs | Secures stable demand for producers and guarantees material access for major aircraft manufacturers. |
| Investment in Energy-Efficient Kroll Process | Reduces operational costs and aligns with global dual carbon goals, improving competitiveness. |
| Development of Additive Manufacturing Feedstock | Opens high-value markets for complex, near-net-shape components in aerospace applications. |
| Implementation of Closed-Loop Recycling Systems | Reduces reliance on virgin material and lowers energy consumption, addressing sustainability mandates. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. The research combined extensive secondary data gathering with primary interviews conducted with aerospace engineers, defense procurement officers, material scientists, and Kroll process plant managers. This approach ensured a robust understanding of market dynamics, triangulating insights from both top-down and bottom-up perspectives.
The forecast framework modeled market dimensions at a granular level, including product type, application, end-user, technology, and regional supply chain strategies across the analysis window. Compound annual growth rates were derived from historical trends, projected demand from new military aircraft programs, and commercial space expansion. Key industry-specific forecast inputs included defense spending forecasts and commercial aircraft build rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical trade policies and energy price volatility. Forecasts reflect assumptions regarding material qualification timelines and technological advancements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace Titanium Market