
 Asia-Pacific Aerospace Composites Market | 2026-2036
Asia-Pacific Aerospace Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aerospace Composites Market Outlook
Tier-one procurement channels between Japanese carbon fiber producers and Chinese airframe integrators is rewriting material flow patterns across the region. Toray Industries Inc. leverages its precursor-to-prepreg vertical chain to anchor supply security for narrowbody programs. TATA Advanced Materials Limited competes on cost-engineered preforms for regional jet platforms. Hexcel Corporation differentiates through qualified resin systems certified by multiple Asia-Pacific airworthiness authorities.
Asia-Pacific aerospace composites are fiber-reinforced polymer structures engineered to specific strength-to-weight ratios exceeding 200 MPa/(g/cm³), manufactured through controlled impregnation and autoclave cure cycles for primary load-bearing airframe applications. Carbon fiber dominates structural component applications where specific stiffness requirements exceed aluminum alternatives by factors of three to five. Prepreg technology leads commercial aviation manufacturing due to repeatable void content below one percent, while wet layup retains share in military retrofit programs where tooling investment constraints apply. Glass fiber occupies interior parts manufacturing where fire-smoke-toxicity regulations permit lower modulus specifications.
Japan's METI enforces JIS standards for carbon fiber tensile modulus classification, while China's SAMR administers GB certification for composite structural repair procedures in civil aviation. India's DGFT import licensing framework for aerospace-grade prepregs shapes local sourcing strategies for defense contractors. Stakeholders must monitor evolving airworthiness reciprocity agreements between national regulators as fleet commonality expands across Asia-Pacific airline networks.
Market Dynamics
Carbon fiber precursor supply concentration in Japan's Chubu region is forcing airframe integrators across Asia-Pacific to renegotiate long-term offtake agreements and accelerate qualification of alternative PAN sources.
Growth Catalysts
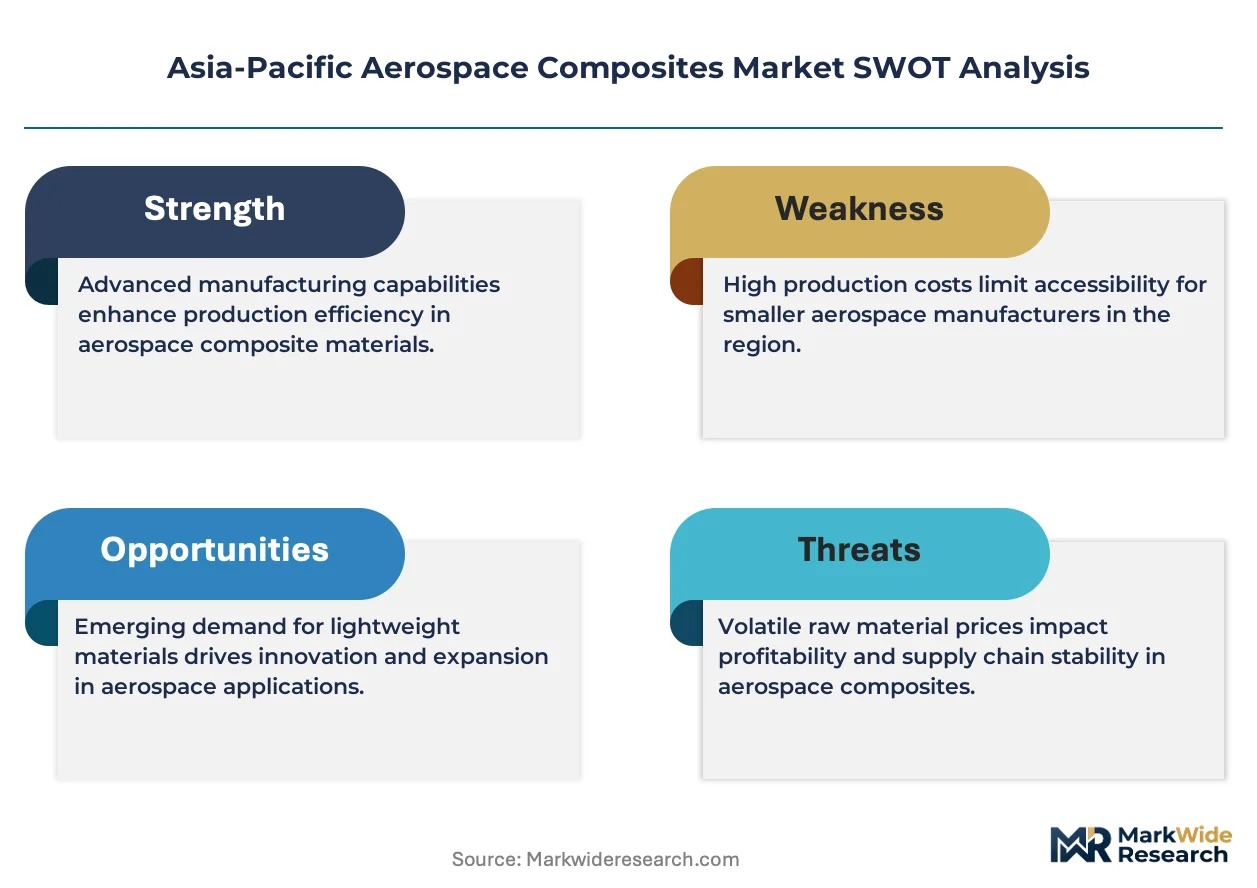
- Commercial narrowbody fleet expansion:Southeast Asian carriers are adding single-aisle aircraft at rates exceeding widebody orders, concentrating composite demand in fuselage barrel and wing skin applications.
- China's MIIT carbon fiber standards:Domestic qualification timelines for T800-grade prepreg have compressed from 24 months to 14 months, enabling faster substitution of imported material in COMAC supply chains.
- Out-of-autoclave curing:Large-scale OOA ovens are displacing autoclave capacity for wing spar production, reducing energy costs and enabling thicker monolithic sections.
Market Restraints
- Acrylonitrile price volatility:Feedstock costs for PAN precursor fluctuate with oil-indexed chemical pricing, compressing margin stability for carbon fiber producers.
- Single-source precursor dependency:Toray Industries and Mitsubishi Chemical control over 70% of global aerospace-grade PAN supply, creating concentration risk for tier-two fabricators.
- Repair certification fragmentation:Divergent GB, JIS, and FAA repair procedures force operators to maintain three parallel technician training programs.
Strategic Opportunities
- India defense aerospace:DGFT import licensing constraints for prepregs are creating captive demand for domestic autoclave capacity serving HAL and DRDO programs.
- Thermoplastic composites:PEEK and PPS matrix systems are enabling weldable primary structures that eliminate mechanical fastening in next-generation regional jets.
- Digital thread integration:Model-based definition workflows are collapsing design-to-manufacture handoff delays for composite tooling fabrication.
Industry Challenges
- Certified NDI technician scarcity:Ultrasonic and thermography inspection qualifications require 18-month apprenticeship cycles that outpace training program expansion.
- Multi-authority qualification burden:Simultaneous CAAC, JCAB, and DGCA certification for repair stations fragments engineering resources and extends approval timelines.
- Legacy aluminum-to-composite transition:MRO facilities lack hot bond repair capability for thermoset damage, forcing expensive component replacement over restoration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aerospace Composites Market |
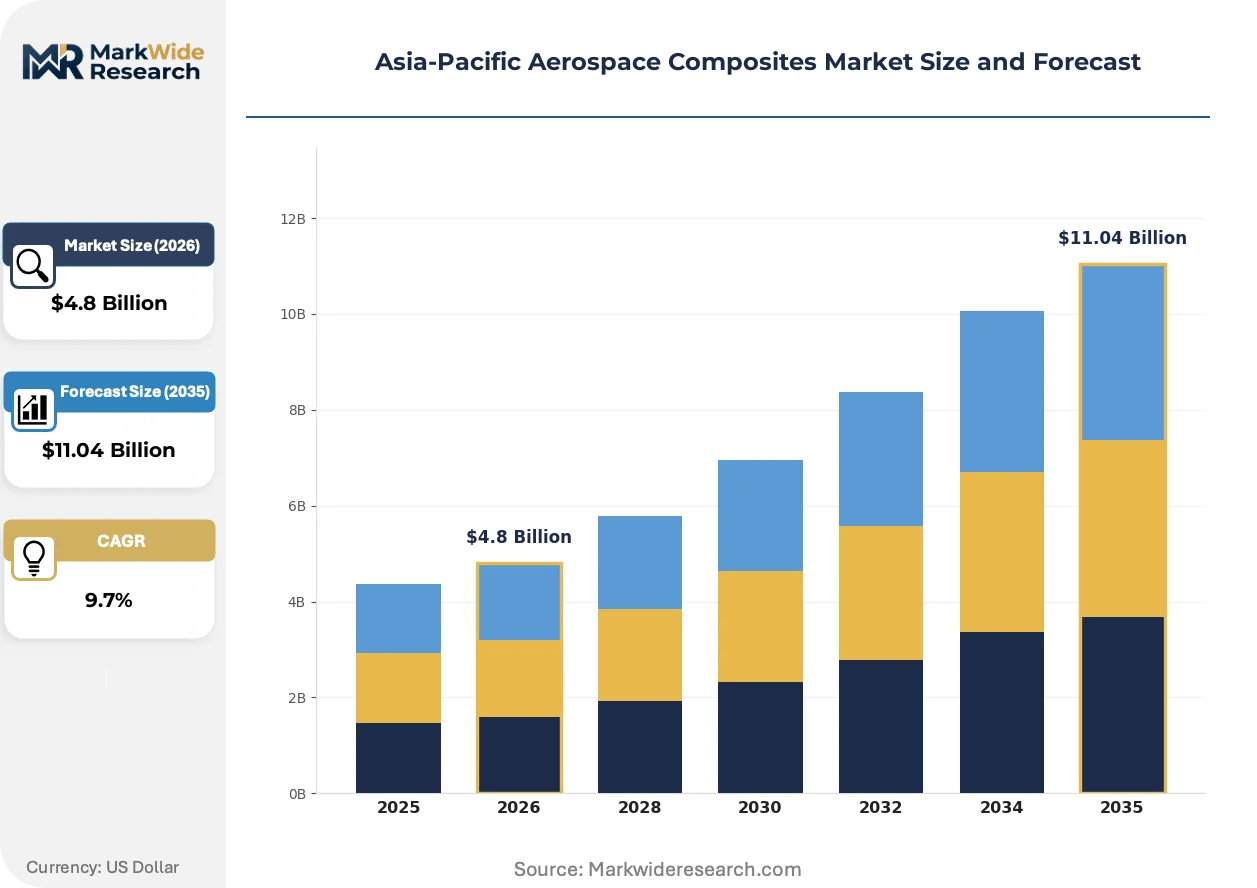
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Natural Fiber Application: Structural Components, Aerodynamic Surfaces, Interior Parts, Engine Components Technology: Prepreg, Wet Layup, RTM, Infusion End User: Commercial Aviation, Military Aviation, UAV Manufacturers, Aerospace OEMs |
| Companies Covered | Hexcel Corporation, Toho Tenax, Harbin Hafei Airbus Composite Manufacturing Centre Co., Ltd., SGL Carbon SE, Korea Composites Inc., Toray Industries Inc., TATA Advanced Materials Limited, Solvay SA, Mitsubishi Chemical Carbon Fiber and Composites Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aerospace Composites Market Strategic Shifts
Automated fiber placement is compressing layup labor content while digital twin architectures are collapsing inspection cycle times. These shifts are redistributing value capture from manual fabrication toward software-defined manufacturing.
Automated fiber placement heads with in-situ compaction control are enabling complex double-curved geometries previously requiring hand layup. Korean Air and SIA Engineering are retrofitting AFP gantries for A350 and 787 wing skin production. This hardware is digitizing the interface between CAD surface definitions and as-built fiber orientation, reducing scrap rates and enabling real-time path correction.
Japan's METI has mandated JIS R 7606 compliance for recycled carbon fiber tensile property disclosure, creating material passport requirements that extend through tier-three suppliers. The regulation is forcing disassembly and fiber recovery economics into original design specifications. European OEMs sourcing from Asia-Pacific fabricators are now requiring JIS-aligned documentation for circularity claims.
Airline technical procurement teams are consolidating composite repair sourcing under single-source MRO agreements that bundle material supply with station certification. This behavior is compressing the independent prepreg distributor channel in Southeast Asia. The shift is most visible in Singapore and Bangkok hubs where LCC fleet commonality enables standardized repair protocols across A320neo and 737 MAX platforms.
Asia-Pacific Aerospace Composites Market Segmentation
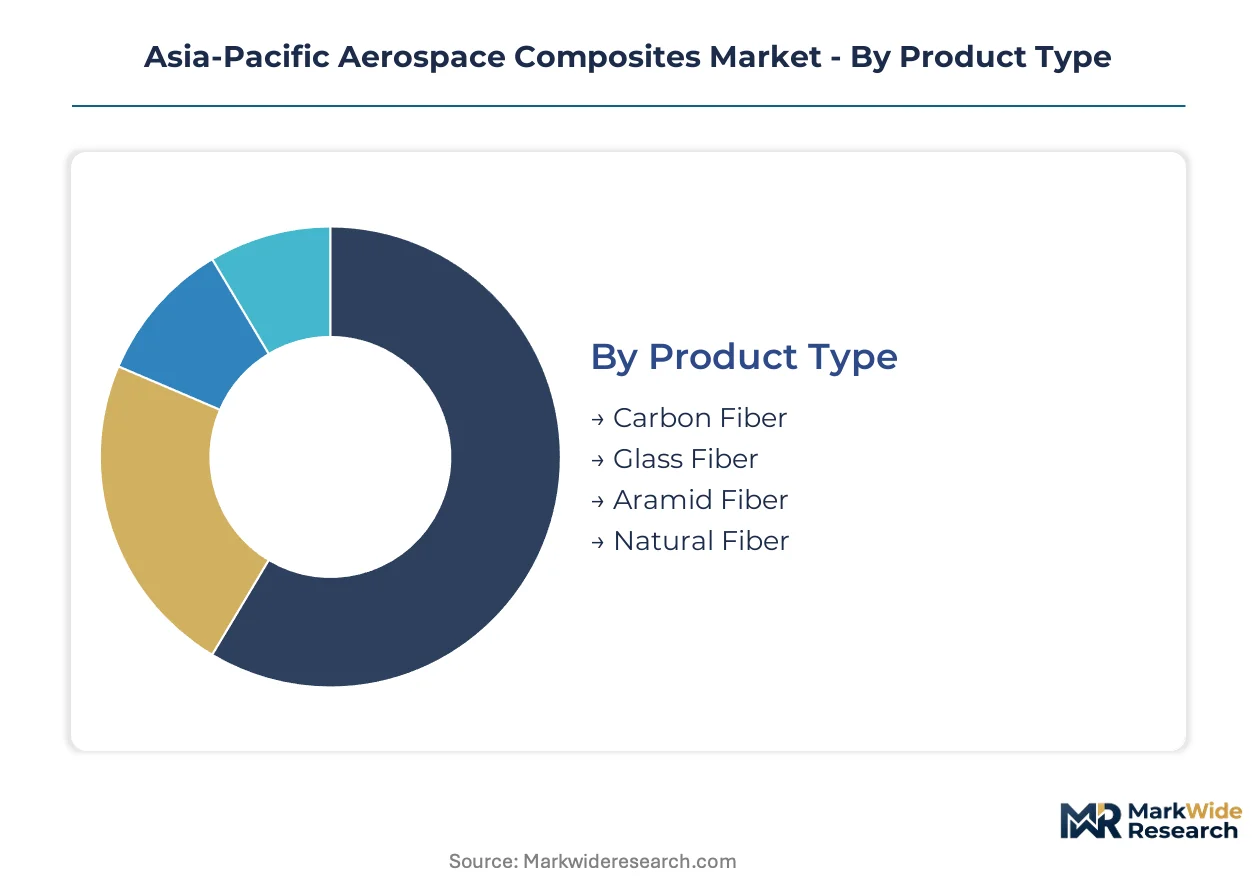
Segmentation in aerospace composites reveals where qualification cycles compress versus where legacy certification locks in incumbent technologies. Cycle-time variation across fiber grades and manufacturing processes directly shapes procurement strategy and inventory positioning for tier-one fabricators.
Product Type:
Carbon fiber commands the longest qualification timelines at 18-24 months for aerospace-grade certification, while natural fiber experiments turn over in 6-12 month prototype cycles without airworthiness burden.
- Carbon Fiber:PAN-based precursor systems deliver tensile modulus exceeding 230 GPa with fiber volume fractions above 60% in cured laminates. Demand clusters in China's Yangtze River Delta where COMAC suppliers co-locate with Toray and Mitsubishi Chemical precursor facilities, though single-source PAN dependency creates concentration risk for tier-two fabricators.
- Glass Fiber:E-glass and S-glass formulations dominate interior applications where fire-smoke-toxicity regulations permit lower modulus specifications. Southeast Asian MRO facilities in Singapore and Bangkok favor glass fiber for galley and sidewall panel refurbishment due to shorter repair certification cycles under CAAC-JCAB reciprocity frameworks.
- Aramid Fiber:Kevlar and Twaron aramid reinforcements serve ballistic protection and engine nacelle applications requiring abrasion resistance.
- Natural Fiber:Flax and hemp fiber experiments concentrate in UAV prototyping programs outside formal airworthiness frameworks.
Carbon fiber dominates installed base. Natural fiber is where expansion concentrates for non-certified applications.
Application:
Structural components absorb capital-intensive autoclave capacity while interior parts manufacturing tolerates lower-cost wet layup methods with compressed tooling investment.
- Structural Components:Wing spars, fuselage barrels, and carry-through structures require specific stiffness exceeding 150 GPa with void content below 1%. Japanese METI JIS standards and China's MIIT GB certification create dual-qualification burdens for components serving both CAAC and JCAB jurisdiction.
- Aerodynamic Surfaces:Control surfaces and fairings demand precise dimensional tolerance across temperature cycles from -55°C to 85°C. Korean Air and SIA Engineering automated fiber placement investments target this segment for A350 and 787 wing skin production.
- Interior Parts:Seat shells, overhead bins, and sidewalls prioritize fire retardancy over structural modulus.
- Engine Components:Fan blades and nacelle structures require oxidation-resistant matrix systems for thermal exposure.
Structural components represent the fastest-growing trajectory. Interior parts hold stable replacement demand.
Technology:
Prepreg manufacturing locks in aerospace-grade quality at energy-intensive autoclave costs, while out-of-autoclave methods compress cycle times for thicker monolithic sections.
- Prepreg:B-stage resin systems with controlled tack enable repeatable fiber placement and sub-1% void content after autoclave cure. China's MIIT has compressed domestic T800-grade prepreg qualification from 24 months to 14 months, accelerating import substitution in COMAC supply chains.
- Wet Layup:Room-temperature curing epoxy systems serve military retrofit programs where tooling investment constraints outweigh void content tolerance.
- RTM:Resin transfer molding enables complex geometry consolidation with reduced secondary bonding.
- Infusion:Vacuum-assisted resin infusion captures wind energy and secondary aerospace structures outside primary load paths.
Prepreg dominates installed base. Out-of-autoclave variants are where expansion concentrates.
End User:
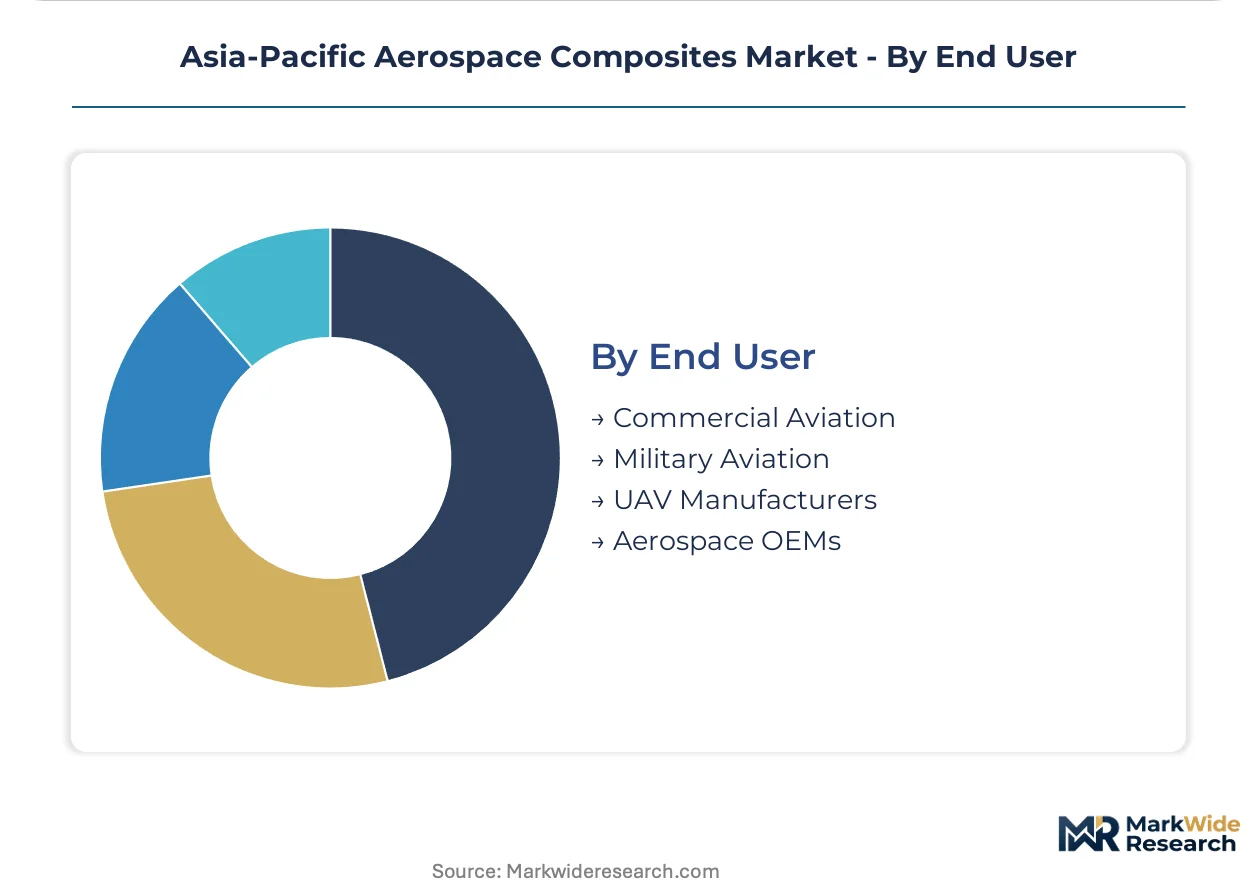
Commercial aviation procurement cycles span 5-7 year fleet planning horizons, while UAV manufacturers iterate on 12-18 month product development timelines without airworthiness gatekeeping.
- Commercial Aviation:Narrowbody fleet expansion across Southeast Asian carriers concentrates composite demand in fuselage barrel and wing skin applications. Single-aisle aircraft orders exceed widebody rates, directing tier-one fabricator capacity toward A320neo and 737 MAX platforms.
- Military Aviation:India's DGFT import licensing constraints for aerospace-grade prepregs create captive demand for domestic autoclave capacity serving HAL and DRDO programs.
- UAV Manufacturers:Uncrewed platforms outside formal certification frameworks enable rapid material substitution and process experimentation.
- Aerospace OEMs:Tier-one integrators coordinate multi-tier supply chains across precursor, prepreg, and fabrication stages.
Commercial aviation dominates installed base. UAV manufacturers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT carbon fiber standards and Japan's METI industrial policy are accelerating qualification timelines across the region. These regulatory frameworks compress domestic prepreg certification cycles and reshape material flow patterns between precursor producers and airframe integrators.
China
COMAC suppliers in the Yangtze River Delta are expanding narrowbody production capacity for C919 and ARJ21 programs. MIIT T800-grade prepreg qualification now completes in 14 months versus 24 months previously, enabling faster substitution of imported material. Shanghai and surrounding Jiangsu province host tier-one fabricators co-located with Toray and Mitsubishi Chemical precursor facilities.
Japan
Chubu region concentration of PAN precursor supply forces airframe integrators to renegotiate long-term offtake agreements. METI enforces JIS R 7606 compliance for recycled carbon fiber tensile property disclosure, creating material passport requirements through tier-three suppliers. Nagoya aerospace cluster anchors automated fiber placement investments for A350 and 787 wing skin production.
India
DGFT import licensing constraints for aerospace-grade prepregs create captive demand for domestic autoclave capacity serving HAL and DRDO defense programs. Bangalore and Hyderabad clusters concentrate UAV prototyping outside formal certification frameworks. Local fabricators compete on cost-engineered preforms for regional jet platforms.
South Korea
Korean Air and SIA Engineering are retrofitting automated fiber placement gantries for commercial narrowbody wing production. Seoul-Incheon corridor hosts composite repair stations consolidating under single-source MRO agreements that bundle material supply with certification. Out-of-autoclave curing investments target thicker monolithic wing spar sections.
Singapore
Changi aviation hub concentrates composite repair sourcing under consolidated technical procurement teams serving LCC fleet commonality. Bangkok-Singapore corridor enables standardized A320neo and 737 MAX repair protocols. MRO facilities face hot bond repair capability gaps for thermoset damage, forcing component replacement economics.
Asia-Pacific Aerospace Composites Market Competitive Environment
On the supply side, the industry is bifurcated between vertically integrated precursor-to-prepreg chains and specialized fabricators competing on process efficiency. Japanese and European chemical conglomerates anchor the upstream tier through captive PAN production and qualified resin systems. Mid-scale Asian fabricators differentiate through proximity to COMAC and defense procurement channels. Dominant competitive moves include qualification timeline compression through regulatory harmonization and automated fiber placement capacity expansion.
Within the integrated chemical conglomerate tier, Toray Industries Inc. and Mitsubishi Chemical Carbon Fiber and Composites Inc. exemplify upstream control over aerospace-grade PAN supply. Among diversified materials specialists, Hexcel Corporation and Solvay SA occupy positions defined by multi-authority resin system certification. TATA Advanced Materials Limited represents the cost-optimized fabricator archetype serving regional defense and commercial programs.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toho Tenax |
| Harbin Hafei Airbus Composite Manufacturing Centre Co., Ltd. |
| SGL Carbon SE |
| Korea Composites Inc. |
| Toray Industries Inc. |
| TATA Advanced Materials Limited |
| Solvay SA |
| Mitsubishi Chemical Carbon Fiber and Composites Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source PAN precursor dependency in Japan's Chubu region determines both the spread between aerospace-grade and industrial-grade carbon fiber pricing and the geographic configuration of tier-one fabricator clusters across the Asia-Pacific. Toray Industries and Mitsubishi Chemical's control over precursor supply forces airframe integrators into long-term offtake negotiations that compress margin buffers for downstream competitors.
Pricing Analysis
Certification level under JIS R 7606 and MIIT GB standards creates the primary spread between premium T800-grade prepreg and standard-modulus alternatives. Three-tier pricing structure across aerospace-certified, industrial-grade, and experimental fiber tiers reflects qualification timeline differentials. Cost compression in standard-modulus segments is intensifying because Chinese domestic producers are accelerating T800-grade qualification cycles. Defense contractors in India exhibit highest price sensitivity due to DGFT import licensing constraints, while Japanese tier-one suppliers show lowest sensitivity given captive precursor supply.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard for tier-two fabricators sourcing from Japanese precursor producers, straining working capital across Southeast Asian MRO channels. Supply concentrates in Japan, China, and South Korea, with PAN precursor production anchored in Chubu and the Yangtze River Delta. Raw material flows draw from acrylonitrile feedstocks, epoxy resin systems, and release film consumables. Single-source vulnerability around Toray's precursor dominance poses structural risk. Distribution runs through qualified prepreg distributors and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific aerospace composites market sits in a cyclical recovery phase driven by narrowbody fleet expansion across Southeast Asian carriers. Procurement cycles are compressing as COMAC production ramps and defense programs accelerate.
For Market Incumbents: Insulate precursor supply security through backward integration into PAN production or locked long-term offtake agreements with Chubu-region suppliers. Accelerate automated fiber placement capacity in Nagoya and Shanghai clusters to defend against Korean Air and SIA Engineering retrofit investments. Certification investment in multi-authority JIS-GB-FAA alignment represents the critical lever against repair station fragmentation.
For New Entrants and Emerging Players: India's captive defense demand under DGFT licensing constraints offers the most penetrable white-space for domestic autoclave capacity. UAV prototyping outside formal certification frameworks in Bangalore and Hyderabad presents rapid iteration entry points. Thermoplastic composite weldable structures for regional jets provide a differentiated go-to-market angle against entrenched thermoset incumbents.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors mid-scale fabricators with qualified resin systems and regional regulatory alignment. Long-term viability over a five-to-ten-year window rests on positioning ahead of out-of-autoclave technology displacement. Acquisition targets should display backward integration into precursor or prepreg stages. The signal to watch is MIIT qualification timeline compression for domestic T800-grade material as an inflection indicator for import substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray's vertical chain anchors supply security for COMAC narrowbody programs against concentration risk. |
| Automated Fiber Placement Capacity Expansion | Korean Air and SIA Engineering gantries compress layup labor content for A350 and 787 wing skins. |
| Multi-Authority Certification Alignment | JIS-GB-FAA repair procedure harmonization collapses parallel technician training burdens for MRO stations. |
| Thermoplastic Composite Weldable Structures | PEEK and PPS matrix systems eliminate mechanical fastening in next-generation regional jet platforms. |
| Domestic Autoclave Capacity Buildout | India's DGFT constraints create captive demand for HAL and DRDO program serving through local fabricators. |
Study Parameters
The analysis maps carbon fiber grades, prepreg technologies, and fabrication processes, each validated through procurement directors at tier-one airframe integrators, composite engineering leads at MRO facilities, regulatory affairs specialists at national aviation authorities, and precursor supply managers at chemical conglomerates. Primary fieldwork combined structured interviews with secondary validation against MIIT certification databases, JCAB airworthiness filings, DGFT import licensing records, and COMAC supplier qualification documents. Bottom-up segment sizing triangulates against top-down fleet expansion forecasts from regional airline procurement disclosures.
Assumptions held fixed include current JIS R 7606 and MIIT GB certification timelines, existing precursor supply concentration in Chubu, and continued narrowbody fleet preference over widebody orders across Southeast Asian carriers. Variables tested include out-of-autoclave curing adoption rates, thermoplastic composite qualification velocity, and DGFT licensing relaxation scenarios. The analytical framework models product type, application, technology, and end user dimensions across the projection horizon. CAGRs derive from segment-level volume build-ups adjusted for qualification cycle compression. Industry-specific inputs include autoclave capacity utilization rates and automated fiber placement installation trajectories at Korean Air and SIA Engineering facilities.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale Chinese fabricators or sudden JCAB-CAAC reciprocity agreements would shift outcomes. Macroeconomic deviation in oil-indexed acrylonitrile pricing, regulatory harmonization acceleration, or breakthrough thermoplastic primary structure certification would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market