
 Ablative Coatings Market | 2026-2036
Ablative Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Ablative Coatings Market Insights
EU REACH restrictions on hazardous substance emissions is restructuring procurement criteria across European aerospace and defense supply chains. Sherwin-Williams leverages its industrial coatings infrastructure to serve thermal protection needs in power generation and marine segments. Lockheed Martin anchors demand through sustained R&D contracts for hypersonic vehicle thermal protection systems. PPG Industries competes on formulation flexibility across polymer matrix and ceramic matrix platforms for diverse end-use specifications.
Ablative coatings are sacrificial thermal protection materials that char, ablate, or decompose endothermically to insulate substrates from extreme heat fluxes, typically formulated with phenolic resins, silicone elastomers, or ceramic fillers and applied in thicknesses ranging from millimeters to centimeters depending on mission duration and peak heating rates. Their primary purpose is to protect structural components during atmospheric entry, rocket motor operation, or exhaust impingement scenarios where temperatures exceed conventional material limits. Epoxy and silicone product types dominate current volume due to established supply chains and processing familiarity, though fluoropolymer formulations command premium positioning in electronics and precision aerospace applications where outgassing control is critical. Ceramic matrix technology leads in defense and space applications requiring the highest heat flux tolerance, while polymer matrix systems capture broader commercial adoption through lower curing complexity and substrate compatibility.
EPA oversight of volatile organic compound emissions shapes formulation choices in the United States, while REACH compliance in Europe mandates substitution of certain crosslinkers and solvents in ablative coating production. China's GB standards and MIIT directives on aerospace material localization are redirecting procurement toward domestic-qualified suppliers. Stakeholders must monitor evolving defense procurement rules and space launch licensing frameworks across multiple jurisdictions to anticipate qualification requirements and supply chain access conditions.
Market Dynamics
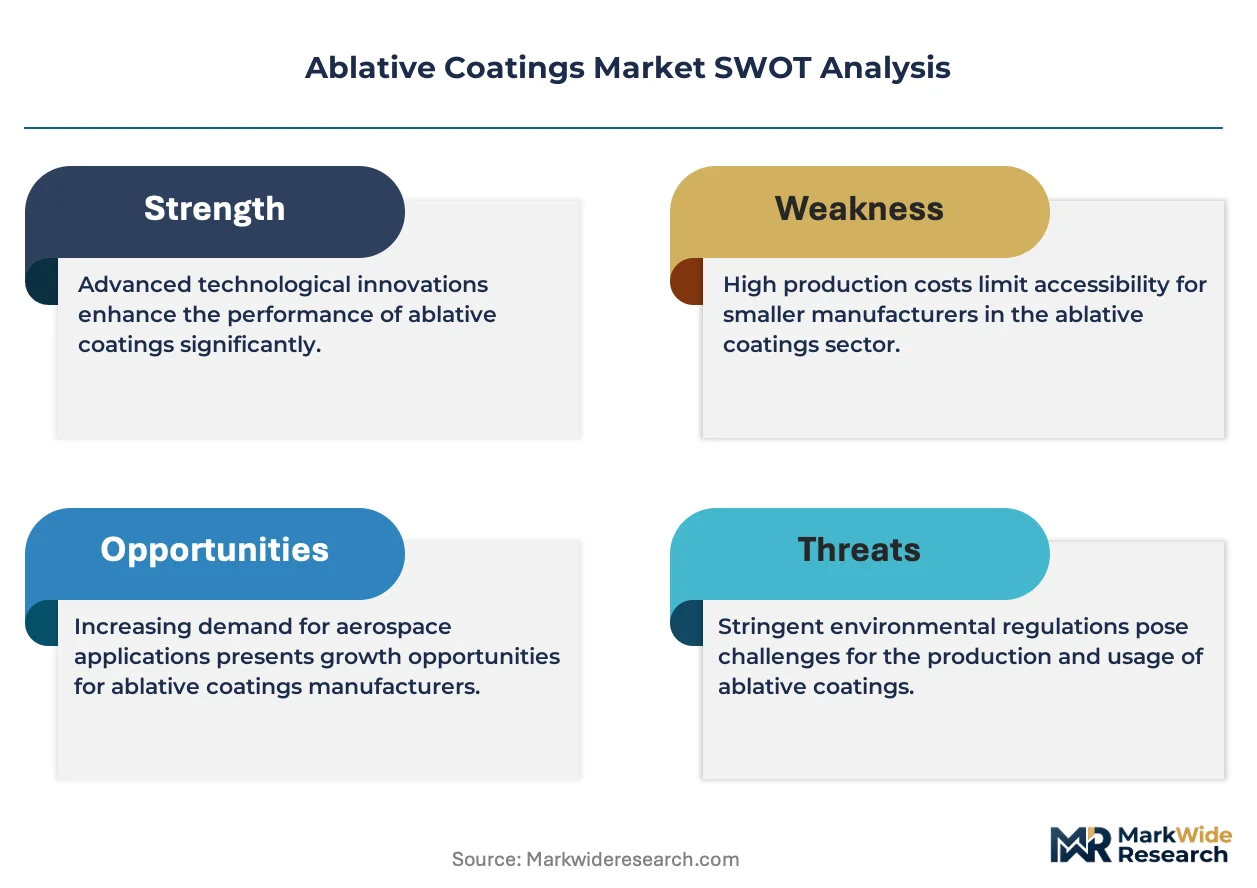
Defense procurement cycles for hypersonic thermal protection systems are compressing qualification timelines, forcing formulators to accelerate ceramic matrix validation while maintaining REACH and EPA emission compliance.
Growth Catalysts
- Hypersonic platform R&D:Sustained Department of Defense contracts in the United States are pulling advanced phenolic-silicone formulations through multi-year qualification pipelines for re-entry vehicle heat shields.
- REACH solvent restrictions:ECHA mandates on volatile organic compound reduction are accelerating waterborne polymer matrix adoption across European aerospace supply chains.
- Space launch frequency:Rising orbital deployment rates in China under MIIT localization directives are expanding domestic qualified-supplier procurement for rocket motor insulation.
Market Restraints
- Raw material concentration:High-purity ceramic fiber supply concentrates in a limited number of qualified producers, creating input vulnerability for ablative composite manufacturers.
- Qualification cost barriers:Multi-year arc-jet and plasma wind tunnel testing requirements for defense applications lock out smaller formulators lacking capital reserves.
- Substitution pressure:Reusable ceramic tile systems for orbital vehicles threaten single-use ablative coatings in medium-heat-flux applications.
Strategic Opportunities
- Power generation expansion:Gas turbine hot-section protection in combined-cycle plants represents an underpenetrated commercial channel for silicone-based ablative formulations.
- EU Green Deal alignment:Carbon border adjustment mechanisms and sustainable product mandates are creating first-mover advantage for bio-based phenolic resin developers.
- Additive manufacturing convergence:Integration of direct energy deposition with ablative material deposition is enabling complex geometry thermal protection for unmanned aerial systems.
Industry Challenges
- Specialized workforce scarcity:Plasma spray operators and high-temperature materials engineers with defense clearance are in critically short supply across the United States and Germany.
- Cross-jurisdictional certification:Divergent FAA, EASA, and CAAC airworthiness standards for commercial spaceflight thermal protection are fragmentating qualification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ablative Coatings Market |
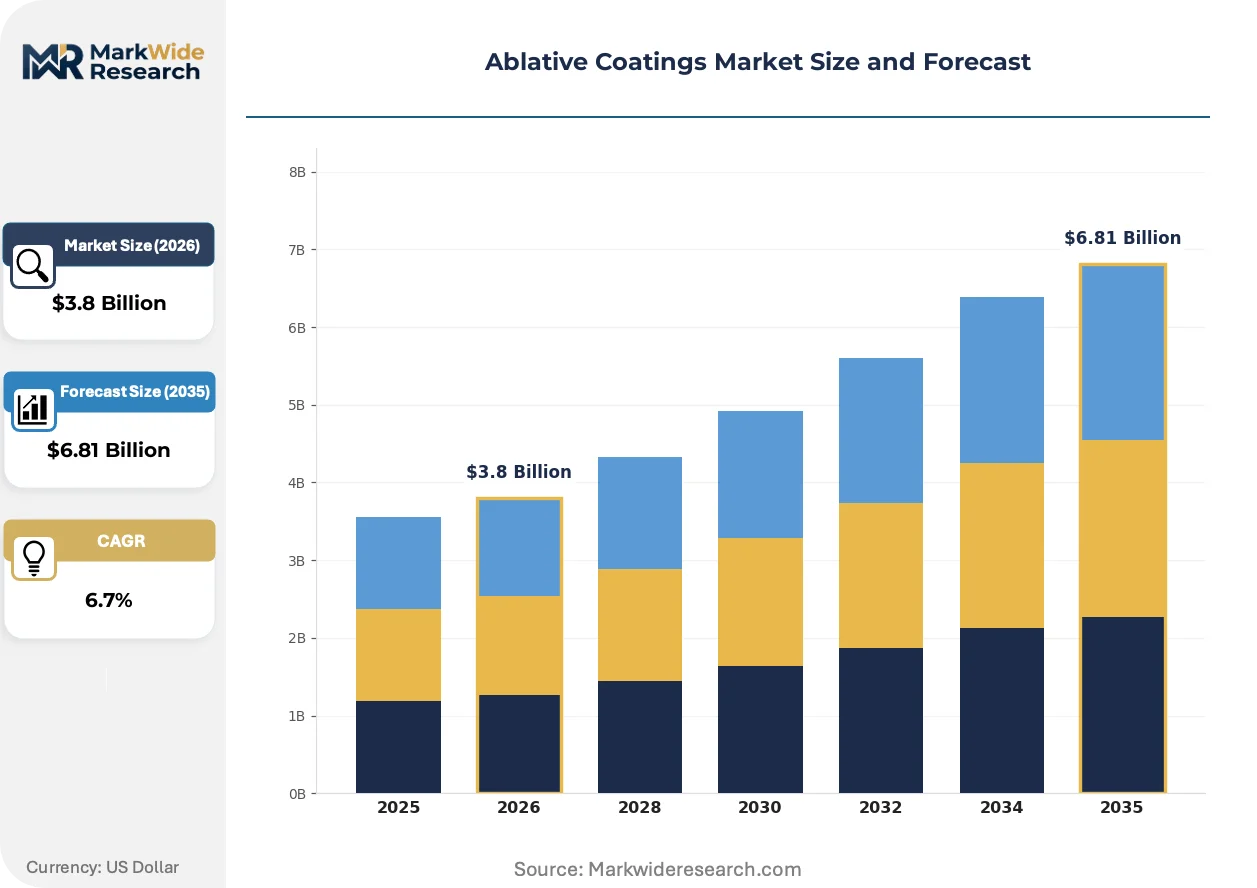
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyurethane, Acrylic, Fluoropolymer Application: Aerospace, Defense, Marine, Power Generation, Electronics Technology: Ceramic Matrix, Polymer Matrix, Carbon Composite, Metal Matrix End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Sherwin-Williams, Lockheed Martin, Dow, Akzo Nobel, PPG Industries, Jotun, Hempel, Sika, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ablative Coatings Market Trends and Innovations
Ceramic matrix composite processing is absorbing capital and talent flows as defense primes demand higher heat-flux tolerance, while regulatory pressure on emissions is rewriting formulation chemistry across multiple jurisdictions.
Carbon-carbon ablative systems with silicon carbide conversion coatings are absorbing the most demanding re-entry thermal loads. NASA and defense agency adopters are pushing these materials through accelerated qualification for next-generation hypersonic glide vehicles. The technology is absorbing market share from legacy carbon-phenolic systems in peak heating environments above 3000 degrees Fahrenheit.
EPA volatile organic compound rules under the Clean Air Act are forcing solvent-based phenolic formulators toward waterborne curing systems. Industrial consequence includes extended drying cycles and modified substrate adhesion protocols. Aerospace OEMs in California and Texas are responding by consolidating procurement with formulators possessing compliant infrastructure.
Buyer concentration among prime defense contractors is compressing supplier negotiation leverage. Long-term thermal protection system contracts with fixed-price escalation clauses are displacing spot purchasing for strategic platforms. This pattern is most visible in United States Department of Defense hypersonic programs where Lockheed Martin and Northrop Grumman anchor supply chain decisions.
Ablative Coatings Market Segmentation
Ablative coating procurement diverges sharply across thermal load specifications and regulatory environments. Formulators must align chemistry portfolios with distinct qualification pathways that separate defense-grade ceramic systems from commercial polymer alternatives.
Product Type:
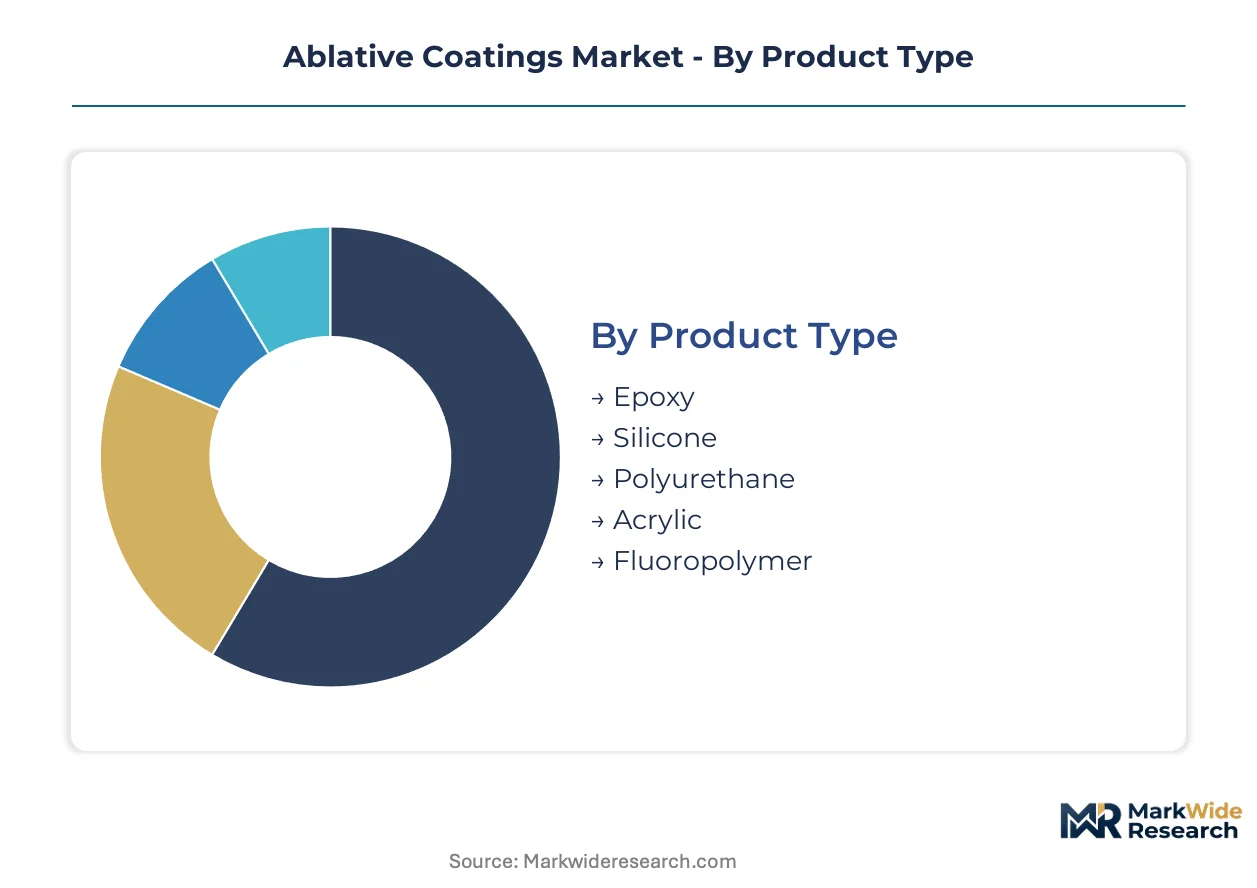
Epoxy and silicone formulations anchor current procurement volumes through established aerospace supply chains, while polyurethane and fluoropolymer grades serve specialized thermal protection niches with distinct processing requirements.
- Epoxy:Phenolic-modified epoxy systems cure at moderate temperatures and bond aggressively to metallic substrates. Demand concentrates in rocket motor insulation for United States Department of Defense programs where multi-year qualification contracts favor incumbent chemistries.
- Silicone:Elastomeric silicone matrices tolerate extended thermal cycling without catastrophic failure. European aerospace OEMs under ECHA solvent restrictions are pulling waterborne silicone formulations through accelerated validation for satellite launch vehicle fairings.
- Polyurethane:Flexible urethane backbones suit marine exhaust stack protection where moderate heat flux combines with salt spray exposure.
- Acrylic:Lower-cost acrylic binders serve electronics enclosure applications with modest thermal protection requirements and tight outgassing limits.
- Fluoropolymer:PTFE and FEP formulations command premium positioning in precision aerospace electronics where volatile emission control is mission-critical.
Mature deployment sits with epoxy. Newer deployment is concentrated in silicone as REACH compliance restructures European formulation preferences.
Application:
Defense and aerospace procurement absorbs the highest-performance formulations, while power generation and marine segments present volume expansion opportunities with less stringent qualification barriers.
- Aerospace:Re-entry vehicle heat shields and launch vehicle thermal protection demand ceramic-polymer hybrids capable of withstanding peak heating above 3000°F. NASA and defense agency R&D contracts are accelerating carbon-carbon system adoption for next-generation hypersonic glide vehicles.
- Defense:Hypersonic platform thermal protection systems require multi-year arc-jet validation and security-cleared manufacturing facilities. The United States Department of Defense is compressing supplier qualification timelines while maintaining fixed-price contract structures.
- Marine:Gas turbine exhaust and stack insulation in commercial shipping operates under IMO emission regulations that favor silicone-based ablative formulations with extended service intervals.
- Power Generation:Combined-cycle gas turbine hot-section protection represents an underpenetrated channel where ceramic matrix spray coatings can extend component life between overhauls.
- Electronics:Satellite and avionics thermal management requires low-outgassing fluoropolymer coatings that maintain dielectric properties across orbital temperature swings.
Defense applications concentrate the steepest expansion trajectory. Power generation offers the most accessible entry path for new formulators lacking security clearances.
Technology:
Matrix selection determines heat flux tolerance, manufacturing complexity, and qualification cost—creating tiered competitive positions that separate defense primes from commercial coating suppliers.
- Ceramic Matrix:Oxide and carbide fiber reinforcements in silica or alumina matrices tolerate the most extreme re-entry environments. Carbon-carbon systems with silicon carbide conversion coatings are displacing legacy carbon-phenolic in peak heating applications above 3000°F.
- Polymer Matrix:Phenolic, silicone, and epoxy resin systems dominate commercial procurement through lower curing temperatures and substrate compatibility. Waterborne polymer formulations are gaining share in European aerospace as ECHA volatile organic compound mandates tighten.
- Carbon Composite:3D-woven carbon preforms with ablative matrices enable complex geometry thermal protection for unmanned aerial system leading edges.
- Metal Matrix:Aluminum or titanium matrices with ceramic particulate reinforcement serve specialized exhaust impingement scenarios where structural load-bearing combines with thermal protection.
Volume leadership belongs to polymer matrix. Ceramic matrix commands the premium tier as hypersonic platform R&D accelerates.
End User:
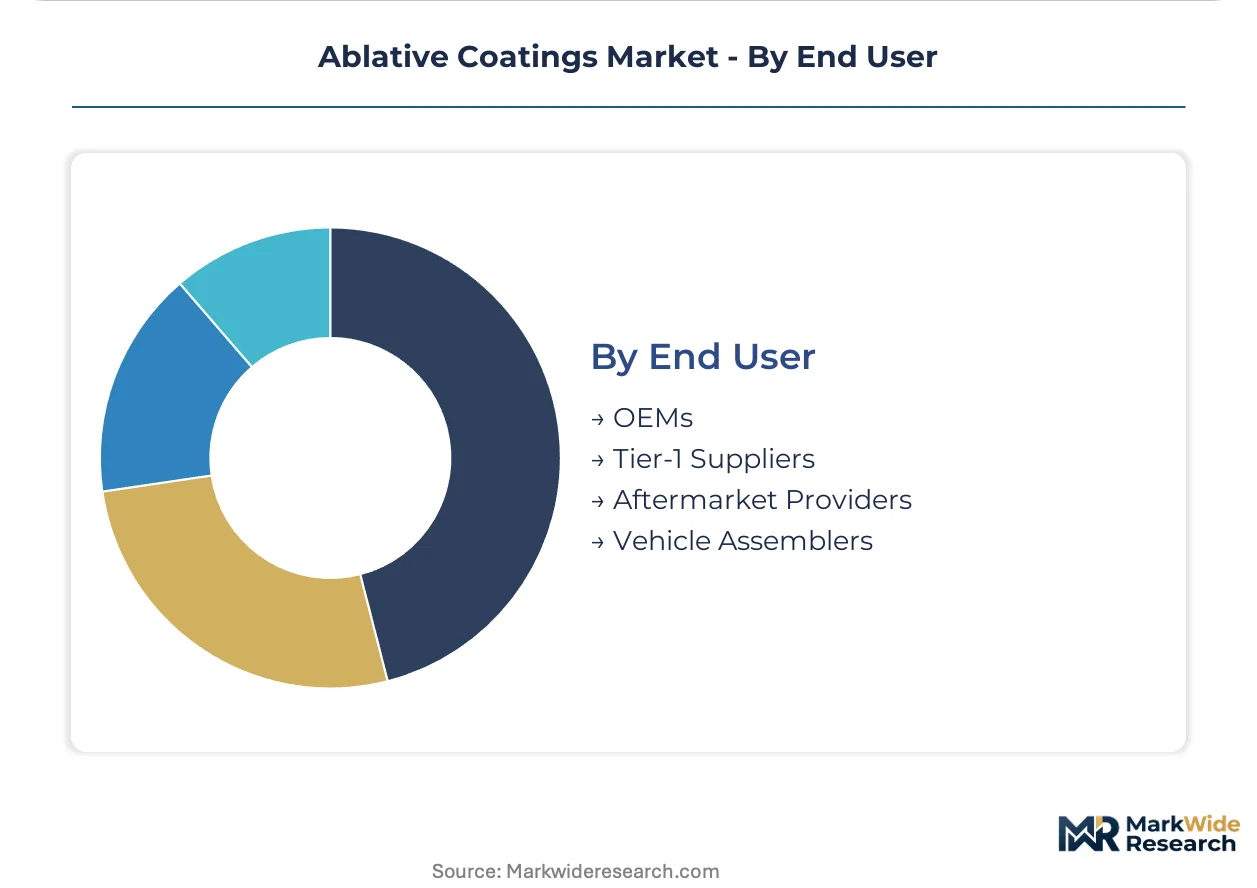
Procurement authority concentrates among prime contractors and vehicle assemblers, compressing supplier negotiation leverage and favoring formulators with scale and security infrastructure.
- OEMs:Lockheed Martin and Northrop Grumman anchor United States thermal protection system procurement through multi-year development contracts with fixed-price escalation clauses.
- Tier-1 Suppliers:Specialized coating applicators with plasma spray and arc-jet testing capabilities serve as qualified intermediaries between formulators and prime contractors.
- Aftermarket Providers:Maintenance, repair, and overhaul operations for legacy defense platforms and commercial power generation turbines create recurring demand for compatible ablative materials.
- Vehicle Assemblers:SpaceX and Blue Origin vertical integration strategies are absorbing some thermal protection functions in-house while outsourcing specialized ceramic matrix components.
Contract concentration sits with OEMs. Aftermarket channels offer the most stable demand visibility for independent formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Huntsville, Alabama anchors North American thermal protection system development through concentrated NASA and Department of Defense R&D infrastructure. Defense procurement cycles and space launch licensing frameworks vary substantially across national jurisdictions.
United States
Department of Defense hypersonic platform contracts and NASA re-entry vehicle programs absorb the highest-performance ceramic matrix formulations. EPA Clean Air Act oversight of volatile organic compound emissions shapes formulation choices in California and Texas manufacturing clusters. The Huntsville-Decatur corridor concentrates arc-jet testing facilities and security-cleared coating applicators serving prime contractors.
Germany
ECHA REACH mandates on hazardous substance substitution are accelerating waterborne polymer matrix adoption across aerospace supply chains. The country's national aerospace regulator enforces strict qualification protocols for defense-grade thermal protection systems. The Munich-Stuttgart industrial corridor hosts specialized formulators serving European Space Agency launch vehicle programs.
China
MIIT directives on aerospace material localization are redirecting procurement toward domestic-qualified suppliers for rocket motor insulation. GB standards on industrial emissions apply to coating manufacturing facilities in coastal provinces. The Beijing-Tianjin-Hebei cluster concentrates state-owned enterprise research institutes developing carbon-carbon ablative systems.
France
CNES space agency thermal protection requirements and DGA defense procurement sustain demand for ceramic-polymer hybrid formulations. The national pharmaceutical and environmental regulator enforces REACH-aligned substance restrictions on aerospace chemical suppliers. The Toulouse aerospace cluster hosts qualified applicators serving Ariane launch vehicle programs.
Japan
METI industrial technology roadmaps prioritize domestic carbon fiber reinforcement capabilities for thermal protection composites. JIS standards govern materials qualification for defense and civilian aerospace applications. The Nagoya-Tokyo industrial corridor concentrates precision coating applicators serving satellite and launch vehicle manufacturers.
Ablative Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification infrastructure and security clearance tiers. The vendor base stratifies between defense-cleared ceramic matrix specialists and commercial polymer formulators serving industrial segments. Three archetypes dominate: integrated aerospace primes with captive coating capabilities, independent specialty chemical formulators with plasma spray infrastructure, and diversified industrial coatings suppliers leveraging existing resin technology platforms. Competitive moves concentrate on strategic partnerships with defense primes and geographic expansion of arc-jet testing capacity.
Within the diversified industrial coatings tier, Sherwin-Williams and PPG Industries occupy positions exemplifying scale-driven formulation flexibility across polymer matrix platforms. Among defense-anchored specialists, Lockheed Martin represents the prime contractor archetype with sustained R&D contract pipelines for hypersonic thermal protection systems. These three companies illustrate the structural divide between commercial coatings infrastructure and defense-cleared specialty operations.
| Leading Market Players |
|---|
| Sherwin-Williams |
| Lockheed Martin |
| Dow |
| Akzo Nobel |
| PPG Industries |
| Jotun |
| Hempel |
| Sika |
| Axalta Coating Systems |
| Others |
Pricing and Supply Chain Analysis
High-purity ceramic fiber costs cascade through three distinct pricing tiers as raw material scarcity concentrates upstream bargaining power among qualified producers in the United States, Japan, and Germany. Defense primes absorbing these inputs for hypersonic thermal protection systems pass cost premiums downstream through fixed-price escalation clauses, while commercial polymer matrix formulators in Europe absorb REACH compliance conversion expenses without equivalent pricing recovery mechanisms.
Pricing Analysis
Arc-jet test throughput anchors value-based pricing for ceramic matrix systems, with formulators commanding premiums proportional to validated heat-flux tolerance documentation. Three-tier pricing structure across defense-grade, aerospace-commercial, and industrial-application levels separates qualification-intensive carbon-carbon systems from commodity silicone formulations. Pricing pressure stems from compressed hypersonic program timelines forcing accelerated validation without proportional contract adjustment. Tier-1 suppliers with security clearance infrastructure exhibit lowest price sensitivity; aftermarket maintenance providers for legacy power generation turbines demonstrate highest sensitivity to formulation cost fluctuations.
Supply Chain Analysis
Plasma spray operator scarcity across Huntsville, Alabama and Munich-Stuttgart corridor manufacturing clusters constrains qualified applicator capacity for defense-grade ceramic deposition. Supply concentrates in the United States, China, and Germany for carbon fiber reinforcement, phenolic resin precursors, and silicon carbide conversion coating chemistries. The chain draws from single-source vulnerability in high-temperature ceramic fiber qualified to defense specifications, with tariff exposure on Chinese-origin carbon preforms intensifying under current trade frameworks. Distribution runs through prime contractor-directed procurement with security-cleared Tier-1 applicators serving as mandatory intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH solvent restrictions and EPA Clean Air Act volatile organic compound rules construct regulatory moats favoring formulators with compliant infrastructure investments already amortized.
For Market Incumbents: Extend ceramic matrix validation capacity through arc-jet facility expansion in Huntsville-Decatur corridor to capture compressing hypersonic qualification timelines. Extend backward integration into phenolic resin precursor supply to defend margin position against raw material concentration among limited qualified producers. Lockheed Martin and Northrop Grumman contract consolidation threatens supplier negotiation leverage; long-term fixed-price agreements with escalation clauses provide defensive anchoring.
For New Entrants and Emerging Players: Launch via power generation aftermarket channels serving combined-cycle gas turbine hot-section protection, the most penetrable segment lacking security clearance barriers. Launch waterborne silicone formulations targeting European aerospace OEMs under ECHA mandates as accelerated validation pathway. Marine exhaust stack insulation under IMO emission regulations offers secondary white-space with moderate qualification requirements and salt spray exposure differentiation.
For Investors and Strategic Acquirers: SpaceX and Blue Origin in-house thermal protection capability announcements are the leading indicator that vertical integration pressure will reshape supplier economics for independent formulators. Five-to-ten-year viability favors acquisition targets possessing plasma spray infrastructure plus existing defense security clearance, not pure formulation chemistry plays. Watch for MIIT localization directive enforcement intensity in China as signal of domestic supplier displacement risk for Western incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Arc-Jet Testing Capacity Expansion | Huntsville facility investments capture compressing hypersonic qualification timelines from Department of Defense primes. |
| Waterborne Polymer Transition | REACH-compliant formulation platforms secure European Space Agency launch vehicle procurement access. |
| Carbon Fiber Precursor Backward Integration | Phenolic resin captive supply mitigates raw material concentration vulnerability among qualified producers. |
| Power Generation Channel Entry | Combined-cycle turbine hot-section protection offers aftermarket recurring revenue without security clearance barriers. |
| Additive Manufacturing Convergence | Direct energy deposition integration enables complex geometry thermal protection for unmanned aerial system leading edges. |
Research Methodology
Independent corroboration across thermal protection system procurement officers at prime defense contractors, plasma spray facility operators in Huntsville and Munich-Stuttgart corridors, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with ceramic matrix composite R&D directors, phenolic resin procurement leads at downstream OEMs, and arc-jet testing facility managers combined with secondary validation from Department of Defense contract announcements, EPA Clean Air Act enforcement records, and MIIT aerospace material localization directives. Bottom-up segment sizing across product type, application, technology, and end user triangulates against top-down defense budget thermal protection line-item analysis.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include matrix technology tier, peak heat-flux specification band, regulatory compliance cluster, and security clearance requirement level. CAGRs derive from qualified supplier capacity expansion trajectories, defense procurement cycle phasing, and space launch frequency assumptions. Industry-specific forecast inputs incorporate arc-jet testing queue depth and REACH solvent restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for reusable ceramic tile systems would alter the outlook for single-use ablative coating demand. Forecasts reflect assumptions regarding defense budget continuity, ECHA enforcement intensity, and MIIT localization directive adherence. Material deviation in hypersonic platform R&D funding levels, REACH substance restriction scope expansion, or carbon fiber trade policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market