
 Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market | 2026-2036
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market Insights
Software-defined test automation is expanding the recurring revenue layer in this market, shifting equipment sales toward subscription-based data analytics and remote monitoring modules. Intertek Group leverages its global laboratory network to anchor certification workflows for additively manufactured pressure vessels. SGS competes through integrated digital reporting platforms that streamline compliance documentation for aerospace clients. TÜV SÜD specializes in European regulatory pathways, sustaining demand for its proof and burst test rig calibration services.
Additive manufactured pressure vessel proof and burst test rigs are mechanical systems designed to apply controlled hydrostatic or pneumatic pressure to 3D-printed containment structures until proof pressure or catastrophic failure, typically operating at test-to-burst ratios exceeding 2.5:1 with data acquisition rates above 1000 Hz for fracture characterization. These rigs serve the critical function of validating structural integrity before operational deployment in life-safety applications. Hydrostatic test rigs dominate current installations due to their established safety profile and compatibility with water-based media for laser powder bed fusion components. Aerospace component testing represents the fastest-growing application segment as directed energy deposition expands for titanium pressure vessel fabrication. Custom test rigs capture premium margin pools where end users require multi-axis loading combined with thermal cycling for subsea equipment assessment.
The US FAA mandates burst test documentation under its additive manufacturing qualification pathway, while NASA enforces proprietary standards for 3D-printed propellant tanks on crewed missions. ASTM International and ISO/ASTM 52900 frameworks shape international test protocol harmonization, though national regulators retain divergent pressure safety factors. The EU Pressure Equipment Directive and ASME Boiler and Pressure Vessel Code Section VIII create dual compliance burdens for rig manufacturers serving transatlantic clients. Stakeholders must monitor how emerging binder jetting standards from ASTM F42 reshape test fixture requirements for ferrous alloy vessels.
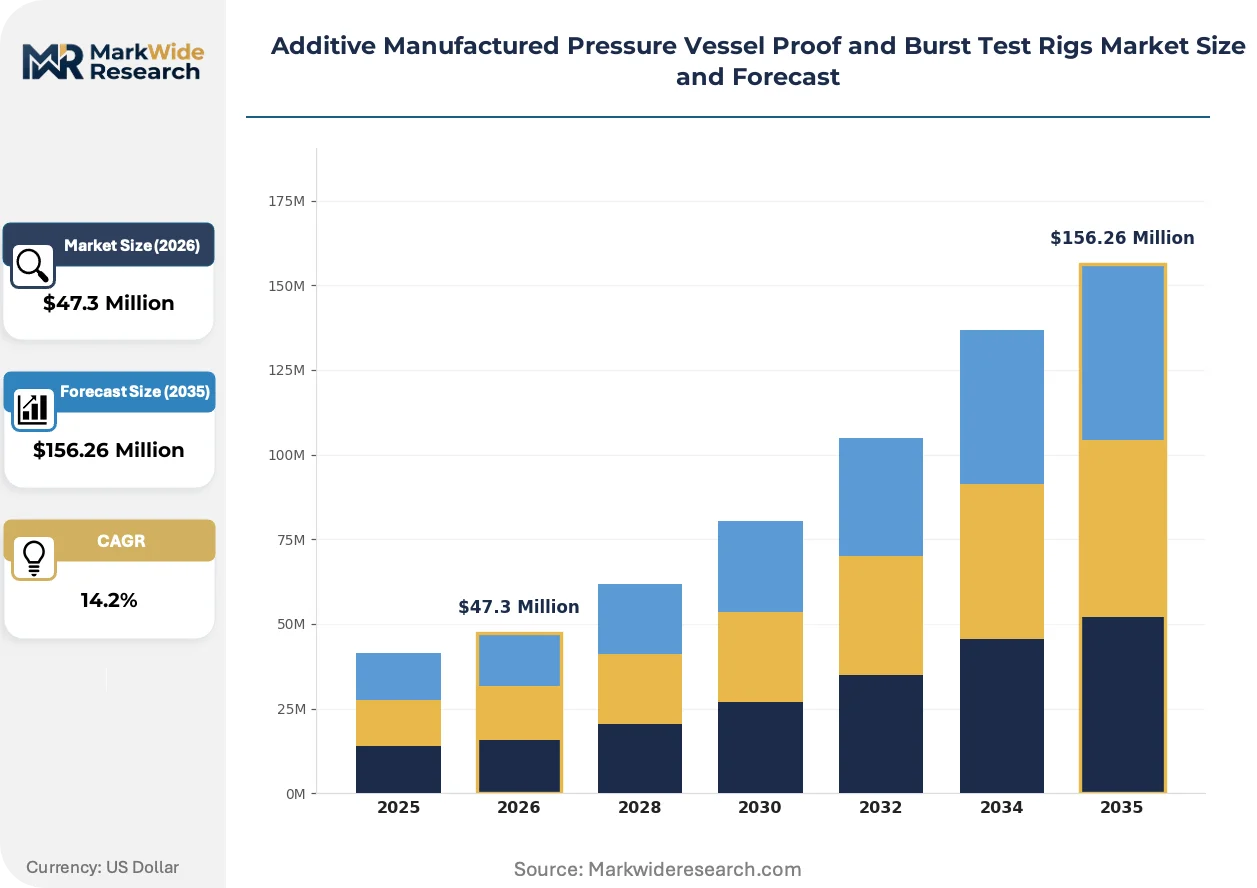
Market Dynamics
Software-defined test automation is compressing equipment refresh cycles as aerospace and oilfield buyers prioritize data acquisition bandwidth over mechanical durability in proof and burst test rig procurement decisions.
Growth Catalysts
- FAA Additive Manufacturing Qualification Pathway:Mandatory burst test documentation for 3D-printed pressure-bearing components creates captive demand for certified test infrastructure across US aerospace supply chains.
- Directed Energy Deposition:Titanium pressure vessel fabrication for crewed space missions is accelerating rig purchases for multi-axis hydrostatic validation with thermal cycling capabilities.
- Texas Cluster Concentration:Adjacent oilfield equipment manufacturers and space technology facilities in Houston and Austin generate localized testing infrastructure investment.
Market Restraints
- Dual Compliance Architecture:Simultaneous ASME Boiler and Pressure Vessel Code Section VIII and EU Pressure Equipment Directive certification requirements inflate engineering overhead for transatlantic rig manufacturers.
- High-Frequency Data Acquisition Component Scarcity:Specialized pressure transducers and strain gauge systems capable of 1000 Hz sampling face concentrated supply from German and Japanese sensor specialists.
- Test Media Compatibility Constraints:Laser powder bed fusion components require water-based hydrostatic media, limiting pneumatic test rig applicability in certain aerospace validation workflows.
Strategic Opportunities
- Subsea Equipment Assessment:Custom multi-axis loading rigs with combined thermal cycling represent premium margin pools as deepwater oilfield operators adopt additively manufactured wellhead components.
- Subscription Analytics Modules:Remote monitoring and predictive fracture characterization software layers create recurring revenue streams beyond one-time equipment sales.
- ASTM F42 Binder Jetting Standards:Emerging ferrous alloy vessel protocols will reshape test fixture requirements, opening first-mover advantage for rig manufacturers with adaptable clamping systems.
Industry Challenges
- Calibration Specialist Shortage:Technicians capable of certifying burst test rigs to ISO/ASTM 52900 protocols remain concentrated in legacy aerospace hubs, constraining field service expansion.
- Legacy System Integration Friction:Digital reporting platforms from third-party certification bodies require custom API development to interface with existing plant SCADA infrastructure at oilfield testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market |
| Market Size in 2026 | $47.3 Million |
| Market Size in 2035 | $156.26 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrostatic Test Rigs, Pneumatic Test Rigs, Combined Test Rigs, Custom Test Rigs Technology: 3D Printing, Laser Powder Bed Fusion, Electron Beam Melting, Binder Jetting, Directed Energy Deposition Application: Pipeline Integrity Testing, Aerospace Component Testing, Pressure Container Validation, Fire Suppression Systems, Subsea Equipment Assessment End User: Oilfield Equipment Manufacturers, Aerospace Engineers, Fire Protection Specialists, Subsea Installers, Scientific Laboratories |
| Companies Covered | Intertek Group, SGS, Element Materials Technology, TÜV SÜD, DEKRA, Bureau Veritas, Applus+, UL Solutions, Pressure Systems International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market Trends and Innovations
Test rig architecture is pivoting from standalone mechanical systems toward integrated data platforms, with fracture characterization algorithms and cloud-based compliance documentation becoming primary competitive differentiators.
Digital twin simulation is converging with physical burst testing protocols as aerospace primes validate additively manufactured propellant tanks. NASA's crewed mission standards now require predictive failure modeling alongside empirical hydrostatic validation. This convergence is compressing prototype iteration cycles from months to weeks for titanium pressure vessel development programs.
The EU Pressure Equipment Directive's 2024 guidance update mandates traceable digital test records for all 3D-printed pressure-bearing components entering European aerospace and energy supply chains. Industrial consequence includes mandatory blockchain-anchored documentation for burst test certificates. German oilfield equipment exporters face the steepest compliance burden as they retest legacy additive components under the new protocol.
Certification-driven procurement preferences now dominate rig selection criteria as buyers prioritize pre-integrated compliance workflows over standalone mechanical specifications. Third-party laboratory networks are displacing in-house testing departments at mid-tier aerospace suppliers. This shift concentrates most visible in Texas, where Intertek and SGS have expanded additive manufacturing validation capacity to capture outsourced burst testing demand from Space Coast suppliers.
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market Segmentation
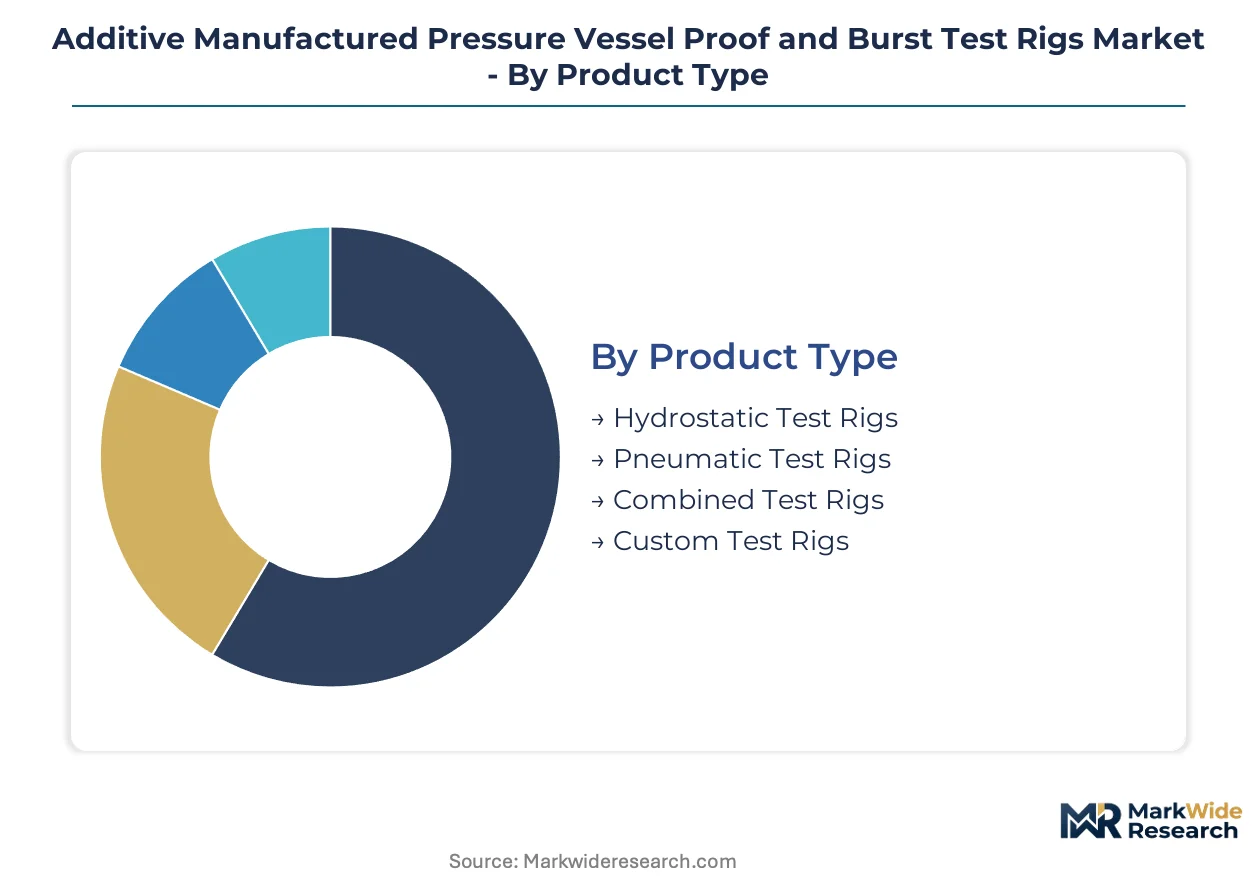
Test rig segmentation reflects divergent certification requirements across additive manufacturing processes. Each dimension—product architecture, build technology, application context, and buyer type—carries distinct procurement logic and margin structures.
Product Type:
Customization versus standardization tension runs deepest here, with off-the-shelf hydrostatic systems competing against engineered-to-order multi-axis configurations.
- Hydrostatic Test Rigs:Water-based pressure application systems dominate current installations due to established safety profiles and compatibility with laser powder bed fusion components. Oilfield equipment manufacturers in Texas anchor demand as they validate wellhead connectors and blowout preventer housings.
- Custom Test Rigs:Engineered configurations incorporating multi-axis loading with thermal cycling command premium pricing for subsea equipment assessment. Deepwater operators in the Gulf of Mexico drive specification complexity as they qualify additively manufactured wellhead components for high-pressure, high-temperature reservoirs.
- Pneumatic Test Rigs:Gas-based systems serve specialized aerospace validation where rapid decompression simulation matters.
- Combined Test Rigs:Hybrid hydrostatic-pneumatic architectures address dual-protocol compliance for transatlantic equipment exporters.
Most installed capacity flows through hydrostatic test rigs. Expansion is steepest in custom test rigs.
Technology:
Build method determines test fixture geometry, pressure safety factors, and fracture characterization protocols.
- Laser Powder Bed Fusion:Powder-bed systems producing near-net-shape titanium and aluminum vessels require water-compatible hydrostatic validation with 1000 Hz data acquisition for pore-initiated fracture tracking. NASA crewed mission standards mandate this technology for propellant tank fabrication.
- Directed Energy Deposition:Wire-fed and powder-fed systems enable large-format pressure vessel fabrication with variable wall thickness, demanding multi-zone pressure testing with real-time strain mapping. Aerospace engineers in Texas and California scale purchases for titanium tank programs.
- 3D Printing:General additive manufacturing category spanning multiple feedstock approaches.
- Electron Beam Melting:Vacuum-based powder-bed systems for reactive alloys require specialized test media handling.
- Binder Jetting:Emerging ferrous alloy vessel protocols from ASTM F42 reshape fixture requirements for green-state infiltration components.
Current validation volume concentrates in laser powder bed fusion. Steepest capacity additions track directed energy deposition.
Application:
Safety-criticality gradients separate commodity pressure testing from mission-assurance validation workflows.
- Aerospace Component Testing:Crewed space missions and commercial aviation demand the most stringent documentation, with FAA additive manufacturing qualification pathway mandating burst test records for all 3D-printed pressure-bearing structures. Directed energy deposition of titanium propellant tanks drives fastest rig procurement.
- Subsea Equipment Assessment:Deepwater oilfield operators require combined pressure-thermal-mechanical validation for wellhead components subjected to 15,000 psi and sub-zero temperatures. Custom multi-axis rigs with thermal cycling capture premium margin pools.
- Pipeline Integrity Testing:Midstream oil and gas infrastructure validation for corrosion-resistant additively manufactured fittings.
- Pressure Container Validation:General industrial pressure vessel certification across chemical and energy applications.
- Fire Suppression Systems:Specialized testing for additive manufactured extinguisher vessels and distribution manifolds.
Pipeline integrity testing holds the largest installed base. Aerospace component testing climbs the fastest.
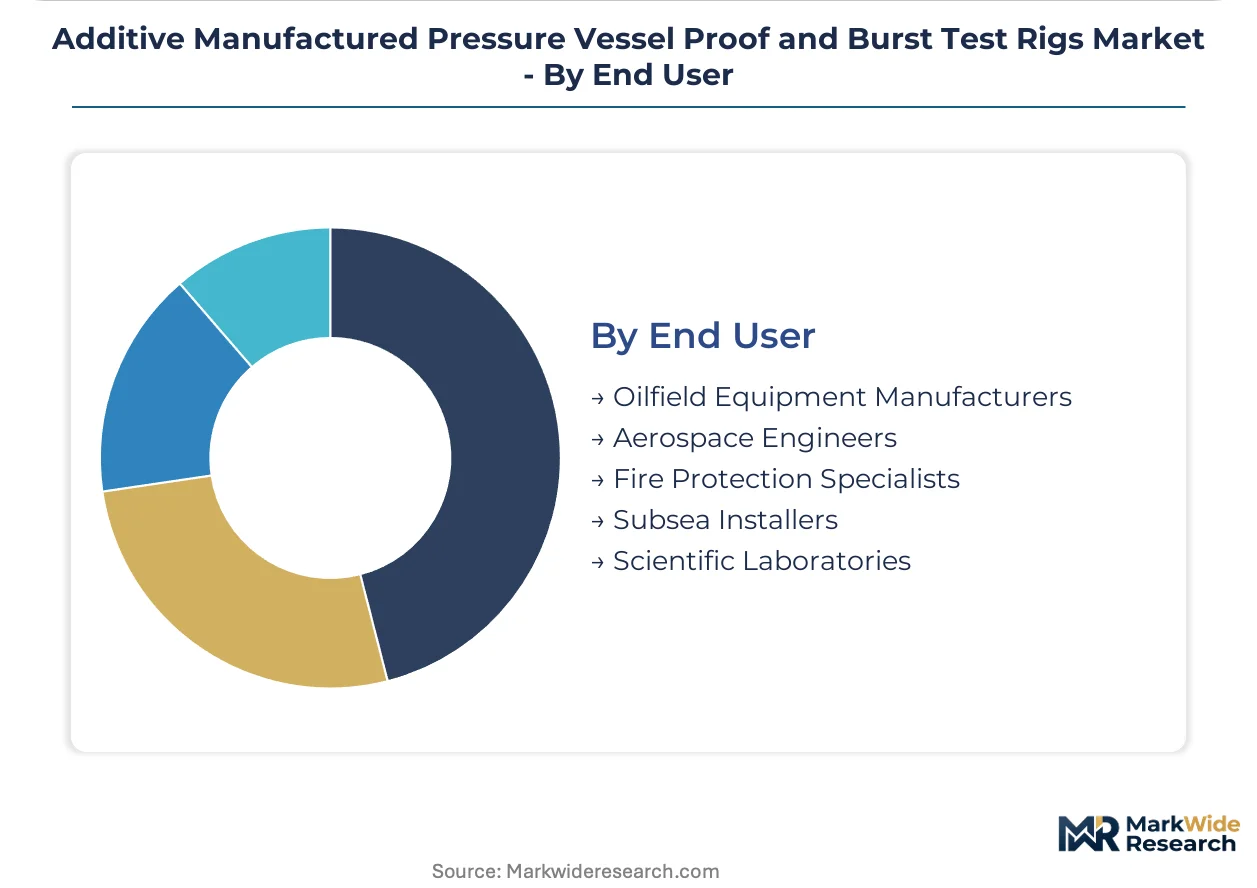
End User:
Buyer sophistication and in-house versus outsourced testing preferences segment procurement behavior sharply.
- Aerospace Engineers:Prime contractors and tier-one suppliers prioritize integrated data platforms with predictive fracture characterization algorithms. NASA crewed mission standards force investment in certified burst and proof test infrastructure with digital twin convergence.
- Oilfield Equipment Manufacturers:Houston and Austin clusters generate localized testing infrastructure investment, with adjacent space technology facilities creating shared supplier ecosystems. These buyers favor hydrostatic systems for laser powder bed fusion compatibility.
- Subsea Installers:Deepwater contractors requiring field-deployable validation for repair components and replacement wellhead elements.
- Fire Protection Specialists:Niche buyers focused on extinguisher vessel and suppression system validation.
- Scientific Laboratories:Research institutions pursuing fundamental fracture mechanics of additively manufactured alloys.
Oilfield equipment manufacturers represent the largest installed base. Aerospace engineers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States and Germany diverge sharply in test rig procurement intensity, with American aerospace primes driving volume through NASA crewed mission standards while German exporters absorb compliance costs under EU Pressure Equipment Directive updates.
United States
FAA additive manufacturing qualification pathway mandates burst test documentation for 3D-printed pressure-bearing components, forcing aerospace supply chains into certified infrastructure investment. NASA proprietary standards for propellant tanks on crewed missions tighten validation protocols further. Houston and Austin clusters concentrate demand, with adjacent oilfield equipment manufacturers and space technology facilities sharing supplier ecosystems for hydrostatic test systems.
Germany
Industrial machinery exporters face dual compliance architecture spanning ASME Boiler and Pressure Vessel Code Section VIII and EU Pressure Equipment Directive requirements. TÜV SÜD calibration services anchor regional certification workflows. Bavaria and Baden-Württemberg host concentrated rig manufacturing capacity, with sensor specialists in these states supplying high-frequency data acquisition components facing concentrated demand from domestic and transatlantic clients.
China
Domestic laser powder bed fusion capacity expansion for aerospace and energy applications generates localized test rig demand. GB standards and MIIT industrial guidance shape validation protocol development for additively manufactured pressure vessels. Yangtze River Delta and Pearl River Delta clusters concentrate both production and testing infrastructure, with state-directed investment prioritizing import substitution in high-frequency pressure transducer supply.
Japan
METI industrial policy directs standardization efforts for metal additive manufacturing in safety-critical applications, with JIS frameworks informing pressure vessel test protocols. Aerospace and precision machinery sectors drive rig procurement for electron beam melting component validation. Kanto and Chubu regions concentrate demand, with Nagoya-area automotive suppliers extending additive qualification programs into pressure-bearing structural applications.
United Kingdom
Post-Brexit regulatory divergence from EU Pressure Equipment Directive creates parallel compliance pathways for pressure equipment exporters. Element Materials Technology leverages domestic laboratory networks to anchor certification workflows for aerospace clients. Midlands and Southeast England concentrate testing infrastructure investment, with space technology supply chains in these regions scaling directed energy deposition validation for satellite propulsion systems.
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with third-party certification bodies capturing outsourced testing demand from mid-tier aerospace suppliers while equipment fabricators serve integrated buyers. The vendor base organizes around three strategic archetypes: global laboratory networks anchoring compliance workflows, regional specialists concentrating calibration services, and equipment manufacturers supplying configurable test platforms. M&A activity concentrates laboratory network consolidation, while capacity expansion dominates among equipment fabricators seeking to capture Texas cluster demand.
Among global laboratory networks, Intertek Group, SGS, and TÜV SÜD represent distinct geographic anchoring strategies. Intertek exemplifies the scale-driven certification archetype through expanded additive manufacturing validation capacity. SGS occupies a position emphasizing digital reporting platform integration. TÜV SÜD sits within the European regulatory specialization tier, sustaining demand for calibration services through regional standards expertise.
| Leading Market Players |
|---|
| Intertek Group |
| SGS |
| Element Materials Technology |
| TÜV SÜD |
| DEKRA |
| Bureau Veritas |
| Applus+ |
| UL Solutions |
| Pressure Systems International |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up laboratory networks now dominate the certification layer, compressing pricing discipline across test rig procurement as consolidated buyers extract volume discounts while fragmented equipment fabricators compete on specification customization. This ownership pattern concentrates supply-side pricing power with third-party validation providers while forcing hardware manufacturers toward subscription-based revenue models.
Pricing Analysis
Capacity additions in Texas are reshaping price floors for hydrostatic test rigs as Houston and Austin cluster expansion creates localized oversupply in standard configurations. Pricing stratifies across certified-premium, standard-compliance, and economy-validation tiers, with differentiation driven by FAA pathway documentation depth and data acquisition bandwidth. Price erosion runs through economy-tier pneumatic systems as laser powder bed fusion compatibility constraints limit addressable demand. Aerospace engineers show least price sensitivity, prioritizing integrated digital twin validation over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements from NASA and FAA mandate multi-supplier qualification for high-frequency pressure transducers, constraining procurement flexibility despite concentrated German and Japanese sensor manufacturing. Supply draws from Germany, Japan, and the United States for precision instrumentation, with Texas anchoring final rig assembly capacity. Specialized strain gauge systems and 1000 Hz sampling electronics face single-source vulnerability from concentrated component specialists. Distribution runs through direct OEM relationships for integrated buyers and third-party laboratory networks for outsourced validation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory qualification pathways harden into permanent compliance infrastructure across aerospace supply chains.
For Market Incumbents: Anchor certification workflows through exclusive calibration partnerships with TÜV SÜD and Intertek Group laboratory networks. Invest in backward integration of high-frequency data acquisition electronics to offset German and Japanese sensor supply constraints. Defend against emerging software-defined automation entrants by bundling predictive fracture analytics with hardware contracts. For New Entrants and Emerging Players: Cloud-based compliance documentation platforms offer the most penetrable entry vector, targeting mid-tier aerospace suppliers displaced from in-house testing departments. Focus initial deployment on Texas cluster oilfield equipment manufacturers seeking outsourced subsea equipment validation. Pursue ASTM F42 binder jetting standard pre-certification to capture first-mover positioning as ferrous alloy protocols mature. For Investors and Strategic Acquirers: Valuations sit cheapest among regional calibration specialists with ISO/ASTM 52900 certification capabilities but limited geographic footprint. Five-to-ten-year viability rests on regulatory pathway permanence rather than cyclical capital expenditure patterns. Watch for FAA additive manufacturing qualification pathway expansion beyond crewed space missions into commercial aviation as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Workflow Integration | Pre-integrated compliance documentation with FAA and NASA standards accelerates customer procurement cycles. |
| Sensor Supply Backward Integration | In-house production of 1000 Hz pressure transducers reduces dependency on German and Japanese component specialists. |
| Subscription Analytics Launch | Remote monitoring modules with predictive fracture algorithms create recurring revenue beyond equipment sales. |
| Binder Jetting Fixture Development | Adaptable clamping systems for ASTM F42 ferrous alloy protocols capture emerging standardization demand. |
| Texas Cluster Capacity Expansion | Adjacent oilfield and aerospace testing facilities in Houston and Austin generate localized demand concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aerospace procurement directors, oilfield equipment validation engineers, third-party laboratory operations managers, and additive manufacturing process specialists with secondary validation against FAA certification databases, NASA technical standards repositories, ASTM F42 committee documentation, and ASME Boiler and Pressure Vessel Code regulatory filings. Bottom-up rig shipment tallies and top-down aerospace capital expenditure patterns were triangulated to anchor volume estimates.
Historical reference periods spanning pre-qualification pathway and post-mandate implementation phases established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across product architecture, build technology, application safety-criticality, and buyer sophistication tiers. CAGRs were derived from equipment procurement cycle analysis and regulatory compliance deadline clustering. Forecast inputs included directed energy deposition capacity expansion rates and subsea wellhead component adoption curves.
Regulatory standard revisions, sensor supply disruptions, and aerospace program cancellation waves are the dominant revision risks to the outlook. Deviation in FAA pathway enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market