
 Low Fat Spaghetti Sauce Market | 2026-2036
Low Fat Spaghetti Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Spaghetti Sauce Market Analytics
Market Context
Capital-intensity divergence between in-house tomato processing and co-packer reliance is redrawing competitive tiers in low fat spaghetti sauce manufacturing. Kraft Heinz Company leverages captive agricultural sourcing across California processing facilities to control input costs. Rao's sustains premium positioning through small-batch production methods and limited distribution. Mizkan America competes on volume scale via automated filling lines and national retail penetration.
Technical Definition and Segment Structure
Low fat spaghetti sauce denotes tomato-based pasta sauces containing reduced lipid content, typically achieved through minimal olive oil inclusion and lean meat exclusion, with FDA-defined standards requiring disclosure when "low fat" claims appear on labeling. The product serves commercial food service operators and retail consumers seeking calorie-controlled meal preparation without flavor compromise. Organic formulations command margin premiums in specialty retail channels while conventional variants dominate supermarket shelf space through price accessibility. Glass jar packaging retains preference among premium brands despite higher logistics costs, whereas pouch formats gain traction in online retail channels for reduced shipping weight.
Regulatory Framework
FDA nutrition labeling standards govern fat-content claims and serving-size declarations for low fat spaghetti sauce distributed in the United States, while USDA organic certification requirements shape ingredient sourcing for premium-tier producers. European EFSA guidelines on health claims and front-of-pack nutritional scoring systems influence export formulation decisions for North American manufacturers. Stakeholders must monitor evolving sodium-reduction mandates and clean-label enforcement trends that could force reformulation investments ahead of compliance deadlines.
Market Dynamics
FDA front-of-pack calorie disclosure mandates and EFSA health-claim guidelines are compressing formulation timelines while clean-label enforcement accelerates R&D reinvestment cycles across tomato-processing operations.
Growth Catalysts
- Clean-label enforcement:USDA organic certification requirements and FDA disclosure rules compel manufacturers to reformulate with recognizable ingredient decks, opening shelf-space advantages for compliant producers in metropolitan retail corridors.
- Home cooking persistence:Health-conscious households in North American urban centers sustain demand for reduced-fat pasta sauces as primary meal-preparation components rather than discretionary purchases.
- Glass-to-pouch migration:Automated pouch-filling technology reduces shipping weights for direct-to-consumer channels, enabling margin recovery previously lost to logistics cost inflation.
Market Restraints
- Tomato input volatility:California agricultural sourcing concentration exposes processors to drought-driven crop yield fluctuations and irrigation cost spikes.
- Co-packer dependency:Mid-tier brands lacking captive processing facilities face margin compression when contract manufacturing rates reset against commodity tomato paste price swings.
- Clean-label cost premium:Organic ingredient sourcing and reduced-sodium reformulation requirements elevate unit production costs above conventional sauce price floors.
Strategic Opportunities
- European export alignment:EFSA front-of-pack nutritional scoring systems create formulation templates that, once validated, unlock supermarket network access across Germany, France, and Netherlands urban corridors.
- Food service portion control:Single-serve pouch formats for commercial kitchen operators address labor-cost pressures in US institutional dining contracts.
- Sodium-reduction tailwinds:Anticipated FDA sodium-target mandates position early reformulators for preferential retail placement when enforcement deadlines activate.
Industry Challenges
- Flavor-chemistry expertise scarcity:Reduced-fat formulation without lipid carriers demands specialized savory-masking competencies that outpace current food-science graduate pipeline output.
- Legacy equipment retrofit costs:Clean-in-place system upgrades for allergen-control compliance strain capital allocation at mid-scale processing facilities.
Report Scope
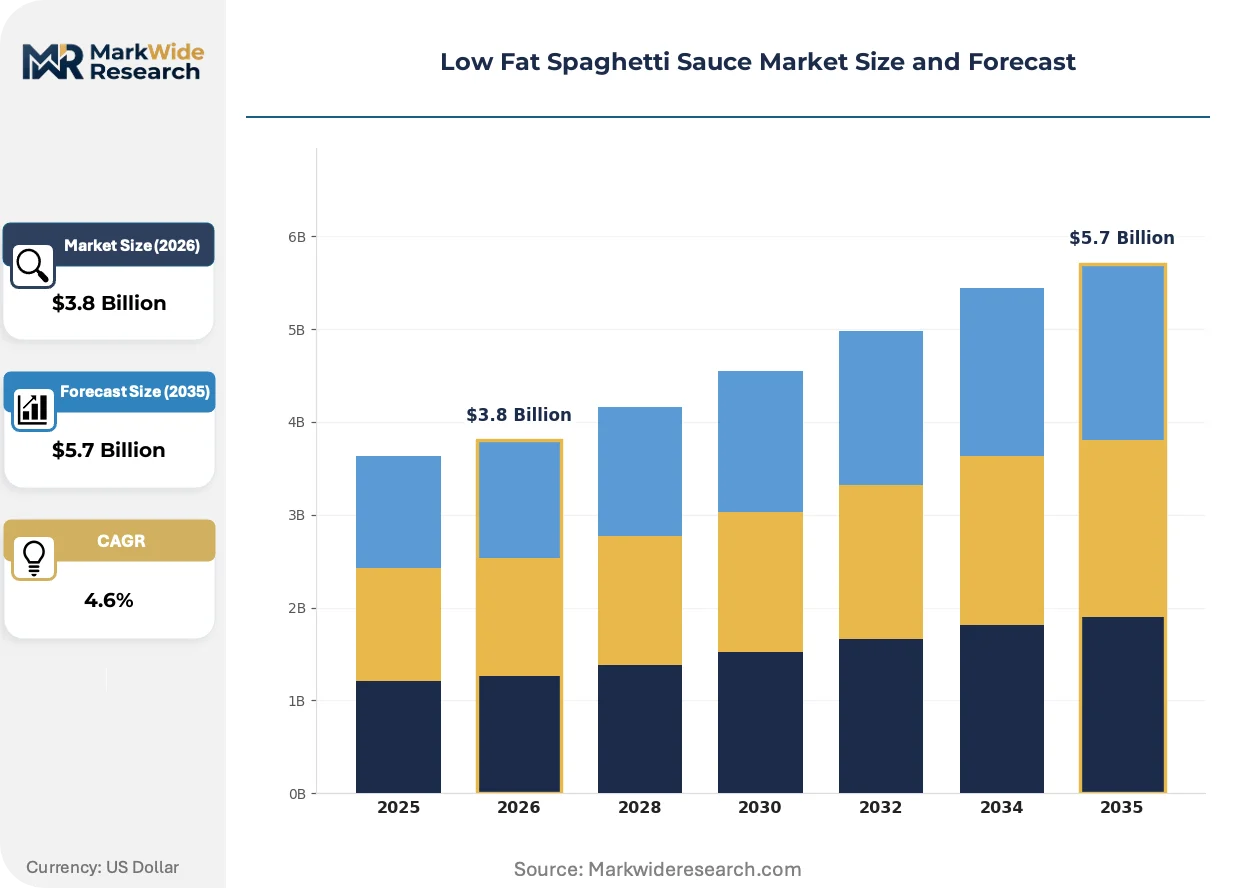
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Spaghetti Sauce Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Gluten-Free, No Added Sugar Packaging Type: Glass Jar, Plastic Bottle, Tetra Pack, Pouch Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Shops End User: Households, Restaurants, Cafés, Food Service Providers |
| Companies Covered | Del Monte Foods, Campbell Soup Company, Kraft Heinz Company, General Mills, Conagra Brands, Barilla G. e R. Fratelli S.p.A., Mizkan America, Rao’s, Primal Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Spaghetti Sauce Market Evolving Landscape
Reformulation science and packaging automation are redrawing competitive boundaries between premium small-batch positioning and mass-market scale efficiency in reduced-fat sauce production.
High-pressure processing technology is fragmenting shelf-stable preservation paradigms by enabling clean-label texture stability without thermal degradation of volatile aromatic compounds. Specialty retail buyers in US coastal metropolitan markets are adopting HPP-treated lines at accelerated placement rates. This capability divergence is fragmenting R&D investment priorities between thermal-processing incumbents and cold-chain-dependent entrants.
EFSA nutrient-profiling criteria for health-claim eligibility are compressing formulation flexibility for export-bound manufacturers, forcing sodium and saturated-fat reductions ahead of domestic regulatory timelines. European supermarket chains are enforcing these standards through private-label procurement specifications. North American producers targeting EU distribution are responding with dual-formulation SKUs segregated by destination market.
Direct-to-pantry subscription models are displacing conventional supermarket replenishment cycles among health-focused consumer cohorts. Meal-kit integrators and specialized online grocers are capturing recurring purchase commitments previously routed through brick-and-mortar retail. This channel rotation is most pronounced in US suburban markets with elevated dual-income household density and limited time-foraging behavior.
Low Fat Spaghetti Sauce Market Segmentation
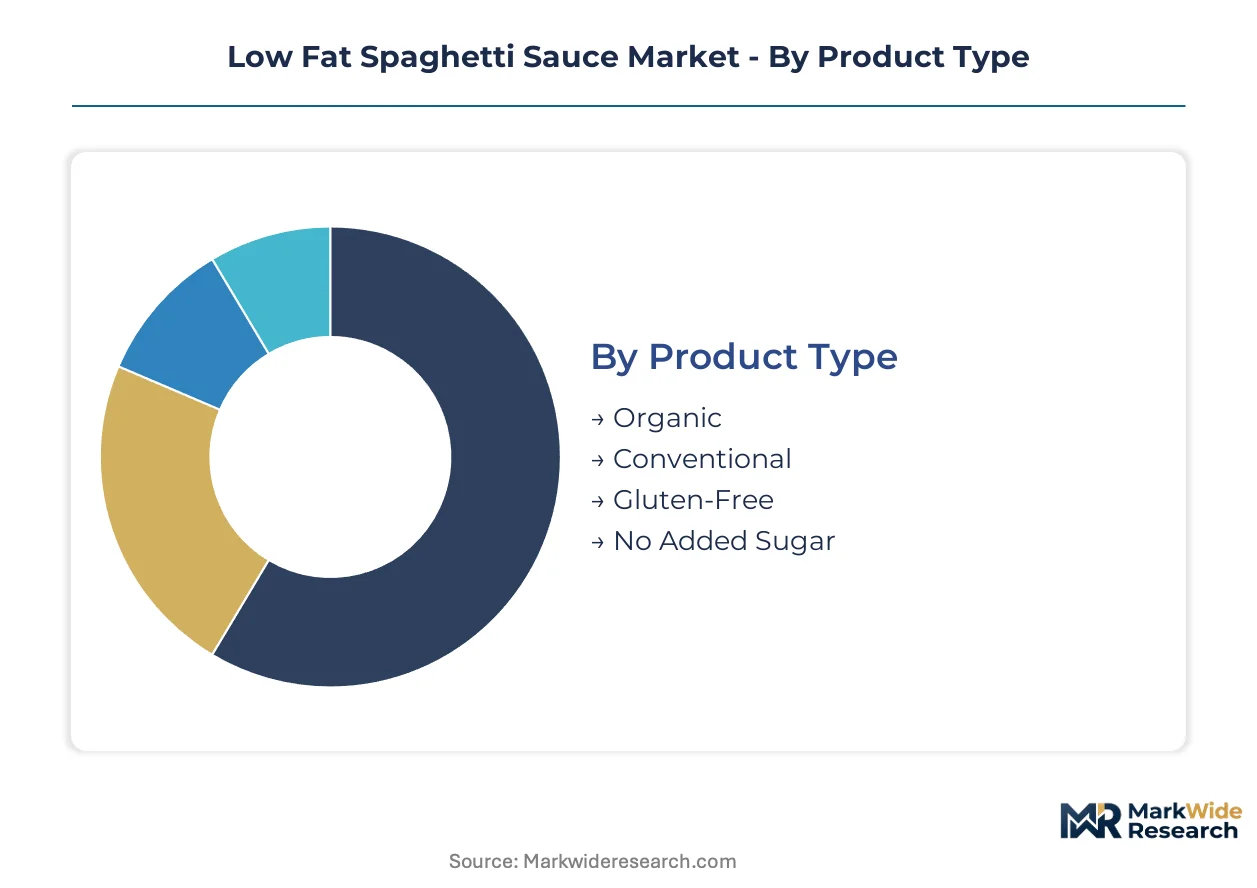
Segmentation in low fat spaghetti sauce reveals divergent margin profiles and channel access patterns. Organic and conventional formulations operate on fundamentally different cost structures, while packaging choices determine logistics feasibility for direct-to-consumer expansion.
Product Type:
Organic formulations concentrate in California and Pacific Northwest metropolitan retail corridors where household income supports price premiums. Conventional variants dominate export volumes to European supermarket networks through co-packer arrangements.
- Organic:USDA-certified ingredient sourcing with restricted synthetic inputs and documented supply chain traceability. Demand concentrates in Whole Foods Market and Sprouts Farmers Market locations across Denver, Austin, and Seattle metropolitan areas where clean-label purchasing drives basket composition.
- Conventional:Standard tomato paste base with permitted food-grade additives and conventional agricultural inputs. Volume leadership in Walmart and Kroger banner stores throughout the US Southeast and Midwest where unit price sensitivity shapes shelf placement decisions.
- Gluten-Free:Certified gluten-free production protocols with segregated processing equipment and third-party validation.
- No Added Sugar:Naturally occurring tomato sugars only, targeting diabetic and ketogenic diet adherents in health-focused retail channels.
Conventional holds the largest share; momentum sits with organic as FDA disclosure rules intensify ingredient scrutiny.
Packaging Type:
Glass jar dominance reflects premium positioning and shelf stability, though shipping cost inflation accelerates format experimentation. Pouch adoption concentrates in subscription-commerce channels where weight reduction offsets last-mile delivery economics.
- Glass Jar:Inert thermal processing compatibility and premium tactile perception with established consumer familiarity. Rao's and Classico maintain placement advantages in Northeast US specialty grocers where jar reuse and recycling align with household sustainability practices.
- Pouch:Flexible film construction with fitment closures enabling precise portion dispensing and reduced shipping cube. Thrive Market and Amazon Fresh procurement teams favor pouch SKUs for fulfillment center efficiency in suburban California and Texas delivery zones.
- Plastic Bottle:PET barrier technology with squeeze dispensing and reduced breakage risk in retail handling.
- Tetra Pack:Aseptic carton filling with ambient distribution economics and rectangular shelf efficiency.
Glass jar retains volume leadership; pouch formats are climbing the fastest as direct-to-pantry subscriptions displace conventional replenishment cycles.
Distribution Channel:
Supermarket concentration reflects established slotting fee structures and promotional calendar dependencies. Online retailer growth correlates with metropolitan household time scarcity and subscription lock-in mechanics.
- Supermarkets:Center-store placement with category management protocols and trade promotion funding requirements. Safeway-Albertsons and Publix banner stores in Florida and California metropolitan corridors maintain the highest low fat sauce category velocity through weekly circular feature support.
- Online Retailers:Algorithmic search placement with review aggregation and auto-replenishment subscription tools. Thrive Market and Thistle capture recurring purchase commitments in Los Angeles and San Francisco suburban markets with limited time-foraging behavior.
- Convenience Stores:Immediate consumption positioning with limited SKU breadth and grab-and-go packaging formats.
- Specialty Shops:Curated assortment with local and artisanal provenance emphasis and educated staff recommendation.
Supermarkets hold the largest share; momentum sits with online retailers as meal-kit integrators capture pantry replenishment occasions.
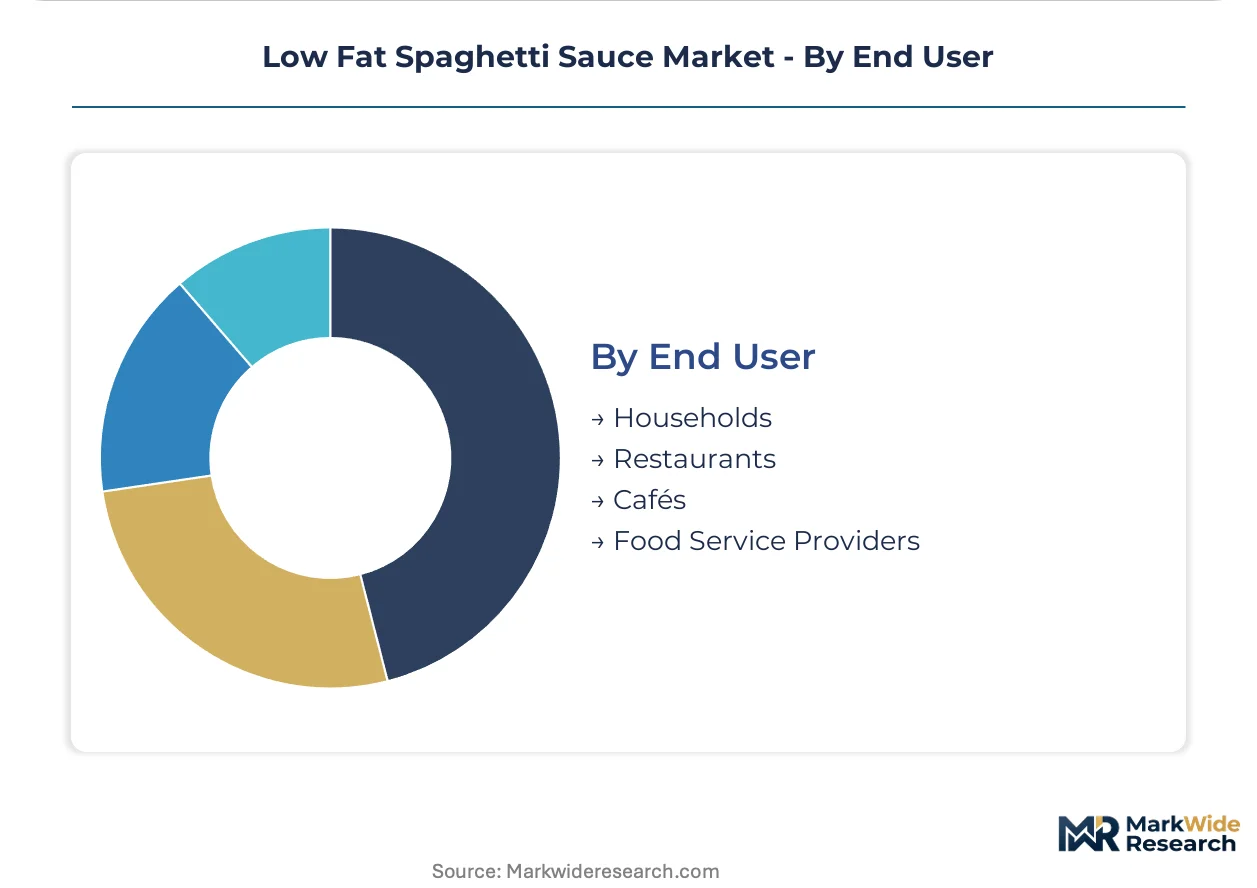
End User:
Household consumption patterns diverge sharply from commercial food service procurement on specification rigor and volume predictability. Restaurant operators prioritize portion consistency and labor minimization over ingredient provenance claims.
- Households:Discretionary purchase with flavor preference heterogeneity and storage constraint sensitivity. Dual-income households in US suburban markets with elevated time scarcity drive pouch and single-serve format adoption for weeknight meal assembly.
- Food Service Providers:Contracted volume procurement with specification compliance and cost-per-portion optimization. Aramark and Compass Group institutional dining contracts in US university and healthcare systems demand sodium-reduced formulations with consistent viscosity for steam-table holding.
- Restaurants:Menu integration with sauce-as-ingredient functionality and back-of-house labor reduction priorities.
- Cafés:Limited menu application with premium positioning and small-batch aesthetic alignment.
Households hold the largest share; momentum sits with food service providers as sodium-reduction mandates approach enforcement deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States metropolitan retail corridors while European supermarket networks enforce stricter margin compression through private-label procurement specifications. This asymmetry shapes where multinational producers prioritize reformulation investments versus volume scale.
United States
Health-conscious households in Denver, Austin, and Seattle metropolitan areas drive organic formulation premiums through Whole Foods Market and Sprouts Farmers Market channels. FDA front-of-pack calorie disclosure mandates compel sodium-reduction R&D ahead of anticipated enforcement deadlines. California agricultural processing clusters around Sacramento and Fresno supply tomato paste inputs to captive Heinz facilities and co-packer networks alike.
Germany
EFSA nutrient-profiling criteria for health-claim eligibility force sodium and saturated-fat reductions ahead of domestic US timelines. German supermarket chains enforce these standards through private-label procurement specifications that North American exporters must satisfy. The Rhine-Ruhr metropolitan corridor concentrates distribution logistics for EU-bound sauce volumes.
France
Clean-label purchasing in Paris and Lyon urban supermarkets prioritizes recognizable ingredient decks over conventional additive-stabilized formulations. ANSM and DGCCRF enforcement of nutritional labeling accuracy creates compliance barriers for imported sauces. Provence-Alpes-Côte d'Azur retail networks favor glass jar formats aligned with established sustainability practices.
United Kingdom
Dual-income households in Greater London and Southeast England drive subscription-commerce adoption for pouch-format sauces through Ocado and Amazon Fresh channels. Food Standards Agency front-of-pack traffic-light labeling influences reformulation priorities for export-bound manufacturers. Midlands distribution hubs handle cross-channel logistics for Irish Republic retail penetration.
Italy
Domestic tomato processing heritage in Emilia-Romagna and Campania sustains artisanal positioning for premium sauce exports. Italian Ministry of Health enforcement of origin labeling requirements protects regional designation value. Milan and Rome metropolitan retail corridors balance imported low-fat formulations against traditional full-fat domestic alternatives.
Low Fat Spaghetti Sauce Market Competitive Landscape
Concentration sits with diversified food conglomerates holding captive agricultural sourcing and national retail slotting arrangements. Mid-tier brands depend on co-packer networks that expose margins to tomato input volatility. Three archetypes dominate: vertically integrated processors controlling California supply chains, premium small-batch specialists with limited distribution, and scale-driven mass-market operators optimizing automated filling lines. Competitive moves center on sodium-reduction R&D racing and pouch-format capacity expansion for direct-to-consumer channels.
Within the diversified conglomerate tier, Kraft Heinz Company and Conagra Brands occupy positions defined by captive supply chain control versus co-packer flexibility trade-offs. Campbell Soup Company exemplifies the mid-tier archetype navigating reformulation cost pressures. Rao's and Primal Kitchen represent premium positioning through ingredient provenance claims rather than volume scale. Mizkan America sits within the scale-driven segment competing on automated production efficiency and national retail penetration breadth.
| Leading Market Players |
|---|
| Del Monte Foods |
| Campbell Soup Company |
| Kraft Heinz Company |
| General Mills |
| Conagra Brands |
| Barilla G. e R. Fratelli S.p.A. |
| Mizkan America |
| Rao's |
| Primal Kitchen |
| Others |
Value Network & Pricing Analysis
USDA organic certification gates both supplier qualification and price differentiation simultaneously, forcing dual-formulation investments that stratify procurement tiers between captive California processors and co-packer dependent mid-tier brands.
Pricing Analysis
The customization-premium spread between small-batch artisanal positioning and mass-market commodity pricing spans three distinct tiers. Premium-mid-economy pricing differentiation rests on organic certification status and glass jar packaging tactile perception, while conventional variants compete on unit accessibility in Walmart and Kroger banner stores. Cost compression in the mid-tier is intensifying because co-packer rate resets track tomato paste commodity swings. Food service providers exhibit the highest price sensitivity due to cost-per-portion optimization mandates, whereas health-focused households in Denver and Seattle metropolitan corridors show the lowest sensitivity.
Supply Chain Analysis
California agricultural processing concentration around Sacramento and Fresno underwrites domestic tomato paste availability for both captive Heinz facilities and contract manufacturing networks. Raw material dependencies center on drought-vulnerable California tomato harvests, imported olive oil inputs, and sodium-reduction substitute compounds. Single-source vulnerability runs through irrigation-cost exposure and climate-driven yield fluctuation. Distribution runs through supermarket center-store slotting arrangements with promotional calendar dependencies, though direct-to-pantry subscription channels are displacing conventional replenishment cycles in suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-pantry subscription mechanics are transforming low fat spaghetti sauce into a platform-economics inflection, where meal-kit integrators and specialized online grocers capture recurring purchase commitments through auto-replenishment lock-in.
For Market Incumbents: Shield shelf-space advantages by accelerating sodium-reduction R&D ahead of FDA enforcement deadlines and securing captive California agricultural sourcing to insulate margins from co-packer rate volatility. Prioritize pouch-format capacity expansion for Thrive Market and Amazon Fresh fulfillment center efficiency. For New Entrants and Emerging Players: Differentiate on high-pressure processing technology for clean-label texture stability without thermal degradation, targeting specialty retail placement in US coastal metropolitan markets. Penetrate the food service single-serve pouch segment where Aramark and Compass Group contracts demand consistent viscosity for steam-table holding. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated pouch-filling line deployment and clean-in-place system upgrades for allergen-control compliance. Long-term viability favors acquisition targets with dual-formulation SKU capabilities for EFSA-aligned European export. Monitor FDA sodium-target mandate announcement timing as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium-Reduction Reformulation | Positions early movers for preferential retail placement when FDA enforcement deadlines activate. |
| Pouch Format Capacity Expansion | Captures direct-to-pantry subscription growth through Thrive Market and Amazon Fresh procurement. |
| High-Pressure Processing Adoption | Enables clean-label texture stability for specialty retail buyers in coastal metropolitan corridors. |
| European Export Formulation Alignment | Unlocks supermarket network access across Germany, France, and Netherlands urban corridors. |
| Captive Agricultural Sourcing | Insulates Kraft Heinz and integrated processors from California drought-driven input volatility. |
Research Methodology
Desk research of FDA filing databases, USDA organic certification registries, and Nielsen retail audit data preceded structured interviews with tomato processing plant managers, category buyers at Kroger and Albertsons banners, and supply planners at co-packer networks. Primary fieldwork with R&D directors at diversified food conglomerates and secondary validation against EFSA nutrient-profiling guidelines supported bottom-up volume modeling and top-down value triangulation.
Variance decomposition across organic versus conventional formulation segments, glass jar versus pouch packaging formats, and supermarket versus online retailer distribution channels anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending with tomato input cost trajectory assumptions and clean-label enforcement timeline modeling.
Material uncertainties — California drought severity, FDA sodium mandate timing, and EFSA health-claim guideline evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions about home cooking persistence and subscription-commerce adoption curves. Practitioners should keep alternative scenarios live as regulatory enforcement deadlines and agricultural yield conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Sauce Making Machine Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Cheese Sauce Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Latin America Pasta Sauce Market