
 Culinary Sauces Market | 2026-2036
Culinary Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Culinary Sauces Market Intelligence
Expanded production capacity in Mexico for tomato and chili-based sauces is rewriting supply chain dynamics for the North American market. The Kraft Heinz Company leverages its vast distribution network to maintain dominance in the household consumer segment. McCormick & Company Inc. specializes in herb-infused and ethnic flavor profiles targeting gourmet channels. Meanwhile, Unilever PLC competes with a broad portfolio that spans multiple condiment categories.
Culinary sauces are liquid or semi-solid preparations designed to add flavor, moisture, and texture to food. These formulations are characterized by specific viscosity and total solids content, which dictate their functional use. Tomato-based sauces constitute a mature, high-volume category, while soy-based and herb-infused varieties are expanding rapidly. Foodservice providers drive demand for large-format cooking bases and dips, contrasting with household consumers who prefer smaller bottles and jars.
Regulations from the US FDA and the European Food Safety Authority (EFSA) mandate strict allergen labeling and control permissible additives. Concurrently, standards from India's FSSAI and China's SAMR influence market access through specific food safety and import requirements. Navigating this complex web of international standards while adapting to volatile ingredient costs remains the central challenge for manufacturers.
Market Dynamics
Demand for culinary sauces is concentrating around two poles: foodservice operators requiring absolute consistency for multi-unit operations and household consumers demanding clean-label, natural ingredients. This dual pressure shapes all aspects of product development, supply chain logistics, and regulatory strategy.
Growth Catalysts
- Foodservice Expansion:The growth of restaurant chains in emerging economies like India and Brazil requires standardized, large-format sauces to ensure flavor consistency.
- Clean-Label Formulations:Consumer demand for transparency and natural ingredients, reinforced by labeling guidelines from bodies like the FDA, drives innovation in natural preservatives.
- Culinary Exploration:Rising disposable incomes and global media exposure encourage consumers to experiment with ethnic flavors, boosting demand for soy-based and herb-infused varieties.
Market Restraints
- Ingredient Volatility:The cost and supply of key agricultural inputs like tomatoes, chilies, and herbs are subject to climate-related and geopolitical disruptions.
- Regulatory Fragmentation:Manufacturers face high compliance costs navigating divergent food safety standards set by the EFSA, FSSAI, and SAMR.
- Supply Chain Risk:Heavy reliance on specific geographies, such as Mexico for chili and tomato processing, creates potential bottlenecks for the North American market.
Strategic Opportunities
- Plant-Based Sauces:Developing dedicated sauce and condiment lines formulated specifically to complement the taste and texture of plant-based meat alternatives represents a significant growth area.
- Functional Formulations:Incorporating ingredients with perceived health benefits, such as probiotics or high-antioxidant spices, can create a new premium tier focused on wellness.
- Direct-to-Consumer Channels:E-commerce platforms and social media marketing enable artisanal and specialty producers to bypass traditional retail and build direct customer relationships.
Industry Challenges
- Natural Preservation Science:Achieving extended shelf stability using only natural preservatives without affecting taste, color, or texture remains a significant formulation challenge for manufacturers.
- Allergen Management Complexity:Adhering to strict allergen labeling laws from regulators like the FDA requires dedicated production lines or complex clean-in-place procedures, increasing operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Culinary Sauces Market |
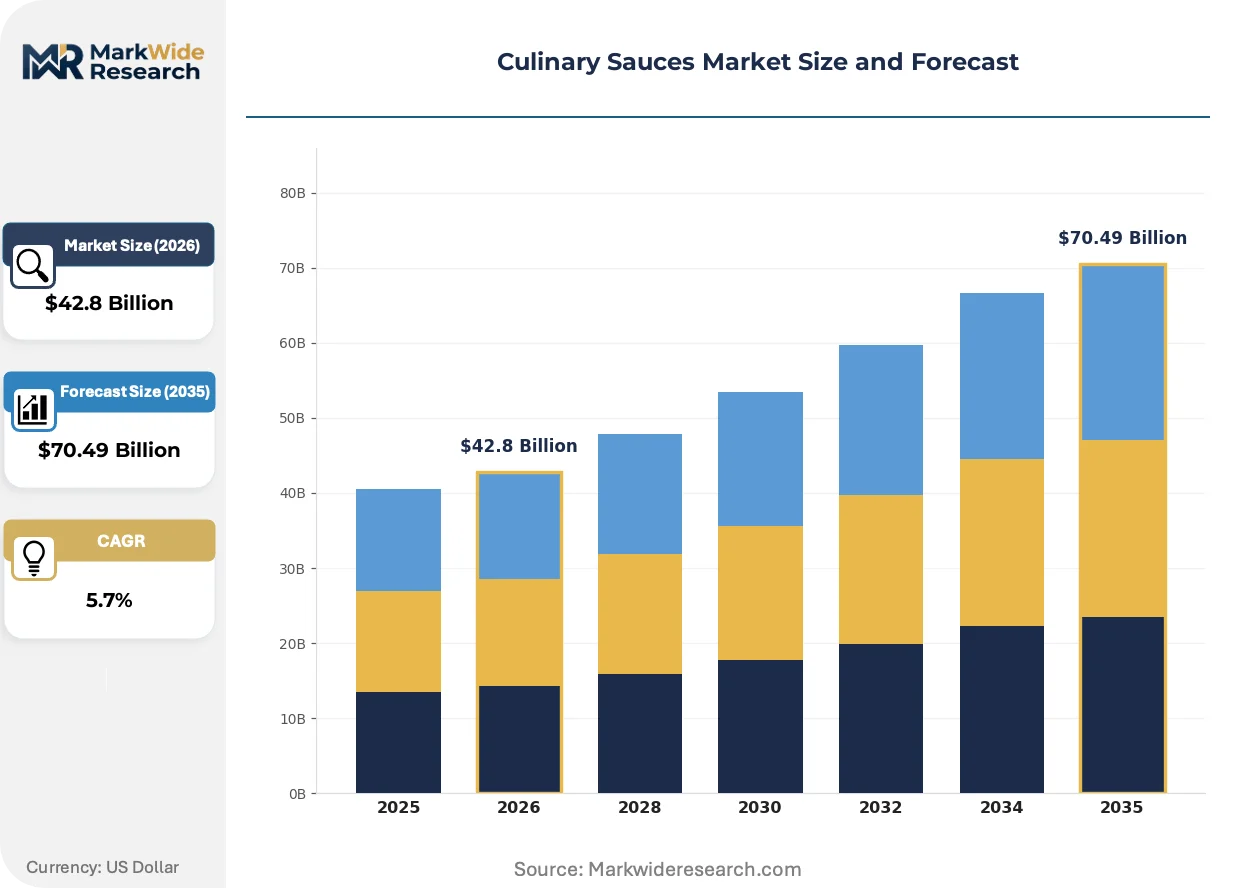
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomato-Based, Cream-Based, Soy-Based, Mustard-Based, Herb-Infused, Vinegar-Based Application: Marinades, Dips, Dressings, Cooking Bases, Glazes, Condiments Packaging Type: Bottles, Pouches, Jars, Tubes, Sachets, Dispensers Customer Type: Foodservice Providers, Gourmet Retailers, Catering Companies, Household Consumers, Specialty Stores, Institutional Buyers |
| Companies Covered | The Kraft Heinz Company, Unilever PLC, McCormick & Company Inc., Kikkoman Corporation, Conagra Brands, Nestlé S.A., Del Monte Foods Inc., Hormel Foods Corporation, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Culinary Sauces Market Strategic Shifts & Innovations
The convergence of advanced food processing science and shifting consumer purchasing channels is reshaping the culinary sauces market. Manufacturers are navigating new formulation challenges while adapting to a digitally-driven distribution landscape that prioritizes customization and direct engagement.
High-Pressure Processing (HPP) provides non-thermal pasteurization that preserves fresh flavor and nutritional value in sauce formulations. Premium and clean-label brands are rapidly adopting this technology for their refrigerated product lines. This adoption is collapsing the long-standing compromise between shelf stability and fresh-like sensory attributes, enabling new product categories.
Mandates from the European Food Safety Authority (EFSA) regarding front-of-pack nutrition labeling are creating new compliance pressures. This forces manufacturers to reformulate products to reduce salt, sugar, and fat content to achieve better scores. The ambient, shelf-stable sauce category is most affected, prompting investment in flavor-enhancing natural ingredients to compensate for reductions.
A shift towards meal-kit subscriptions and ghost kitchen models alters buying patterns for sauce manufacturers. This model bypasses traditional retail channels, creating demand for customized, portion-controlled formats supplied directly to these new foodservice ventures. The trend is most visible in dense urban centers across the United States and the United Kingdom.
Culinary Sauces Market Segmentation
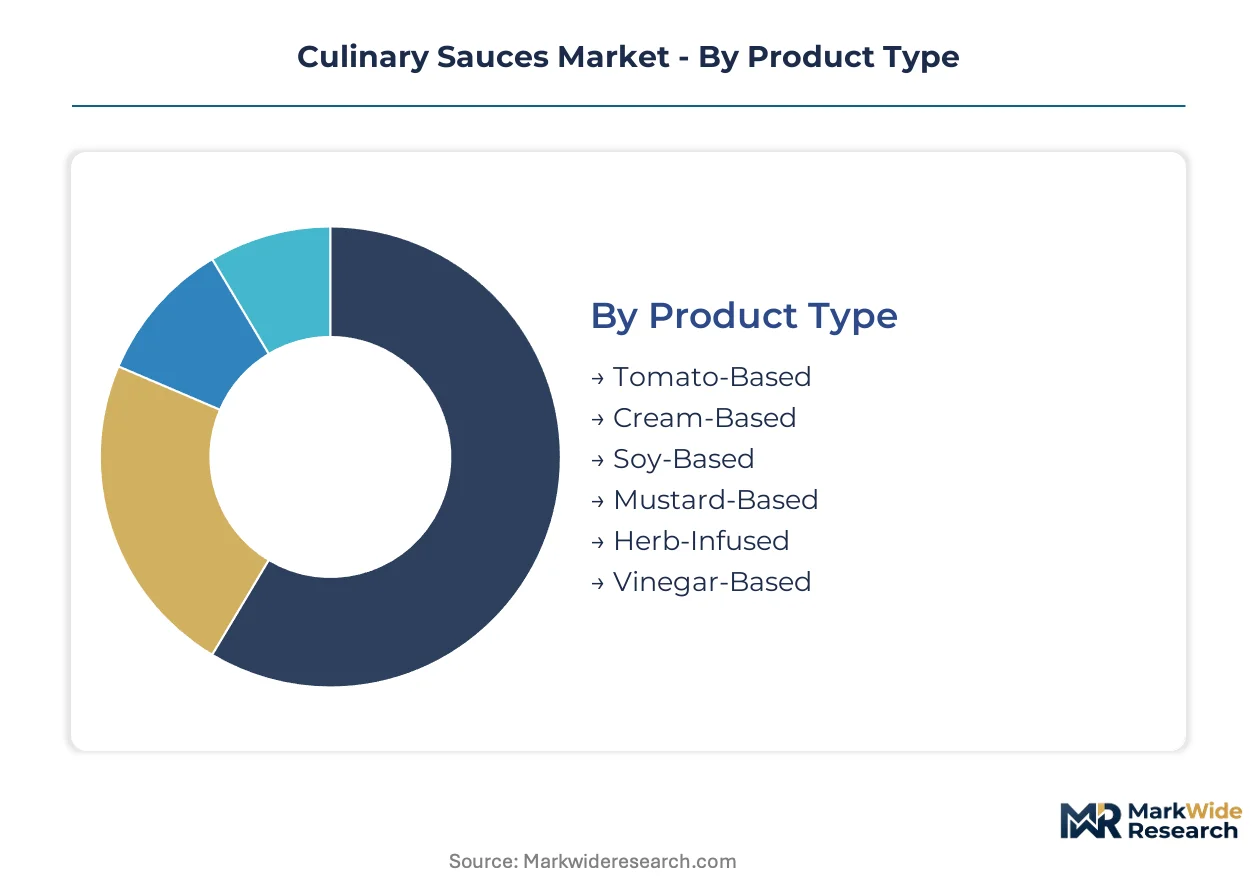
The culinary sauces market fragments across diverse product types, applications, packaging formats, and customer groups. Understanding these distinct segments is essential for manufacturers to tailor product development, distribution strategies, and marketing efforts effectively. Each segment exhibits unique characteristics influencing consumer preferences and operational requirements.
Product Type:
Segments within product type exhibit varied consumption cycle times, from daily staples to occasional gourmet ingredients.
- Tomato-Based:These sauces, derived primarily from tomatoes, form a foundational, high-volume category known for versatility in cooking. Demand remains robust among household consumers and foodservice providers for consistent, familiar flavor profiles.
- Soy-Based:Characterized by fermented soybeans, these varieties deliver umami flavors, expanding rapidly in markets like India and Brazil. Culinary exploration drives consumer interest in ethnic flavors, boosting demand for these versatile sauces.
- Cream-Based:These sauces offer rich, often dairy-infused textures, frequently used in pasta dishes and gratins.
- Mustard-Based:Offering piquant and tangy notes, these sauces serve as popular condiments and flavor enhancers for various cuisines.
- Herb-Infused:Varieties featuring fresh or dried herbs provide aromatic and complex flavor profiles, targeting gourmet channels.
- Vinegar-Based:These sauces, often acidic, are utilized for marinades, dressings, and as a balancing agent in many culinary preparations.
Tomato-Based anchors the volume base while Soy-Based gains share at the steepest rate.
Application:
The application categories delineate how culinary sauces integrate into meal preparation, influencing purchase volume and frequency.
- Condiments:These sauces are typically added to food after preparation, enhancing flavor directly at the table, with broad household consumer appeal. Demand for condiments focuses on convenience and diverse flavor options for everyday meals.
- Cooking Bases:Designed as foundational flavor components, these large-format preparations provide a consistent starting point for complex dishes, crucial for multi-unit restaurant chains. Foodservice providers prioritize these for operational efficiency and standardized taste.
- Marinades:Used to tenderize and flavor meats or vegetables before cooking, these preparations penetrate the food structure.
- Dips:Thick, flavorful sauces designed for dipping snacks or appetizers, popular in social settings and casual dining.
- Dressings:Liquid preparations used to flavor salads and other cold dishes, often vinegar or oil-based.
- Glazes:Sweet or savory coatings applied to food, typically during or after cooking, to impart shine and flavor.
Condiments often command consistent household spending, whereas Glazes frequently achieve higher per-unit margins in specialty channels.
Packaging Type:
Packaging formats dictate product shelf life and convenience, directly impacting the volume purchased by different consumer groups.
- Bottles:Traditional glass or plastic containers widely used for household consumer products, offering good shelf stability and brand visibility. Household consumers prefer bottles for their familiarity and ease of storage in home kitchens.
- Pouches:Flexible packaging solutions offering lightweight, space-saving, and often single-serve options, gaining traction in e-commerce and meal kits. Foodservice operators increasingly adopt pouches for reduced waste and easier bulk handling.
- Jars:Glass containers, often used for premium or artisanal sauces, providing good product visibility and perceived quality.
- Tubes:Squeezeable containers, common for concentrated pastes or specialty sauces, offering controlled dispensing.
- Sachets:Small, single-serving packets providing convenience and portion control, prevalent in fast-food and travel sectors.
- Dispensers:Large-format containers with pumps or spouts, primarily for high-volume foodservice and institutional use.
Bottles remain the preferred format for household consumers, while Dispensers increasingly cater to high-volume foodservice operations.
Customer Type:
Customer types range from high-volume institutional buyers to niche gourmet retailers, each presenting distinct cost and service requirements.
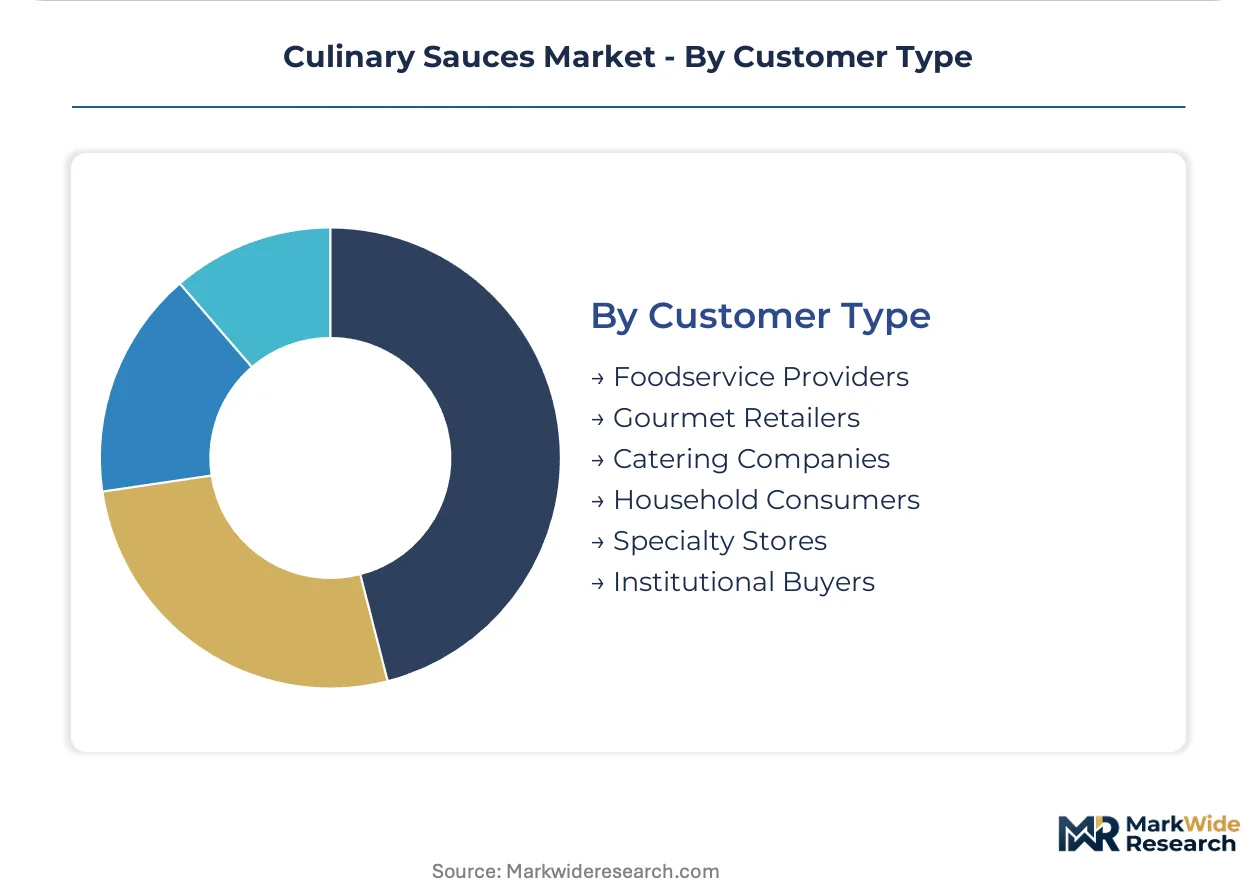
- Household Consumers:Individual shoppers purchasing sauces for home consumption, driven by brand loyalty, convenience, and clean-label preferences. This segment drives demand for smaller formats and diverse flavor options.
- Foodservice Providers:Restaurants, cafes, and caterers requiring consistent quality, large formats, and reliable supply chains for their commercial operations. Their demand centers on product consistency for multi-unit operations.
- Gourmet Retailers:Specialty stores offering premium, artisanal, or imported sauces, targeting consumers seeking unique culinary experiences.
- Catering Companies:Businesses providing food services for events, requiring bulk packaging and versatile sauce options.
- Specialty Stores:Niche retail outlets focusing on specific culinary themes or imported goods, stocking unique sauce varieties.
- Institutional Buyers:Large organizations like schools, hospitals, or corporate cafeterias, prioritizing cost-effectiveness and bulk purchasing.
Household Consumers drive the largest demand, and Foodservice Providers influence supply chain configurations through bulk procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA mandates on allergen labeling significantly influence product formulations and supply chain practices across North America. This regulatory environment shapes how manufacturers develop and distribute culinary sauces, emphasizing safety and consumer transparency. Demand patterns reflect both large-scale foodservice needs and evolving household preferences for diverse flavors.
United States
Household consumers in the United States drive demand for clean-label, natural ingredients across condiment categories. Foodservice providers require consistent flavor profiles for multi-unit restaurant operations. US FDA regulations on food additives and labeling guide product innovation. California's Central Valley remains a critical hub for tomato processing, supplying a significant portion of the nation's tomato-based sauce ingredients.
India
Rising disposable incomes and extensive culinary exploration propel demand for soy-based and ethnic culinary sauces in India. The FSSAI's food safety and import requirements dictate market access and product compliance. Delhi and Mumbai's expanding restaurant chains represent major growth poles for large-format cooking bases and dips.
Mexico
Expanded production capacity in Mexico for tomato and chili-based sauces reconfigures North American supply chain dynamics. Local food safety standards ensure product quality for both domestic consumption and export markets. Sinaloa's agricultural processing centers contribute significantly to the raw material supply for sauce manufacturers.
Brazil
Culinary exploration and increasing disposable incomes stimulate demand for diverse culinary sauces within Brazil. ANVISA regulations govern food product registration and ingredient specifications. São Paulo's urban centers exhibit strong demand for both household condiments and foodservice preparations.
Germany
European consumer demand for gourmet and herb-infused culinary sauces influences product development in Germany. EFSA directives on front-of-pack nutrition labeling necessitate reformulation efforts to reduce salt and sugar. Hamburg's sophisticated food processing industry focuses on high-quality, specialty sauce production for regional and international markets.
Culinary Sauces Market Key Industry Players
Capability concentration sits with one tier of culinary sauce manufacturers focused on specialized formulations, while scale advantage sits with another tier managing vast distribution networks. The market structure exhibits a tiered consolidation, with large, diversified food companies alongside numerous niche players. Strategic archetypes include global brand powerhouses, regional specialists, and artisanal producers. Dominant competitive moves involve portfolio diversification into emerging flavor profiles and geographic expansion into high-growth consumer markets.
Global brand powerhouses like The Kraft Heinz Company leverage extensive distribution networks to maintain strong positions in household consumer segments. McCormick & Company Inc. exemplifies a specialist approach, targeting gourmet channels with herb-infused and ethnic flavor profiles. Unilever PLC operates with a broad portfolio, spanning multiple condiment categories and catering to diverse consumer preferences across various regions.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Unilever PLC |
| McCormick & Company Inc. |
| Kikkoman Corporation |
| Conagra Brands |
| Nestlé S.A. |
| Del Monte Foods Inc. |
| Hormel Foods Corporation |
| General Mills Inc. |
| Others |
Cost & Logistics Intelligence
Commodity volatility for key agricultural inputs like tomatoes and chilies determines both pricing tier spreads and supply chain shape. This volatility influences cost structures for manufacturers, affecting consumer prices for staple sauces and the margins available for specialty formulations. Supply chain resilience hinges on diversifying sourcing to mitigate regional crop failures or geopolitical disruptions.
Pricing Analysis
Geographic price spreads reflect regional input costs and market competition, with variations across continents. The dominant pricing structure for culinary sauces is a hybrid of contract-based long-term offtake for foodservice and per-unit transactional sales for household consumers. Price differentiation stems from volume scale for bulk purchases and brand premium for recognized labels. Cost compression in the ambient, shelf-stable category intensifies due to reformulation efforts to meet EFSA nutrition labeling mandates. Household consumers purchasing daily staples exhibit higher price sensitivity compared to gourmet retailers stocking artisanal products.
Supply Chain Analysis
Upstream feedstock sourcing for culinary sauces heavily depends on agricultural production centers globally. Geographic supply concentration includes Mexico for tomato and chili-based ingredients, alongside the United States for tomato processing in California's Central Valley. Raw material dependencies involve tomatoes, chilies, herbs, and soy, which are subject to climate-related and geopolitical disruptions. A structural supply chain risk is single-source vulnerability, particularly for North American markets relying on Mexican production capacity. Distribution runs through dual channels, directly to foodservice operators and via retail networks for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Culinary exploration by consumers creates a fragmentation opportunity within this market, driving demand for novel and ethnic flavor profiles. This shift enables new product categories and specialized offerings beyond traditional staples.
For Market Incumbents:Build brand equity through consistent flavor profiles and clean-label messaging to counter emerging private labels. Invest in research and development for natural preservation science to meet consumer demand for transparency, addressing the threat of synthetic additive avoidance. Expand production capacity in strategic geographies like Mexico to secure raw material access and optimize logistics for North American distribution. Leverage existing distribution networks to introduce plant-based sauce lines, capitalizing on the shift towards meat alternatives.
For New Entrants and Emerging Players:Pursue niche segments with specialized product formulations, such as functional sauces incorporating probiotics or high-antioxidant spices. Target the direct-to-consumer channel for artisanal and specialty products, which is a penetrable segment due to lower entry barriers. Develop unique flavor combinations that cater to specific dietary preferences or ethnic cuisines, using e-commerce platforms as a primary go-to-market angle. Focus on High-Pressure Processing (HPP) technology to offer premium refrigerated sauces with enhanced fresh flavor and nutritional value.
For Investors and Strategic Acquirers:EFSA nutrition labeling mandates reshape the acquisition landscape, favoring companies with clean-label formulation expertise. The long-term viability of the culinary sauces market rests on continuous flavor diversification and adaptation to evolving health trends. Acquisition targets should include specialty producers with strong intellectual property in natural preservation or unique ingredient sourcing capabilities. A signal to watch is the rate of adoption of plant-based meat alternatives, as this will drive demand for complementary sauce formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Natural Preservation R&D | Enables clean-label product development, meeting consumer demand for healthier options. |
| Expand Production in Emerging Markets | Secures raw material access and optimizes supply chains for regional demand centers. |
| Develop Plant-Based Sauce Lines | Captures growth in the expanding plant-based food and meat alternative segments. |
| Acquire Specialty Flavor Houses | Diversifies product portfolios and gains expertise in ethnic or gourmet culinary profiles. |
| Implement High-Pressure Processing (HPP) | Extends shelf life while preserving fresh flavor, enabling premium refrigerated product lines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather comprehensive market insights. Primary interviews included food technologists, procurement managers at restaurant chains, brand managers, and retail category buyers. These insights were validated against secondary data from sources like FDA and EFSA regulatory documents, FSSAI reports, and company financial filings. The methodology integrated a bottom-up assessment of market segments with a top-down analysis of macroeconomic factors.
The analytical framework calibrated historical data and projected future trends across the analysis window. Segmentation dimensions modeled included product type, application, packaging type, customer type, and the regional regulatory landscape. Compound annual growth rates (CAGRs) were derived by assessing year-on-year changes in market values and volumes, factoring in key market drivers. Industry-specific forecast inputs included agricultural crop yields for key ingredients and disposable income growth rates in emerging economies.
Sensitivities concentrate around commodity price volatility and new food safety regulations, which could necessitate forecast revisions. Forecasts reflect assumptions regarding consumer preferences and technological advancements in food processing. Cross-checking against publicly available trade data and national food consumption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Oyster Sauce Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market