
 Egg Substitutes Market | 2026-2036
Egg Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Substitutes Market Analysis
Food service buyer concentration is expanding as national bakery chains and quick-service operators consolidate purchasing decisions across multi-state networks. Cargill, Incorporated leverages its grain-processing infrastructure to supply modified starches and plant proteins for industrial-scale egg replacement. Archer-Daniels-Midland Company anchors North American distribution through its oilseed processing footprint and food ingredient logistics. Kerry Group plc differentiates via flavor-masked binding systems that replicate egg functionality in clean-label applications.
Egg substitutes comprise formulated or naturally derived ingredients designed to replicate the emulsifying, binding, leavening, and moisture-retention properties of whole eggs in food systems, typically incorporating proteins from legumes, starches from tubers, or hydrocolloids such as xanthan gum to achieve equivalent performance at specified usage rates. Commercial egg replacer formulations dominate industrial volume due to standardized functionality and extended shelf stability, while aquafaba gains traction in artisan baking and vegan product lines where foam stability and meringue replication matter. Powder forms sustain the largest share of food manufacturing procurement because of transport efficiency and dry-blend compatibility, though liquid formats are accelerating in food service channels seeking portion-control convenience.
The FDA oversees allergen labeling and GRAS determinations for novel egg substitute proteins, while the USDA sets standards for organic and plant-based claims in retail products. The EU Green Deal and EFSA novel food assessments shape which protein sources achieve market access across European member states. Stakeholders must monitor evolving clean-label thresholds and regional protein self-sufficiency mandates that will determine which formulations secure long-term supply contracts.
Market Dynamics
Industrial bakeries and quick-service chains are consolidating procurement decisions across multi-state networks, compressing supplier margins while demanding standardized functionality at scale. This buyer concentration is restructuring how egg substitute manufacturers configure production and distribution assets.
Growth Catalysts
- EU Green Deal protein diversification mandates:Industrial food manufacturers across Germany, France, and the Netherlands face binding sustainability targets that accelerate plant-based ingredient adoption in formulated products.
- Aquafaba foam stabilization technology:Artisan bakeries and vegan confectionery producers leverage chickpea-derived liquid to replicate meringue structures without albumen, expanding application scope beyond traditional replacers.
- Quick-service restaurant chain standardization:North American burger and bakery chains specify commercial egg replacers for cross-location consistency, creating pull-through demand for powder and liquid formats.
Market Restraints
- Legume protein input cost volatility:Pea and chickpea concentrate prices fluctuate with North American and Canadian pulse crop yields, squeezing margin stability for formulated replacer producers.
- Clean-label threshold stringency:EFSA novel food assessments and FDA GRAS determination timelines extend 18-36 months for emerging protein isolates, delaying commercialization of next-generation binders.
- Whole egg price competitiveness:Cage-free shell egg supply recovery in key producing regions restores conventional ingredient cost advantages in commodity baking applications.
Strategic Opportunities
- India food service channel penetration:Quick-service pizza and bakery chains in Mumbai, Bangalore, and Delhi present untapped demand for cost-optimized liquid replacers in eggless product lines.
- Precision fermentation protein convergence:Microbial-derived ovalbumin replicas, combined with plant hydrocolloids, promise functional equivalence with simplified ingredient declarations.
- USDA organic certification tailwind:Organic plant protein supply chain expansion supports premium positioning for certified egg replacers in natural retail channels.
Industry Challenges
- Food technologist specialization scarcity:Formulation expertise spanning protein chemistry, starch modification, and hydrocolloid synergies concentrates in legacy ingredient companies, constraining startup R&D velocity.
- Legacy equipment retrofit requirements:Industrial bakeries running high-speed continuous mixers require viscosity-matched replacer formulations, complicating supplier qualification protocols.
- Cross-contamination certification complexity:Allergen-free production line validation for legume-based replacers demands capital-intensive facility segregation to meet BRC and SQF standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Substitutes Market |
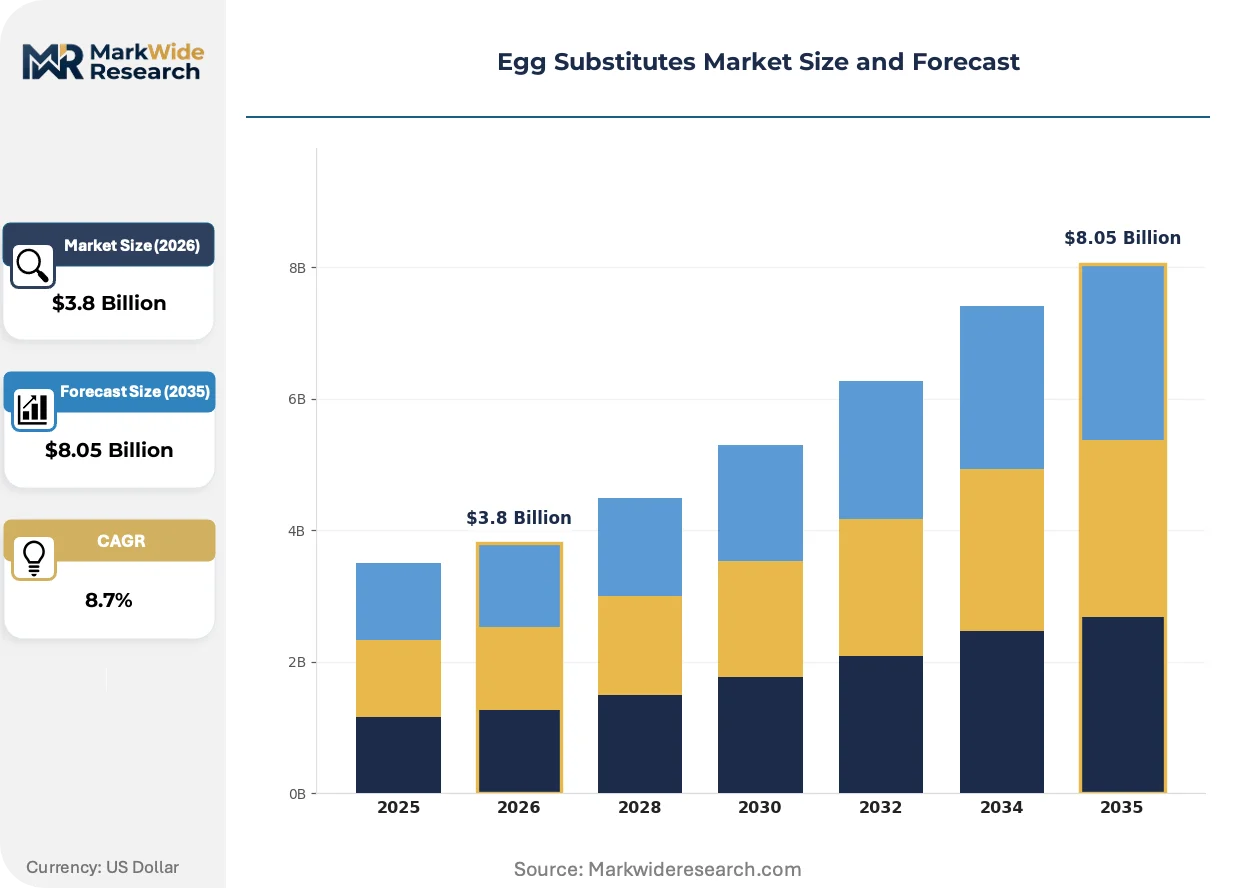
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Flaxseed Meal, Aquafaba, Commercial Egg Replacer Application: Baking, Cooking, Food Processing, Vegan Products Form: Powder, Liquid, Gel, Granule End User: Household, Food Service, Bakery, Catering |
| Companies Covered | Cargill, Incorporated, Archer-Daniels-Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Kerry Group plc, Puratos, Corbion, Eat Just, Inc., The EVERY Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Substitutes Market Emerging Trajectories
Protein extraction and texturization advances are collapsing the functional gap between plant-derived and animal-derived binding systems. Formulators now engineer multi-component systems that replicate egg performance across diverse thermal and shear conditions.
Enzyme-modified potato starch is electrifying industrial baking applications by delivering gelation temperatures and water-binding capacity that match egg yolk functionality. Large-scale bread and cake manufacturers in Germany and the United States are adopting these systems at accelerating rates, displacing traditional modified starches that required higher usage levels and produced denser crumb structures.
EFSA novel food assessment streamlining under the EU Green Deal implementation timeline is compressing market access barriers for emerging protein sources. The industrial consequence is accelerated commercialization of fava bean and lentil isolates that previously faced 24-month safety evaluation periods. German and Dutch ingredient suppliers are prioritizing these filings to secure first-mover positioning in continental bakery and confectionery channels.
Direct procurement from ingredient technology developers is displacing traditional distributor intermediaries among mid-sized North American bakery chains. These buyers now negotiate volume contracts for custom-formulated replacers, bypassing broadline foodservice distributors. The pattern is most visible in the Northeast United States, where regional bakery cooperatives aggregate purchasing power to specify proprietary binding systems.
Egg Substitutes Market Segmentation
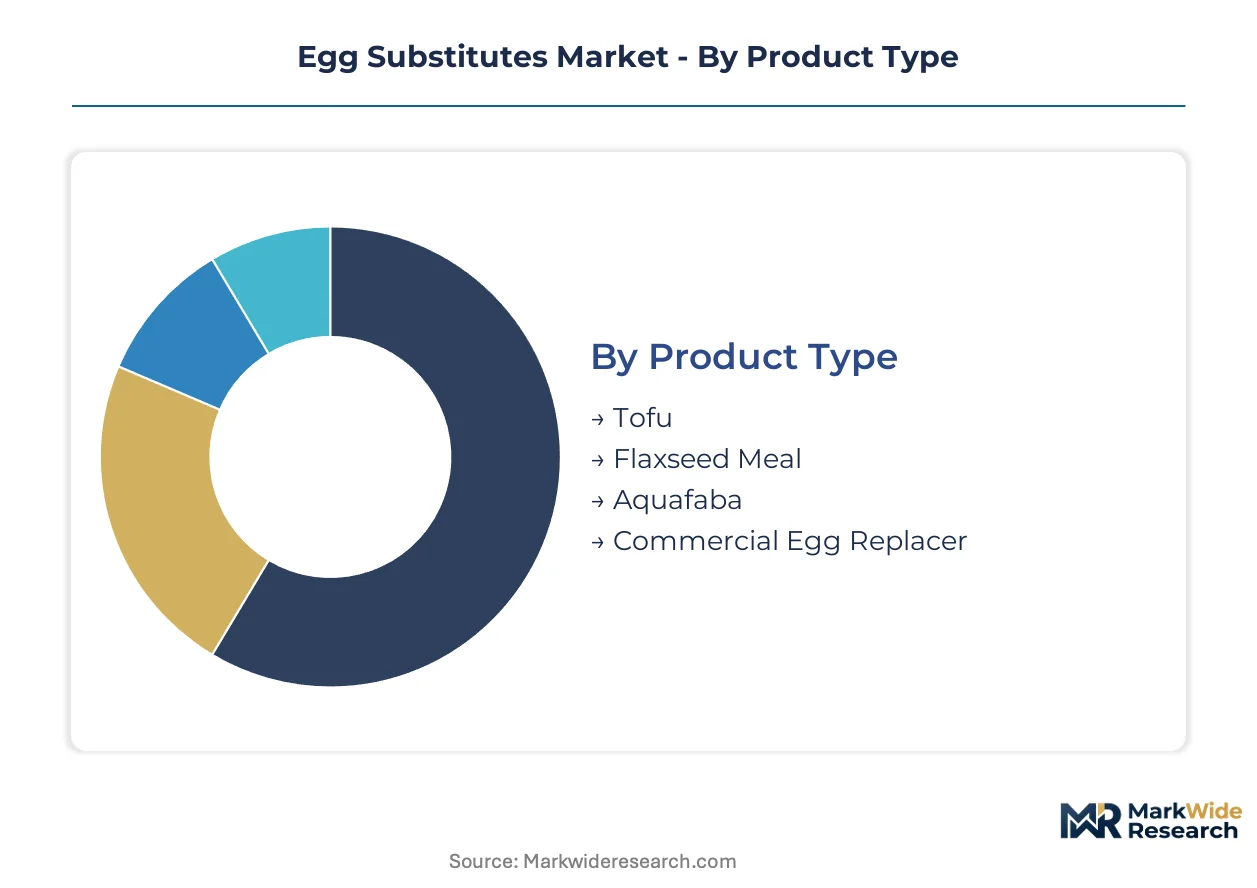
Segmentation in egg substitutes reveals how formulation chemistry, distribution channel, and end-use requirements fragment procurement patterns. Manufacturers configure production assets around specific functional specifications rather than pursuing universal formulations.
Product Type:
Protein source and processing intensity define performance boundaries across baking, confectionery, and savory applications.
- Commercial Egg Replacer:Multi-component formulations blend modified starches, plant proteins, and hydrocolloids to standardize emulsification and binding at industrial scale. Industrial bakeries in Germany specify these systems for cross-batch consistency in high-speed continuous mixers.
- Aquafaba:Chickpea-derived liquid concentrate replicates albumen foam stability for meringue and macaron applications. Artisan vegan confectionery producers in France and the Netherlands drive demand where clean-label declarations outweigh cost premiums.
- Tofu:Soy protein curd delivers moisture retention and crumb structure in dense cakes and quiches. Asian food service channels favor silken varieties for custard replication.
- Flaxseed Meal:Ground linseed provides mucilaginous binding in small-batch baking with minimal processing. Health-focused household consumers in natural retail channels sustain regional procurement.
Mature deployment sits with Commercial Egg Replacer. Newer deployment is concentrated in Aquafaba.
Application:
Thermal processing conditions and finished-product specifications determine which replacer chemistries achieve qualification.
- Baking:Cakes, breads, and pastries require leavening assistance, moisture retention, and Maillard browning replication. Quick-service bakery chains across the United States specify powder formats for cross-location standardization.
- Vegan Products:Plant-based confectionery and frozen desserts demand foam stability and emulsification without animal-derived inputs. EU Green Deal protein diversification mandates accelerate formulation adoption in German and Dutch manufacturing.
- Cooking:Scramble and omelet analogs depend on gelation temperature control and texture mimicry. Food service operators in India incorporate liquid replacers for eggless breakfast menu expansion.
- Food Processing:Mayonnaise, pasta, and processed meat applications require emulsification and binding at volume scale. Extended shelf stability drives powder procurement decisions.
Volume concentration centers on Baking. Premium positioning concentrates in Vegan Products.
Form:
Physical state dictates logistics economics, reconstitution protocols, and equipment compatibility across manufacturing and food service environments.
- Powder:Dehydrated formulations enable dry-blend compatibility, extended shelf life, and transport efficiency. Large-scale bread manufacturers in Germany and the United States anchor procurement volumes for inventory optimization.
- Liquid:Ready-to-use concentrates eliminate reconstitution steps for food service portion control. Quick-service restaurant chains in North America specify liquid formats for kitchen labor reduction.
- Gel:Pre-hydrated systems match viscosity requirements for high-shear industrial mixers without powder dispersion steps. Specialty confectionery producers adopt gel formats for precise dosing.
- Granule:Agglomerated particles improve dispersibility in ambient-temperature water. Small-batch bakery operations favor granule forms for reduced clumping.
Industrial procurement favors Powder. Food service conversion is accelerating in Liquid.
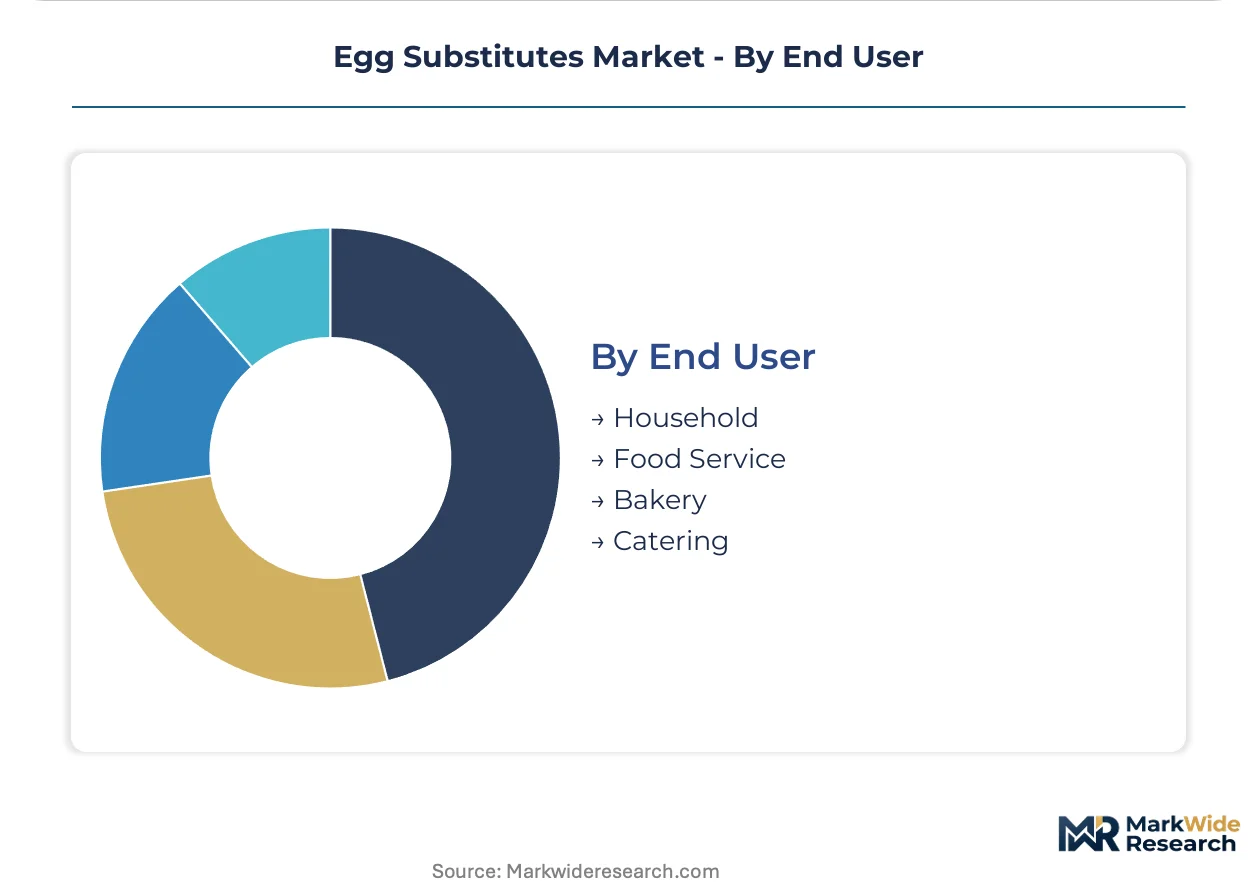
End User:
Scale, technical capability, and formulation control requirements segment buyer behavior and contract structures.
- Food Service:National quick-service chains and contract caterers consolidate purchasing across multi-location networks. Standardized functionality specifications compress supplier margins while demanding technical support.
- Bakery:Industrial-scale bread and cake manufacturers require viscosity-matched formulations for legacy equipment compatibility. Direct procurement from ingredient technology developers is displacing distributor intermediaries.
- Household:Retail consumers select based on allergen declarations, organic certification, and recipe compatibility. Natural channel positioning supports premium pricing.
- Catering:Event and institutional food service operators prioritize cost optimization and bulk handling efficiency. Volume contracts concentrate procurement with regional cooperatives.
Contract consolidation is most advanced in Food Service. Organic tailwinds are strongest in Household.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian pea and chickpea cultivation anchors North American protein feedstock supply for formulated replacers, while German industrial bakeries and Dutch ingredient technology clusters drive European formulation demand.
United States
Quick-service restaurant chains consolidate procurement across multi-state networks, demanding standardized powder and liquid formats. FDA GRAS determinations for novel protein isolates shape which formulations achieve commercial scale. Northeast regional bakery cooperatives aggregate purchasing power to specify proprietary binding systems.
Germany
Industrial bakeries drive bulk procurement of commercial egg replacers for high-speed continuous mixer compatibility. EU Green Deal protein diversification mandates accelerate plant-based ingredient adoption in formulated products. Cologne-Düsseldorf ingredient technology corridors host formulation R&D facilities serving continental bakery channels.
Netherlands
Artisan vegan confectionery producers demand aquafaba for meringue replication where clean-label declarations outweigh cost premiums. EFSA novel food assessments under EU Green Deal implementation compress market access timelines for emerging protein sources. Wageningen food innovation clusters advance enzyme-modified starch applications.
India
Quick-service pizza and bakery chains in Mumbai, Bangalore, and Delhi present untapped demand for cost-optimized liquid replacers in eggless product lines. FSSAI labeling standards govern alternative protein claims in retail and food service channels. Maharashtra and Karnataka industrial corridors concentrate contract manufacturing for bakery ingredient supply.
France
Artisan vegan confectionery producers in Paris and Lyon drive aquafaba adoption for macaron and meringue applications. EU Green Deal sustainability targets bind food manufacturers to plant-based ingredient procurement quotas. Alsace-Lorraine agricultural processing zones supply modified starches for cross-border industrial bakery supply.
Egg Substitutes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and clean-label specialization. The supplier base concentrates among grain processors with captive starch and protein extraction infrastructure, alongside ingredient technology specialists with formulation expertise. Three archetypes dominate: diversified agricultural processors, specialized hydrocolloid and protein blenders, and biotechnology-driven novel protein developers. Capacity expansion in North American pulse processing and strategic partnerships between ingredient developers and industrial bakeries represent the primary competitive vectors.
Within the agricultural processor tier, Cargill, Incorporated and Archer-Daniels-Midland Company exemplify scale-driven supply positions anchored in grain-processing infrastructure. Kerry Group plc occupies a specialized position among flavor-masked binding system developers. These three entities represent divergent strategic anchors: captive raw material control, distribution network breadth, and application-specific formulation expertise respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Kerry Group plc |
| Puratos |
| Corbion |
| Eat Just, Inc. |
| The EVERY Company |
| Others |
Supply Flow & Price Mechanics
Clean-label certification tiers bifurcate procurement economics between artisan vegan confectionery channels and industrial bakery commodity supply, with EU organic and BRC allergen-free validations commanding formulation premiums while unbranded modified starch systems compress margins in high-volume bread manufacturing.
Pricing Analysis
Technical service bundling separates premium formulation partnerships from transactional commodity supply, with enzyme-modified potato starch systems including viscosity calibration support for legacy mixer compatibility while standard replacers ship unassisted. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded levels tracks functionality depth and documentation burden. Pricing pressure stems from quick-service chain procurement consolidation demanding cross-location standardization at volume discounts. Industrial bakery buyers exhibit highest price sensitivity due to thin commodity margins, while artisan vegan confectioners accept premiums for foam-stability guarantees.
Supply Chain Analysis
Direct-to-industrial-bakery channels handle German and United States hyperscale buyer demand, bypassing traditional distributor intermediaries for custom-formulated binding systems. Raw material supply concentrates in Canadian pea and chickpea cultivation, German modified starch processing, and Dutch hydrocolloid refinement. Formulated replacer production draws from North American pulse protein isolation, European enzyme modification, and Asian aquafaba concentration. Single-source vulnerability sits with Canadian pulse crop yields exposed to prairie drought cycles. Distribution runs through regional ingredient technology developers with captive formulation laboratories serving continental bakery cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial bakery buyer concentration is forcing supplier consolidation, with multi-state procurement standardization eliminating sub-scale formulation houses unable to meet technical service and volume consistency thresholds.
For Market Incumbents: Anchor market position through backward integration into Canadian pulse protein extraction and German enzyme modification capacity, securing captive supply of pea isolate and potato starch hydrocolloids against input cost volatility from climate-stressed prairie yields. Deepen technical service moats by embedding food technologists within quick-service chain R&D facilities, creating switching costs through proprietary viscosity-matched formulations for legacy high-speed mixer infrastructure. For New Entrants and Emerging Players: Precision fermentation-derived ovalbumin replicas offer a technology-first wedge into clean-label vegan confectionery channels where EFSA novel food timelines have stalled incumbent plant protein diversification. Target India's quick-service pizza and bakery chains in Mumbai and Bangalore with cost-optimized liquid replacers for eggless menu expansion, exploiting underdeveloped local formulation expertise and FSSAI labeling clarity gaps. Pursue direct procurement relationships with regional bakery cooperatives, mirroring Northeast United States cooperative aggregation models. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap hydrocolloid blenders possessing enzyme modification capabilities and existing BRC-certified allergen-free production lines, given EU Green Deal protein diversification mandates accelerating plant-based procurement quotas across German and Dutch manufacturing. Acquisition screening should prioritize targets with validated high-shear mixer compatibility and embedded quick-service chain technical relationships. Monitor EFSA novel food approval velocity for fava bean and lentil isolates as inflection indicator for next-generation protein source commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Protein Extraction | Captive Canadian pea and chickpea concentrate supply insulates margin stability against prairie yield volatility. |
| Embedded Technical Service Partnerships | Resident food technologists at quick-service chain R&D facilities create proprietary formulation switching costs. |
| EFSA Novel Food Pre-Approval Investment | Early fava bean and lentil isolate filings secure first-mover positioning in continental bakery channels. |
| Precision Fermentation Protein Convergence | Microbial-derived ovalbumin combined with plant hydrocolloids promises simplified clean-label declarations. |
| Regional Cooperative Procurement Aggregation | Northeast United States bakery cooperative models enable direct volume contracts bypassing distributor intermediaries. |
Methodological Framework
Document review covered FDA GRAS determination filings, EFSA novel food assessment registers, EU Green Deal implementation directives, and USDA organic certification standards, complemented by interviews with industrial bakery procurement directors, quick-service chain food technologists, hydrocolloid formulation scientists, and pulse protein extraction plant managers. Secondary validation drew from customs trade data for modified starch and plant protein flows, SEC 10-K disclosures from agricultural processors, and German industrial bakery association production surveys. Bottom-up demand modeling triangulated against top-down protein substitution rate assumptions across baking and confectionery applications.
Segment-level value outputs tracked commercial egg replacer, aquafaba, tofu, and flaxseed meal chemistries across powder, liquid, gel, and granule formats, with application splits for baking, vegan products, cooking, and food processing channels. Modeled dimensions included protein source intensity, thermal processing compatibility, and end-user scale tier from household retail through industrial bakery. CAGRs derived from elasticity-adjusted substitution curves for cage-free shell egg price competitiveness and EU regulatory procurement mandate enforcement timelines. Forecast inputs incorporated Canadian prairie yield variance bands and EFSA assessment duration distributions.
Several conditions sit outside the modeled scope, including precision fermentation protein cost curves reaching commercial parity, abrupt FSSAI labeling standard revisions in India, and catastrophic single-season drought across North American pulse growing regions. Forecasts reflect documented assumptions regarding EU Green Deal binding target enforcement and quick-service chain standardization adoption velocity. Practitioners should monitor EFSA novel food approval cadence, Canadian prairie soil moisture indices, and quick-service chain RFP consolidation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Low Carbs Vegan Food Market