
 Asia-Pacific Fat Replacers Market | 2026-2036
Asia-Pacific Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fat Replacers Market Outlook
Plant-derived proteins and modified starches are recalibrating cost structures for reduced-fat dairy and bakery applications across Asia-Pacific. Kerry Group plc leverages its regional flavor systems expertise to anchor reformulation partnerships with multinational food manufacturers. Cargill Inc. competes through its integrated supply chain from oilseed processing to specialty ingredient output. Tate & Lyle PLC differentiates with soluble fiber technologies that restore mouthfeel in low-fat confectionery.
Asia-Pacific fat replacers comprise functional ingredients engineered to mimic the physicochemical properties of dietary fats—mouthfeel, creaminess, and moisture retention—while delivering substantially lower caloric density, typically through modified carbohydrate polymers, protein microparticulates, or lipid analogues structured to resist digestive lipase activity. These ingredients primarily serve food manufacturers seeking to reformulate processed foods without sacrificing sensory acceptance or shelf stability. Carbohydrate-based replacers dominate current volume owing to mature supply chains and lower unit costs, while protein-based variants capture accelerating interest in premium dairy alternatives where label simplicity drives purchase decisions. Fiber-based systems occupy a specialized niche in bakery and meat applications where water-binding capacity intersects with digestive health positioning.
FSSAI in India enforces progressively stricter nutrient profiling for packaged foods, compelling domestic manufacturers to validate fat reduction claims through reformulation rather than labeling alone. China's SAMR and GB standards framework governs ingredient safety assessments and nutritional claims for reduced-fat products entering retail channels. Japan's Ministry of Health, Labour and Welfare maintains distinct specifications for fat-modified foods that influence export-oriented formulation decisions. Stakeholders must monitor divergent national approval pathways for novel protein and fiber ingredients, as regulatory lag between jurisdictions threatens to fragment product portfolios and delay regional scale-up.
Market Dynamics
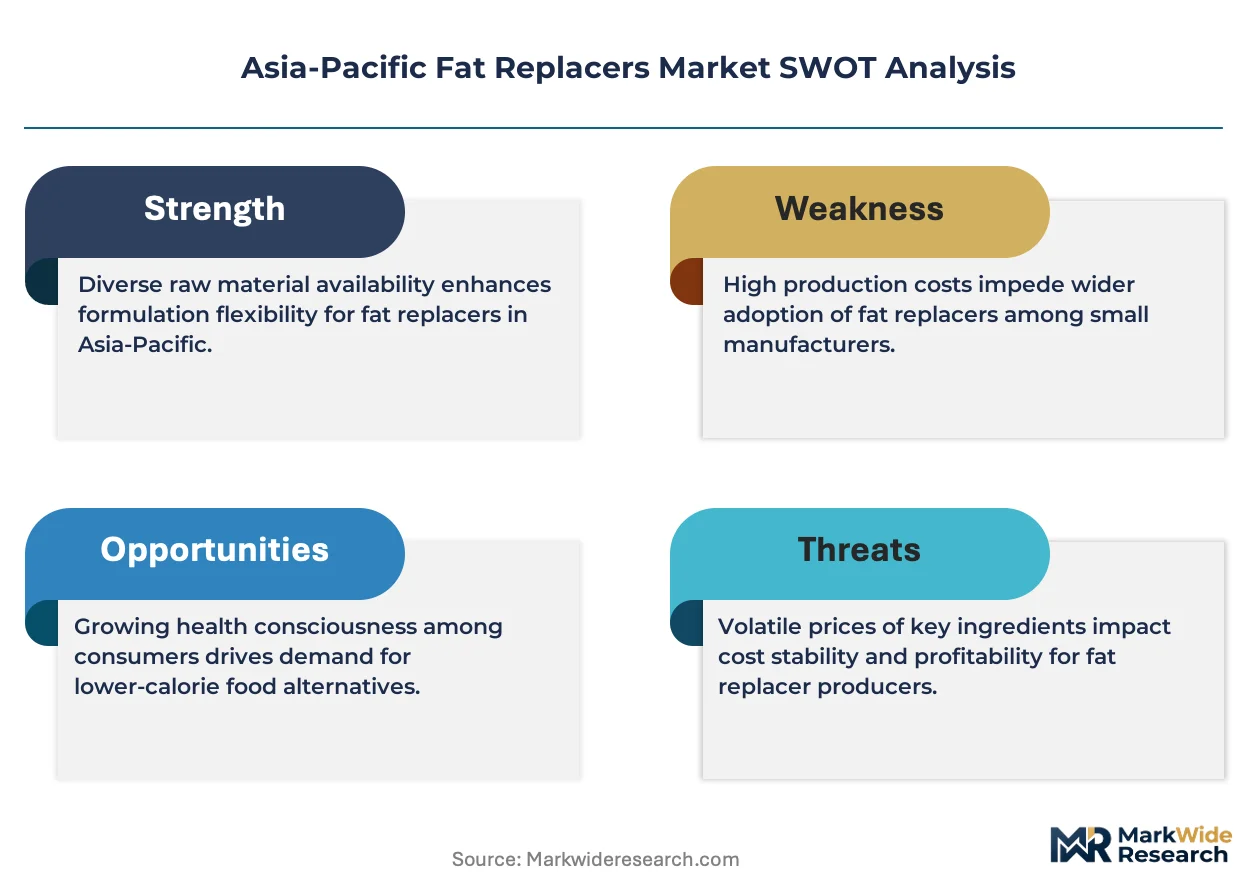
India's FSSAI front-of-pack labeling rules and China's GB standards for reduced-fat claims are forcing reformulation investments that compress margins while raising technical barriers to market entry across Asia-Pacific.
Growth Catalysts
- Carbohydrate-based replacer maturation:Modified starches from cassava and tapioca supply chains in Thailand and Vietnam achieve cost parity with conventional fats in bakery applications. Thai processors now export pre-gelatinized starches to Indian biscuit manufacturers at scale.
- Japan's Ministry of Health, Labour and Welfare specifications:Export-oriented Japanese food manufacturers demand fat-modified formulations that satisfy domestic labeling requirements, pulling premium protein-based replacer development across the region.
- Eastern China manufacturing corridor concentration:Dairy processors in Jiangsu and Zhejiang provinces cluster near flavor houses and ingredient distributors, accelerating reformulation cycle times for reduced-fat yogurt and ice cream lines.
Market Restraints
- Palm oil price volatility:Fat replacer formulations still benchmark against palm olein costs, and Malaysian supply disruptions transmit directly to modified lipid analogue pricing power.
- Protein microparticulate supply concentration:Whey protein isolate and pea protein concentrate production clusters in New Zealand and Australia, exposing Indian and Southeast Asian formulators to currency and shipping cost swings.
- Moisture retention ceiling in high-heat applications:Carbohydrate-based systems fail above 180°C frying temperatures, blocking penetration into Asia-Pacific snack food segments where deep-frying dominates.
Strategic Opportunities
- Vietnam's processed dairy underpenetration:Refrigerated distribution expansion in Ho Chi Minh City and Hanoi creates first-mover space for reduced-fat cheese and spreadable cream products using localized starch blends.
- Indonesia's BPOM nutrition labeling evolution:Pending front-of-pack regulations will mandate saturated fat disclosure, preemptive adoption by multinational manufacturers creates demand for proven reformulation partnerships.
- Soluble fiber and protein convergence:Tate & Lyle's resistant maltodextrin technologies combined with rice protein microparticulates enable clean-label positioning in Chinese premium confectionery channels.
Industry Challenges
- Sensory scientist scarcity:Asia-Pacific food science programs produce insufficient trained formulators who can correlate instrumental texture analysis with consumer mouthfeel perception in reduced-fat dairy.
- Dual certification timelines:Novel fiber ingredients require sequential FSSAI approval in India and SAMR registration in China, stretching product launch schedules across incompatible documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fat Replacers Market |
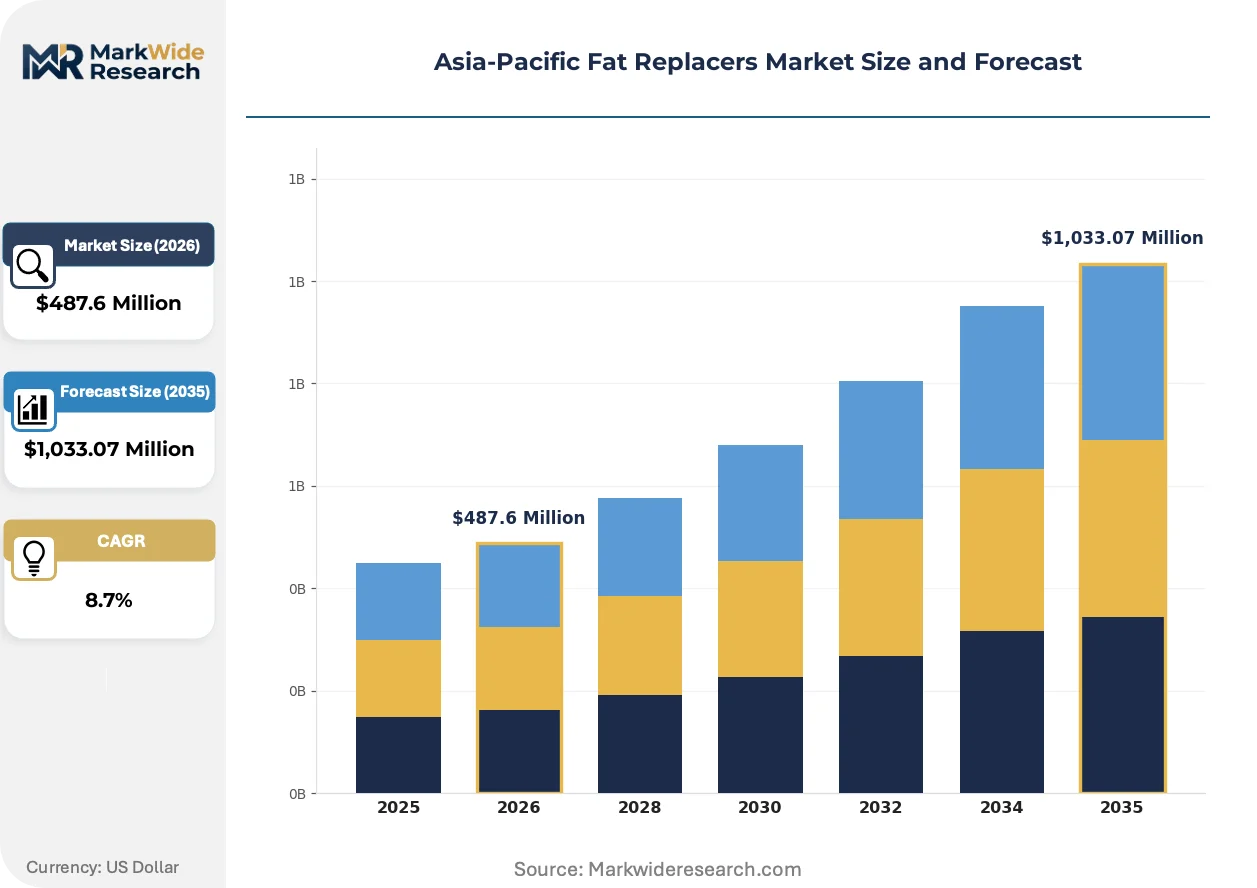
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbohydrate-based, Protein-based, Fat-based, Fiber-based Application: Dairy Products, Bakery Goods, Meat Products, Confectionery End User: Food Manufacturers, Retailers, Food Service Providers, Households Form: Liquid, Powder, Emulsion, Granule |
| Companies Covered | Kerry Group plc, BENEO, Cargill Inc., Archer Daniels Midland Company, Wilmar International Ltd, Tate & Lyle PLC, CP Kelco U.S., Inc., Dupont, Ingredion Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fat Replacers Market Strategic Shifts
Ingredient suppliers and food manufacturers across Asia-Pacific are converging on hybrid systems that combine multiple fat-mimicking mechanisms rather than single-ingredient substitution, reshaping R&D priorities and procurement specifications simultaneously.
Enzymatically modified rice starches are integrating lipid-like crystallization behavior with protein-stabilized emulsion structures to replicate the melting profile of milk fat in ice cream. Chinese dairy processors in the Yangtze River Delta are adopting these systems at pilot scale ahead of anticipated GB standard tightening. The technology is integrating formerly separate carbohydrate and protein supply chains into unified ingredient platforms that reduce supplier count and simplify quality assurance protocols.
FSSAI's proposed star-rating system for packaged foods creates immediate compliance pressure on Indian snack and confectionery manufacturers with high saturated fat baselines. Domestic reformulation service providers are building dedicated application laboratories in Mumbai and Delhi to accelerate client validation timelines. Premium biscuit and chocolate categories face the steepest rating downgrades, driving concentrated investment in oleogel-based shortening alternatives that maintain shelf stability without hydrogenation.
Direct technical partnerships between ingredient suppliers and retail private-label programs are displacing traditional distributor-mediated procurement in Southeast Asian markets. Thai and Indonesian supermarket chains now embed formulation scientists within supplier qualification processes, compressing switching cycles from annual to quarterly reviews. This pattern concentrates most visibly in fresh dairy and chilled desserts where margin pressure from discounters demands rapid cost-engineering without sensory degradation.
Asia-Pacific Fat Replacers Market Segmentation
Ingredient selection in Asia-Pacific fat replacers hinges on capital deployment for specialized processing equipment and regulatory validation infrastructure. Manufacturers must align segment-specific investments with reformulation timelines driven by FSSAI and SAMR compliance windows.
Product Type:
Capital intensity varies sharply across production technologies, with protein microparticulation requiring the most substantial upfront equipment outlays.
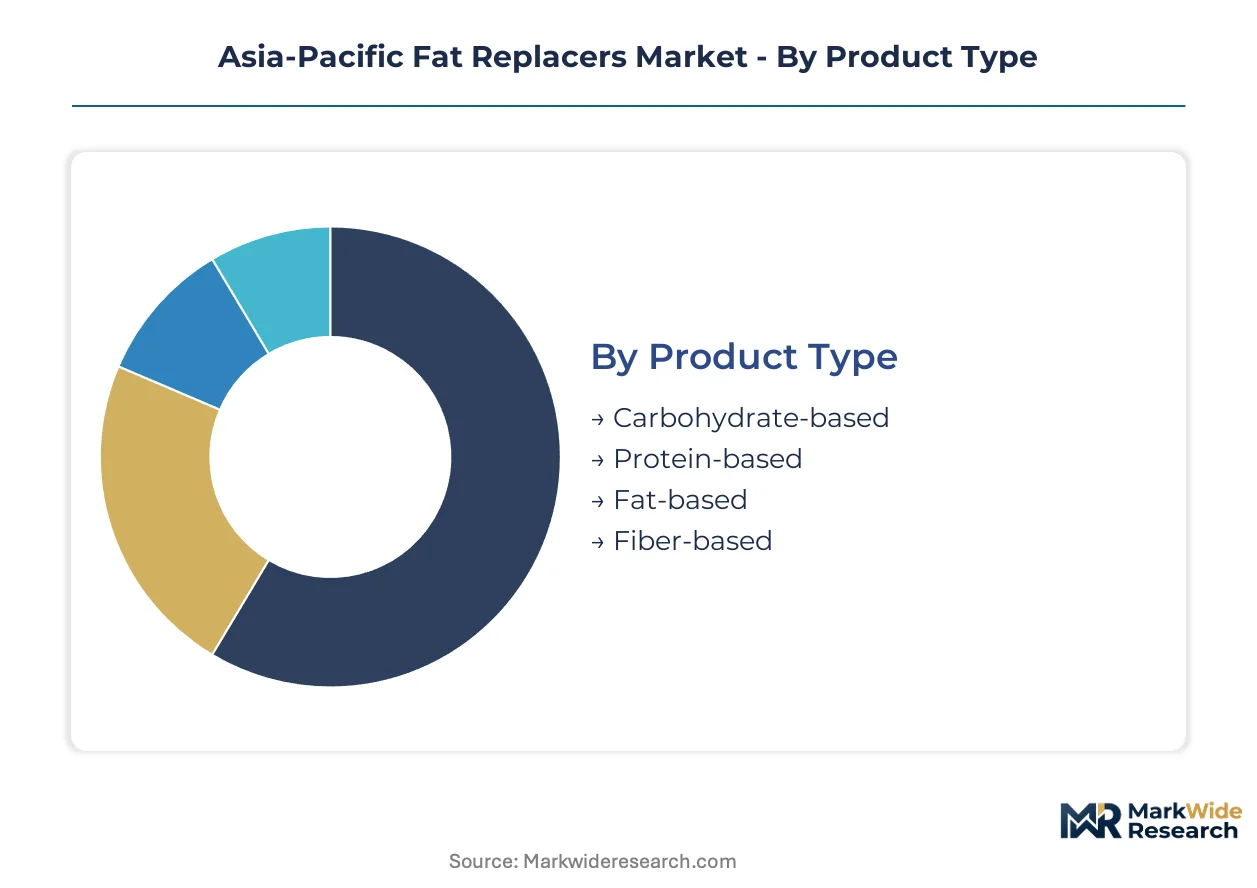
- Carbohydrate-based:Modified starches and maltodextrins dominate volume through mature cassava and tapioca supply chains in Thailand and Vietnam. Indian biscuit manufacturers absorb pre-gelatinized starch shipments at scale, though formulations fail above 180°C frying temperatures.
- Protein-based:Whey and pea protein microparticulates demand spray-drying and homogenization assets that concentrate investment in New Zealand and Australian processing facilities. Premium dairy alternatives in China's Yangtze River Delta pull regional development despite currency exposure for Southeast Asian formulators.
- Fat-based:Structured lipid analogues and oleogels require enzymatic interesterification capacity that benchmarks against palm olein pricing volatility.
- Fiber-based:Soluble fiber systems occupy specialized niches in bakery and meat applications where water-binding intersects with digestive health positioning.
Most installed capacity flows through carbohydrate-based systems. Expansion is steepest in protein-based variants.
Application:
End-use concentration determines R&D resource allocation, with dairy commanding disproportionate sensory science investment.
- Dairy Products:Reduced-fat yogurt and ice cream lines in Jiangsu and Zhejiang provinces cluster near flavor houses, accelerating reformulation cycles. Japanese export specifications pull premium protein-based development.
- Bakery Goods:Indian biscuit and bread manufacturers face immediate FSSAI star-rating pressure, driving oleogel-based shortening adoption without hydrogenation.
- Meat Products:Processed meat applications in Vietnam and Indonesia utilize fiber-based systems for moisture retention and fat mimicry.
- Confectionery:Premium chocolate categories face steepest rating downgrades, demanding clean-label positioning through resistant maltodextrin technologies.
Technical partnerships concentrate in dairy applications. Reformulation urgency peaks in bakery goods.
End User:
Procurement sophistication separates volume tiers, with multinational food manufacturers demanding integrated supplier relationships.
- Food Manufacturers:Multinational processors in eastern China and western India anchor demand through direct technical partnerships with ingredient suppliers.
- Retailers:Thai and Indonesian supermarket chains embed formulation scientists in supplier qualification, compressing review cycles to quarterly intervals.
- Food Service Providers:Chained foodservice operations in Vietnam's expanding Ho Chi Minh City corridor create first-mover space for reduced-fat spreadable products.
- Households:Direct consumer purchase remains minimal due to limited retail distribution of pure ingredient formats.
Contract volume concentrates with food manufacturers. Relationship intensity is climbing fastest among retailers.
Form:
Handling characteristics and shelf stability requirements shape logistics investment across distribution networks.
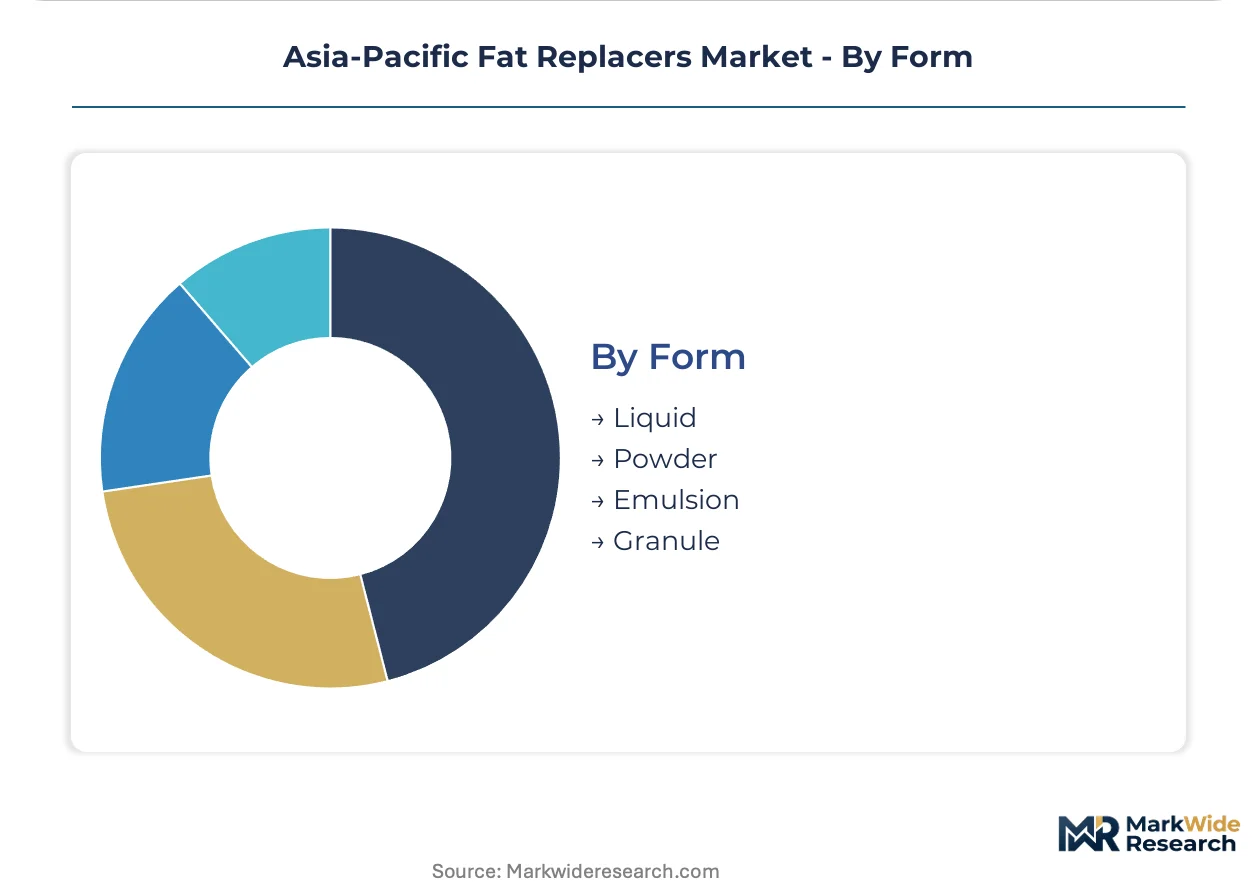
- Liquid:Pumpable emulsion concentrates suit high-volume dairy processing in clustered manufacturing corridors.
- Powder:Spray-dried formats dominate export logistics from Thai and Vietnamese starch processors to Indian formulators.
- Emulsion:Pre-stabilized systems reduce in-house processing steps for mid-tier bakery manufacturers.
- Granule:Free-flowing formats address specific meat and confectionery applications requiring controlled hydration rates.
Distribution infrastructure favors powder forms. Functional sophistication is advancing most quickly in emulsion systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The eastern China manufacturing corridor anchors Asia-Pacific fat replacer demand through concentrated dairy and bakery reformulation activity. India's western processed food belt and Japan's export-oriented food manufacturers pull differentiated ingredient specifications across the region.
China
Jiangsu and Zhejiang provinces cluster reduced-fat yogurt and ice cream processors near flavor houses and ingredient distributors. SAMR's GB standards for reduced-fat claims mandate validated reformulation documentation for retail channel entry. Yangtze River Delta dairy manufacturers pilot enzymatically modified rice starch systems ahead of anticipated regulatory tightening.
India
Maharashtra and Gujarat host the densest concentration of biscuit and bread manufacturers facing FSSAI star-rating compliance pressure. FSSAI front-of-pack labeling rules compel domestic processors to validate fat reduction through reformulation rather than labeling adjustments alone. Mumbai and Delhi application laboratories accelerate client validation timelines for oleogel-based shortening alternatives.
Japan
Export-oriented food manufacturers in Kanto and Kansai regions demand fat-modified formulations satisfying domestic Ministry of Health, Labour and Welfare specifications. METI-aligned quality frameworks influence regional ingredient sourcing decisions for premium protein-based replacer development. Osaka-based processors pull advanced microparticulate technologies into regional supply chains.
Vietnam
Ho Chi Minh City and Hanoi refrigerated distribution expansion creates first-mover space for reduced-fat cheese and spreadable cream products. General food safety administration oversight of processed dairy categories intensifies as cold chain infrastructure matures. Localized starch blend suppliers position near emerging dairy processing clusters in the southern manufacturing corridor.
Indonesia
Jakarta and Surabaya multinational manufacturing facilities anticipate BPOM front-of-pack nutrition labeling mandates for saturated fat disclosure. Pending regulatory evolution drives preemptive reformulation partnerships with proven ingredient suppliers. Indonesian supermarket chains embed formulation scientists within supplier qualification processes, compressing review cycles.
Asia-Pacific Fat Replacers Market Competitive Environment
Strategic partnerships dominate the current landscape as ingredient suppliers embed technical resources within food manufacturer R&D facilities. The vendor base separates into three tiers: multinational integrated suppliers with regional flavor systems expertise, specialized carbohydrate processors anchored in Southeast Asian starch supply chains, and emerging protein technology developers serving premium dairy alternatives. Market structure favors direct technical collaboration over distributor-mediated procurement, particularly in chilled dairy and bakery segments. Capacity expansion and portfolio diversification constitute the primary competitive vectors as participants build application laboratories and acquire complementary texture modification capabilities.
Within the integrated multinational tier, Kerry Group plc and Cargill Inc. occupy positions defined by regional formulation infrastructure and supply chain control from raw material processing through specialty ingredient output. Tate & Lyle PLC exemplifies the technology-differentiated archetype through soluble fiber and resistant maltodextrin platforms. Southeast Asian market presence concentrates among Archer Daniels Midland Company and Wilmar International Ltd, with the latter's Singapore-based structure reflecting palm oil and oleochemical processing origins. Ingredion Incorporated and BENEO represent the carbohydrate-specialist segment with established modified starch supply relationships into Indian and Chinese bakery manufacturers.
| Leading Market Players |
|---|
| Kerry Group plc |
| BENEO |
| Cargill Inc. |
| Archer Daniels Midland Company |
| Wilmar International Ltd |
| Tate & Lyle PLC |
| CP Kelco U.S., Inc. |
| Dupont |
| Ingredion Incorporated |
| Others |
Value Chain & Pricing Dynamics
FSSAI star-rating compliance pressure on Indian biscuit manufacturers forces multi-supplier qualification for oleogel-based shortenings, compressing procurement timelines and fragmenting volume across competing starch and protein microparticulate sources.
Pricing Analysis
Input-cost pass-through from palm olein benchmarks governs modified lipid analogue quotations, with enzymatic interesterification premiums widening during Malaysian supply disruptions. Three-tier pricing structure across premium protein microparticulates, standard modified starches, and economy maltodextrin grades reflects certification investment and spray-drying asset intensity. Cost compression in carbohydrate-based systems intensifies as Thai cassava processors expand pre-gelatinized starch output. Mid-tier bakery manufacturers exhibit highest price sensitivity, while multinational dairy processors in Jiangsu absorb premium protein premiums for Japanese export compliance.
Supply Chain Analysis
Dual-sourcing requirements from multinational food manufacturers mandate simultaneous qualification of Thai cassava starch processors and Vietnamese tapioca suppliers for Indian biscuit reformulation programs. Raw material flows draw from Malaysian palm olein refineries, New Zealand whey protein isolate facilities, and Australian pea protein concentrate plants. Single-source vulnerability concentrates in spray-drying assets for microparticulate production, exposing Southeast Asian formulators to currency and shipping cost swings. Distribution runs through direct technical partnerships with clustered dairy processors in the Yangtze River Delta and western Indian manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific fat replacers rests on enzymatic modification technology maturation that collapses protein-carbohydrate hybrid production costs while premium clean-label positioning captures FSSAI and SAMR compliance premiums.
For Market Incumbents: Acquire spray-drying and homogenization assets in New Zealand and Australia to secure whey protein isolate supply continuity against emerging pea protein disruptors. Anchor formulation partnerships with Yangtze River Delta dairy processors ahead of anticipated GB standard tightening. Certification investment in FSSAI and SAMR dual-approval documentation capabilities defends against regulatory lag fragmentation. For New Entrants and Emerging Players: BPOM front-of-pack nutrition labeling evolution in Indonesia opens a window for preemptive reformulation partnerships with Jakarta and Surabaya multinational manufacturing facilities. Target Vietnam's underpenetrated processed dairy segment in Ho Chi Minh City and Hanoi where refrigerated distribution expansion outpaces localized ingredient supply. Embed application scientists within Thai and Indonesian supermarket chain procurement teams to compress supplier qualification cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with Southeast Asian carbohydrate-specialist processors possessing backward integration into cassava and tapioca cultivation. Long-term viability over the mid-decade horizon favors participants with enzymatic modification capabilities spanning protein and starch platforms. Monitor FSSAI star-rating implementation velocity as inflection indicator for accelerated reformulation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Technology Acquisition | Consolidates protein and starch supply chains into unified ingredient platforms for dairy applications. |
| Dual-Certification Application Laboratory Buildout | Compresses FSSAI and SAMR approval timelines for novel fiber and protein ingredients. |
| Direct Technical Partnership with Retail Private-Label Programs | Displaces distributor-mediated procurement in Thai and Indonesian supermarket chains. |
| Backward Integration into Cassava Cultivation | Secures cost parity for modified starches against palm olein benchmarks in bakery applications. |
| Hybrid System R&D Convergence | Combines resistant maltodextrin and rice protein microparticulates for Chinese premium confectionery channels. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food manufacturer R&D directors, ingredient supplier technical sales leads, FSSAI regulatory consultants, SAMR registration specialists, and Southeast Asian supermarket chain procurement managers with secondary validation through customs trade data, GB standards documentation, FSSAI notification records, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling from application-level consumption and top-down triangulation against regional processed food production statistics anchored the analytical framework.
Comparable-period anchoring linked projection assumptions to historical reformulation cycle observations across the modeling period. Segmentation dimensions spanned ingredient type, application category, end-user procurement sophistication, and physical form, with regional regulatory cluster effects modeled separately. CAGRs derived from slope-consistent growth trajectory analysis incorporating enzymatic technology adoption curves and front-of-pack labeling implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under palm oil supply disruption scenarios or divergent national approval timelines for novel protein ingredients. Deviation in FSSAI star-rating enforcement velocity or BPOM mandate finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Synthetic Food Market