
 Microalgae Based Products Market | 2026-2036
Microalgae Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Microalgae Based Products Market Intelligence
Expanded cultivation capacity in Southeast Asian countries like Vietnam and Thailand is reshaping the supply landscape for spirulina and chlorella. This shift influences raw material availability and cost structures for downstream processors. Cyanotech Corporation leverages its specialized production of high-value astaxanthin from its facilities in Hawaii. DIC Corporation sustains its market leadership through extensive spirulina cultivation and a global distribution network, while Corbion N.V. focuses on fermentation-based algae ingredients for food and animal feed applications.
Microalgae based products originate from microscopic aquatic organisms cultivated for their rich composition of proteins, lipids, carotenoids, and other bioactive compounds. These products are typically processed into powders or oils, with key compounds like omega-3 fatty acids, astaxanthin, and phycocyanin extracted for specific commercial purposes. Spirulina and chlorella products dominate market volume, driven by their established use in dietary supplements and animal feed. Higher-margin opportunities, however, reside in purified extracts like astaxanthin, which command premium pricing in nutraceutical and cosmetic applications.
Regulatory frameworks, including the FDA's GRAS notifications in the United States and the EFSA's novel food regulations in Europe, govern market access for food and supplement ingredients. In Asia, bodies like India's FSSAI and China's SAMR set standards for algal-based food products, impacting formulation and labeling. Future success for producers depends on navigating these diverse international regulations while scaling production to meet cost targets for mainstream food and feed applications.
Market Dynamics
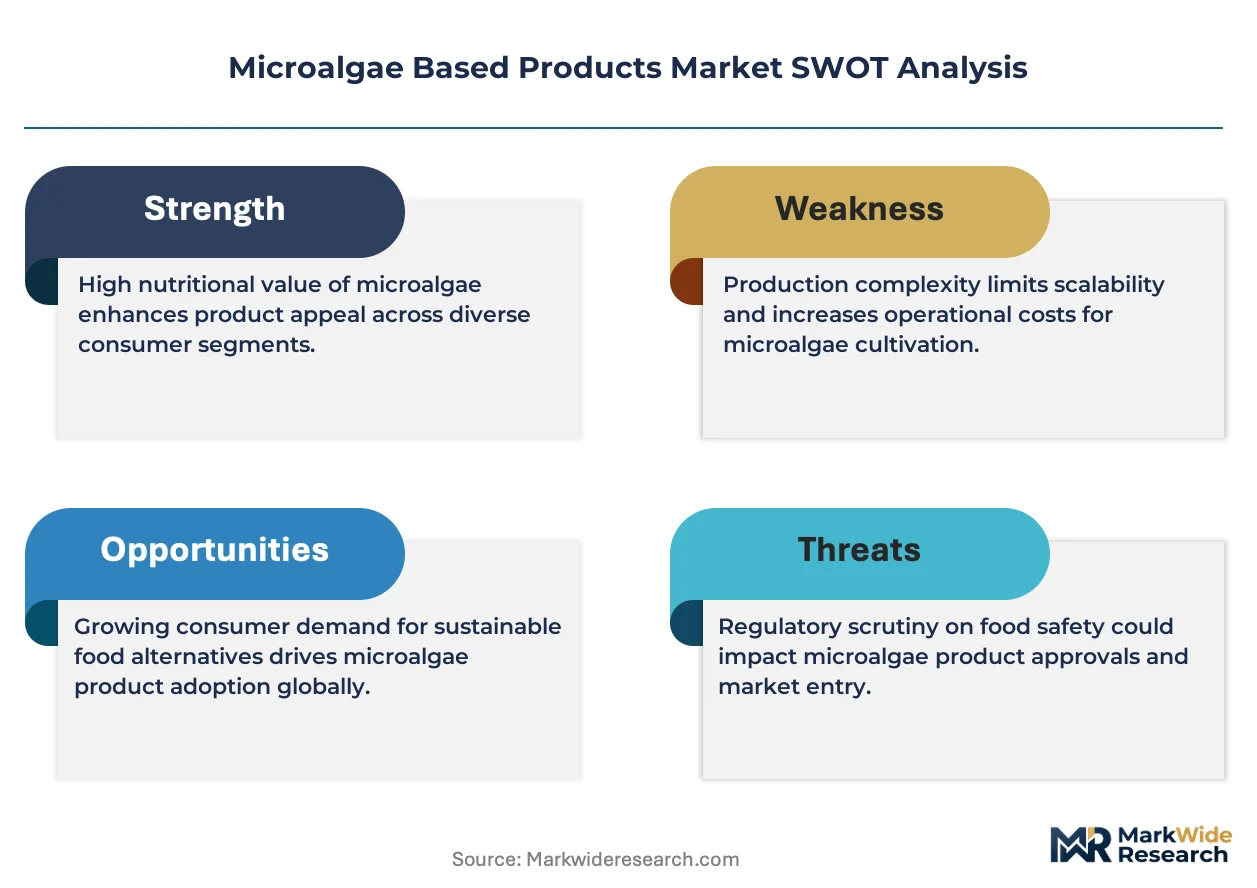
The central dynamic in the microalgae based products market is the bifurcation between high-volume, low-margin commodities like spirulina for feed and high-value, low-volume extracts like astaxanthin for nutraceuticals. This split influences investment in cultivation technology and downstream processing capabilities.
Growth Catalysts
- Regulatory Approvals:The U.S. FDA's Generally Recognized as Safe (GRAS) notifications and the European Food Safety Authority's (EFSA) novel food authorizations are clearing pathways for new algal ingredients in food and dietary supplements, boosting manufacturer confidence.
- Cultivation Technology:Advances in closed-loop photobioreactors and fermentation techniques are improving yield, purity, and consistency of microalgae biomass, enabling production of higher-grade ingredients for cosmetic and pharmaceutical applications.
- Consumer Demand for Plant-Based Ingredients:Strong consumer preference for vegan and sustainable sources of protein and omega-3 fatty acids is driving adoption of chlorella and spirulina in the plant-based food sector across North America and Europe.
Market Restraints
- High Production Costs:The significant capital expenditure and operational costs associated with advanced cultivation systems like photobioreactors limit price competitiveness against conventional products such as fish oil or synthetic colorants.
- Technical Cultivation Hurdles:Open-pond cultivation systems, while cost-effective, are susceptible to contamination from bacteria, heavy metals, and other algal species, posing risks to product quality and safety for human consumption.
- Competition from Substitutes:Microalgae-derived omega-3s face intense competition from the well-established fish oil industry, which benefits from mature supply chains, economies of scale, and broad consumer recognition.
Strategic Opportunities
- Biofuel and Bioplastic Development:Research into lipid-rich algal strains presents a long-term opportunity to produce sustainable aviation fuels (SAF) and biodegradable plastics, aligning with corporate and governmental decarbonization goals.
- Aquaculture Feed Market Penetration:Untapped demand exists in the aquaculture sectors of Southeast Asian and Latin American countries for algae-based feeds that improve fish health and coloration, offering a sustainable alternative to fishmeal.
- Strain Development via Genetic Engineering:Applying gene-editing tools like CRISPR to optimize algal strains for higher yields of specific compounds, such as proteins or carotenoids, can create proprietary, high-performance ingredients.
Industry Challenges
- Lack of Ingredient Standardization:The absence of globally harmonized standards for testing and labeling the potency of active compounds like phycocyanin or astaxanthin creates market confusion and challenges for quality control.
- Scaling Production Economically:Transitioning from pilot-scale to commercial-scale production while maintaining low costs per unit remains a primary operational hurdle, particularly for ingredients targeting the mass-market food industry.
- Navigating International Regulations:Producers face significant complexity and delays in securing approvals for novel ingredients across disparate regulatory bodies like China's SAMR and Brazil's ANVISA, slowing market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microalgae Based Products Market |
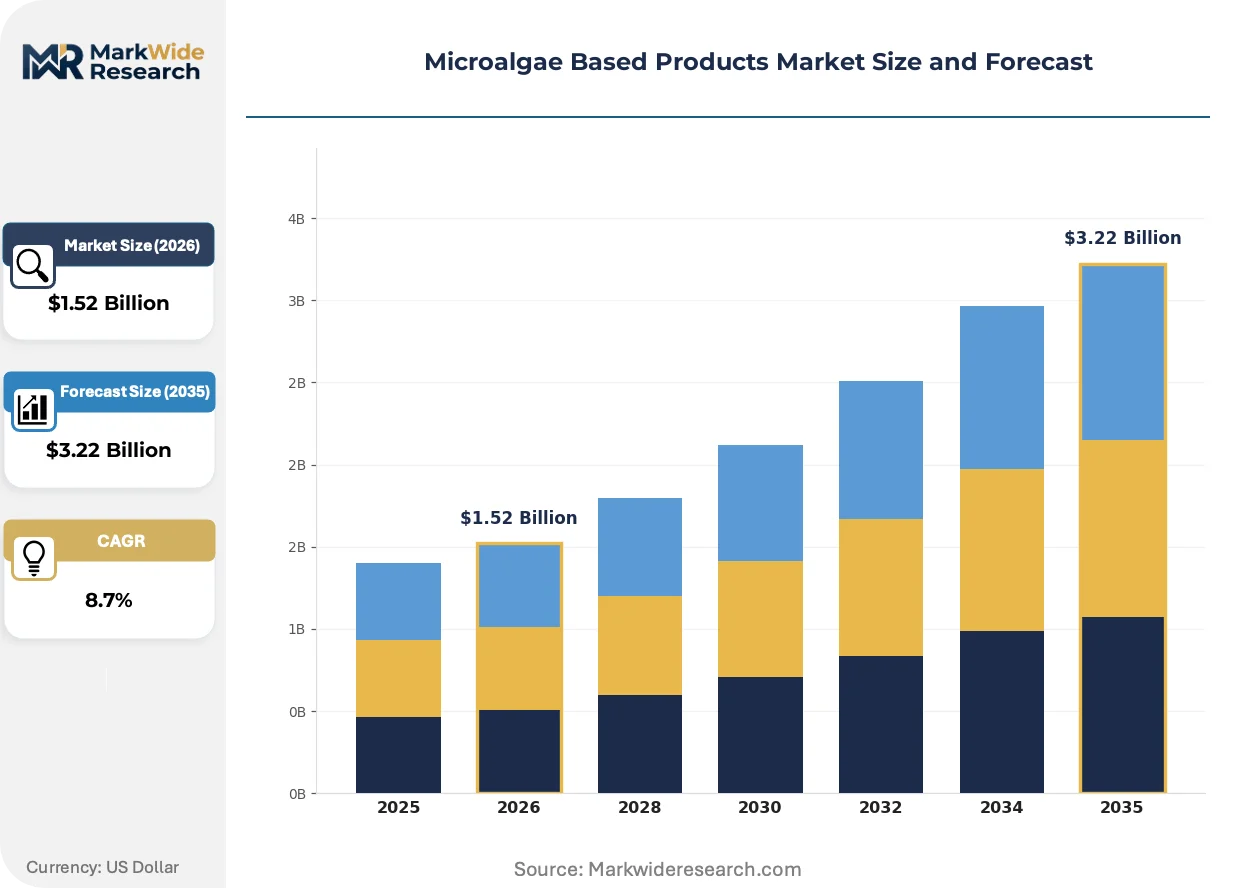
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
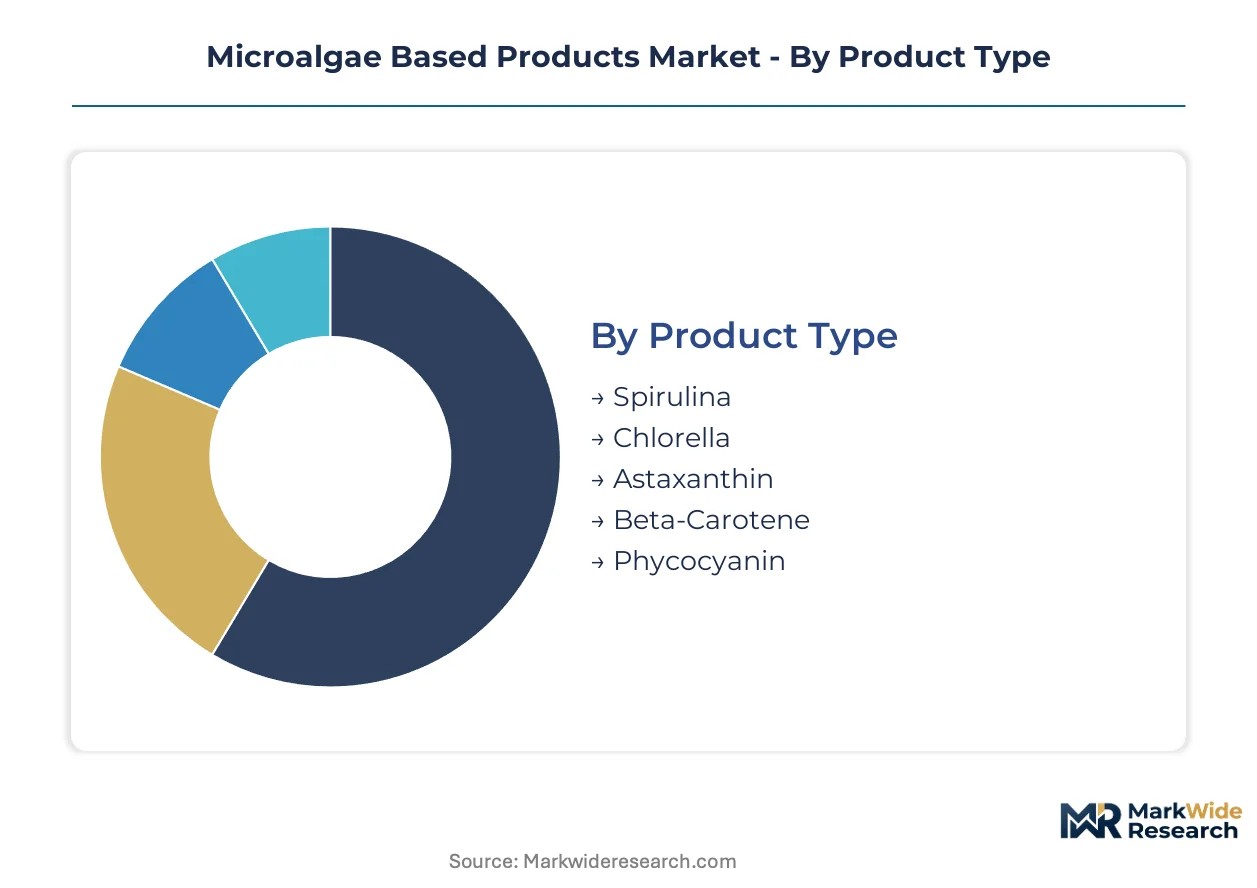
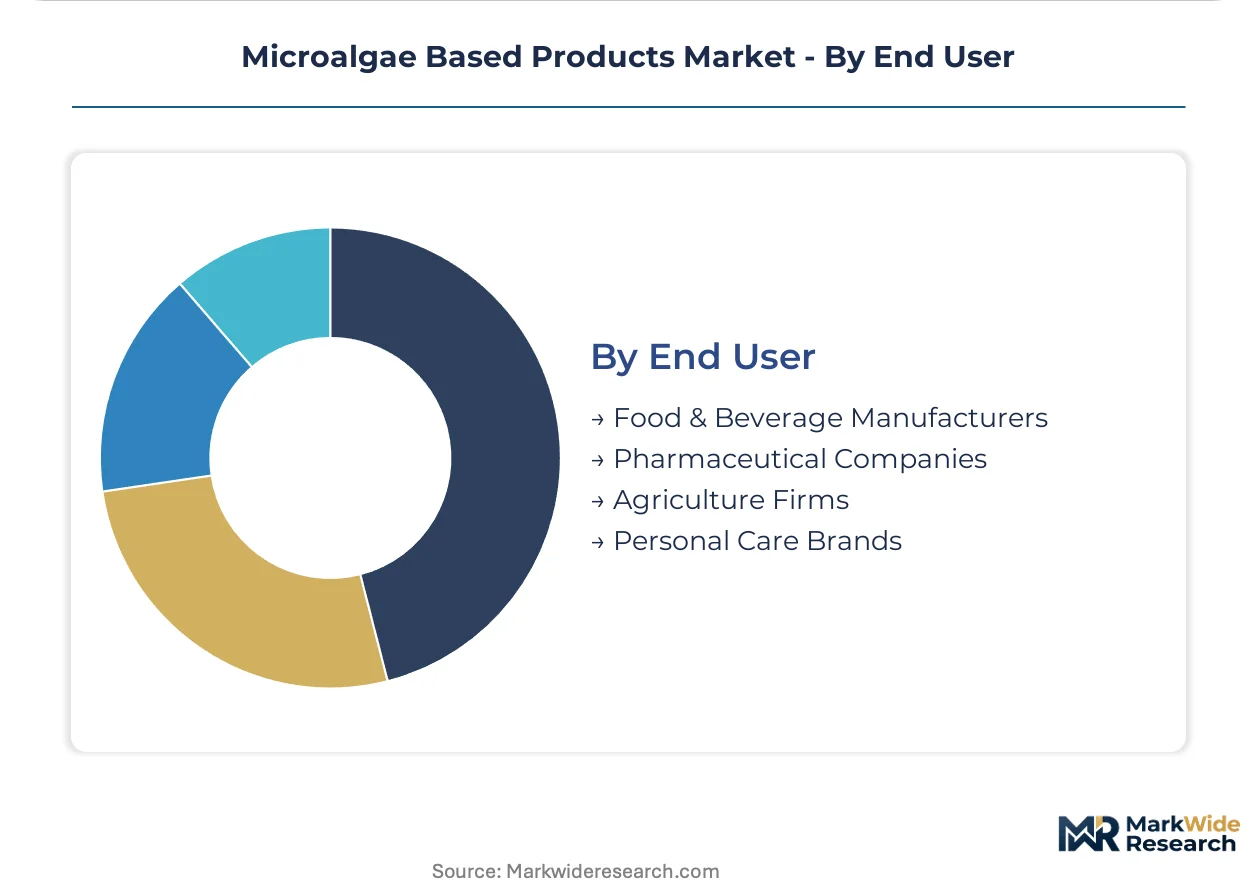
| Segmentation | Product Type: Spirulina, Chlorella, Astaxanthin, Beta-Carotene, Phycocyanin Application: Dietary Supplements, Animal Feed, Biofertilizers, Bioplastics, Cosmetics Technology: Photobioreactors, Open Pond Systems, Fermentation, Ultrasonic Extraction, Freeze Drying End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Agriculture Firms, Personal Care Brands |
| Companies Covered | Cyanotech Corporation, DIC Corporation, Corbion N.V., Cargill, Incorporated, DSM-Firmenich, BASF SE, Earthrise Nutritionals, LLC, E.I.D. Parry (India) Ltd, Fuqing King Dnarmsa Spirulina Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microalgae Based Products Market Strategic Shifts & Innovations
The market's evolution is defined by a strategic shift from selling bulk algal biomass to marketing purified, high-functionality extracts. This transition prioritizes scientific validation and application-specific performance over raw volume, reshaping value chains and competitive strategies.
Closed-loop photobioreactors integrated with AI-powered monitoring systems allow for precise control over light, pH, and nutrient levels. Nutraceutical and pharmaceutical ingredient producers are rapidly adopting these systems to guarantee consistent quality and purity. This technology is collapsing the production cycle time and batch-to-batch variability that plagued traditional open-pond cultivation methods.
Europe's novel food regulation, administered by the EFSA, establishes a rigorous pre-market approval process for new food ingredients, including those derived from microalgae. This framework creates a high barrier to entry but provides a significant competitive shield for companies that achieve authorization. The regulation primarily impacts developers of new algal strains or unique extracts targeting the EU food market, compelling extensive investment in safety and toxicological data.
A distinct behavioral shift is occurring as food formulators now source specific, functional compounds rather than bulk algal powders. This trend disrupts commodity suppliers and benefits specialized processors who can deliver standardized astaxanthin for antioxidant supplements or phycocyanin as a natural blue colorant. This pattern is most pronounced within the clean-label food and beverage sector in the United States and Germany, where ingredient functionality and traceability are key purchasing criteria.
Microalgae Based Products Market Segmentation
Understanding the Microalgae Based Products market through segmentation reveals distinct value propositions and operational models. This analysis highlights how different product forms, applications, technologies, and end-user demands shape investment priorities and competitive strategies. Producers must align their cultivation and processing capabilities with specific market niches.
Product Type:
Product types in the microalgae market exhibit varying production cycle times and market maturity, influencing their commercialization pathways.
- Spirulina:Spirulina is a blue-green algae rich in protein and phycocyanin, processed into powder or tablets. Demand concentrates in North America and Europe for dietary supplements, driven by its nutritional profile.
- Chlorella:Chlorella is a green algae known for detoxification properties and high chlorophyll, popular in supplements and health foods.
- Astaxanthin:Astaxanthin is a potent carotenoid from *Haematococcus pluvialis*, valued for its antioxidant properties. High-margin demand exists in nutraceuticals and cosmetics across the United States and Germany.
- Beta-Carotene:Beta-carotene, a Vitamin A precursor, is extracted from *Dunaliella salina* for natural colorant and nutritional supplement use.
- Phycocyanin:Phycocyanin is a natural blue pigment from spirulina, gaining traction as a clean-label food colorant and antioxidant.
Spirulina dominates the installed production base. Astaxanthin is where value expansion concentrates.
Application:
Applications for microalgae products span a wide range of value propositions, from high-volume, lower-margin uses to specialized, premium-priced markets.
- Dietary Supplements:This segment uses microalgae powders and extracts like spirulina and astaxanthin for their nutritional and bioactive compounds. Consumer demand for plant-based omega-3s in North America drives product innovation.
- Animal Feed:Microalgae serve as a sustainable protein source in aquaculture, poultry, and pet feeds, enhancing growth and immune function. Cost-effective spirulina gains traction in Southeast Asian aquaculture.
- Biofertilizers:Microalgae are developed as biofertilizers to improve soil health and nutrient availability, reducing reliance on synthetic inputs.
- Bioplastics:Research explores microalgae as renewable feedstock for biodegradable plastics, aligning with sustainability goals.
- Cosmetics:Algae extracts, like astaxanthin, are incorporated into skincare for antioxidant and anti-aging benefits.
Dietary Supplements currently hold the largest market share. Bioplastics and Cosmetics show the steepest expansion trajectory.
Technology:
Cultivation and processing technologies determine product purity, scalability, and cost-effectiveness, influencing the final application and market positioning of microalgae ingredients.
- Photobioreactors:These closed-loop systems provide controlled environments for microalgae, optimizing light and nutrients to maximize yield and purity. Pharmaceutical producers in Europe favor them for consistent production.
- Open Pond Systems:Large outdoor ponds expose microalgae to sunlight and CO2, representing a low-cost, high-volume cultivation method. This technology dominates spirulina production in Southeast Asia.
- Fermentation:Heterotrophic fermentation cultivates microalgae in bioreactors using sugar, enabling high cell densities independent of light.
- Ultrasonic Extraction:Ultrasonic extraction uses sound waves to disrupt algal cells, efficiently releasing intracellular compounds like lipids.
- Freeze Drying:Freeze drying preserves microalgae biomass by sublimating ice, retaining nutritional integrity and extending shelf life.
Open Pond Systems account for the majority of bulk biomass production. Photobioreactors are critical for high-purity, premium-grade extracts.
End User:
End-user segments impose distinct requirements for product specifications, regulatory compliance, and supply chain reliability, directly impacting microalgae product development.
- Food & Beverage Manufacturers:These manufacturers integrate microalgae as functional ingredients, colorants, and protein sources into food products. Consumer demand for clean-label ingredients in the United States drives adoption.
- Pharmaceutical Companies:Pharmaceutical firms utilize purified microalgae extracts, such as astaxanthin, for drug development and medical food applications. Stringent regulatory requirements in Europe necessitate advanced technologies.
- Agriculture Firms:Agriculture firms procure microalgae for biofertilizers and animal feed, enhancing crop yields and livestock health.
- Personal Care Brands:Personal care brands incorporate microalgae extracts into cosmetics, leveraging their antioxidant and anti-inflammatory properties.
Food & Beverage Manufacturers represent the largest volume purchasers. Pharmaceutical Companies navigate the most complex regulatory landscape.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. FDA's Generally Recognized as Safe (GRAS) notifications facilitate market access for microalgae ingredients in North America. This supports product innovation and consumer adoption in the United States for dietary supplements and functional foods. European EFSA regulations also shape market entry for novel food ingredients, compelling extensive safety and toxicological data.
United States
Consumer demand for plant-based omega-3s and high-value nutraceuticals drives significant market activity. The FDA's GRAS notifications clear pathways for new algal ingredients, boosting manufacturer confidence. Hawaii serves as a key production hub, with companies like Cyanotech Corporation specializing in astaxanthin cultivation.
Germany
Demand concentrates in Germany for high-value nutritional and cosmetic products, particularly clean-label foods. The EFSA's rigorous novel food regulations establish a high barrier to entry but provide competitive protection for authorized ingredients. Biotech clusters in regions like Bavaria foster advanced photobioreactor technologies for consistent, high-purity production.
Vietnam
Expanded cultivation capacity in Vietnam is reshaping the supply landscape for spirulina and chlorella, influencing raw material costs. National food safety standards guide the production and export of these bulk ingredients for animal feed and dietary supplements. The Mekong Delta region is witnessing significant investment in open-pond cultivation systems for cost-effective biomass.
China
China's market for algal-based food products and dietary supplements is substantial, driven by domestic consumption and export opportunities. The SAMR sets comprehensive standards for algal-based food products, impacting formulation and labeling. Shandong province is a major center for large-scale spirulina production, benefiting from favorable climate and infrastructure.
India
India's demand for nutritional supplements and functional food ingredients includes a growing interest in microalgae. The FSSAI regulates algal-based food products, ensuring quality and safety for consumers. Southern states, particularly Tamil Nadu, host numerous microalgae cultivation facilities, leveraging local agricultural expertise and resources.
Microalgae Based Products Market Key Industry Players
Capability concentration sits with one tier of specialized extract producers; scale advantage sits with another tier of bulk biomass suppliers. The market exhibits a clear bifurcation between high-volume, low-margin commodities and high-value, low-volume extracts. Strategic archetypes include integrated producers, technology innovators, and application-focused developers. Companies engage in capacity expansion and strategic partnerships to secure market positions.
Specialists in high-value extracts like astaxanthin anchor the premium segment, with Cyanotech Corporation leveraging its specialized production. Integrated players focused on large-scale cultivation and global distribution, such as DIC Corporation, sustain market leadership through extensive spirulina operations. Corbion N.V. represents a segment focusing on fermentation-based algae ingredients for specific food and animal feed applications.
| Leading Market Players |
|---|
| Cyanotech Corporation |
| DIC Corporation |
| Corbion N.V. |
| Cargill, Incorporated |
| DSM-Firmenich |
| BASF SE |
| Earthrise Nutritionals, LLC |
| E.I.D. Parry (India) Ltd |
| Fuqing King Dnarmsa Spirulina Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Regulatory approval delays for novel microalgae ingredients determine both pricing tier spreads and the geographic shape of the supply chain. These delays create market entry barriers, influencing the premium commanded by authorized products and the regions capable of compliant production.
Pricing Analysis
Geographic price spreads are evident, with premium extracts like astaxanthin commanding higher prices in North America and Europe, where the dominant pricing model is per-unit transactional. Long-term contract-based offtake characterizes bulk commodities. Price differentiation stems from quality grade, particularly certification levels like FDA GRAS and EFSA novel food authorizations, and volume scale. Cost compression in the bulk spirulina segment intensifies due to expanded Southeast Asian production, making animal feed manufacturers highly price sensitive compared to nutraceutical and cosmetic brands.
Supply Chain Analysis
Stringent regulatory approvals for novel microalgae ingredients limit the flow of new products and advanced cultivation technologies across borders. Supply concentrates in China, Vietnam, and India for bulk spirulina and chlorella, while high-value astaxanthin production centers in Hawaii and Germany. The supply chain relies on consistent access to CO2, specific nutrients, and clean water. Contamination risk in open pond systems poses a structural risk, with distribution running through specialized ingredient distributors and direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microalgae based products market is an early-cycle expansion story, driven by strong consumer demand for plant-based ingredients. This tailwind in adoption across food and dietary supplements creates significant long-term growth opportunities.
For Market Incumbents:
Pre-empt commodity price volatility by deepening vertical integration into specialized cultivation technologies like photobioreactors. Secure long-term offtake agreements with high-value nutraceutical and cosmetic brands to stabilize revenue streams. Invest in advanced strain development via genetic engineering to counter emerging substitute technologies. Prioritize certification investment, particularly EFSA novel food authorizations, to maintain market access and premium positioning against new entrants.
For New Entrants and Emerging Players:
Build out specialized production capabilities for high-purity, niche extracts beyond common spirulina and chlorella. Target the underpenetrated aquaculture feed market in Southeast Asia and Latin America with cost-effective, sustainable protein sources. Focus go-to-market strategies on scientific validation and clear sustainability claims, appealing to clean-label food formulators in Europe. Leverage fermentation-based technologies to offer consistent, light-independent supply for specific functional ingredients.
For Investors and Strategic Acquirers:
Expanded U.S. FDA GRAS notifications reshape the acquisition landscape for microalgae ingredient producers over the next 5-10 years. Seek acquisition targets with proprietary algal strains and robust intellectual property in high-value compounds like astaxanthin or phycocyanin. Prioritize companies demonstrating scalable, cost-effective production methods for premium extracts. The signal to watch is the increasing number of successful commercializations of genetically engineered algal strains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | DIC Corporation expands spirulina cultivation in Shandong province to meet growing global demand. |
| R&D in Strain Optimization | Cyanotech Corporation invests in *Haematococcus pluvialis* strain development for higher astaxanthin yields. |
| Regulatory Approval Pathway | Corbion N.V. pursues EFSA novel food authorization for new fermentation-based algal proteins. |
| Strategic Partnership | Earthrise Nutritionals, LLC forms alliances with food manufacturers for plant-based omega-3 integration. |
| Green Manufacturing Transition | Fuqing King Dnarmsa implements sustainable water recycling systems in chlorella production. |
Research Approach
A standing panel of microalgae cultivators, ingredient formulators, regulatory experts, and food R&D leads provided ongoing calibration. This involved combining primary interviews with industry stakeholders and secondary validation from diverse sources. Secondary data included FDA GRAS notices, EFSA opinions, academic journals, and company financial reports. Bottom-up market sizing was triangulated with top-down validation to ensure data accuracy.
Scenario-bracketing across optimistic and conservative outlooks defined the forecast framework over the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, technology, end-user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived from historical trends and expert projections. Key industry-specific forecast inputs included new regulatory approvals and raw material cost fluctuations.
Stress conditions across raw material supply shocks and major policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Material shifts in global trade policies or unforeseen technological breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
South America Fat Replacers Market