
 Global Meal Replacement Market | 2026-2036
Global Meal Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Meal Replacement Market Outlook
Single-serve bundling is hardening as the dominant configuration pattern, with brands packaging shakes, bars, and powders into weekly subscription boxes that reduce per-unit decision fatigue. Herbalife Nutrition leverages its direct-sales infrastructure to sustain recurring revenue from bundled nutrition programs. Abbott Laboratories anchors its medical-nutrition credibility through hospital and pharmacy channels. Huel differentiates via digital-native positioning and complete-nutrition claims that compete with conventional food occasions.
Meal replacements are formulated food products designed to substitute a standard meal while delivering controlled macronutrient profiles, typically containing 200–400 calories with specified protein, carbohydrate, fat, vitamin, and mineral content per serving. Their primary commercial purpose centers on convenience-driven nutrition for consumers seeking time-efficient alternatives to prepared food without sacrificing dietary balance. Powder formats occupy the mature volume base due to lower per-serving costs and longer shelf stability, while ready-to-drink shakes capture expanding margin pools through premium positioning in fitness centers and online retail channels. Vegan nutritional profiles represent the fastest-growing segment as plant-protein extraction technologies improve sensory acceptance and allergen labeling requirements tighten.
The US FDA exercises oversight through food-labeling standards and health-claim substantiation, while the EU EFSA evaluates novel-food approvals and nutrient-profile regulations under the EU Green Deal sustainability frameworks. China's SAMR enforces GB standards for pre-packaged food labeling that affect imported meal replacement access. Stakeholders must monitor evolving protein-source regulations and carbon-footprint disclosure mandates that will determine which formulations secure shelf space and consumer trust.
Market Dynamics
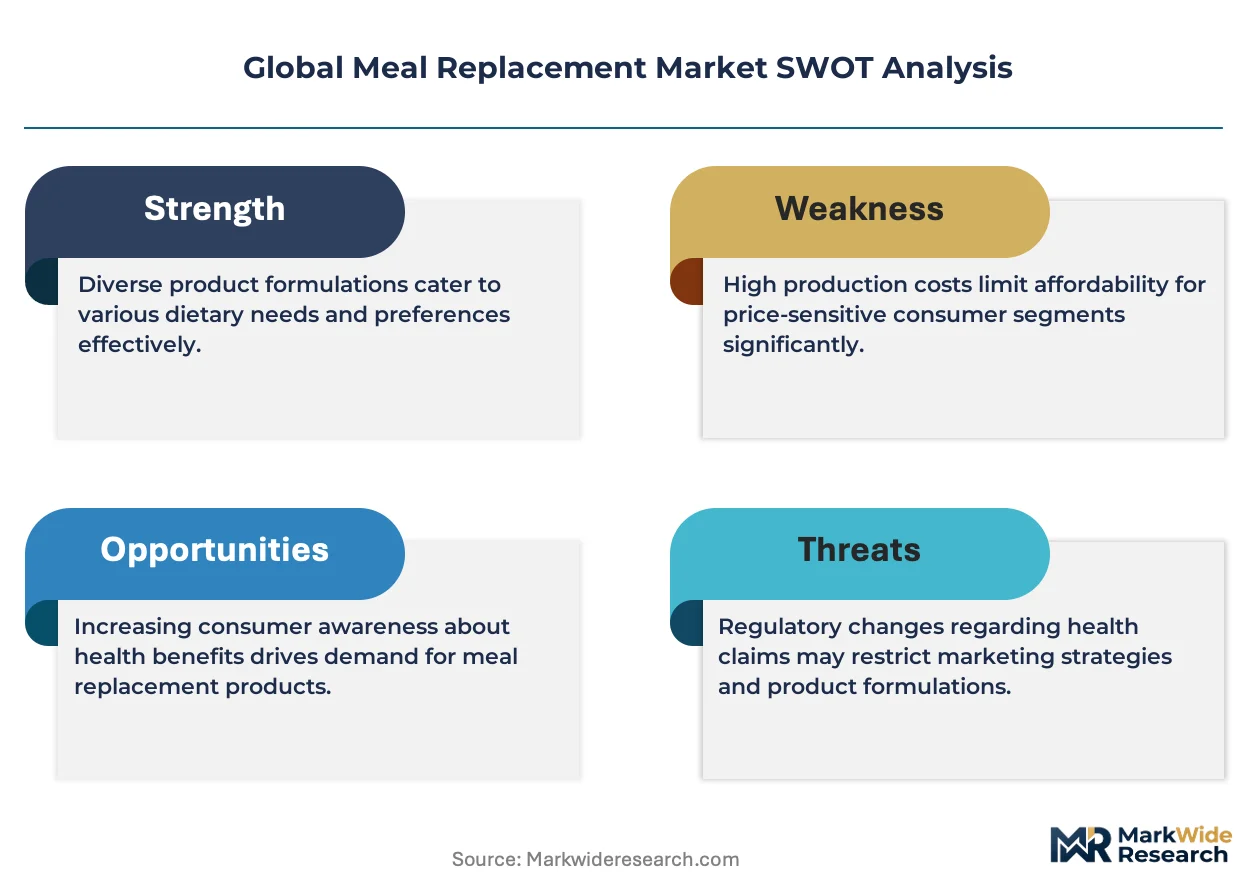
Protein fortification technologies and clean-label formulation mandates are compressing product development cycles, forcing manufacturers to rebuild supply chains around plant-protein extraction and allergen-free processing infrastructure.
Growth Catalysts
- EU Green Deal nutrient-profile regulations:The framework accelerates reformulation toward lower-carbon protein sources, creating compliant product lines that preempt trade barriers in Western European retail channels.
- China's SAMR GB standards alignment:Pre-packaged food labeling harmonization reduces import friction for powder formats, opening pharmacy and e-commerce distribution to foreign brands.
- Precision fermentation:This biotechnology delivers cost-competitive dairy-identical proteins without lactose or cholesterol, expanding addressable markets among allergen-sensitive consumers.
Market Restraints
- Pea protein concentrate volatility:Weather-driven harvest fluctuations in Canada and Ukraine create input cost instability that squeezes margin on mid-tier powder products.
- EFSA novel-food approval timelines:The 18-24 month evaluation window for alternative proteins delays European launch schedules and ties up R&D capital.
- Whole-food prepared meal substitution:Fresh meal-kit services and ghost-kitchen delivery compress the convenience gap that meal replacements historically exploited.
Strategic Opportunities
- India's metro professional cohort:Underpenetrated demand among Mumbai and Bangalore white-collar workers offers first-mover advantage for ready-to-drink formats in corporate canteen channels.
- US IRA clean manufacturing credits:Tax incentives for low-carbon production facilities reduce capex burden for domestic protein processing plants serving North American markets.
- Telehealth-nutrition integration:Physician-prescribed meal protocols for metabolic management create reimbursable channels distinct from discretionary retail.
Industry Challenges
- Food technologist scarcity:Shortage of specialists in plant-protein texturization and flavor masking extends formulation timelines and inflates compensation costs.
- Dual certification burden:Simultaneous pursuit of USDA Organic and Non-GMO Project verification creates documentation complexity and audit expense that disadvantages smaller entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Meal Replacement Market |
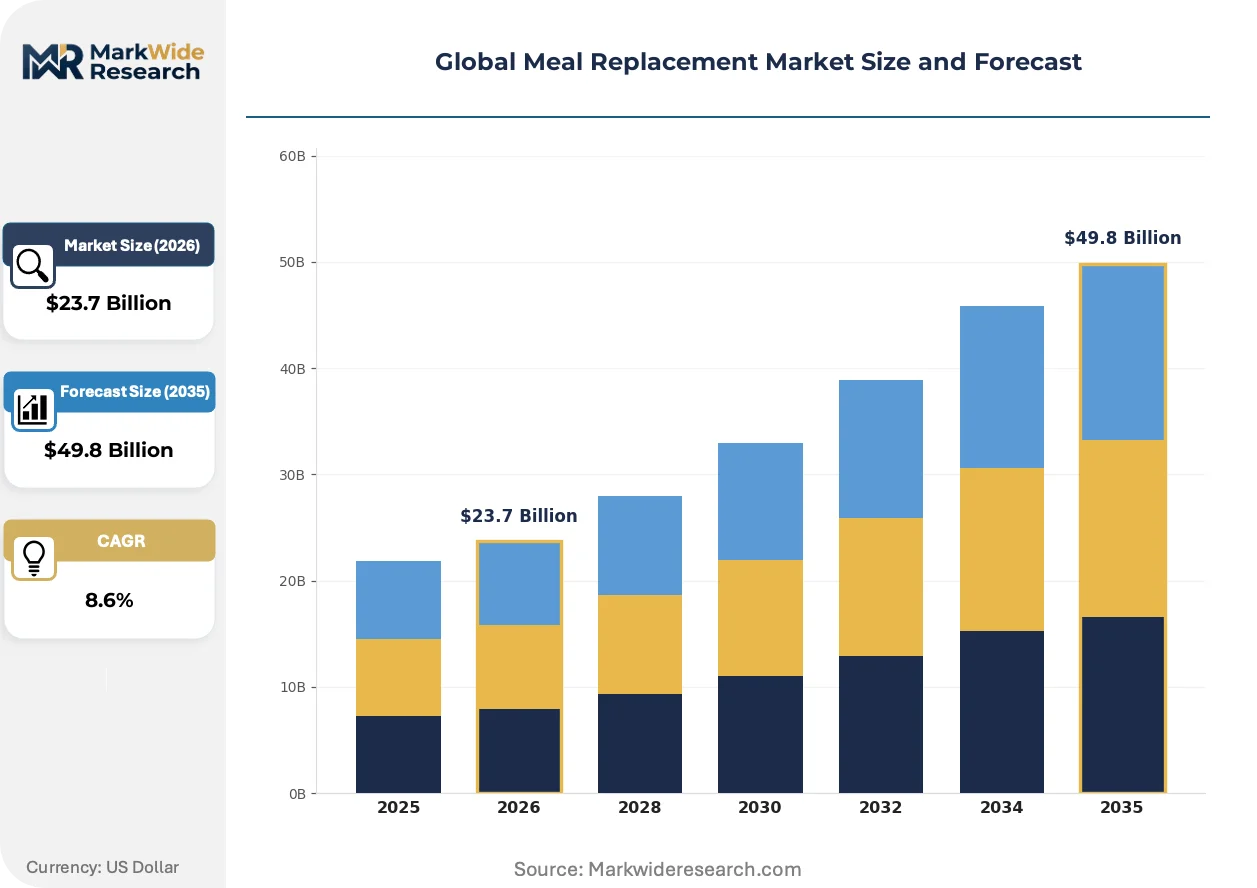
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shakes, Bars, Powders, Soups Nutritional Profile: High Protein, Low Carb, Low Calorie, Vegan End User: Athletes, Weight Management, Busy Professionals, Health Conscious Distribution Channel: Online Retail, Supermarkets, Health Stores, Fitness Centers |
| Companies Covered | Herbalife Nutrition, General Mills, Abbott Laboratories, Amway, Kellogg Co., Nestle, Glanbia Plc, Huel, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Meal Replacement Market Strategic Shifts
Digital-native distribution models and precision biotechnology are fragmenting traditional retail dominance while elevating subscription-based customer relationships and personalized nutrition protocols.
Cell-cultured whey protein is integrating into powder formulations as a hybrid ingredient that bridges sensory performance gaps in plant-only products. Sports nutrition brands in Germany and the Netherlands are adopting this material at pilot scale. The technology is integrating high-performance dairy nutrition with vegan positioning, compressing the historical trade-off between clean-label claims and amino acid completeness.
China's SAMR is tightening GB 28050 nutritional labeling enforcement for imported meal replacements, requiring explicit disclosure of added sugars and sodium content. This policy shift elevates compliance costs for legacy formulations while advantaging domestic manufacturers with pre-aligned documentation. Powder formats targeting pharmacy channels face the steepest reformulation pressure, with several US and EU brands accelerating China-specific product line development.
Subscription bundling is displacing single-unit retail purchasing among busy professionals seeking automated nutrition routines. Direct-to-consumer platforms capture recurring revenue through algorithmic flavor rotation and portion customization, while conventional supermarkets lose traffic in core urban markets. This behavioral pivot is most pronounced in London, New York, and Tokyo, where delivery density supports weekly replenishment economics.
Global Meal Replacement Market Segmentation
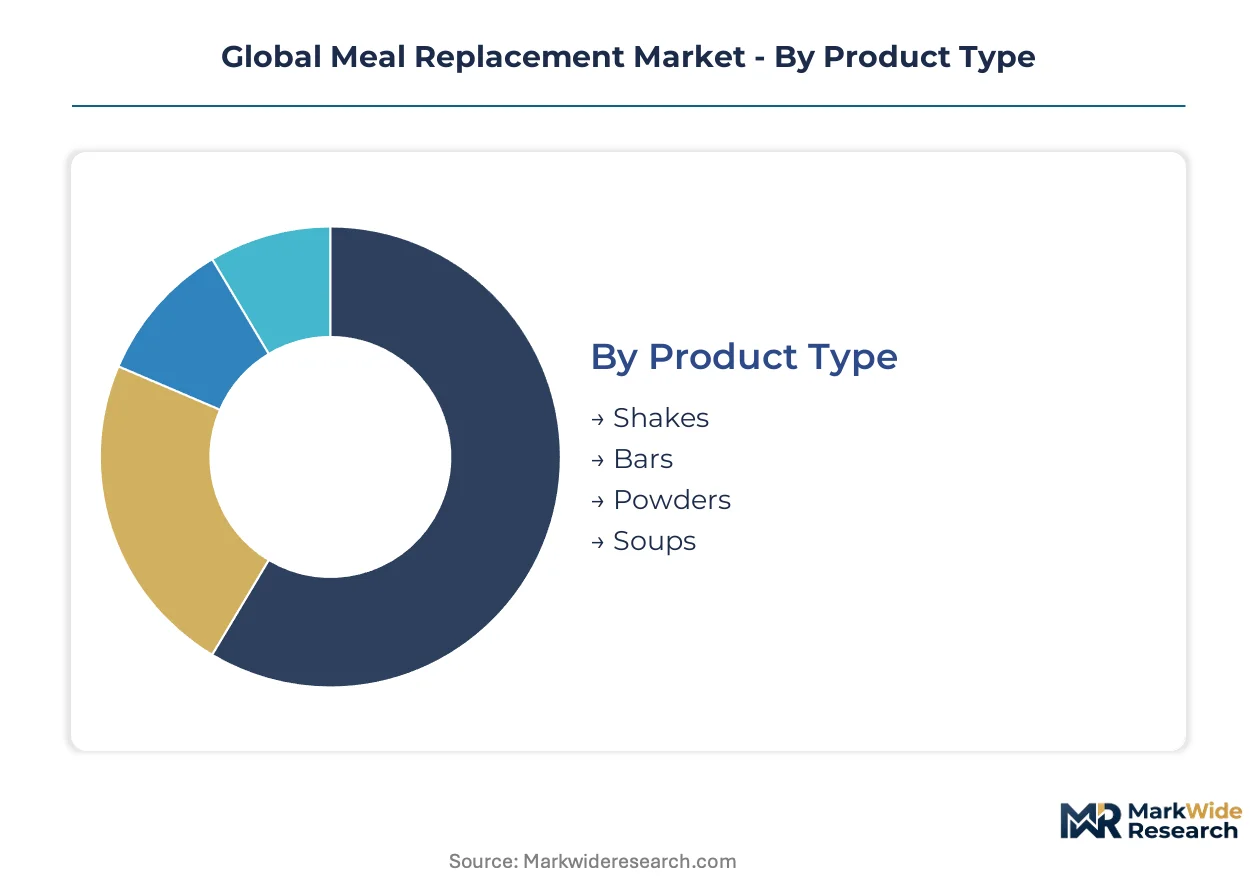
Meal replacement manufacturers allocate capital unevenly across format categories, with powder production requiring fermentation tanks and spray-drying infrastructure while ready-to-drink lines demand aseptic bottling systems. Segmentation clarity exposes where margin pools concentrate versus where volume scales.
Product Type:
Powder production commands the heaviest upfront capital commitment due to spray-drying towers, blending silos, and climate-controlled storage infrastructure that protect protein integrity across shelf life.
- Powders:Dry-blend formulations combine protein isolates, maltodextrin carriers, and micronutrient premixes into shelf-stable formats. Demand concentrates in Germany and the United Kingdom where home-blending rituals persist among fitness enthusiasts; EFSA novel-food approvals for alternative proteins delay reformulation cycles here.
- Shakes:Ready-to-drink liquids integrate emulsion stabilizers and retort or aseptic processing to deliver grab-and-go convenience. United States gym chains and Japanese convenience stores drive procurement; cold-chain distribution requirements constrain margin expansion.
- Bars:Extruded and enrobed formats bind protein crisps with humectant syrups for portable satiety.
- Soups:Savory liquid alternatives target consumers seeking warm meal substitutes beyond sweet profiles.
Powders absorb the bulk of installed capacity; shakes are expanding most quickly.
Nutritional Profile:
Formulation complexity varies sharply by macronutrient target, with vegan profiles demanding the most R&D expenditure to mask off-notes from legume and grain protein sources.
- High Protein:Isolates and concentrates deliver 20–30g protein per serving through whey, casein, or blended plant sources. Athletes in Australia and South Korea prioritize leucine content and digestibility scores; precision fermentation is compressing cost differentials between dairy and next-generation alternatives.
- Vegan:Excludes all animal derivatives through pea, rice, fava, or cell-cultured protein integration. Germany and Netherlands retail channels enforce strict allergen labeling that advantages transparent supply chains; sensory gaps versus dairy benchmarks persist in texture and mouthfeel.
- Low Carb:Restricts glycemic load through fiber enrichment and sugar alcohol substitution.
- Low Calorie:Targets 150–200 kcal portions for controlled energy intake protocols.
High Protein captures the deepest revenue pools; Vegan gains share fastest.
End User:
Customer acquisition costs diverge by behavioral segment, with athletes demanding clinical substantiation while busy professionals respond to convenience automation.
- Busy Professionals:Time-constrained white-collar workers in Mumbai, London, and New York subscribe to automated replenishment for breakfast and lunch substitution. Corporate wellness programs in India subsidize powder formats; subscription bundling hardens loyalty against single-unit retail.
- Athletes:Competitive and recreational performers prioritize amino acid completeness and third-party certification. United States collegiate sports and CrossFit affiliates drive premium shake consumption; NSF Certified for Sport and Informed Sport testing adds compliance overhead.
- Weight Management:Calorie-controlled protocols for metabolic health and body composition goals.
- Health Conscious:General wellness seekers prioritizing clean labels and ingredient transparency.
Busy Professionals anchor recurring revenue; Athletes sustain premium pricing power.
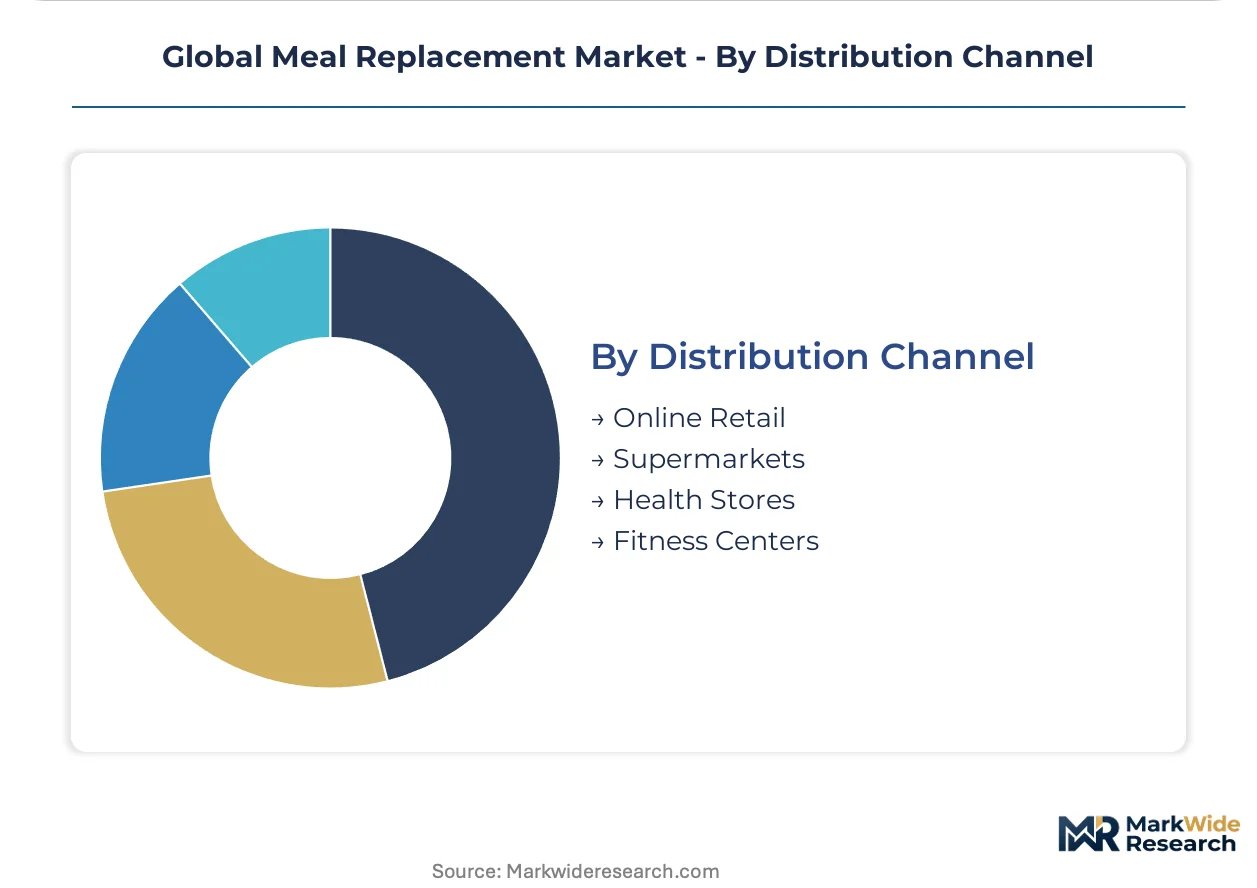
Distribution Channel:
Channel selection determines working capital intensity, with direct-to-consumer platforms requiring inventory flexibility while retail mandates slotting fees and promotional depth.
- Online Retail:Direct-to-consumer and marketplace platforms enable algorithmic personalization and subscription mechanics. China's Tmall and JD.com pharmacy flagships face SAMR GB 28050 labeling enforcement; domestic brands with pre-aligned documentation secure faster listing approvals.
- Fitness Centers:On-premise vending and pro-shop placement captures high-intent consumption moments. United States Equinox and Life Time locations stock refrigerated shakes; point-of-sampling converts trial to subscription at above-average rates.
- Supermarkets:Mass retail placement demands trade spending and promotional calendar coordination.
- Health Stores:Specialty retailers emphasize curated assortments and staff recommendation authority.
Online Retail concentrates fulfillment infrastructure investment; Fitness Centers deliver the steepest customer lifetime value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Germany while consumption expands fastest in India and China. Powder production dominates North American and European output. Ready-to-drink shake demand concentrates in urban centers across Asia-Pacific.
United States
Fitness center vending networks and direct-to-consumer subscription platforms drive shake consumption among time-constrained professionals. The FDA maintains food-labeling standards and health-claim substantiation requirements that shape formulation decisions. Chicago and Austin host concentrated co-manufacturing infrastructure serving both domestic and export markets.
Germany
Plant-protein powder demand accelerates as vegan nutritional profiles gain share in pharmacy and organic retail channels. EFSA novel-food approval timelines and EU Green Deal nutrient-profile regulations compress reformulation cycles. Cologne and Hamburg anchor spray-drying and blending facilities supplying Western European distribution networks.
China
Urban white-collar workers in tier-one cities adopt ready-to-drink formats through Tmall and JD.com pharmacy flagships. SAMR enforces GB 28050 nutritional labeling standards that elevate compliance costs for imported powder formulations. Shanghai and Shenzhen concentrate domestic manufacturing capacity and e-commerce fulfillment infrastructure.
India
Mumbai and Bangalore professionals represent underpenetrated demand for automated nutrition subscriptions in corporate canteen channels. FSSAI labeling requirements and import tariff structures affect foreign brand market entry strategies. Hyderabad and Pune develop contract manufacturing capabilities serving both domestic consumption and regional export.
United Kingdom
Digital-native brands capture recurring revenue through algorithmic flavor rotation and portion customization among London professionals. EFSA novel-food regulations apply through retained EU alignment mechanisms pending divergence reviews. Manchester and Birmingham host powder blending operations with cold-chain distribution reach into Ireland and Scandinavia.
Global Meal Replacement Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across format and channel dimensions. The vendor base spans multinational nutrition companies, direct-sales networks, and digital-native entrants. Three archetypes dominate: medical-nutrition credibility builders, subscription bundling platforms, and ingredient technology suppliers. Competitive moves concentrate on supply chain backward integration and telehealth channel development.
Among direct-sales nutrition networks, Herbalife Nutrition exemplifies recurring revenue architecture through bundled program structures. Within medical-nutrition credibility, Abbott Laboratories occupies a position anchored through hospital and pharmacy channel presence. At the digital-native vector, Huel represents complete-nutrition positioning competing with conventional food occasions. These three entities illustrate divergent paths to customer acquisition and retention economics.
| Leading Market Players |
|---|
| Herbalife Nutrition |
| General Mills |
| Abbott Laboratories |
| Amway |
| Kellogg Co. |
| Nestle |
| Glanbia Plc |
| Huel |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal nutrient-profile regulations gate qualified supply and premium-tier pricing access, as compliance with carbon-footprint disclosure mandates determines which formulations secure shelf space in Western European retail channels. Manufacturers lacking aligned documentation face exclusion from pharmacy and organic retail networks where price premiums concentrate.
Pricing Analysis
Margin tightening in mid-tier powder products reflects pea protein concentrate volatility from weather-driven harvest fluctuations in Canada and Ukraine. Three-tier pricing structure across premium, standard, and economy levels separates precision fermentation-derived formulations from conventional plant-protein and commodity whey alternatives. Cost-down pressure accelerates because cold-chain distribution requirements for ready-to-drink shakes constrain margin expansion. Busy professionals demonstrate lowest price sensitivity through subscription bundling, while occasional fitness consumers in mass retail exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Canadian and Ukrainian pea protein harvests that feed European and North American formulation facilities. Manufacturing gravity draws from Germany, the United States, and China, where spray-drying towers and aseptic bottling systems cluster. Raw material dependencies rest on protein isolates, emulsion stabilizers, and micronutrient premixes. Tariff exposure from China's SAMR GB standards alignment creates import friction for legacy powder formulations. Distribution runs through direct-to-consumer platforms and fitness center vending networks that capture recurring revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-drying and precision fermentation capacity scarcity props pricing power, constraining volume expansion for compliant product lines. Manufacturers without backward integration into protein processing face persistent margin compression.
For Market Incumbents: Acquire fermentation tank and spray-drying infrastructure to secure captive supply of protein isolates. Abbott Laboratories and Herbalife Nutrition should deepen backward integration into plant-protein extraction facilities in Germany and the United States to defend against precision fermentation entrants. Certification investment in USDA Organic and Non-GMO Project verification creates defensive moats against mid-tier competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for algorithmic flavor rotation and portion customization. Target India's Mumbai and Bangalore corporate canteen channels with ready-to-drink formats, where FSSAI labeling requirements remain less burdensome than China's SAMR enforcement. Telehealth-nutrition integration provides a reimbursable go-to-market angle distinct from discretionary retail. For Investors and Strategic Acquirers: EFSA novel-food approval timeline compression is the leading indicator that European launch schedules will accelerate, unlocking trapped R&D capital. Cell-cultured whey protein technology suppliers represent the highest-conviction acquisition archetype over a five-to-ten year horizon, bridging sensory performance gaps in plant-only products. Watch for precision fermentation cost parity announcements as the signal that dairy-identical proteins have achieved mainstream viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Processing | Captive supply of pea and fava protein isolates insulates margin from Canadian harvest volatility. |
| Direct-to-Consumer Platform Launch | Algorithmic subscription mechanics harden loyalty among London and New York professionals. |
| Precision Fermentation Scale-Up | Cost-competitive dairy-identical proteins expand addressable markets among allergen-sensitive consumers. |
| Telehealth Channel Partnership | Physician-prescribed meal protocols for metabolic management create reimbursable revenue streams. |
| China-Specific Product Line Development | Pre-aligned GB 28050 documentation secures faster Tmall and JD.com pharmacy flagship approvals. |
Study Parameters
SEC filings, customs and trade databases, and EFSA novel-food approval registers formed the secondary backbone of this analysis. Primary interviews with food technology R&D directors, protein processing plant managers, retail category buyers, and telehealth platform operators validated demand assumptions. Bottom-up volume modeling across powder, shake, bar, and soup formats triangulated with top-down macroeconomic sizing.
Historical trendline analysis of protein fortification adoption and clean-label formulation shifts anchored the projection framework. Segmentation dimensions modeled include product type, nutritional profile, end-user behavioral archetype, and distribution channel complexity. CAGRs derived from curve-fitting across the projection horizon incorporated precision fermentation cost reduction trajectories and EU Green Deal compliance timelines as industry-specific inputs.
The model holds under stable regulatory enforcement timelines and protein crop yield patterns; deviation in EFSA approval acceleration or severe North American drought would shift volume and value outputs. Forecasts reflect documented assumptions about substitution elasticity between meal replacements and fresh meal-kit services. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mealworms Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Vegan Caviar Market