
 Fish Oil Alternatives Market | 2026-2036
Fish Oil Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Oil Alternatives Market Foresight
Subscription-based omega-3 ingredient sampling is restructuring how food producers evaluate and commit to fish oil alternatives. Cargill Incorporated leverages its global oilseed infrastructure to secure consistent supply chains for plant-derived omega sources. DSM-Firmenich anchors its position through biotechnology platforms that produce EPA and DHA from fermented algae. Corbion competes with closed-system photobioreactor technology that eliminates marine ecosystem dependence.
Fish oil alternatives encompass non-marine lipid sources engineered to deliver equivalent omega-3 fatty acid profiles, with algal oil achieving DHA concentrations of 35-55% through heterotrophic fermentation in controlled bioreactors. These substitutes serve pharmaceutical and nutraceutical applications requiring contaminant-free docosahexaenoic acid and eicosapentaenoic acid inputs. Algal oil commands premium positioning in infant formula and medical nutrition where purity thresholds exceed standard dietary supplement requirements. Powder and emulsion forms are gaining formulation share as beverage and fortified food manufacturers seek oil-in-water dispersibility without flavor masking systems.
The EU Green Deal and REACH frameworks restrict wild-caught fishmeal sourcing while EFSA Novel Food approvals govern algal and krill oil entry into European food channels. FDA GRAS notifications and EPA water quality standards shape American product qualification timelines and contamination testing protocols. Stakeholders must monitor regulatory divergence between jurisdictions where sustainability credentials and novel food safety assessments create divergent market access conditions.
Market Dynamics
EU Green Deal enforcement is compressing marine-derived omega-3 supply chains while biotechnology fermentation scales to fill the void. Algal oil producers now compete directly with traditional fish oil on DHA concentration parity, forcing ingredient buyers to requalify formulations around sustainability credentials rather than cost alone.
Growth Catalysts
- REACH Framework Tightening:ECHA restrictions on wild-caught fishmeal sourcing redirect European nutraceutical procurement toward controlled-environment algal cultivation. Infant formula manufacturers in Germany accelerate DHA supplier transitions.
- Fermentation Biotechnology:Heterotrophic bioreactor systems achieve 35-55% DHA oil concentrations without marine ecosystem exposure. Pharmaceutical-grade purity specifications now match algal output capabilities.
- Contaminant-Free Positioning:Heavy metal and microplastic accumulation in ocean fish stocks drives US functional food producers toward land-based omega-3 sources. Clean label requirements eliminate post-harvest purification steps.
Market Restraints
- Feedstock Cost Volatility:Glucose and nitrogen inputs for heterotrophic fermentation fluctuate with agricultural commodity cycles. Algal oil carries 40-60% production cost premiums versus anchovy-derived equivalents.
- Single-Source Concentration Risk:Strain IP and bioreactor engineering expertise concentrate among three biotechnology platforms. Licensing dependencies create supply vulnerability for second-tier ingredient distributors.
- EFSA Novel Food Timeline:European pre-market authorization processes extend 18-24 months for new algal strains. DHA-rich Schizochytrium variants face sequential toxicology and allergenicity assessments.
Strategic Opportunities
- Medical Nutrition Expansion:Enteral and parenteral lipid emulsion formulations require EPA/DHA with batch-level contaminant documentation. Hospital procurement channels reward fermentation-derived traceability.
- India Nutraceutical Liberalization:FSSAI functional food regulations relax omega-3 fortification limits in dairy and bakery applications. Domestic algal cultivation pilots reduce import dependency.
- Photobioreactor-Pharma Convergence:Closed-system cultivation infrastructure transfers from biologics manufacturing to food-grade lipid production. cGMP-compliant facilities command pharmaceutical ingredient premiums.
Industry Challenges
- Strain Engineering Talent Scarcity:Industrial microbiologists with heterotrophic algae optimization experience command biotechnology sector salaries. Food ingredient employers compete against pharmaceutical fermentation recruiters.
- IP Licensing Complexity:DHA biosynthesis pathway patents fragment across academic institutions and biotechnology firms. Royalty stacking inflates unit economics for commercial-scale deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Oil Alternatives Market |
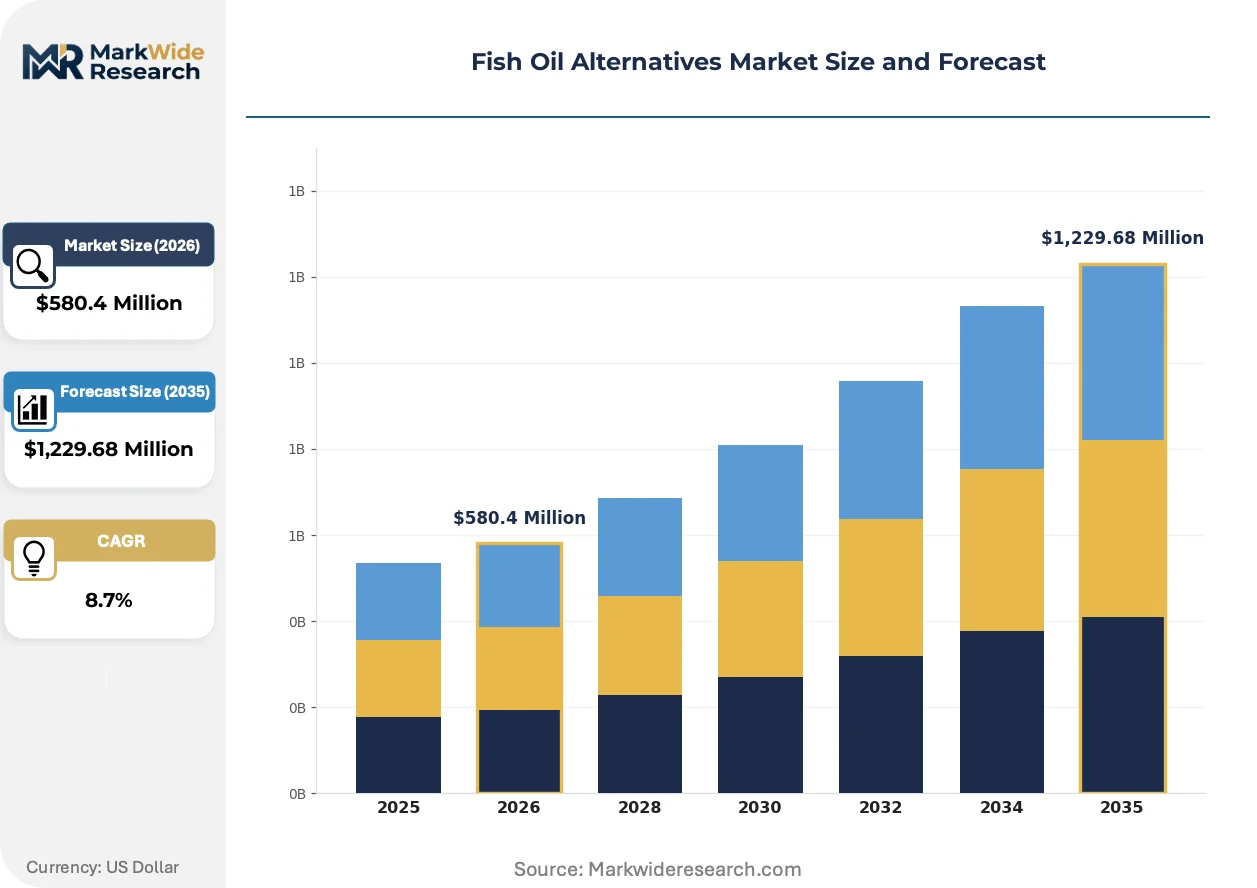
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $1,229.68 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algal Oil, Krill Oil, Flaxseed Oil, Echium Oil, Perilla Oil Application: Dietary Supplements, Functional Foods, Cosmetics, Pharmaceuticals, Animal Feed End User: Health Stores, Pharmacies, Personal Care Manufacturers, Veterinary Suppliers, Food Producers Form: Capsules, Liquids, Powders, Emulsions, Concentrates |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Wilmar International Limited, DSM-Firmenich, Corbion, BASF, Burcon, Prinova Group LLC, Nutiva Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Oil Alternatives Market Shifts & Advancements
Biotechnology fermentation is displacing extraction-based omega-3 production across pharmaceutical and infant nutrition tiers. Ingredient buyers now evaluate suppliers on carbon intensity metrics and water stewardship rather than fatty acid profiles alone.
Precision fermentation using metabolically engineered Schizochytrium strains is converging with pharmaceutical-grade lipid emulsion manufacturing. Contract development organizations adopt food-grade algal platforms for active pharmaceutical ingredient adjuvants. This convergence collapses the historical separation between nutritional and clinical omega-3 supply chains, enabling single-source qualification for dual-use facilities.
REACH authorization timelines and EFSA Novel Food safety assessments are extending European market entry barriers for new marine-derived ingredients. Wild-caught fish oil importers face mandatory sustainability certification under EU Green Deal due diligence rules. German and Dutch ingredient distributors accelerate algal oil inventory builds to preempt supply interruptions from tightened marine sourcing audits.
Subscription-based sampling programs are restructuring how beverage and fortified food manufacturers evaluate omega-3 alternatives. Procurement teams now test powder and emulsion formats through quarterly ingredient boxes before committing to volume contracts. This model compresses supplier qualification cycles in the United States, where functional food innovation cycles outpace traditional ingredient approval timelines.
Fish Oil Alternatives Market Segmentation
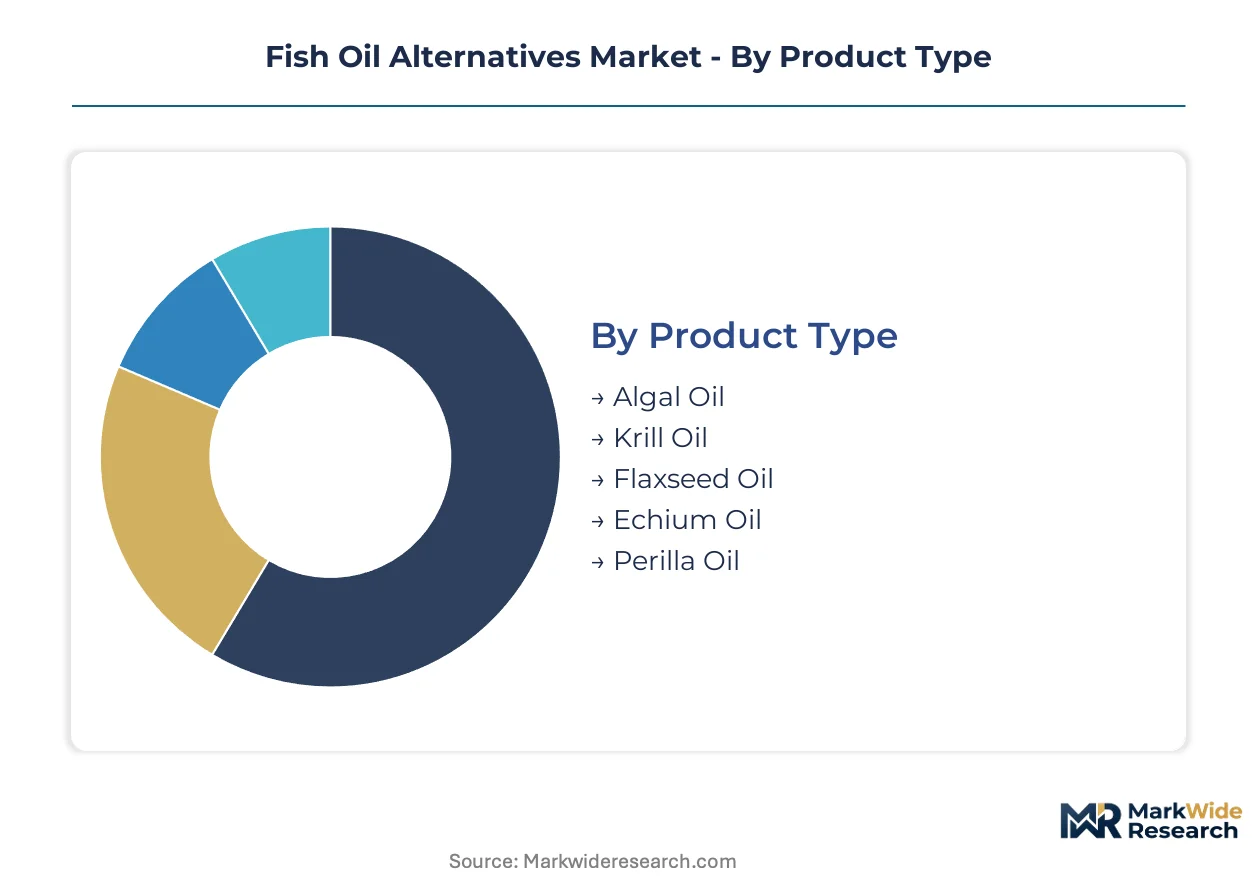
Ingredient buyers navigate divergent purity requirements, formulation constraints, and regulatory pathways across omega-3 alternatives. Segmentation reveals where fermentation-derived lipids displace extraction-based supply chains versus where plant oils retain cost advantages.
Product Type:
Customization intensity varies from standardized commodity oils to strain-engineered fermentation outputs with pharmaceutical-grade documentation.
- Algal Oil:Heterotrophic fermentation in controlled bioreactors yields DHA concentrations of 35-55% without marine ecosystem exposure. Infant formula manufacturers in Germany and the United States prioritize algal sources for contaminant-free docosahexaenoic acid under tightening EU Green Deal and FDA GRAS frameworks.
- Krill Oil:Antarctic krill extraction delivers phospholipid-bound omega-3s with superior bioavailability versus triglyceride forms. EFSA Novel Food timelines and Antarctic Treaty sustainability certifications constrain European and North American volume expansion.
- Flaxseed Oil:Cold-pressed alpha-linolenic acid from Canadian and Ukrainian seed crops serves vegetarian positioning at commodity price points.
- Echium Oil:Stearidonic acid-rich biotechnology crop from UK and Dutch cultivation fills mid-tier omega-3-6-9 balanced formulations.
- Perilla Oil:Traditional East Asian seed oil with rosmarinic acid co-benefits targets Korean and Japanese functional food fortification.
Most installed capacity flows through Algal Oil. Expansion is steepest in Krill Oil.
Application:
Margin structures separate pharmaceutical-grade documentation requirements from commodity food fortification economics.
- Dietary Supplements:Softgel and capsule formats dominate direct-to-consumer channels with third-party testing certifications driving brand differentiation. United States health store procurement emphasizes USP-verified algal and krill sources.
- Functional Foods:Beverage and bakery fortification demands oil-in-water dispersibility without flavor masking. Powder and emulsion forms from DSM-Firmenich and Corbion platforms accelerate formulation adoption.
- Cosmetics:Topical omega-3 claims in anti-inflammatory skincare leverage algal oil traceability for clean beauty positioning.
- Pharmaceuticals:Enteral and parenteral lipid emulsions require batch-level contaminant documentation with cGMP fermentation infrastructure commanding ingredient premiums.
- Animal Feed:Aquaculture and pet nutrition applications substitute algal DHA for fishmeal in salmon and premium pet food rations.
Pharmaceutical-grade specifications concentrate in Pharmaceuticals. Volume scaling runs fastest in Functional Foods.
End User:
Channel control determines qualification timelines and sustainability credential verification depth.
- Health Stores:United States specialty retailers drive algal oil capsule growth through practitioner and influencer endorsement channels.
- Pharmacies:German and French pharmacy chains require EFSA-compliant novel food documentation for omega-3 shelf placement.
- Personal Care Manufacturers:Cosmetic formulators in Korea and France source traceable algal lipids for clean beauty certification programs.
- Veterinary Suppliers:Premium pet food brands in the United States and United Kingdom specify fermentation-derived DHA for contaminant-free positioning.
- Food Producers:Dairy and bakery manufacturers in India under FSSAI liberalized regulations trial algal powder fortification.
Qualification rigor peaks with Pharmacies. Procurement volume aggregates with Food Producers.
Form:
Processing intensity separates commodity extraction outputs from precision-engineered delivery systems.
- Capsules:Softgel encapsulation of algal and krill oils dominates supplement shelf presence with enteric coating options for gastric tolerance.
- Liquids:Flaxseed and echium oil bulk formats serve food manufacturing and functional beverage blending operations.
- Powders:Microencapsulated algal DHA enables bakery and dry mix fortification without oxidative stability concerns.
- Emulsions:Oil-in-water nanoemulsions from Corbion's photobioreactor platforms deliver beverage dispersibility without flavor masking systems.
- Concentrates:Pharmaceutical-grade EPA/DHA concentrates above 80% purity serve medical nutrition and prescription omega-3 applications.
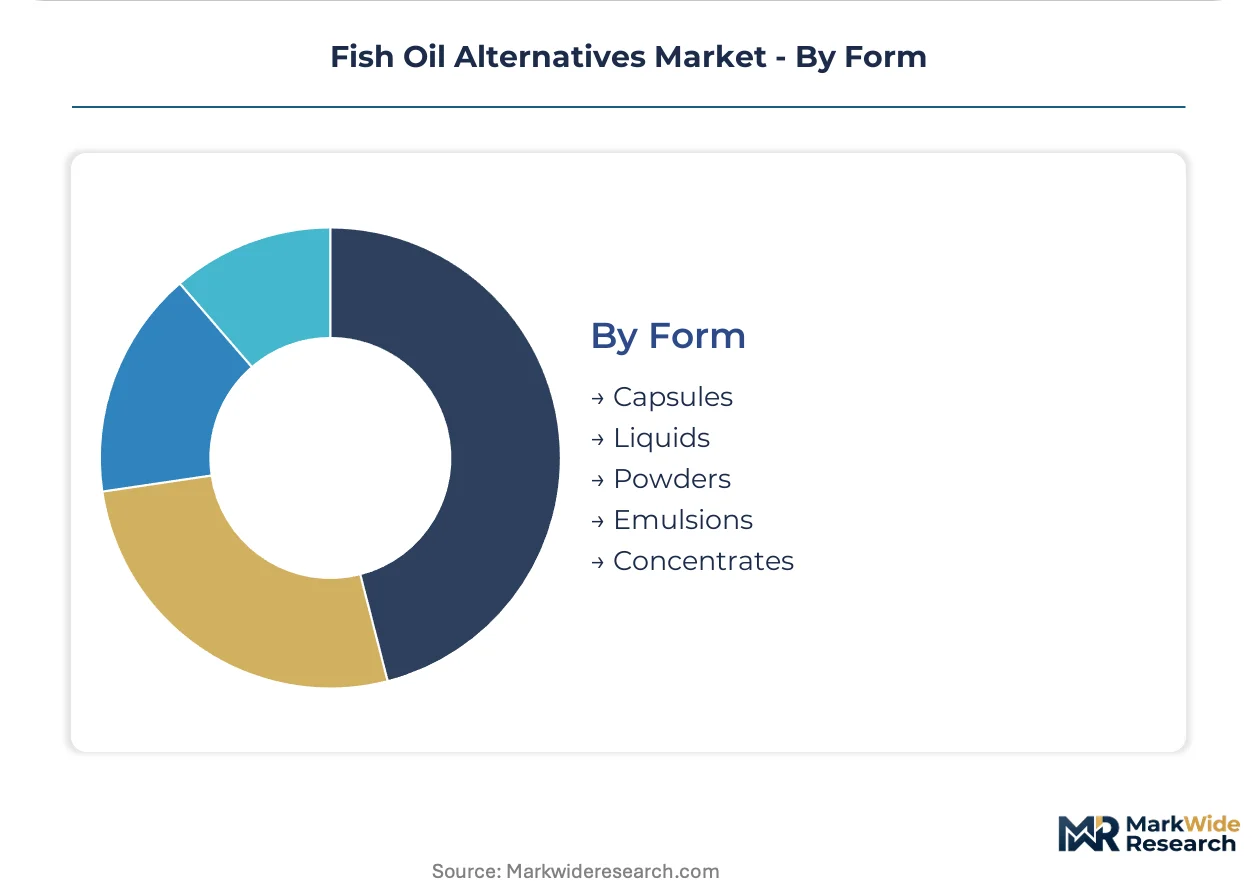
Current production volumes concentrate in Capsules. Technology investment prioritizes Emulsions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's infant formula manufacturers accelerate algal oil transitions faster than United States functional food producers, though both face tightening contaminant thresholds. Japan maintains distinct perilla oil traditions while India liberalizes fortification rules.
United States
Functional food producers in California and Illinois seek omega-3 alternatives free from ocean-borne heavy metals and microplastics. FDA GRAS notifications and EPA water quality standards shape product qualification timelines. DSM-Firmenich biotechnology platforms supply pharmaceutical-grade DHA to medical nutrition formulators in Greater Boston.
Germany
Dietary supplement manufacturers expand algal oil sourcing as EU Green Deal enforcement compresses marine-derived supply chains. ECHA REACH restrictions redirect procurement toward controlled-environment cultivation. Corbion's photobioreactor technology serves infant formula producers in North Rhine-Westphalia with batch-level traceability documentation.
India
FSSAI functional food regulations relax omega-3 fortification limits in dairy and bakery applications across Maharashtra and Gujarat. Domestic algal cultivation pilots reduce import dependency for DHA inputs. Food producers in Karnataka trial microencapsulated powder formats for dry mix integration.
Japan
Traditional perilla oil with rosmarinic acid co-benefits anchors Korean and Japanese functional food fortification channels. METI standards govern novel lipid ingredient safety assessments. Cosmetic formulators in Osaka source traceable algal lipids for clean beauty certification programs targeting premium skincare exports.
United Kingdom
Echium oil cultivation in East Anglia fills mid-tier omega-3-6-9 balanced formulations for vegetarian positioning. EFSA Novel Food timelines constrain European market entry for new marine-derived strains. Veterinary suppliers in Southeast England specify fermentation-derived DHA for premium pet food contaminant-free positioning.
Fish Oil Alternatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with biotechnology platforms commanding pharmaceutical-grade premiums while commodity oilseed processors compete on volume. The vendor base concentrates around three strain engineering platforms with heterotrophic fermentation expertise. Strategic archetypes include integrated oilseed traders, precision fermentation specialists, and closed-system photobioreactor operators. Competitive moves center on backward integration into glucose feedstock sourcing and geographic licensing partnerships for strain IP access.
Within the biotechnology platform tier, DSM-Firmenich and Corbion exemplify divergent cultivation philosophies, with the former leveraging heterotrophic fermentation and the latter advancing closed-system photobioreactor technology. Cargill Incorporated anchors the integrated commodity oilseed archetype, utilizing global infrastructure to secure plant-derived omega supply chains. These three entities represent the dominant competitive anchors shaping how ingredient buyers evaluate sustainability credentials against cost parity in formulation requalification decisions.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Wilmar International Limited |
| DSM-Firmenich |
| Corbion |
| BASF |
| Burcon |
| Prinova Group LLC |
| Nutiva Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal enforcement gates qualified supply for fermentation-derived omega-3 lipids and premium-tier pricing access for batch-traceable algal oil. REACH authorization timelines compress marine-derived availability, forcing ingredient buyers to pay contamination-free premiums for controlled-environment cultivation outputs.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for pharmaceutical-grade algal oil. Pricing stratifies across premium fermentation-derived DHA, standard plant-based ALA sources, and economy flaxseed commodity tiers. Price differentiation hinges on EFSA Novel Food certification status and cGMP compliance documentation. Cost compression in standard plant oils is intensifying because Ukrainian and Canadian seed crop volumes are recovering. Contract manufacturers represent the most price-sensitive buyers, while infant formula producers in North Rhine-Westphalia exhibit lowest sensitivity due to purity mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for European algal oil logistics. Manufacturing concentrates in the Netherlands, Germany, and the United States for fermentation platforms, with India emerging for domestic cultivation pilots. Glucose feedstock, nitrogen inputs, and bioreactor engineering expertise constitute critical dependencies. Single-source vulnerability around Schizochytrium strain IP creates supply risk for second-tier distributors. Distribution runs through ingredient sampling programs and quarterly subscription boxes before volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal marine sourcing restrictions are accelerating demand displacement toward land-based alternatives.
For Market Incumbents: Deploy backward integration into glucose feedstock sourcing to anchor cost structures against agricultural commodity cycles. DSM-Firmenich and Corbion should lock exclusive strain licensing partnerships in India and Southeast Asia before FSSAI liberalization attracts regional competitors. Certification investment in EFSA Novel Food parallel-track submissions defends shelf position against delayed entrants. For New Entrants and Emerging Players: Hospital procurement channels for enteral and parenteral lipid emulsions represent an underserved buyer archetype with pharmaceutical-grade documentation requirements. Medical nutrition formulators in Greater Boston and German hospital systems offer the most penetrable entry point. A go-to-market angle emphasizing batch-level carbon intensity metrics and water stewardship credentials bypasses incumbent cost advantages. For Investors and Strategic Acquirers: Roll-up economics work for precision fermentation platforms because strain engineering talent scarcity and IP fragmentation favor consolidated licensing portfolios. Five-to-ten year viability hinges on dual-use facility qualification for both nutritional and pharmaceutical applications. The signal to watch is EFSA Novel Food approval acceleration for new algal strains as an inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Licensing Partnership | DSM-Firmenich secures exclusive Schizochytrium access in Maharashtra before domestic competitors scale. |
| cGMP Facility Conversion | Photobioreactor infrastructure from biologics manufacturing transfers to food-grade lipid production with pharmaceutical premiums. |
| Subscription Sampling Program | Quarterly ingredient boxes compress supplier qualification cycles for US functional food procurement teams. |
| Glucose Feedstock Integration | Cargill leverages global oilseed infrastructure to secure captive supply for heterotrophic fermentation inputs. |
| EFSA Parallel-Track Submission | Novel Food toxicology and allergenicity assessments run simultaneously to preempt 18-24 month authorization delays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations engaged fermentation biotechnology directors, infant formula procurement managers, EFSA regulatory affairs consultants, and hospital pharmacy formulary committees. Secondary validation drew from EFSA Novel Food approval databases, REACH authorization registries, FSSAI functional food notifications, and SEC filings of listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional regulatory cluster dimensions.
Segment-weighting approaches applied differential growth assumptions across the projection horizon. Modeling incorporated pharmaceutical-grade versus food-grade purity tiers, powder versus emulsion formulation splits, and subscription versus transactional procurement patterns. CAGRs derived from historical trajectory analysis adjusted for regulatory milestone impacts and biotechnology scale-up curves. Industry-specific inputs included heterotrophic fermentation yield improvements and EU Green Deal enforcement intensity scenarios.
Inputs from EFSA, FDA GRAS notification logs, and FSSAI regulatory circulars were available through the study window; gaps in real-time bioreactor capacity utilization data introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding strain engineering advancement rates and marine sourcing restriction timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Sugar Alternative Market