
 Anti-Submarine Warfare Market | 2026-2036
Anti-Submarine Warfare Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Submarine Warfare Market Analysis
Market Context
Defense leasing and performance-based service contracts is fragmenting capital ownership across the Anti-Submarine Warfare ecosystem, allowing mid-tier contractors to field advanced capabilities without balance-sheet concentration. BAE Systems plc leverages its integrated sonar manufacturing and sovereign UK test ranges to sustain long-term service revenue streams. Northrop Grumman Corporation anchors US Navy fixed-wing ASW programs through the MQ-4C Triton maritime surveillance platform. Lockheed Martin Corporation dominates integrated combat system architectures, extending its footprint from platform sensors to fleet-level command networks.
Technical Definition and Segment Structure
Anti-Submarine Warfare encompasses the detection, tracking, classification, and neutralization of hostile submarines through integrated sensor networks, kinetic weapons, and autonomous platforms operating across surface, airborne, and subsurface domains. Primary industrial purpose centers on preserving sea lines of communication and protecting high-value naval assets from undersea threats, with modern systems requiring acoustic processing below 100 Hz in deep-ocean environments and real-time cross-platform data fusion. Sonar Systems commands the largest installed base and recurring modernization spend, while Unmanned Underwater Vehicles represents the fastest-expanding solution category as navies accept autonomous risk in contested waters. Among end users, Naval Forces concentrate procurement authority and dictate interoperability standards, whereas Defense Contractors absorb expanding integration complexity as sovereign shipyards lack capacity for full system-of-systems delivery.
Regulatory Framework and Outlook
The US Navy's Undersea Warfare Directorate, NATO's Maritime Capability Group, and the UK's Defence Equipment and Support agency collectively shape ASW product standards through classified performance specifications and allied interoperability mandates such as the NATO Standardization Agreement 4155 for sonobuoy interfaces. These frameworks restrict market access for non-allied suppliers while creating captive demand cycles for cleared contractors. Stakeholders must monitor how AUKUS technology-sharing protocols reshape supplier eligibility and whether emerging acoustic transparency standards for unmanned platforms open new vendor categories.
Market Dynamics
Autonomous underwater platforms are compressing procurement cycles across NATO naval forces, forcing legacy sonar manufacturers to reconfigure service models around unmanned system integration rather than platform-centric hardware sales.
Growth Catalysts
- AUKUS Technology-Sharing Protocols:Trilateral security arrangements between Australia, the United Kingdom, and the United States are accelerating submarine detection capability transfers and standardizing acoustic sensor interfaces across allied fleets.
- Deep-Ocean Acoustic Processing:Signal processing below 100 Hz in contested Indo-Pacific waters enables detection of next-generation quiet submarines, driving refresh demand for hull-mounted and towed array sonar systems.
- Distributed Maritime Operations Doctrine:US Navy operational concepts mandate networked sensor grids spanning multiple platforms, creating pull-through demand for interoperable command-and-control architectures.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium dependencies for advanced sonar transducers concentrate in single-source refining operations, exposing contractors to input volatility and sovereign export controls.
- Classified Integration Standards:NATO Standardization Agreement 4155 and allied interoperability mandates restrict vendor eligibility to security-cleared suppliers, blocking non-allied technology providers from sensor network procurement.
- Acoustic Signature Transparency Requirements:Unmanned underwater vehicle platforms must meet stringent self-noise thresholds that exceed current commercial-off-the-shelf propulsion capabilities, extending development timelines.
Strategic Opportunities
- Indo-Pacific Layered Architectures:Japan, South Korea, and Australia are constructing multi-domain ASW networks combining fixed seabed sensors, autonomous gliders, and aerial platforms, opening integration contracts for system-of-systems providers.
- Performance-Based Service Contracts:Defense leasing models shift capital ownership from sovereign navies to prime contractors, enabling recurring revenue streams for through-life sensor maintenance and software updates.
- Dual-Use Acoustic Transparency Standards:Emerging civilian regulations for offshore wind farm environmental monitoring are converging with military low-noise specifications, creating common technical baselines for sensor manufacturers.
Industry Challenges
- Acoustic Systems Engineering Talent Scarcity:Specialized expertise in ocean acoustics, signal processing, and undersea hydrodynamics concentrates in aging workforce cohorts at national laboratories and legacy defense primes.
- Legacy Combat System Integration Friction:New autonomous platforms must interface with shipboard combat management systems designed decades prior, requiring costly middleware development and extended sea trial validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Submarine Warfare Market |
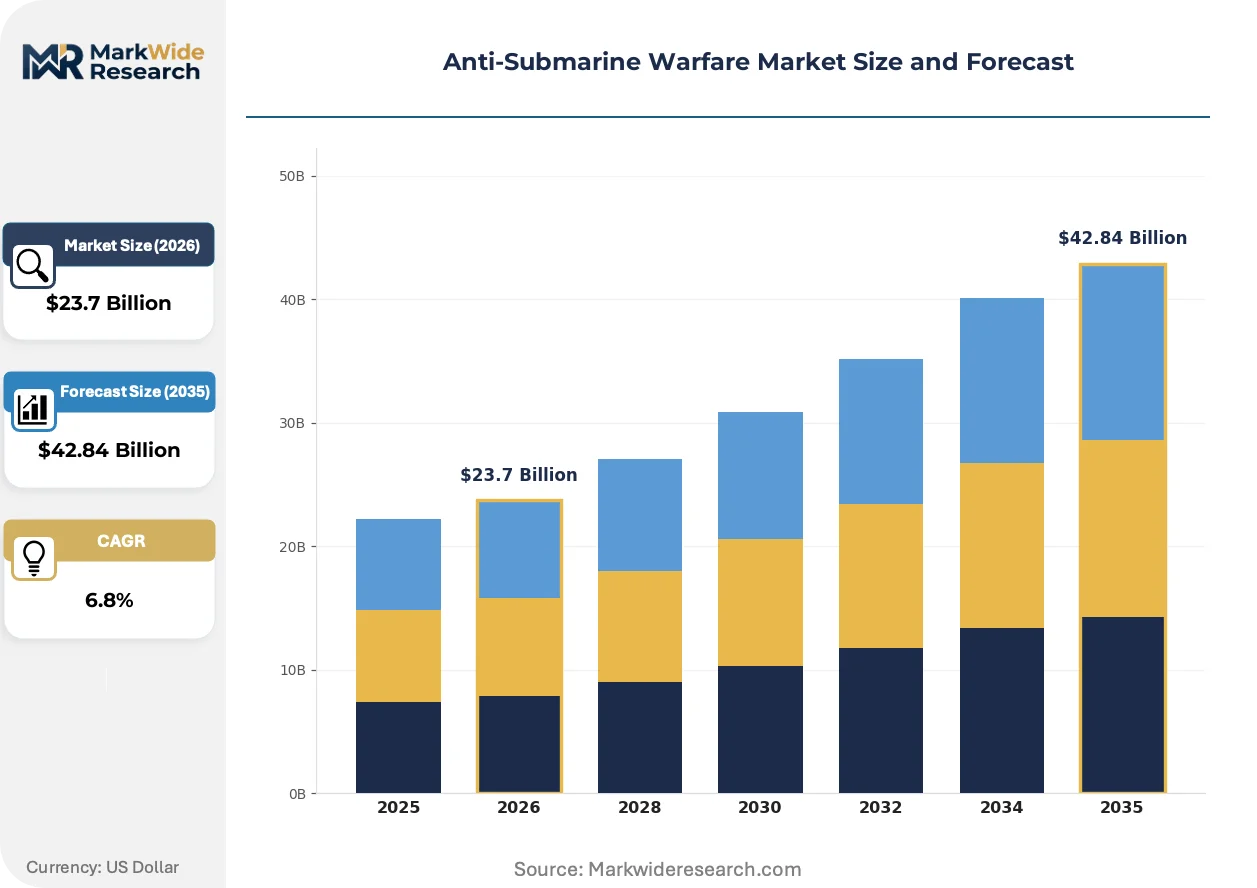
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Sonar Systems, Torpedoes, Unmanned Underwater Vehicles, Surveillance Systems End User: Naval Forces, Coast Guard, Defense Contractors, Research Institutions Technology: Active Sonar, Passive Sonar, Electromagnetic Waves, Fiber Optics Application: Coastal Defense, Anti-Submarine Operations, Maritime Surveillance, Search and Rescue |
| Companies Covered | BAE Systems plc, Northrop Grumman Corporation, Lockheed Martin Corporation, Saab AB, L3Harris Technologies Inc., RTX Corporation, General Dynamics Corporation, Ultra Maritime, Thales S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Submarine Warfare Market Emerging Trajectories
Artificial intelligence is restructuring how raw acoustic data converts into actionable targeting information, compressing the sensor-to-shooter timeline from hours to minutes while reducing operator cognitive load.
Machine-learning classification algorithms are digitizing passive sonar signal processing, replacing rule-based detection methods with neural network pattern recognition. Naval forces in the United States and United Kingdom are fielding these capabilities on Virginia-class and Astute-class submarines. This transition is digitizing acoustic intelligence workflows, enabling single operators to monitor multiple frequency bands simultaneously.
The EU Green Deal's sustainability disclosure requirements are extending to defense industrial base suppliers through the Corporate Sustainability Reporting Directive, mandating carbon footprint documentation for sonar array manufacturing. Tier-1 contractors must now trace rare earth magnet sourcing and underwater testing range environmental impact. Surface ship sonar integration programs face the steepest compliance cost adjustments.
Buyer organizations are consolidating sensor procurement authority under fleet-level capability managers, displacing platform-specific program offices. The US Navy's Unmanned Maritime Systems program office now controls cross-platform autonomous vehicle acquisitions, compressing vendor access points. This concentration is most visible in P-8 Poseidon maritime patrol aircraft and MQ-4C Triton unmanned system sustainment contracts.
Anti-Submarine Warfare Market Segmentation
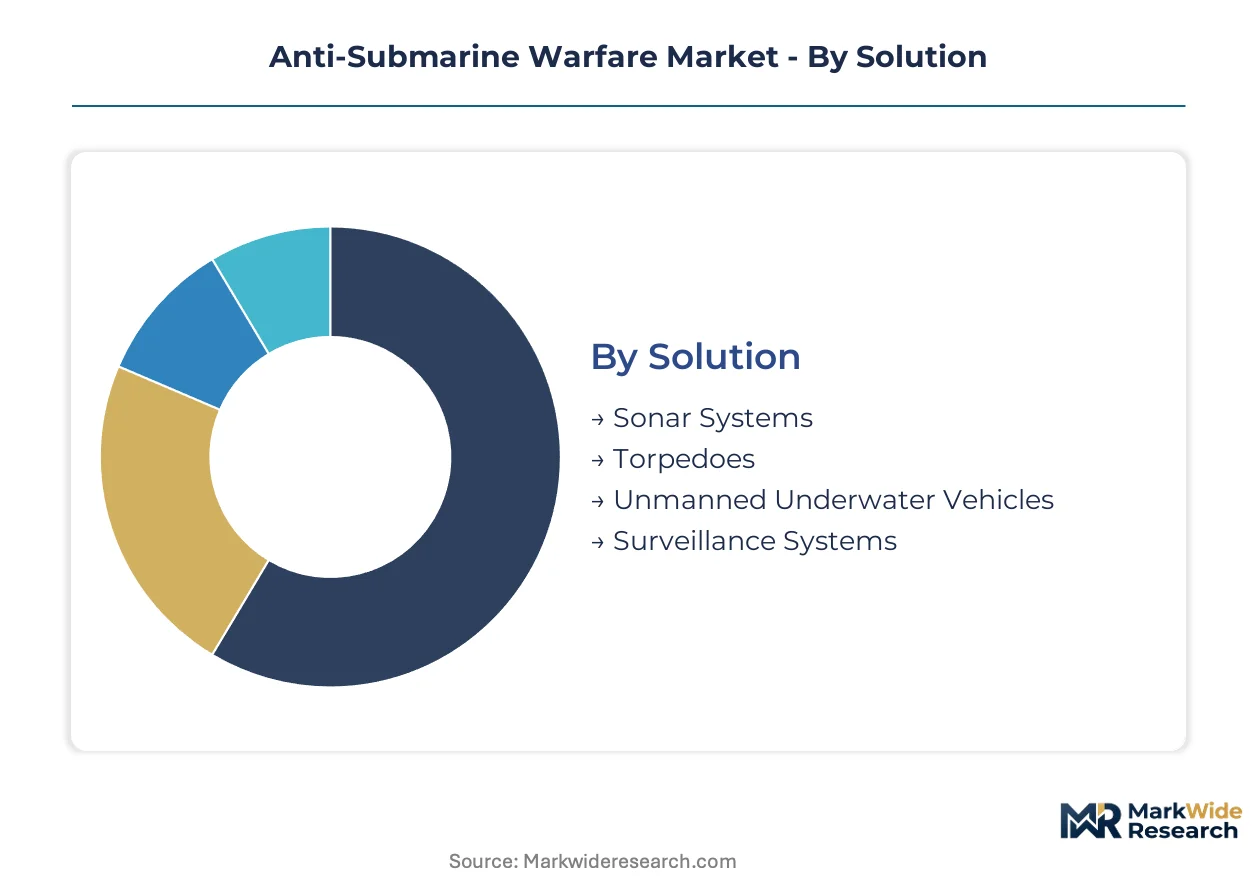
ASW procurement fragments across mission profiles, platform types, and sovereign capability requirements. Solution architecture, end-user command structures, sensor modalities, and operational applications each reshape vendor access points and contract structures.
Solution:
Use-case spectrum spans legacy platform integration through fully autonomous networked systems.
- Sonar Systems:Hull-mounted, towed array, and dipping sonar configurations process acoustic signals below 100 Hz for deep-ocean detection. US Navy Virginia-class submarines and Royal Navy Astute-class vessels drive refresh demand as NATO fleets modernize acoustic processing chains.
- Unmanned Underwater Vehicles:Autonomous gliders and propeller-driven platforms execute persistent seabed surveillance without risking crewed assets. Japan, Australia, and South Korea are deploying layered UUV architectures across contested Indo-Pacific chokepoints, compressing procurement cycles for autonomous integration specialists.
- Torpedoes:Wire-guided and autonomous homing weapons deliver kinetic neutralization against detected submarines. Naval forces prioritize wake-homing and shallow-water variants for littoral operations.
- Surveillance Systems:Fixed seabed sensor networks and aerial maritime patrol platforms fuse multi-source intelligence into fleet-level command architectures.
The dominant share belongs to Sonar Systems, while Unmanned Underwater Vehicles is closing the gap fastest.
End User:
Procurement authority concentrates where operational risk and classified system access intersect.
- Naval Forces:Sovereign navies dictate interoperability standards and control classified integration specifications. The US Navy's distributed maritime operations doctrine and NATO's Maritime Capability Group shape ASW product requirements across allied fleets.
- Defense Contractors:Prime integrators absorb system-of-systems complexity as sovereign shipyards lack capacity for full combat system delivery. Performance-based service contracts shift capital ownership from navies to contractors, creating recurring revenue streams for through-life sensor maintenance.
- Coast Guard:Maritime law enforcement agencies procure scaled-down ASW capabilities for Exclusive Economic Zone patrol and port security missions.
- Research Institutions:National laboratories and university consortia develop acoustic processing algorithms and undersea hydrodynamics expertise, though aging workforce cohorts constrain talent pipelines.
Naval Forces command the largest procurement volumes, though Defense Contractors are capturing expanding integration value.
Technology:
Sensor modality selection trades detection range against platform vulnerability and processing load.
- Passive Sonar:Acoustic receivers detect submarine radiated noise without emitting detectable signals. Machine-learning classification algorithms are digitizing passive processing workflows, enabling single operators to monitor multiple frequency bands on US and UK submarines.
- Active Sonar:Projected acoustic pulses generate target returns but risk platform detection. Hull-mounted and dipping configurations dominate surface ship and rotary-wing applications where stealth is less critical.
- Electromagnetic Waves:Magnetic anomaly detection and radar systems supplement acoustic methods for periscope and snorkel identification.
- Fiber Optics:Towed array data transmission and seabed sensor networking exploit low-loss optical signaling for high-bandwidth underwater communications.
Passive Sonar retains the largest installed base, while Active Sonar is gaining share through unmanned platform proliferation.
Application:
Mission type determines sensor mix, platform allocation, and command architecture requirements.
- Anti-Submarine Operations:Dedicated prosecution of hostile submarines through detection, tracking, classification, and neutralization sequences. The Indo-Pacific submarine fleet buildouts by multiple nations require layered architectures combining fixed seabed sensors, autonomous gliders, and aerial platforms.
- Maritime Surveillance:Broad-area sea control missions protecting sea lines of communication. The US Navy's MQ-4C Triton and P-8 Poseidon programs anchor fixed-wing ASW and surface surveillance integration.
- Coastal Defense:Littoral zone protection against submarine incursion and mine threats. Shallow-water acoustic propagation challenges drive demand for specialized sonar processing.
- Search and Rescue:Submarine escape and distressed vessel location missions utilizing side-scan sonar and underwater locator beacons.
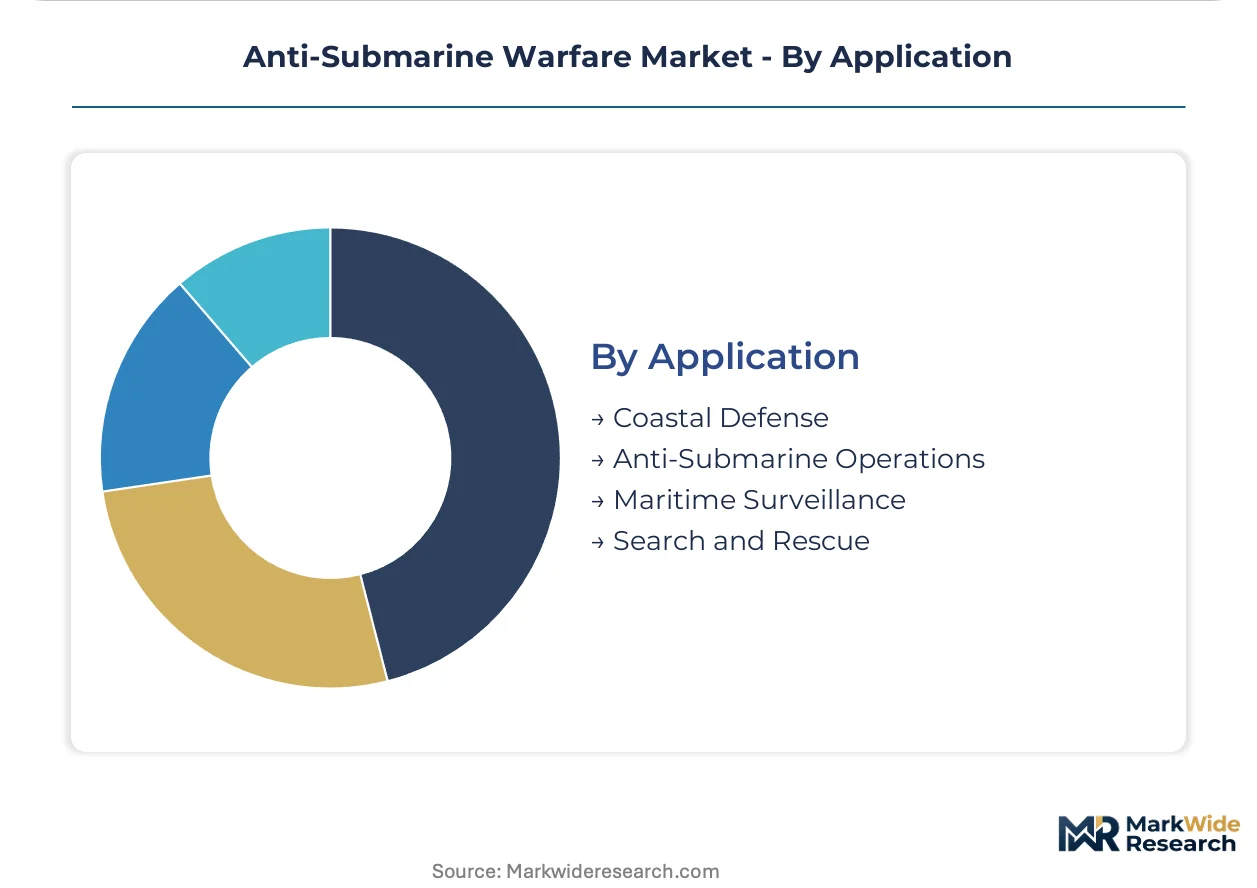
Anti-Submarine Operations absorbs the dominant procurement priority, though Maritime Surveillance is expanding most quickly through unmanned platform fielding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Navy's distributed maritime operations doctrine and AUKUS technology-sharing protocols are reshaping procurement patterns across allied naval forces. Sovereign capability requirements and classified integration standards concentrate investment in specific national industrial bases.
United States
The US Navy drives the largest ASW modernization spend through Virginia-class submarine sonar refreshes and MQ-4C Triton unmanned system fielding. The Undersea Warfare Directorate shapes NATO interoperability standards through classified performance specifications. Industrial concentration clusters around Baltimore-Washington defense corridor and southeastern shipyards in Virginia and Mississippi.
United Kingdom
Royal Navy Astute-class acoustic processing upgrades and AUKUS submarine commitments sustain sovereign test range utilization at Clyde and Portland. The UK's Defence Equipment and Support agency mandates supplier security clearances through the UK-US Mutual Defence Agreement. BAE Systems plc anchors integrated sonar manufacturing at Portsmouth and Glasgow facilities.
Australia
AUKUS nuclear-powered submarine acquisition and layered Indo-Pacific surveillance architectures accelerate autonomous platform procurement. The Department of Defence's Sovereign Guided Weapons and Explosive Ordnance Enterprise reshapes local integration requirements. Industrial activity concentrates at Henderson shipyard complex in Western Australia and Adelaide's Osborne naval precinct.
Japan
Maritime Self-Defense Force investments in fixed seabed sensor networks and autonomous glider deployments address Chinese submarine fleet expansion. METI's defense industrial base policies restrict foreign vendor access to critical acoustic technologies. Manufacturing and integration capabilities cluster around Kobe and Yokosuka naval industrial zones.
South Korea
Navy KSS-III submarine program and coastal defense sonar modernization drive hull-mounted and towed array procurement. The Defense Acquisition Program Administration prioritizes indigenous combat system development through offset arrangements. ASW industrial capabilities concentrate at DSME and HHI shipyards in Geoje and Ulsan.
Anti-Submarine Warfare Market Vendor Landscape
Channel-controlling players compete with product-specialist players across platform integration, sensor manufacturing, and autonomous system domains. The market exhibits tiered consolidation where prime contractors absorb system-of-systems complexity while mid-tier suppliers capture component-level recurring revenue. Two strategic archetypes dominate: vertically integrated platform integrators and specialized acoustic sensor houses. Competitive moves center on performance-based service contract capture and unmanned platform integration partnerships.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the integrated combat system archetype, while BAE Systems plc represents the sovereign-nation specialist model with UK test range control. These three entities occupy positions spanning platform sensors through fleet-level command architectures, reflecting the market's bifurcation between scale-driven integration and geographically captive capability delivery.
| Leading Market Players |
|---|
| BAE Systems plc |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Saab AB |
| L3Harris Technologies Inc. |
| RTX Corporation |
| General Dynamics Corporation |
| Ultra Maritime |
| Thales S.A. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in rare earth magnet refining operations across China and Myanmar is compressing margins for advanced sonar transducer manufacturers while simultaneously elevating pricing power for cleared defense contractors with captive supply arrangements. This utilization squeeze propagates through NATO procurement cycles, forcing tier-1 integrators to absorb cost volatility or pass through to performance-based service contracts.
Pricing Analysis
Certification level (NATO STANAG 4155 compliance and national security clearance tier) creates the primary spread between qualified suppliers and commercial-off-the-shelf vendors. Three-tier pricing structure across fully-cleared, dual-use, and commercial-grade levels dominates sonar system procurement, with hull-mounted arrays commanding premium positioning due to integration complexity. Cost compression in unmanned underwater vehicle sensor packages is intensifying because commercial propulsion manufacturers lack acoustic signature transparency expertise. Naval Forces exhibit lowest price sensitivity given mission-critical requirements and classified performance mandates, whereas research institutions face strict budget ceilings that favor dual-use acoustic components.
Supply Chain Analysis
Contract manufacturing concentration rests with sovereign shipyards in the United States, United Kingdom, and Australia that retain classified facility clearances for combat system integration. Rare earth magnet dependencies draw from Chinese and Burmese refining operations, while fiber optic towed array cabling sources from Japanese and German specialty manufacturers. Single-source vulnerability in neodymium-dysprosium supply chains exposes contractors to export control disruptions and sovereign resource nationalism. Distribution runs through national defense equipment agencies—US Navy's NAVSEA, UK Defence Equipment and Support, Australia's Department of Defence—that gate vendor access via security clearance protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating under fleet-level capability managers, displacing platform-specific program offices and compressing vendor access points to a handful of cross-domain procurement authorities.
For Market Incumbents: Pre-empt autonomous platform integration friction by acquiring middleware specialists with legacy combat system interface expertise. Threat substitution from machine-learning acoustic classification algorithms demands accelerated R&D investment in neural network pattern recognition for passive sonar processing. Backward integration into rare earth magnet supply through offtake agreements with Australian and Canadian mining ventures reduces input volatility exposure. For New Entrants and Emerging Players: Pursue dual-use acoustic transparency standards convergence between offshore wind environmental monitoring and military low-noise specifications as the most penetrable entry vector. White-space exists in civilian-military sensor manufacturing where emerging regulations create common technical baselines. Go-to-market angle centers on supplying commercial glider platforms to research institutions, then certifying upward through defense agency security clearance pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among performance-based service contractors with through-life sensor maintenance obligations and software update entitlements. Long-term viability over the medium-term horizon favors cleared integrators with sovereign test range control and NATO interoperability mandate compliance. Acquisition target archetype: mid-tier acoustic sensor houses with aging workforce expertise in ocean acoustics and signal processing. Signal to monitor: AUKUS technology-sharing protocol expansions beyond trilateral core that reshape supplier eligibility pools.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Platform Integration Partnership | BAE Systems and Northrop Grumman anchor unmanned system architectures through MQ-4C Triton and Astute-class sonar refresh programs. |
| Performance-Based Service Contract Capture | Lockheed Martin extends fleet-level command network footprints via recurring software update revenue streams. |
| Rare Earth Supply Security Arrangement | RTX Corporation and Ultra Maritime reduce neodymium-dysprosium exposure through Australian mining joint ventures. |
| Machine Learning Acoustic Classification Investment | Thales S.A. and L3Harris digitize passive sonar workflows for Virginia-class and Astute-class submarine deployments. |
| Indo-Pacific Layered Architecture Expansion | Saab AB and General Dynamics capture integration contracts for Japan-South Korea-Australia multi-domain sensor networks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with US Navy Undersea Warfare Directorate program managers, Royal Navy acoustic systems engineers, BAE Systems sonar manufacturing directors, and Australian Department of Defence procurement officers. Secondary validation drew from NATO Standardization Agreement documentation, US Congressional Research Service naval modernization reports, UK National Audit Office defense equipment assessments, and AUKUS trilateral communiqués. Bottom-up segment sizing across sonar systems, unmanned underwater vehicles, torpedoes, and surveillance platforms was triangulated against top-down defense budget allocation analysis.
Calibration against historical procurement cycles and announced modernization timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass solution architecture, end-user command structure, sensor modality technology, and operational application mission type. CAGRs were derived through regression analysis of defense capital expenditure trajectories and technology refresh cycle compression rates. Industry-specific forecast inputs included AUKUS submarine delivery schedules and Indo-Pacific seabed sensor network deployment announcements.
Sensitivities concentrate around AUKUS protocol expansion scope, rare earth export control enforcement intensity, and autonomous platform acoustic signature threshold revisions. Forecasts embed assumptions regarding allied interoperability mandate continuity and sovereign shipyard capacity constraints. Quarterly review of NATO Maritime Capability Group procurement directives and METI defense industrial base policy adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Marine Penetrators Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Military Frigate Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Combat Management System Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Naval Artillery System Market