
 Naval Vessels and Surface Combatants Market | 2026-2036
Naval Vessels and Surface Combatants Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Vessels and Surface Combatants Market Analysis
Integrated electric propulsion and modular mission payload architectures is tilting warship design away from single-purpose hulls toward reconfigurable combatants. BAE Systems leverages its Type 26 Global Combat Ship program to anchor UK and Australian frigate modernization with integrated sonar and radar suites. General Dynamics Corporation sustains US Navy destroyer construction through its Bath Iron Works yard, competing for Arleigh Burke-class follow-on contracts. Mitsubishi Heavy Industries dominates Japan's surface combatant pipeline, specializing in stealth-optimized destroyer designs with domestic AEGIS integration.
Naval vessels and surface combatants are steel-hulled or composite-reinforced warships displacing 1,500 to 10,000+ tonnes, engineered for sustained blue-water operations with integrated weapons, sensor, and propulsion systems operating at speeds exceeding 25 knots. Their primary purpose is sea control, force projection, and layered defense against submarine, air, and surface threats in contested maritime environments. Frigates represent the fastest-expanding vessel type as navies prioritize lower-cost, multi-role hulls for constabulary and escort duties alongside high-end operations. Composite materials and hybrid structures are gaining share in superstructure fabrication where radar cross-section reduction and weight savings offset higher fabrication costs. Command and control systems integration now constitutes the dominant margin pool, exceeding hull and mechanical systems in contract value for major combatant programs.
The US Navy's shipbuilding certification requirements, the UK Ministry of Defence's Defence Standardization, and NATO's STANAG interoperability protocols collectively dictate combat system architecture, sensor fusion standards, and cross-fleet logistics compatibility for Western-aligned programs. China's SAMR and GB military shipbuilding standards enforce sovereign supply chain controls that constrain foreign subsystem participation in domestic programs. Procurement authorities must weigh modular upgrade pathways against platform longevity commitments as directed-energy weapons and hypersonic defense requirements mature on divergent timelines.
Market Dynamics
Integrated electric propulsion architectures are compressing the design-to-delivery cycle for surface combatants while simultaneously elevating power budgets for directed-energy weapons and high-bandwidth sensor fusion.
Growth Catalysts
- NATO STANAG Interoperability Mandates:Cross-fleet logistics compatibility requirements are standardizing combat system architectures across allied navies, reducing integration costs for multi-national procurement programs.
- Submarine Proliferation in the Indo-Pacific:Undersea threat density is compelling Australia, Japan, and South Korea to expand destroyer and frigate orders with integrated anti-submarine warfare suites.
- Directed-Energy Weapon Maturation:Solid-state laser programs are creating new power-generation requirements that favor integrated electric propulsion over mechanical drive systems.
Market Restraints
- Specialized Steel Alloy Supply Concentration:HY-80 and HY-100 high-yield steel production concentrates in a limited number of qualified domestic mills, constraining hull fabrication throughput.
- China's SAMR Sovereign Supply Chain Controls:GB military shipbuilding standards enforce captive subsystem participation that constrains foreign technology access to the People's Liberation Army Navy procurement pipeline.
- Extended Combat System Integration Timelines:AEGIS and comparable integrated air defense systems require 18-24 month shore-based testing periods that extend delivery schedules beyond contractual baselines.
Strategic Opportunities
- Modular Mission Payload Architectures:Containerized weapon and sensor modules are enabling hull-form standardization across constabulary and high-intensity variants, reducing unit production costs.
- UK Ministry of Defence Type 26 Export Pipeline:The Global Combat Ship program's Australian and Canadian selections are establishing a multi-national production base with shared qualification costs.
- Composite Superstructure Fabrication:Radar cross-section reduction requirements are expanding addressable market share for carbon-fiber reinforced polymer suppliers in mast and enclosure construction.
Industry Challenges
- Combat Systems Software Integration Complexity:Multi-vendor sensor fusion architectures require sustained government-furnished equipment coordination that delays sea trials.
- Skilled Welder and Pipefitter Labor Scarcity:Naval shipyard workforces face demographic compression as experienced trades retire faster than apprenticeship pipelines replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Vessels and Surface Combatants Market |
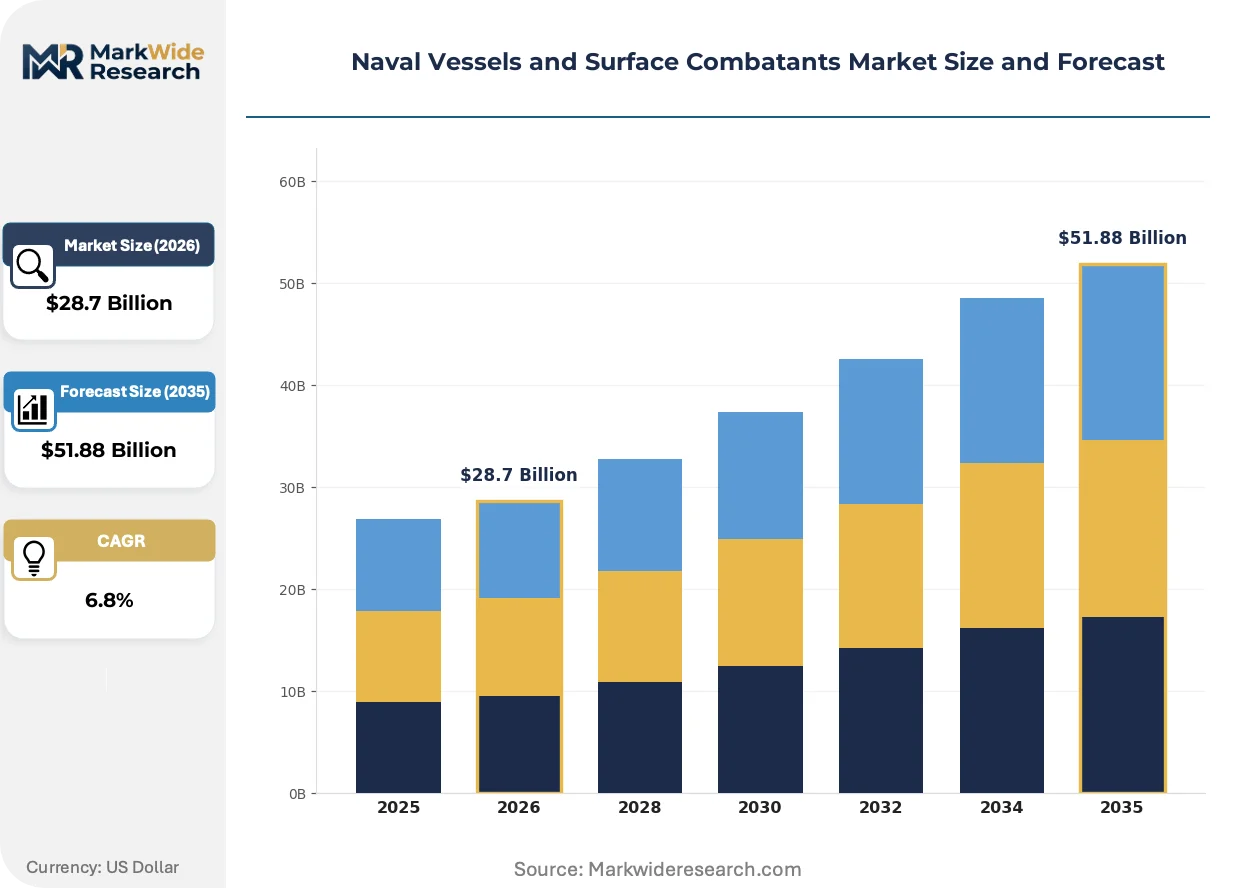
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Frigates, Destroyers, Corvettes, Amphibious Assault Ships Construction Material: Steel, Aluminum, Composite Materials, Hybrid Structures Operational Role: Anti-Submarine Warfare, Surveillance, Naval Gunfire Support, Anti-Air Warfare Technology Integration: Command & Control Systems, AEGIS, Surface-to-Air Missiles, Sonar Systems |
| Companies Covered | BAE Systems, Naval Group, Hyundai Heavy Industries Co., Ltd., Samsung Heavy Industries, Thales Group, China State Shipbuilding Corporation, General Dynamics Corporation, Huntington Ingalls Industries, Mitsubishi Heavy Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Vessels and Surface Combatants Market Emerging Trajectories
Distributed maritime operations doctrine is fragmenting sensor and strike capabilities across smaller hulls, elevating data-link reliability and autonomous system coordination above raw platform displacement.
Integrated electric propulsion is digitizing power distribution from centralized turbine generators to zonal load centers. The US Navy's DDG(X) program and UK Type 26 frigates are adopting this architecture to enable 75-plus megawatt power budgets. This shift is digitizing combat system upgrade pathways by decoupling propulsion and sensor power allocation from mechanical shaft constraints.
REACH and RoHS substance restrictions are constraining anti-fouling coating formulations and electrical component solder compositions in European naval programs. ECHA authorization requirements are accelerating substitution of legacy chromate primers with cerium-based alternatives. German and French surface combatant programs are responding through qualified supplier development for compliant material specifications.
Multi-year vessel procurement contracts are compressing supplier pricing visibility and fragmenting risk allocation between prime contractors and subsystem vendors. The US Navy's block-buy arrangements for Arleigh Burke-class destroyers are displacing annual negotiated pricing with fixed escalation mechanisms. This pattern is most visible in Bath, Maine and Pascagoula, Mississippi production facilities where material cost pass-through clauses have narrowed.
Naval Vessels and Surface Combatants Market Segmentation
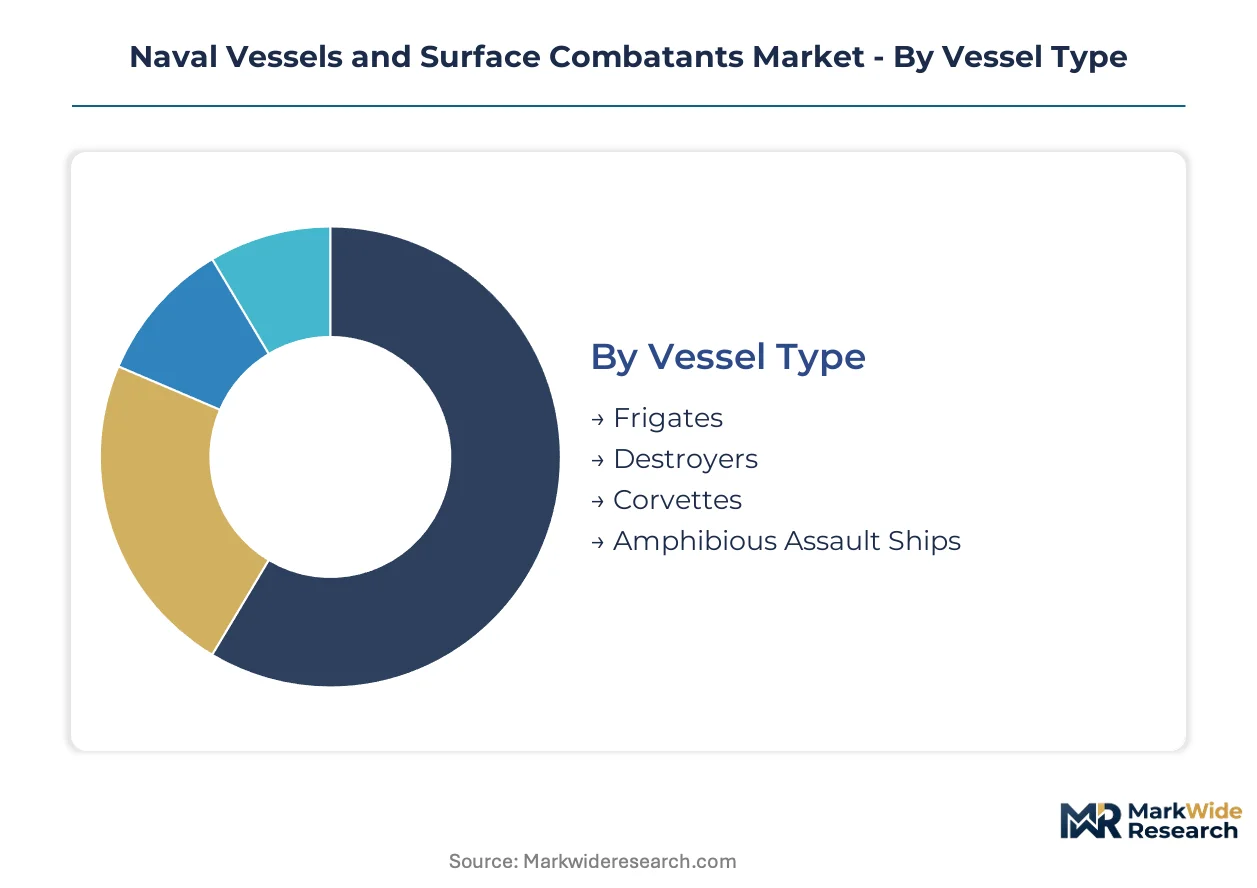
Segmentation in naval vessels reflects divergent procurement priorities between high-intensity combat requirements and constabulary presence missions. Platform architecture, material selection, and combat system integration each create distinct supplier ecosystems and upgrade pathways that shape contract structures.
Vessel Type:
Naval procurement spans constabulary patrol through carrier strike group escort, with displacement and combat system density determining construction yard specialization and program timelines.
- Frigates:Multi-role hulls displacing 3,000 to 7,000 tonnes with modular mission bays for anti-submarine, surface, and limited air defense roles. Australia's Hunter-class and Canada's River-class orders under the Type 26 program demonstrate how frigates concentrate Indo-Pacific demand for lower-cost, adaptable platforms that balance presence missions with high-end warfare requirements.
- Destroyers:Large surface combatants exceeding 8,000 tonnes with integrated air defense suites and 90-plus vertical launch cells. Japan's Maya-class and South Korea's KDX-III Batch II programs illustrate destroyer demand driven by AEGIS integration requirements and ballistic missile defense missions in contested East Asian waters.
- Corvettes:Compact 1,500 to 3,000 tonne hulls optimized for littoral operations and exclusive economic zone patrol.
- Amphibious Assault Ships:Aviation-capable platforms supporting expeditionary force projection and humanitarian response.
Established volume favors destroyers; emerging adoption favors frigates.
Construction Material:
Material selection trades structural longevity against signature management and through-life maintenance costs, with regulatory constraints on coating systems increasingly influential.
- Steel:HY-80 and HY-100 high-yield alloys remain dominant for pressure hulls and load-bearing structures in major combatants, with fabrication constrained to qualified domestic mills under military certification regimes.
- Composite Materials:Carbon-fiber reinforced polymers enable radar cross-section reduction in mast and superstructure applications where electromagnetic transparency outweighs ballistic protection requirements.
- Aluminum:Weight-critical superstructure elements in littoral combatants where corrosion management protocols address galvanic coupling with steel hulls.
- Hybrid Structures:Combined material architectures optimizing steel strength with composite signature performance in next-generation frigate designs.
Steel retains procurement dominance; composite applications are climbing the fastest.
Operational Role:
Mission specialization determines sensor and weapons fit, with multi-role platforms commanding premium pricing against single-purpose hulls.
- Anti-Submarine Warfare:Integrated sonar suites, variable-depth towed arrays, and torpedo countermeasures define hull-form requirements for quiet operation and acoustic superiority.
- Anti-Air Warfare:AEGIS and comparable integrated air defense systems with phased-array radar and cooperative engagement capability represent the highest-margin combat system category.
- Surveillance:Intelligence-gathering configurations prioritizing signals intercept, electro-optical sensors, and extended endurance over kinetic weapons density.
- Naval Gunfire Support:Shore bombardment missions requiring large-caliber gun systems and precision munitions integration for expeditionary operations.
Anti-air warfare commands unit premiums; anti-submarine configurations are gaining share fastest.
Technology Integration:
Combat system architecture now exceeds hull and mechanical costs in major programs, with software integration timelines driving delivery risk.
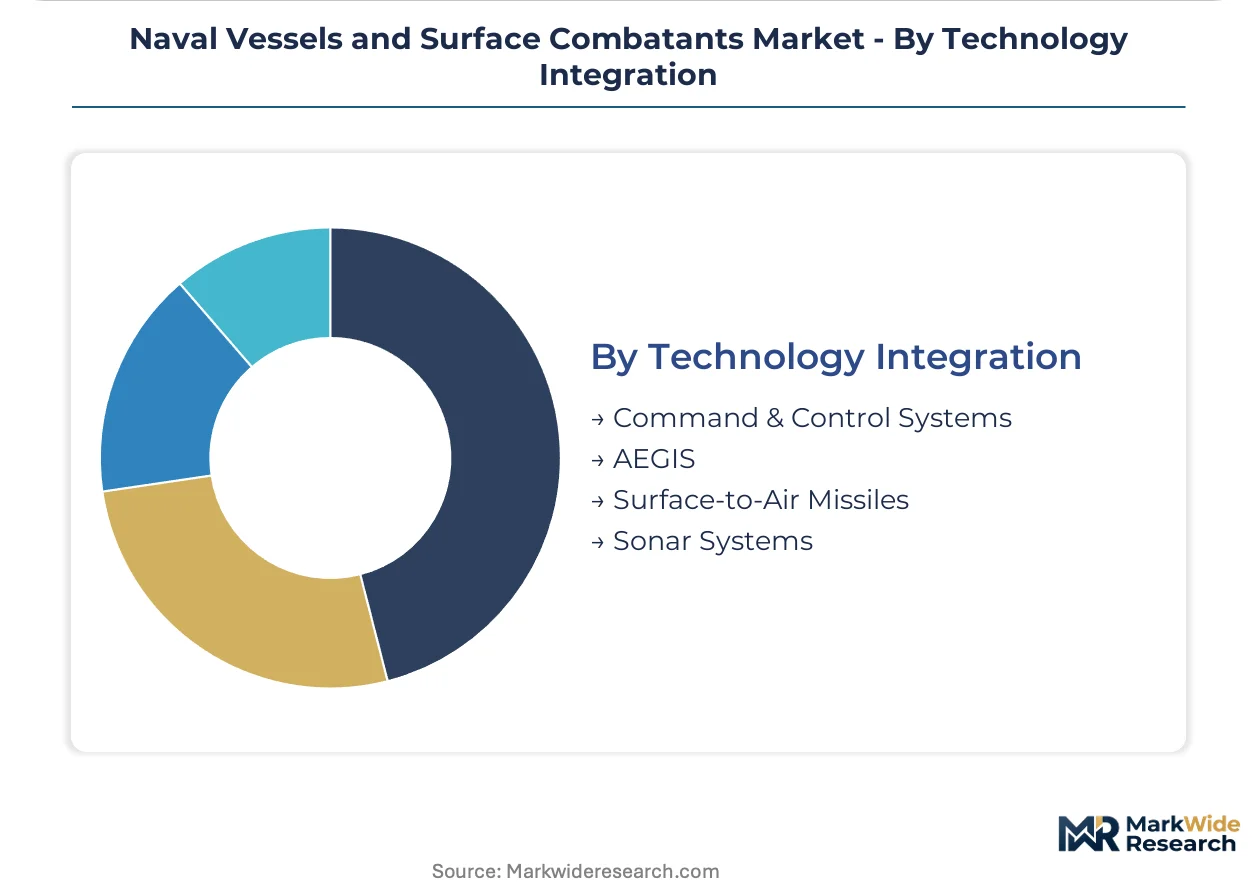
- Command & Control Systems:Multi-sensor fusion and distributed decision-support software integrating platform and off-board data into unified tactical pictures.
- AEGIS:Lockheed Martin's integrated combat system with AN/SPY radar and Mk 41 vertical launch system, requiring 18-24 month shore-based testing periods that extend delivery schedules.
- Surface-to-Air Missiles:Evolved Sea Sparrow, Standard Missile, and comparable interceptors with active radar seekers and network-enabled targeting.
- Sonar Systems:Hull-mounted, towed, and dipping sonar configurations for undersea threat detection and torpedo defense.
AEGIS integration dominates program value; command and control systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement authorities in the United States, United Kingdom, Japan, Australia, and South Korea concentrate the majority of surface combatant demand through sovereign shipbuilding programs and multi-national platform collaborations.
United States
The US Navy's distributed maritime operations doctrine and DDG(X) next-generation destroyer program drive demand for integrated electric propulsion and 75-plus megawatt power architectures. The Department of Defense's National Defense Industrial Strategy mandates domestic sourcing for critical submarine and surface combatant components. Bath Iron Works in Maine and Ingalls Shipbuilding in Mississippi anchor US destroyer construction, with both facilities operating at capacity under multi-year block-buy arrangements.
United Kingdom
The Royal Navy's Type 26 Global Combat Ship program and Type 83 destroyer replacement sustain demand for advanced sonar integration and modular mission systems. The UK Ministry of Defence's Defence Standardization protocols enforce NATO STANAG interoperability requirements across combat system architectures. Glasgow's shipyards on the River Clyde concentrate frigate fabrication, with BAE Systems' Govan facility delivering hulls for domestic and Australian export programs.
Japan
Maritime Self-Defense Force destroyer procurement responds to ballistic missile defense missions and submarine proliferation in contested East Asian waters. METI's defense production base maintenance policies preserve domestic warship construction capabilities through licensed technology arrangements. Nagasaki's Mitsubishi Heavy Industries shipyard specializes in stealth-optimized Maya-class destroyers with integrated domestic AEGIS combat systems.
Australia
The Royal Australian Navy's Hunter-class frigate program under the SEA 5000 procurement generates demand for nine Type 26-derived hulls with anti-submarine warfare specialization. Defence and Strategic Goods List regulations control technology transfer frameworks for combat system integration. Osborne in South Australia hosts the national shipbuilding hub, where ASC Shipbuilding coordinates hull construction with UK design authority support.
South Korea
The Republic of Korea Navy's KDX-III Batch II destroyer program and KDDX next-generation frigate initiative address North Korean submarine threats and regional maritime disputes. Defense Acquisition Program Administration guidelines prioritize indigenous combat system development while permitting selective foreign subsystem procurement. Busan's Hyundai Heavy Industries and Samsung Heavy Industries yards dominate domestic surface combatant output, with both expanding into international frigate export markets.
Naval Vessels and Surface Combatants Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated market structure where national champions dominate sovereign procurement pipelines. Prime contractors integrate hull fabrication, combat systems, and through-life support under single-contract arrangements that exclude pure-play subsystem vendors from platform-level awards. Three archetypes prevail: state-owned shipbuilding conglomerates with captive domestic demand, diversified defense contractors with multi-domain portfolios, and specialist naval architects with platform-design authority. Competitive dynamics center on strategic partnerships for technology access and geographic expansion through export program participation.
Within the state-owned tier, China State Shipbuilding Corporation exemplifies vertically integrated production spanning military and commercial output. Among diversified Western contractors, BAE Systems and General Dynamics Corporation occupy positions as national champions with design authority over major combatant classes. Hyundai Heavy Industries Co., Ltd. and Mitsubishi Heavy Industries, Ltd. represent Asia-Pacific fabricators combining domestic naval construction with commercial shipbuilding scale. These entities anchor competitive positioning through platform-level program wins rather than subsystem specialization.
| Leading Market Players |
|---|
| BAE Systems |
| Naval Group |
| Hyundai Heavy Industries Co., Ltd. |
| Samsung Heavy Industries |
| Thales Group |
| China State Shipbuilding Corporation |
| General Dynamics Corporation |
| Huntington Ingalls Industries |
| Mitsubishi Heavy Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors connecting Korean and Japanese steel mills to Australian and US West Coast shipyards transmit raw material cost volatility directly into hull fabrication pricing, while concentrated HY-80 alloy supply tightens contractor margins and forces tiered contract structures that separate NATO STANAG-compliant programs from non-aligned procurement.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics producer price index escalation dominate major combatant programs, separating AEGIS-integrated destroyer premiums from corvette economy tiers. Price differentiation rests on combat system certification grade and sovereign content requirements. Cost compression in frigate segments intensifies as Australia's SEA 5000 and Canada's River-class orders force volume-driven supplier consolidation. Government shipyards exhibit lowest price sensitivity; export customers in Southeast Asia face tightest budget constraints.
Supply Chain Analysis
US International Traffic in Arms Regulations and UK Export Control Organisation restrictions fragment combat system component flows across allied procurement pipelines. HY-80 steel production concentrates in US, Japanese, and Korean qualified mills. Towed sonar arrays and phased-array radar modules draw from UK, US, and French subsystem specialists. Single-source vulnerability pervades high-yield alloy forging capacity. Distribution runs through sovereign shipyard integration with government-furnished equipment coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern naval vessel procurement as modular mission architectures and NATO STANAG interoperability standards transform hull-form standardization into ecosystem leverage, with Type 26 Global Combat Ship multi-national production demonstrating how shared qualification costs reshape competitive positioning.
For Market Incumbents: Pre-empt emerging specialist naval architects by securing design authority over next-generation integrated electric propulsion architectures. Lock in HY-80 supply through backward integration into qualified domestic forging capacity. Counter South Korean and Japanese export frigate competition by anchoring multi-national production consortia around established combat system integration credentials.
For New Entrants and Emerging Players: Composite superstructure fabrication for radar cross-section reduction in next-generation frigate programs represents the most penetrable entry point for carbon-fiber reinforced polymer specialists lacking hull fabrication scale. Containerized weapon module suppliers serving constabulary patrol variants offer second white-space target. Pursue qualification partnerships with prime contractors holding NATO STANAG certification rather than direct platform competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates with underperforming naval divisions lacking design authority over major combatant classes. Long-term viability centers on through-life support revenue streams tethered to integrated electric propulsion upgrade cycles. Monitor directed-energy weapon power budget requirements as inflection signal for next-generation propulsion architecture investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Mission Payload Standardization | Enables hull-form reuse across Australia's Hunter-class and Canada's River-class programs, compressing unit production costs. |
| Integrated Electric Propulsion Investment | Positions Bath Iron Works and BAE Systems Glasgow for DDG(X) and Type 83 power architecture requirements. |
| Composite Superstructure Supplier Development | Addresses radar cross-section reduction mandates in Japan's Maya-class and South Korea's KDDX frigate initiatives. |
| Multi-National Production Consortium Formation | Distributes Type 26 Global Combat Ship qualification costs across UK, Australian, and Canadian shipbuilding hubs. |
| Directed-Energy Weapon Power Integration | Locks in 75-plus megawatt electrical architecture standards for next-generation destroyer and frigate programs. |
Methodological Framework
A standing panel of naval program managers, combat system integration leads, shipyard procurement officers, and defense ministry acquisition executives provided ongoing calibration against primary interview findings. Secondary validation drew from US Navy shipbuilding certification filings, UK Ministry of Defence contract award announcements, NATO STANAG documentation, and customs data on high-yield steel alloy trade flows. Bottom-up hull delivery schedules and top-down defense budget appropriations were triangulated to anchor volume estimates.
Scenario-bracketing around submarine proliferation intensity and directed-energy weapon maturation timelines shaped demand projections across the analysis window. Segmentation modeling spanned vessel type, construction material, operational role, and technology integration tiers. CAGRs derived from hull delivery backlogs and multi-year procurement contract structures. Forecast inputs included METI defense production base maintenance policies and Australia's Defence and Strategic Goods List technology transfer constraints.
Practitioners should monitor sovereign content requirement shifts and HY-80 mill capacity utilization for early signals of contract pricing revision. Forecasts reflect assumptions about NATO STANAG interoperability mandate persistence and Indo-Pacific submarine threat density trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Marine Radar Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Coastal Patrol Military Vessels Market