
 Military Frigate Market | 2026-2036
Military Frigate Market Size, Share, and Industry Trends Forecast 2026-2036
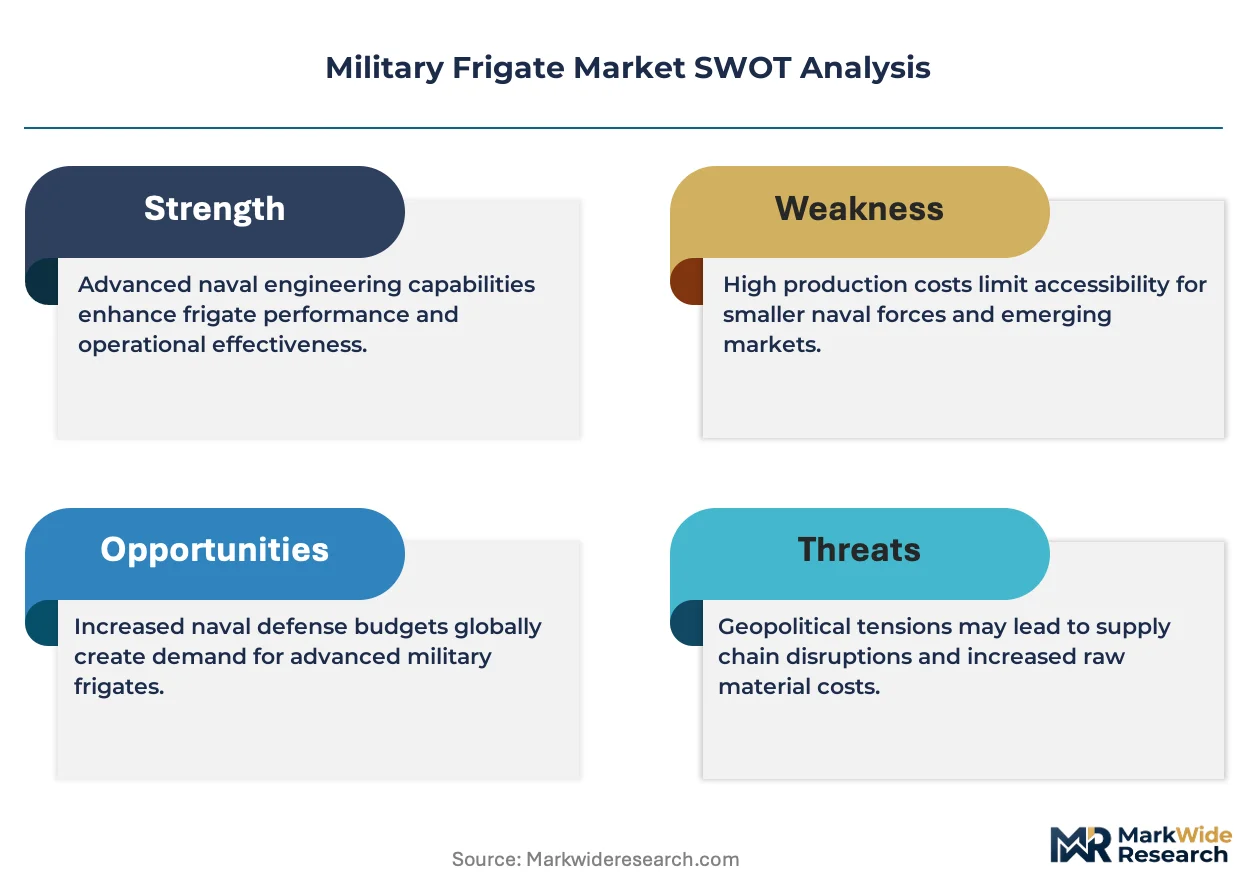
Military Frigate Market Analysis
United Kingdom naval shipyard expansion is fragmenting traditional procurement patterns across NATO-aligned fleets. BAE Systems plc leverages vertical integration through its Glasgow facilities to anchor Royal Navy Type 26 production. Naval Group competes via stealth-optimized hull designs, while thyssenkrupp AG sustains German and export market presence through modular combat system architectures.
A military frigate denotes a medium-displacement surface combatant, typically displacing 3,000 to 7,000 tonnes, optimized for anti-submarine warfare, air defense, and maritime patrol through integrated sonar suites and vertical launch missile systems. Multirole frigates dominate current procurement as navies prioritize hull-count efficiency over specialized single-mission vessels. Weapon systems technology attracts disproportionate R&D allocation due to sensor-to-shooter integration requirements, while propulsion systems shift toward hybrid-electric configurations for acoustic signature management.
FDA standards for embedded medical systems and NATO STANAG interoperability frameworks govern subsystem certification, with EU Green Deal emission benchmarks now penetrating European naval procurement specifications. The U.S. Navy's NAVAIR certification process and Australia's sovereign shipbuilding requirements create divergent compliance pathways for multinational suppliers. Stakeholders must monitor how classified data-handling mandates reshape cross-border teaming arrangements before committing to joint development structures.
Market Dynamics
The U.S. Navy's distributed maritime operations concept is compressing procurement timelines while forcing sensor-to-shooter integration across allied fleets. This operational doctrine demands hull-count efficiency over single-mission specialization, reshaping how navies evaluate combatant value.
Growth Catalysts
- Australia's sovereign shipbuilding mandates:The country's domestic construction programs create captive demand for combat system integration and sustainment services across the Indo-Pacific.
- NATO STANAG interoperability frameworks:These technical standards accelerate cross-border subsystem certification and reduce duplicate testing cycles for multinational suppliers.
- Hybrid-electric propulsion architectures:Acoustic signature management requirements from anti-submarine warfare missions drive R&D allocation toward integrated power and distribution systems.
Market Restraints
- Specialized steel alloy supply concentration:High-tensile naval-grade plate production clusters in limited geographic basins, creating input cost volatility for hull fabricators.
- EU Green Deal emission benchmarks:These penetration specifications into European naval procurement add compliance layers without corresponding budget adjustments.
- Classified data-handling mandates:Cross-border teaming arrangements face structural friction from divergent national security protocols between allied programs.
Strategic Opportunities
- Integrated mast sensor architectures:The convergence of radar, electronic warfare, and communications arrays into unified superstructures opens white space for subsystem specialists.
- Underpenetrated Southeast Asian fleet modernization:Indonesia and Vietnam naval expansion programs lack mature domestic supplier ecosystems.
- U.S. NAVAIR certification process streamlining:Potential procedural reforms could compress foreign system integration timelines for allied shipbuilders.
Industry Challenges
- Combat systems integration talent scarcity:Sonar-to-missile vertical launch coordination requires specialized software engineers in short supply across NATO shipyards.
- Legacy platform interoperability:New frigate classes must communicate with existing fleet data links without compromising next-generation encryption standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Frigate Market |
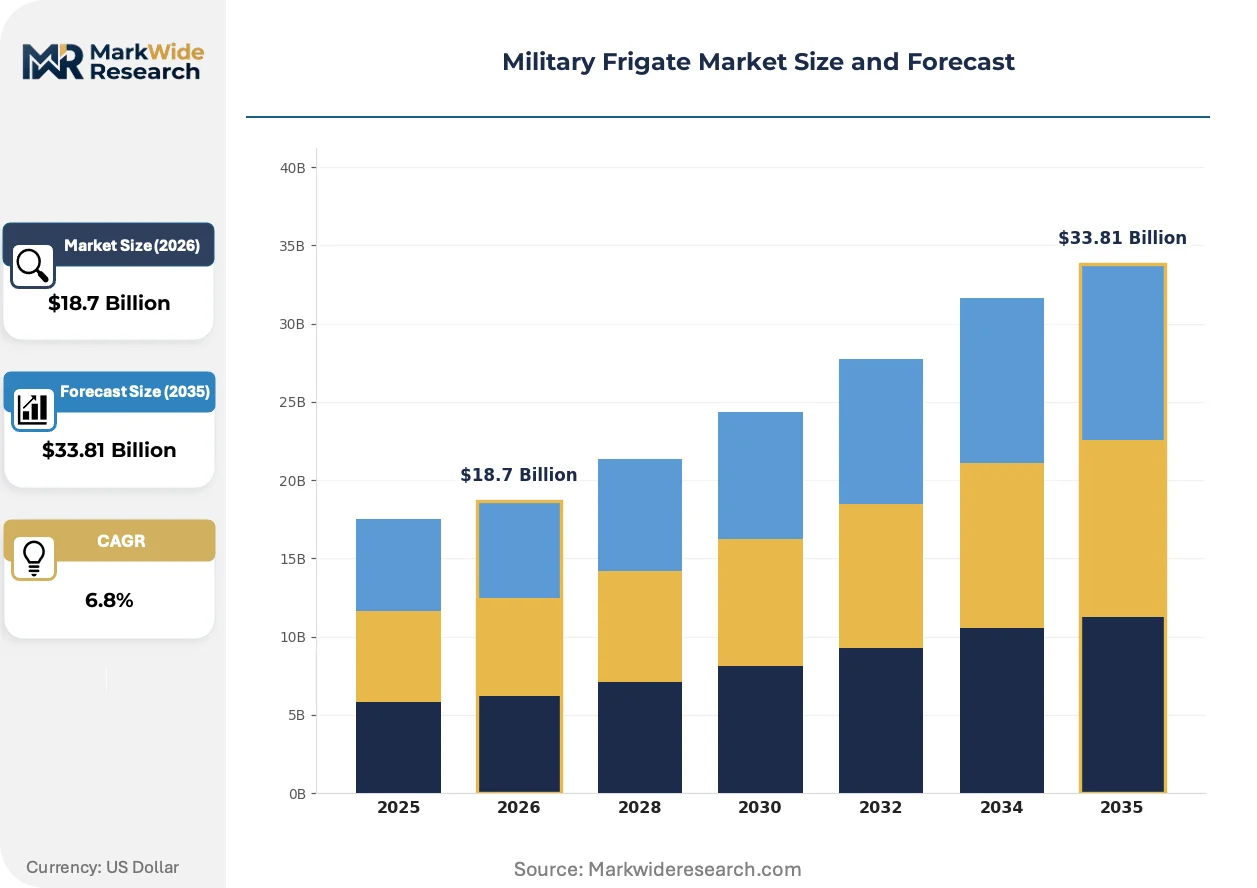
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Multirole Frigates, Anti-Submarine Frigates, Air Defense Frigates, Explore Frigates Technology: Stealth Technology, Propulsion Systems, Navigation Systems, Weapon Systems End User: Naval Forces, Coast Guards, Private Security, International Alliances Deployment: Offshore Operations, Coastal Defense, Anti-Piracy Missions, Humanitarian Assistance |
| Companies Covered | BAE Systems plc, Fincantieri S.p.A., Naval Group, thyssenkrupp AG, Lockheed Martin Corporation, Austal Limited, United Shipbuilding Corporation, General Dynamics Corporation, Damen Shipyards Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Frigate Market Emerging Trajectories
Propulsion, sensor, and certification technologies are converging to redefine combatant design priorities. These shifts compress development cycles while elevating subsystem integration complexity.
Integrated power systems are hybridizing naval propulsion architectures. Combined diesel-electric and gas turbine arrangements enable acoustic quieting for submarine hunting while sustaining sprint speeds for carrier escort missions. The U.S. Navy's Constellation-class program and the United Kingdom's Type 26 both specify these configurations, compressing supplier qualification timelines for European and American component manufacturers.
EU Green Deal emission benchmarks are penetrating naval procurement specifications. The European Commission's defense industrial strategy now references carbon accounting for vessel construction and lifecycle operation. German and French shipyards face compressed deadlines to demonstrate alternative fuel compatibility, with hydrogen storage and fuel cell auxiliary power receiving accelerated R&D allocation.
Allied joint venture structures are displacing traditional prime-contractor models. Australia's Hunter-class program with BAE Systems and the AUKUS technology-sharing framework demonstrate how risk and intellectual property now distribute across national boundaries. This pattern concentrates in the Indo-Pacific, where sovereign construction requirements force foreign designers into local partnership arrangements with domestic shipyards.
Military Frigate Market Segmentation
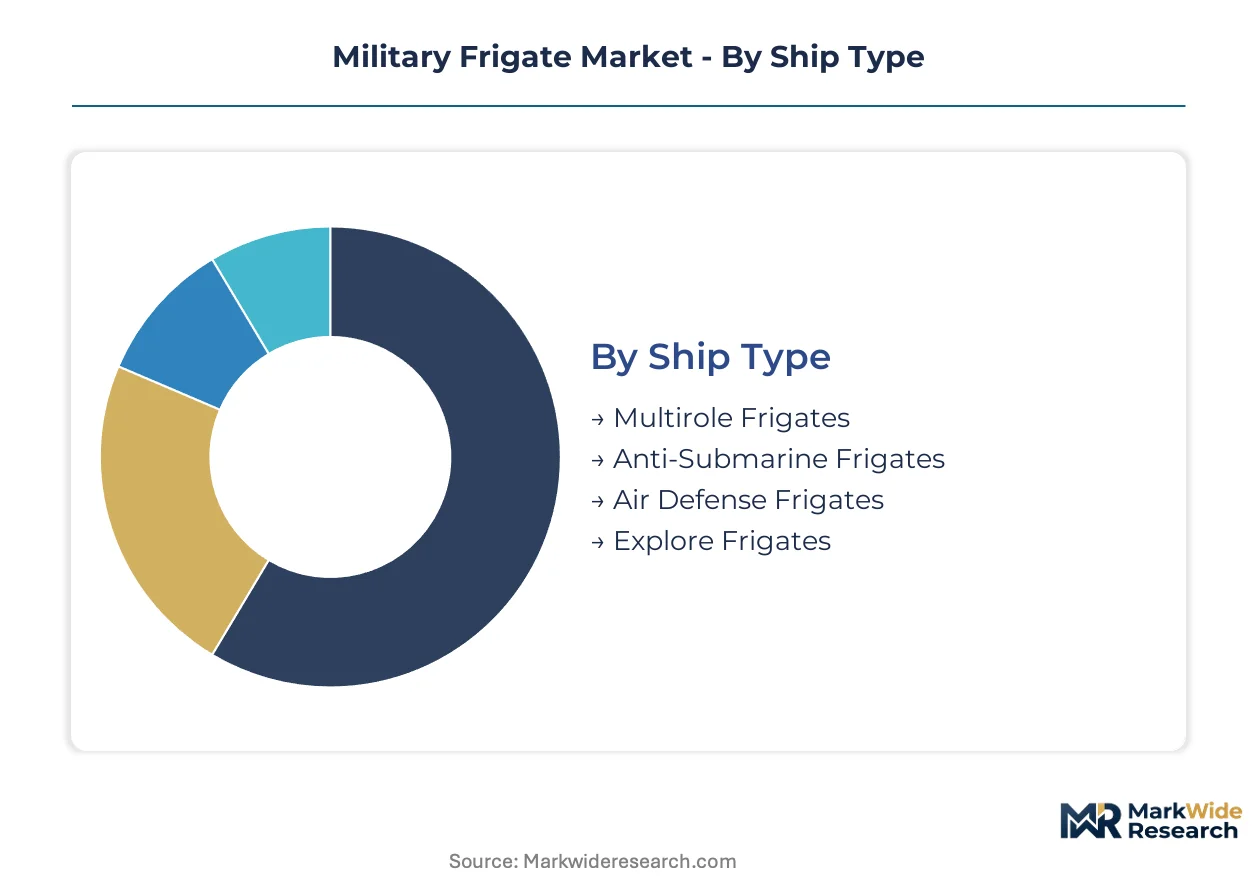
Frigate procurement patterns diverge sharply across mission profiles and technology maturity. Commanders prioritize hull-count efficiency through multirole configurations while acoustic signature management and sensor integration reshape subsystem specifications.
Ship Type:
Mature anti-submarine designs coexist with emerging multirole architectures as navies balance specialization against operational flexibility.
- Multirole Frigates:Integrated sonar suites, vertical launch missile systems, and modular mission bays enable simultaneous anti-submarine, air defense, and surface warfare operations. Australia's Hunter-class program and the U.S. Constellation-class procurement concentrate demand here as fleet managers prioritize hull-count efficiency over single-mission vessels.
- Anti-Submarine Frigates:Optimized hull forms and towed array sonar configurations deliver acoustic advantage against diesel-electric submarines. NATO STANAG interoperability frameworks accelerate cross-border subsystem certification for these hulls across allied fleets.
- Air Defense Frigates:Area denial platforms with enhanced radar cross-section reduction and extended-range interceptors.
- Explore Frigates:Lightly armed patrol variants optimized for maritime domain awareness and constabulary duties.
Multirole Frigates retain volume leadership; Explore Frigates hold the steepest expansion curve among emerging navies with constrained procurement budgets.
Technology:
Cost tier stratification separates proven mechanical systems from digitally intensive architectures requiring specialized integration talent.
- Propulsion Systems:Combined diesel-electric and gas turbine arrangements enable acoustic quieting for submarine hunting while sustaining sprint speeds for carrier escort missions. Hybrid-electric architectures attract disproportionate R&D allocation as EU Green Deal emission benchmarks penetrate European naval procurement specifications.
- Weapon Systems:Vertical launch missile systems, naval gun mounts, and close-in weapon systems demand sensor-to-shooter integration. Combat systems integration talent scarcity constrains deployment timelines across NATO shipyards.
- Stealth Technology:Radar-absorbent materials and infrared signature suppression for reduced detectability.
- Navigation Systems:Inertial guidance, GPS augmentation, and celestial backup for contested electromagnetic environments.
Weapon Systems command premium pricing tiers; Propulsion Systems face the steepest compliance cost escalation from emission benchmarks.
End User:
Customer type determines specification stringency, with naval forces demanding full combat capability and coast guards accepting reduced armament suites.
- Naval Forces:Blue-water and littoral combatant commands specifying integrated mast sensor architectures and distributed maritime operations compatibility. The U.S. Navy's procurement timelines compress as the distributed maritime operations concept forces allied fleet interoperability.
- Coast Guards:Law enforcement and search-and-rescue platforms with reduced weapons fit and enhanced boat launch facilities. Indonesia and Vietnam naval expansion programs create demand concentration for these lower-specification hulls.
- Private Security:Armed escort vessels for commercial maritime protection in high-risk corridors.
- International Alliances:Jointly procured hulls under AUKUS-type technology-sharing frameworks with distributed intellectual property.
Naval Forces dominate absolute procurement volume; International Alliances exhibit the most rapid contract structure innovation.
Deployment:
Application context shapes survivability requirements, with offshore operations demanding full combat systems and humanitarian missions permitting reduced defensive suites.
- Offshore Operations:Carrier strike group escort and independent task force assignments requiring comprehensive sensor and weapons fit. The U.S. Navy's integrated mast sensor architectures reshape procurement priorities for these high-intensity missions.
- Anti-Piracy Missions:Sustained patrol in Gulf of Aden and Southeast Asian chokepoints with helicopter facilities and rigid-hull inflatable boat deployment systems. Australia's sovereign shipbuilding mandates create captive regional demand for sustained presence platforms.
- Coastal Defense:Territorial water patrol with mine countermeasures and shallow-draft maneuverability.
- Humanitarian Assistance:Hospital facilities, heavy lift cranes, and enhanced habitability for extended disaster relief operations.
Offshore Operations anchor procurement volume; Anti-Piracy Missions demonstrate the fastest fleet rotation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-tensile naval-grade steel production clusters in limited geographic basins, creating input cost volatility that shapes fleet procurement timelines across NATO and Indo-Pacific navies.
United States
The U.S. Navy's distributed maritime operations concept compresses procurement timelines while forcing sensor-to-shooter integration across allied fleets. NAVAIR certification processes govern subsystem approval for foreign system integration. Integrated mast sensor architectures reshape procurement priorities at shipyards in Maine and Mississippi.
United Kingdom
BAE Systems plc anchors Royal Navy Type 26 production through Glasgow facilities, fragmenting traditional procurement patterns across NATO-aligned fleets. The UK's naval shipyard expansion competes with continental European programs for NATO STANAG interoperability compliance. Scottish shipyards concentrate design-to-delivery capability for anti-submarine warfare hulls.
Australia
Sovereign shipbuilding mandates under the Hunter-class program create captive demand for combat system integration across the Indo-Pacific. TGA-equivalent defense certification frameworks and AUKUS technology-sharing requirements reshape supplier qualification. South Australian shipyards in Adelaide host BAE Systems partnerships for domestic construction.
Germany
Thyssenkrupp AG sustains German and export market presence through modular combat system architectures for NATO and non-aligned customers. EU Green Deal emission benchmarks penetrate naval procurement specifications, adding compliance layers to hull construction. Northern German shipyards in Kiel and Hamburg concentrate diesel-electric propulsion integration expertise.
France
Naval Group competes via stealth-optimized hull designs for domestic and export markets, particularly in Mediterranean and Middle Eastern fleets. ANSM defense procurement frameworks and EU defense industrial strategy requirements shape carbon accounting for vessel construction. Breton shipyards in Lorient anchor integrated sonar suite production for anti-submarine variants.
Military Frigate Market Vendor Landscape
State-affiliated prime contractors and commercial shipbuilders split the market between sovereign capability preservation and export-driven volume production. The vendor base concentrates around five European and North American entities with established naval architecture credentials. Two strategic archetypes dominate: vertically integrated defense conglomerates with captive steel and electronics supply chains, and specialist combat system integrators licensing hull designs to regional shipyards. Competitive moves center on joint venture structures for AUKUS-type technology sharing and backward integration into high-tensile alloy production.
Among British and French state-linked fabricators, BAE Systems plc and Naval Group exemplify the vertically integrated archetype through Glasgow and Lorient facilities. Thyssenkrupp AG occupies a position within the modular-systems tier, anchoring German export competitiveness through component-level standardization. These three entities represent contrasting approaches to NATO STANAG compliance: captive production versus licensed technology transfer.
| Leading Market Players |
|---|
| BAE Systems plc |
| Fincantieri S.p.A. |
| Naval Group |
| thyssenkrupp AG |
| Lockheed Martin Corporation |
| Austal Limited |
| United Shipbuilding Corporation |
| General Dynamics Corporation |
| Damen Shipyards Group |
| Others |
Supply Flow & Price Mechanics
The Trans-Suez container corridor's freight cost volatility amplifies input price spreads between European and Indo-Pacific shipyards, compressing margins for hull fabricators dependent on distant steel sourcing while enabling premium pricing for regionally integrated builders with captive alloy production.
Pricing Analysis
NATO STANAG interoperability frameworks dictate the pricing tier structure across allied procurement programs. Three-tier pricing structure across premium, standard, and economy levels separates integrated mast sensor architectures from modular combat system configurations and coast guard patrol variants. Cost compression in standard-tier hulls is intensifying because EU Green Deal emission benchmarks add compliance layers without corresponding budget adjustments. Coast guard and emerging navy buyers exhibit highest price sensitivity; naval forces with sovereign shipbuilding mandates demonstrate lowest.
Supply Chain Analysis
High-tensile naval-grade steel plate production draws from concentrated blast furnace capacity in South Korea, Japan, and Germany. Towed array sonar systems, vertical launch missile canisters, and integrated power electronics represent critical component dependencies. Single-source vulnerability in specialized alloy supply creates structural exposure to geopolitical trade restrictions. Distribution runs through state-affiliated prime contractors with captive shipyard networks and licensed technology transfer arrangements with regional construction facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military frigate market is accelerating through hybrid-electric propulsion disruption as EU emission benchmarks and acoustic signature requirements converge to reshape R&D allocation across NATO and Indo-Pacific fleets.
For Market Incumbents: Pre-empt modular combat system integrators from capturing subsystem share by anchoring Glasgow and Lorient production facilities with backward integration into high-tensile alloy supply. Lock in AUKUS-type joint venture structures before Australian sovereign shipbuilding mandates harden local partnership requirements. Prioritize sensor-to-shooter software engineering capacity as combat systems integration talent scarcity constrains rival deployment timelines.
For New Entrants and Emerging Players: Build out white-space positions in Southeast Asian fleet modernization by targeting Indonesia and Vietnam naval expansion programs lacking mature domestic supplier ecosystems. Exploit underpenetrated integrated mast sensor architectures where radar, electronic warfare, and communications convergence opens subsystem specialist opportunities. Lead with licensed hull design partnerships rather than prime-contractor competition against state-linked fabricators.
For Investors and Strategic Acquirers: Specialist combat system integrators with NATO STANAG certification credentials and AUKUS-cleared intellectual property represent the most defensible acquisition archetype. Long-term viability hinges on exposure to distributed maritime operations procurement timelines and hybrid-electric propulsion R&D allocation trends. Watch for NAVAIR certification process streamlining signals as inflection indicators for foreign system integration timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Structure | AUKUS technology-sharing frameworks distribute risk and intellectual property across national boundaries for Indo-Pacific programs. |
| Backward Integration | Captive high-tensile naval-grade steel production insulates margin compression from concentrated alloy supply basins. |
| Certification Investment | NATO STANAG interoperability compliance accelerates cross-border subsystem qualification and reduces duplicate testing cycles. |
| Modular Combat System Architecture | Component-level standardization sustains German export competitiveness against vertically integrated state-linked fabricators. |
| Hybrid-Electric Propulsion R&D | EU Green Deal emission benchmarks and acoustic signature requirements drive disproportionate allocation to integrated power systems. |
Methodological Framework
Operator-level perspectives from naval procurement officers, shipyard program managers, combat system integration engineers, and defense ministry acquisition leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through NATO STANAG documentation, national defense procurement filings, and customs trade data for high-tensile alloy shipments. SEC filings from listed shipbuilders and EIA maritime fuel consumption statistics provided demand-side triangulation. Bottom-up hull delivery schedules and top-down defense budget appropriations were reconciled across the analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by ship type, propulsion architecture, end-user category, and regional procurement cluster. CAGRs were derived from trend-line extrapolation of defense budget trajectories and fleet replacement cycles, cross-referenced against documented hull construction timelines. Hybrid-electric propulsion adoption curves and sovereign shipbuilding mandate implementation schedules served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-affiliated prime contractors into modular system licensing would shift outcomes beyond modeled ranges. Cross-checking against national defense white papers and parliamentary budget appropriations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Marine Radar Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Naval Vessels Market