
 Anti-UAV Defence System (AUDS) Market | 2026-2036
Anti-UAV Defence System (AUDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-UAV Defence System (AUDS) Market Analysis
Buyer concentration among military end users is expanding as defense ministries consolidate counter-drone procurement under unified command structures rather than siloed service branches. RTX leverages its radar-integrated kill-chain portfolio to anchor large-format fixed-site deployments across multiple allied nations. Lockheed Martin Corporation sustains technology leadership in high-energy laser subsystems through sustained R&D commitments to beam control and thermal management. DroneShield Ltd competes in the mobile-jamming tier with rapidly deployable man-portable systems designed for expeditionary units and VIP protection details.
An anti-UAV defence system constitutes an integrated hardware-software architecture combining detection, tracking, identification, and neutralization subsystems to defeat unmanned aerial vehicles across kinetic, electronic, and directed-energy modalities. Detection ranges typically span 5–15 kilometers for radar-based configurations, with command-and-control layers fusing multi-sensor inputs into engagement decisions within sub-ten-second timelines. Jamming technology dominates current procurement volumes due to lower per-unit cost and reduced collateral risk in populated environments, while laser systems represent the fastest-expanding segment as solid-state fiber and slab architectures mature toward tactically relevant power-on-target thresholds. Kinetic interceptors retain margin concentration in naval and fixed-base applications where rules of engagement permit explosive defeat mechanisms.
The EU AI Act's risk-tier framework shapes product development trajectories by mandating human-in-the-loop protocols for autonomous engagement decisions, while NATO STANAG standards harmonize interoperability requirements across member-state procurements. The US FAA coordinates airspace deconfliction protocols that constrain testing and operational deployment timelines near civil aviation corridors. Stakeholders must monitor evolving rules-of-engagement doctrines that determine whether detection-only or full-defeat architectures qualify for specific operational contexts.
Market Dynamics
Defense ministries across NATO member states are consolidating counter-drone procurement under unified command structures, compressing vendor selection cycles and favoring integrated kill-chain providers over point-solution specialists.
Growth Catalysts
- EU AI Act risk classification:The framework mandates human-in-the-loop protocols for autonomous engagement, creating compliance-driven refresh cycles for legacy detection-only systems across Germany, France, and the United Kingdom.
- Critical infrastructure protection mandates:Tightening security requirements for power grids, airports, and government facilities in NATO states are accelerating layered architecture deployments combining radar, RF sensing, and electronic defeat.
- Solid-state laser maturation:Fiber and slab architectures are approaching tactically relevant power-on-target thresholds, opening procurement pathways for directed-energy systems in naval and fixed-base applications.
Market Restraints
- Collateral risk constraints:Kinetic interceptors face operational limitations in populated environments, restricting explosive defeat mechanisms to naval and remote fixed-base contexts where rules of engagement permit broader employment.
- Airspace deconfliction protocols:The US FAA coordinates testing and operational deployment timelines near civil aviation corridors, extending qualification periods for new detection and defeat systems.
- Beam control thermal management:High-energy laser subsystems require sustained R&D commitments to thermal dissipation and precision pointing, elevating development costs relative to electronic warfare alternatives.
Strategic Opportunities
- Expeditionary man-portable tier:Rapidly deployable jamming systems for VIP protection and mobile units represent underpenetrated demand within expeditionary military formations and private security details.
- NATO STANAG interoperability:Harmonized standards across member-state procurements create pathways for vendors to scale single-platform designs across multiple national defense ministries.
- Multi-sensor fusion architectures:Integration of radar, electro-optical, and RF detection layers is compressing engagement decision timelines below ten seconds, enabling premium positioning for command-and-control software providers.
Industry Challenges
- Human-in-the-loop certification:Autonomous engagement protocols require extensive validation under EU AI Act high-risk system requirements, extending compliance timelines for product launches.
- Legacy system integration:Existing air defense networks operate on proprietary data formats, forcing costly middleware development for AUDS platforms seeking plug-and-play interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-UAV Defence System (AUDS) Market |
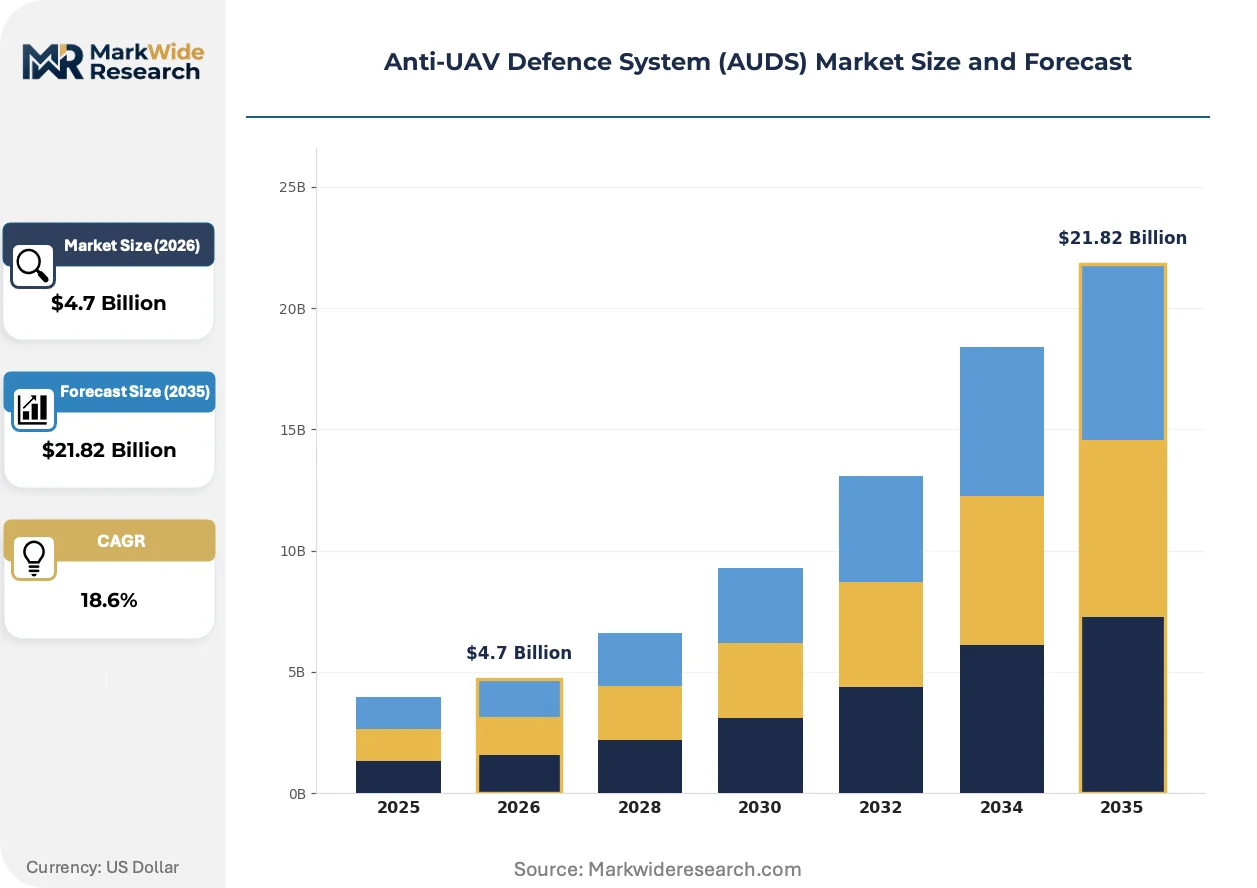
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Laser, Electromagnetic, Kinetic, Jamming End User: Military, Commercial, Government, Private Security Deployment: Onshore, Offshore, Mobile, Fixed Component: Radar, Sensors, Command and Control, Launch Systems |
| Companies Covered | RTX, Lockheed Martin Corporation, Northrop Grumman Corporation, Israel Aerospace Industries, Thales Group, BAE Systems, Leonardo S.p.A., Rafael Advanced Defense Systems, DroneShield Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-UAV Defence System (AUDS) Market Emerging Trajectories
Counter-drone architectures are migrating from standalone detection or defeat modules toward fused kill-chains, compressing vendor landscapes and elevating software-defined coordination layers above hardware-centric point solutions.
Solid-state directed-energy systems are consolidating market positioning around naval and fixed-site applications where thermal management infrastructure permits sustained power delivery. Defense ministries in the United States and allied NATO states are prioritizing these platforms for base protection and maritime air defense, compressing procurement timelines for chemical laser alternatives that require hazardous fuel handling.
The EU AI Act's high-risk classification for autonomous weapon systems is reshaping product development trajectories across European defense contractors. Manufacturers must now embed human-in-the-loop decision protocols and comprehensive audit trails, elevating software architecture costs while creating compliance barriers for non-EU vendors seeking access to member-state procurement channels.
Buyer concentration among unified defense procurement commands is displacing siloed service-branch purchasing, compressing vendor qualification cycles and elevating integrated platform providers. This pattern is most visible in Germany, France, and the United Kingdom, where ministry-level counter-drone strategies now mandate multi-domain interoperability standards that legacy point-solution vendors struggle to satisfy.
Anti-UAV Defence System (AUDS) Market Segmentation
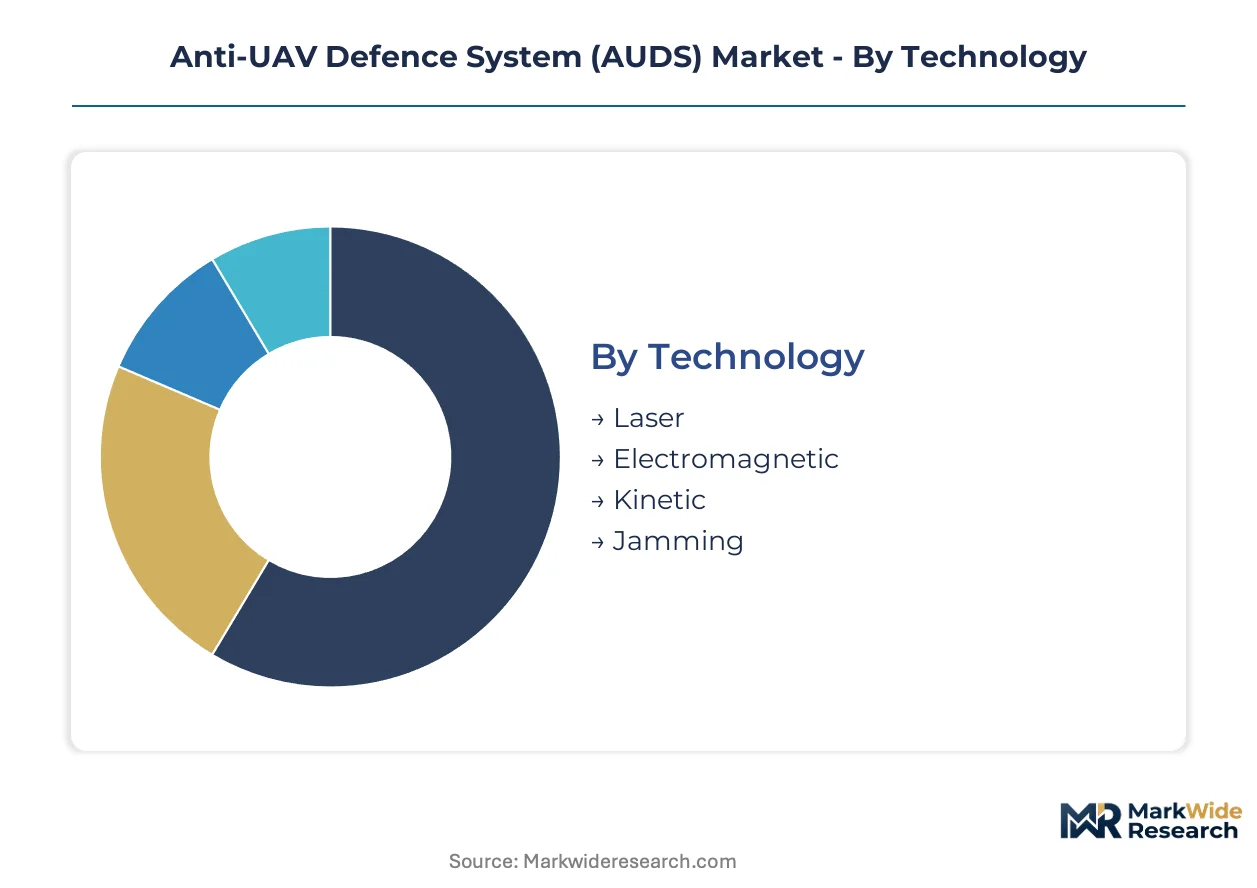
Segmentation reveals how procurement priorities diverge across operational contexts, from expeditionary military formations requiring man-portable jamming systems to fixed-site critical infrastructure demanding fused kill-chain architectures. Understanding these divides enables vendors to align R&D investments with the specific certification burdens and interoperability standards governing each tier.
Technology:
Certification intensity varies sharply across modalities, with directed-energy platforms facing EU AI Act high-risk system protocols while electronic warfare alternatives navigate lighter electromagnetic compatibility frameworks.
- Jamming:Radio-frequency and GNSS disruption systems dominate current procurement volumes due to lower per-unit cost and reduced collateral risk in populated environments. Demand concentrates in Germany and the United Kingdom where critical infrastructure protection mandates favor non-kinetic defeat mechanisms near urban centers and airports.
- Laser:Solid-state fiber and slab architectures approach tactically relevant power-on-target thresholds for base protection and maritime applications. Procurement pathways are opening in France and the United States for naval installations where thermal management infrastructure permits sustained power delivery.
- Kinetic:Explosive interceptors and net-capture systems retain relevance in naval and remote fixed-base contexts where rules of engagement permit broader employment.
- Electromagnetic:High-power microwave and electromagnetic pulse systems offer area-denial capabilities against swarming threats, with development programs active across NATO research establishments.
Leading the category by volume: Jamming. Expanding most quickly: Laser.
End User:
Procurement authority consolidation under unified defense commands is compressing vendor selection cycles and elevating integrated platform providers above point-solution specialists.
- Military:Layered counter-drone architectures combining radar, RF sensing, and electronic defeat are accelerating across NATO member states following operational lessons from expeditionary deployments. Germany, France, and the United Kingdom are consolidating service-branch procurement under ministry-level strategies mandating multi-domain interoperability.
- Government:Critical infrastructure protection mandates for power grids, government facilities, and transport nodes are tightening security requirements. Demand clusters in national capitals and strategic industrial corridors where EU AI Act compliance drives refresh cycles for legacy detection-only systems.
- Commercial:Airport operators and energy utilities are deploying perimeter defense systems under national aviation authority coordination with civil airspace regulators.
- Private Security:VIP protection details and corporate facilities are adopting rapidly deployable man-portable systems for expeditionary security formations.
Highest procurement concentration: Military. Steepest expansion trajectory: Government.
Deployment:
Physical configuration dictates supply chain structure, with fixed-site installations requiring civil engineering integration while mobile platforms prioritize rapid deployment and man-portable logistics.
- Fixed:Large-format installations anchor layered kill-chains at military bases, critical infrastructure nodes, and government facilities. These deployments integrate radar, electro-optical, and RF detection layers with command-and-control software compressing engagement timelines below ten seconds.
- Mobile:Vehicle-mounted and expeditionary systems serve expeditionary military formations requiring rapid repositioning across operational theaters. NATO STANAG interoperability standards enable single-platform designs to scale across multiple national defense ministries.
- Onshore:Terrestrial deployments encompass perimeter defense for airports, power grids, and urban government facilities subject to civil aviation deconfliction protocols.
- Offshore:Maritime platforms protect naval vessels and offshore energy installations where kinetic interceptors face fewer collateral constraints.
Dominant revenue share: Fixed. Gaining share fastest: Mobile.
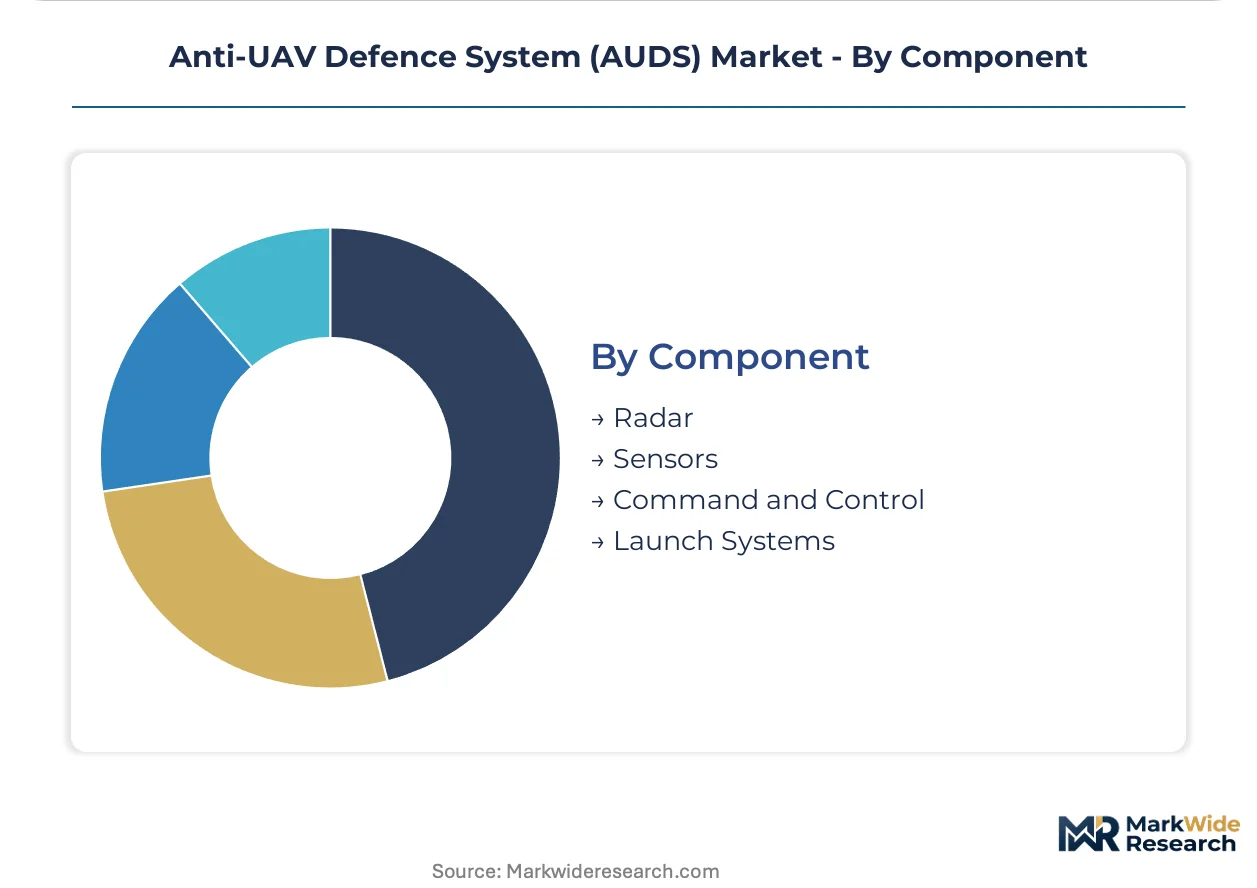
Component:
Software-defined coordination layers are elevating above hardware-centric point solutions as multi-sensor fusion architectures compress engagement decision timelines.
- Command and Control:Software architectures fuse multi-sensor inputs into engagement decisions within sub-ten-second timelines. Human-in-the-loop protocols mandated by EU AI Act high-risk system requirements are elevating development costs while creating compliance barriers for non-EU vendors.
- Radar:Detection ranges typically span 5–15 kilometers for radar-based configurations, with integrated kill-chain portfolios anchoring large-format fixed-site deployments across multiple allied nations.
- Sensors:Electro-optical and infrared detection layers provide identification and tracking capabilities, with RF sensing addressing passive detection requirements.
- Launch Systems:Kinetic interceptor deployment mechanisms retain margin concentration in naval applications where rules of engagement permit explosive defeat.
Fastest value migration: Command and Control. Highest hardware spend: Radar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide and rare-earth magnet supply chains concentrated in China and Australia underpin AUDS component manufacturing across major defense industrial bases.
United States
Fixed-site layered architectures anchor procurement at naval installations and critical infrastructure nodes. The FAA coordinates airspace deconfliction protocols that constrain testing timelines near civil aviation corridors. Defense contractors cluster around Washington DC-Baltimore corridor and Southern California aerospace corridors where directed-energy R&D programs concentrate.
Germany
Critical infrastructure protection mandates for power grids and government facilities drive layered system deployments. The EU AI Act mandates human-in-the-loop protocols for autonomous engagement decisions, creating compliance-driven refresh cycles. Industrial activity concentrates in Bavaria and North Rhine-Westphalia where defense electronics manufacturers integrate radar and electronic warfare subsystems.
France
Naval base protection and maritime air defense applications accelerate solid-state laser procurement pathways. National procurement standards align with NATO STANAG interoperability requirements. The Provence-Alpes-Côte d'Azur region hosts systems integration facilities serving Mediterranean fleet installations.
United Kingdom
Expeditionary military formations and VIP protection details generate demand for rapidly deployable man-portable jamming systems. Ministry-level counter-drone strategies now mandate multi-domain interoperability standards. Defense industrial activity clusters in Southeast England and Scotland where command-and-control software development concentrates.
Israel
Operational experience with layered counter-drone architectures informs rapid-response system development for expeditionary units. National security doctrine emphasizes autonomous engagement capabilities within regulatory constraints. Defense technology development concentrates in Tel Aviv metropolitan corridor and Haifa Bay industrial zone.
Anti-UAV Defence System (AUDS) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue expeditionary man-portable specializations and software-defined coordination layers. The vendor base structures around integrated kill-chain providers, point-solution specialists, and directed-energy technology developers. Three archetypes dominate: radar-integrated platform anchors, mobile-jamming tier competitors, and high-energy laser subsystem leaders. Competitive dynamics center on strategic partnerships for multi-sensor fusion and geographic expansion through NATO STANAG certification pathways.
Within the integrated platform tier, RTX and Lockheed Martin Corporation exemplify large-format fixed-site deployment anchors, while DroneShield Ltd occupies a position representing rapidly deployable expeditionary specialists. RTX leverages radar-integrated portfolios across allied nations. Lockheed Martin Corporation sustains technology leadership in beam control and thermal management subsystems. DroneShield Ltd competes in mobile-jamming applications for expeditionary units and VIP protection formations.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Israel Aerospace Industries |
| Thales Group |
| BAE Systems |
| Leonardo S.p.A. |
| Rafael Advanced Defense Systems |
| DroneShield Ltd |
| Others |
Supply Flow & Price Mechanics
Solid-state laser maturation toward tactically relevant power-on-target thresholds is compressing unit economics for directed-energy platforms while concentrating procurement authority among integrated kill-chain providers capable of absorbing thermal management subsystem costs. This technological transition simultaneously elevates software-defined coordination layers above hardware-centric point solutions and reshapes margin distribution across the vendor base.
Pricing Analysis
Extended warranty and lifecycle service bundling separate premium-tier integrated platform providers from unbundled point-solution vendors in competitive tenders. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by NATO STANAG certification status, human-in-the-loop protocol compliance depth, and multi-sensor fusion architecture sophistication. Cost compression in the jamming tier is intensifying because RF component commoditization and Chinese gallium arsenide substrate availability are eroding hardware margins. Government procurement commands demonstrate lowest price sensitivity due to mandate-driven refresh cycles, while private security details exhibit highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Gallium arsenide substrate supply rests on Chinese and Australian rare-earth processing capacity, with fiber laser pump diodes drawing from Japanese and German precision optics manufacturers. Critical dependencies span gallium arsenide wafers, rare-earth magnet assemblies for beam steering gimbals, and solid-state laser gain media. Single-source vulnerability concentrates in Chinese gallium arsenide refining infrastructure subject to export licensing variability. Distribution runs through defense ministry procurement commands and NATO-aligned systems integrators rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated kill-chain providers as EU AI Act compliance costs and NATO STANAG certification barriers force point-solution specialists toward acquisition or exit.
For Market Incumbents: Lock in multi-year service contracts with unified defense procurement commands to anchor recurring revenue streams against emerging software-defined competitors. Deepen backward integration into radar subsystem manufacturing to capture margin migrating from hardware to command-and-control software layers. Prioritize thermal management R&D partnerships with naval installation operators where sustained power delivery infrastructure creates switching costs for laser platform customers. For New Entrants and Emerging Players: Systems integrators serving expeditionary military formations represent the most penetrable channel for rapidly deployable man-portable jamming platforms lacking legacy air defense network integration burdens. Target VIP protection details and private security details in the United Kingdom and Germany where procurement decentralization permits faster vendor qualification cycles than ministry-level military tenders. Pursue NATO STANAG pre-certification through collaborative development agreements with established radar platform providers to bypass standalone validation timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated platform anchors seeking directed-energy or mobile-jamming capability gaps. Long-term viability favors vendors with demonstrated EU AI Act high-risk system compliance and existing NATO member-state contract vehicles. Watch for EU AI Act enforcement variance across member states as the inflection indicator for compliance-cost arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| NATO STANAG Certification Investment | Enables single-platform designs to scale across German, French, and UK defense ministries under harmonized interoperability mandates. |
| Directed-Energy Thermal Management Partnership | Secures naval base protection contracts where sustained power delivery infrastructure creates platform stickiness. |
| Human-in-the-Loop Software Architecture Development | Satisfies EU AI Act high-risk system protocols that gate access to European government procurement channels. |
| Expeditionary Man-Portable Product Line Launch | Captures underpenetrated demand from VIP protection details and rapid-response security formations. |
| Multi-Sensor Fusion Command-and-Control Acquisition | Compresses engagement decision timelines below ten seconds for premium positioning in fixed-site deployments. |
Methodological Framework
Independent corroboration across defense ministry procurement officers, systems integration engineers at layered kill-chain providers, and regulatory affairs specialists navigating EU AI Act compliance underwrites the qualitative findings in this study. Primary interviews with radar subsystem program managers, directed-energy thermal management researchers, and NATO standardization committee participants combined with secondary validation from national defense budget disclosures, EU regulatory filings, and FAA airspace coordination protocols. Bottom-up segment sizing across jamming, laser, kinetic, and electromagnetic technology tiers triangulated against top-down defense expenditure allocation analysis.
Comparable-period anchoring to historical procurement cycles across the analysis window informed projection framework construction. Modeled dimensions span technology modality, end-user archetype, deployment configuration, and component category, with additional granularity around EU AI Act risk-tier classification. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion patterns. Industry-specific forecast inputs incorporate solid-state laser power-on-target improvement trajectories and NATO member-state critical infrastructure protection mandate implementation timelines.
Caveats apply where EU AI Act enforcement variance, NATO STANAG revision schedules, or FAA airspace deconfliction protocol changes could materially shift the outlook. Forecasts reflect assumptions regarding human-in-the-loop protocol adoption rates and directed-energy thermal management maturation timelines. A small set of named triggers warrants ongoing watch: EU AI Act high-risk system certification delays, gallium arsenide export licensing disruptions, and NATO procurement command consolidation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Europe Military Unmanned Vehicles Market