
 Anti-Ship Missile Defense System Market | 2026-2036
Anti-Ship Missile Defense System Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Ship Missile Defense System Market Analysis
The US Navy's net-zero operational emissions mandate is hardening requirements for energy-efficient radar and directed-energy subsystems aboard surface combatants. Lockheed Martin Corporation leverages its Aegis combat system integration heritage to anchor naval fleet modernization programs across multiple allied navies. Raytheon Technologies Corporation sustains competitive position through dense R&D investment in gallium nitride radar transmit-receive modules. Northrop Grumman Corporation dominates airborne early warning and electronic attack portfolios that cue layered missile defense engagements.
An anti-ship missile defense system comprises integrated sensor, command-and-control, and kinetic or non-kinetic effector architectures engineered to detect, track, intercept, and neutralize sea-skimming, ballistic, and hypersonic anti-ship threats at standoff distances from defended vessels. These systems employ X-band or S-band active electronically scanned array radars, infrared seekers, and RF decoys to achieve engagement timelines measured in seconds against Mach 2+ threats. Interceptor systems command the largest value share given unit costs of vertically launched missiles and associated fire control infrastructure, while electro-optical systems represent the fastest-expanding technology segment due to passive targeting resilience in jamming-contested environments. Decoy technology captures concentrated margin pools as navies prioritize expendable offboard countermeasures against saturation attacks.
The US Department of Defense mandates NIST cybersecurity standards for weapon system software supply chains, while NATO's STANAG 4156 governs data link interoperability between national missile defense assets. The US Missile Defense Agency and the UK's Defence Science and Technology Laboratory coordinate test and evaluation protocols that shape product qualification timelines and market access for non-allied suppliers. Stakeholders must monitor directed-energy weapon maturation and hypersonic threat proliferation to calibrate portfolio bets between kinetic interceptors and next-generation soft-kill architectures.
Market Dynamics
Hypersonic threat proliferation is compressing engagement timelines and forcing navies to abandon sequential defense architectures in favor of simultaneous multi-domain intercept capabilities. This structural pressure is redefining procurement specifications across NATO and Indo-Pacific fleets.
Growth Catalysts
- US Navy distributed maritime operations doctrine:Mandates networked sensor-to-shooter architectures that harden requirements for interoperable command-and-control systems across allied surface combatants.
- China's A2/AD investments:Compel regional recapitalization of fleet air defense among Japan, Australia, South Korea, and Taiwan procurement agencies.
- Directed-energy weapon maturation:Gallium nitride solid-state laser arrays achieve megawatt-class output thresholds that enable cost-per-shot economics competitive with kinetic interceptors.
Market Restraints
- Gallium nitride substrate supply concentration:US and Japanese substrate manufacturers control critical feedstock for AESA radar transmit-receive modules, creating single-source vulnerability.
- NIST cybersecurity compliance timelines:Weapon system software supply chain certification adds 18-24 months to qualification schedules for non-incumbent suppliers.
- Hypersonic glide vehicle tracking limitations:Current X-band radar architectures lack sustained track custody against Mach 5+ maneuvering threats in terminal phases.
Strategic Opportunities
- Expendable offboard decoy architectures:Royal Australian Navy and Japan Maritime Self-Defense Force procurement programs prioritize saturation-attack countermeasures that capture concentrated margin pools.
- Electro-optical/infrared sensor convergence:Passive targeting resilience in jamming-contested environments enables new layered defense configurations alongside active radar.
- UK Defence Science and Technology Laboratory test protocols:Coordination with US Missile Defense Agency creates qualification pathway for non-allied suppliers meeting STANAG 4156 interoperability standards.
Industry Challenges
- Systems engineering talent scarcity:Integration of kinetic and directed-energy effectors demands specialized expertise in fire control algorithm development that outstrips naval industrial base capacity.
- Legacy Aegis combat system backward compatibility:New interceptor interfaces must maintain operational continuity with fielded Baseline 9 configurations, constraining architectural innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Ship Missile Defense System Market |
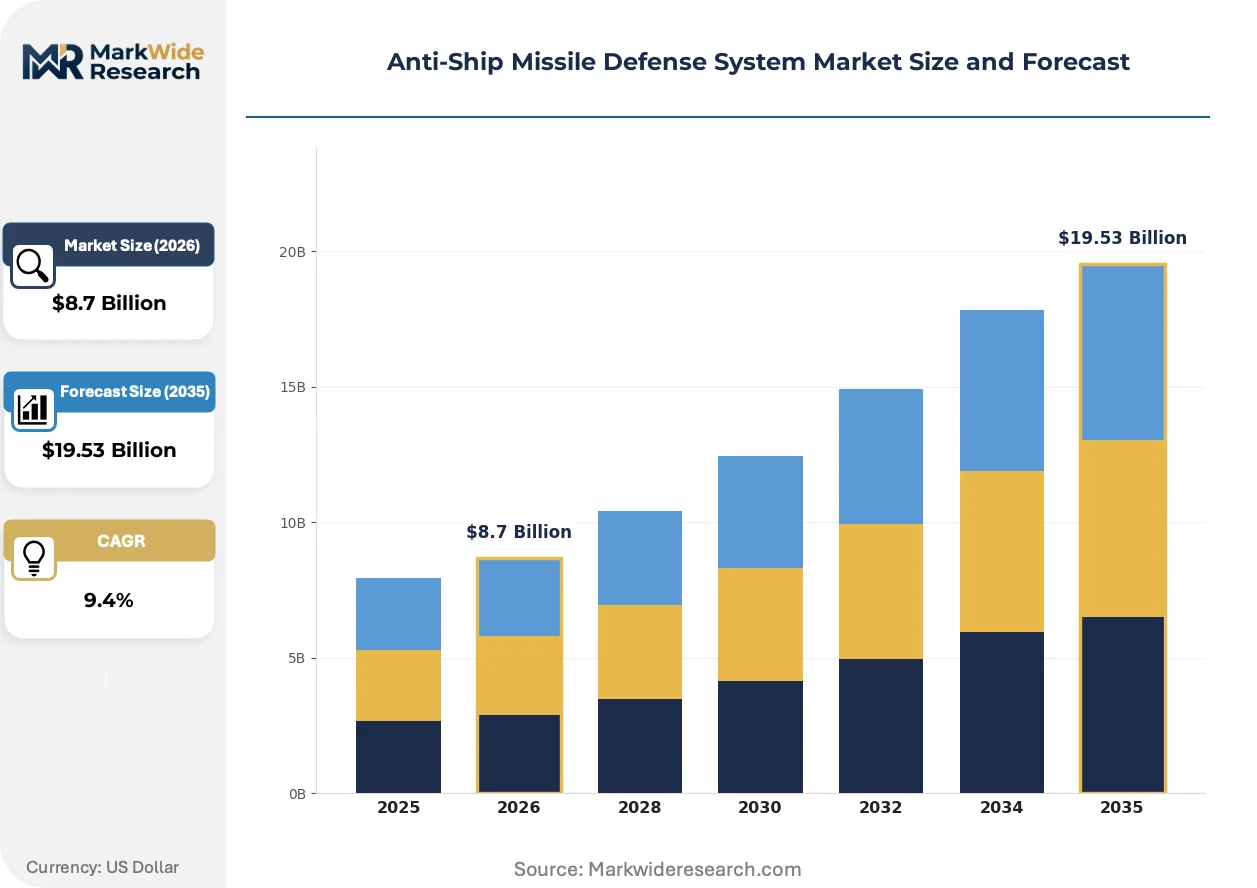
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long-Range Missiles, Short-Range Missiles, Interceptor Systems, Decoy Systems Technology: Guided Missile Technology, Radar Systems, Electro-Optical Systems, Decoy Technology End User: Naval Forces, Defense Contractors, Coast Guards, Maritime Security Agencies Deployment: Onshore Installations, Offshore Installations, Mobile Platforms, Fixed Platforms |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems, Thales Group, MBDA, General Dynamics Corporation, Leonardo, Rafael Advanced Defense Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Ship Missile Defense System Market Emerging Trajectories
Layered defense architectures are fragmenting traditional platform-centric procurement into subsystem-specific competitions. This decomposition is accelerating technology insertion cycles and reshaping supplier relationships across naval industrial bases.
Software-defined radar processing is modularizing combat system upgrade pathways. Naval operators in the US, UK, and Australia are fielding incremental capability drops through firmware updates rather than hardware replacement programs. This approach is compressing obsolescence cycles for proprietary signal processing hardware and enabling third-party algorithm integration.
EU Green Deal emissions benchmarks are extending to naval vessel operational profiles. STANAG 4156 data link interoperability requirements now incorporate power consumption specifications that favor gallium nitride over legacy gallium arsenide radar architectures. European surface combatant programs in France, Italy, and Germany are prioritizing energy-efficient sensor suites that extend at-sea endurance without refueling.
Fleet operators are unbundling decoy procurement from prime combat system contracts. Direct acquisition of expendable offboard countermeasures through separate funding lines is displacing bundled spares-and-support arrangements. This pattern is most visible in Indo-Pacific navies facing saturation attack scenarios, where magazine depth requirements exceed traditional inventory planning assumptions.
Anti-Ship Missile Defense System Market Segmentation
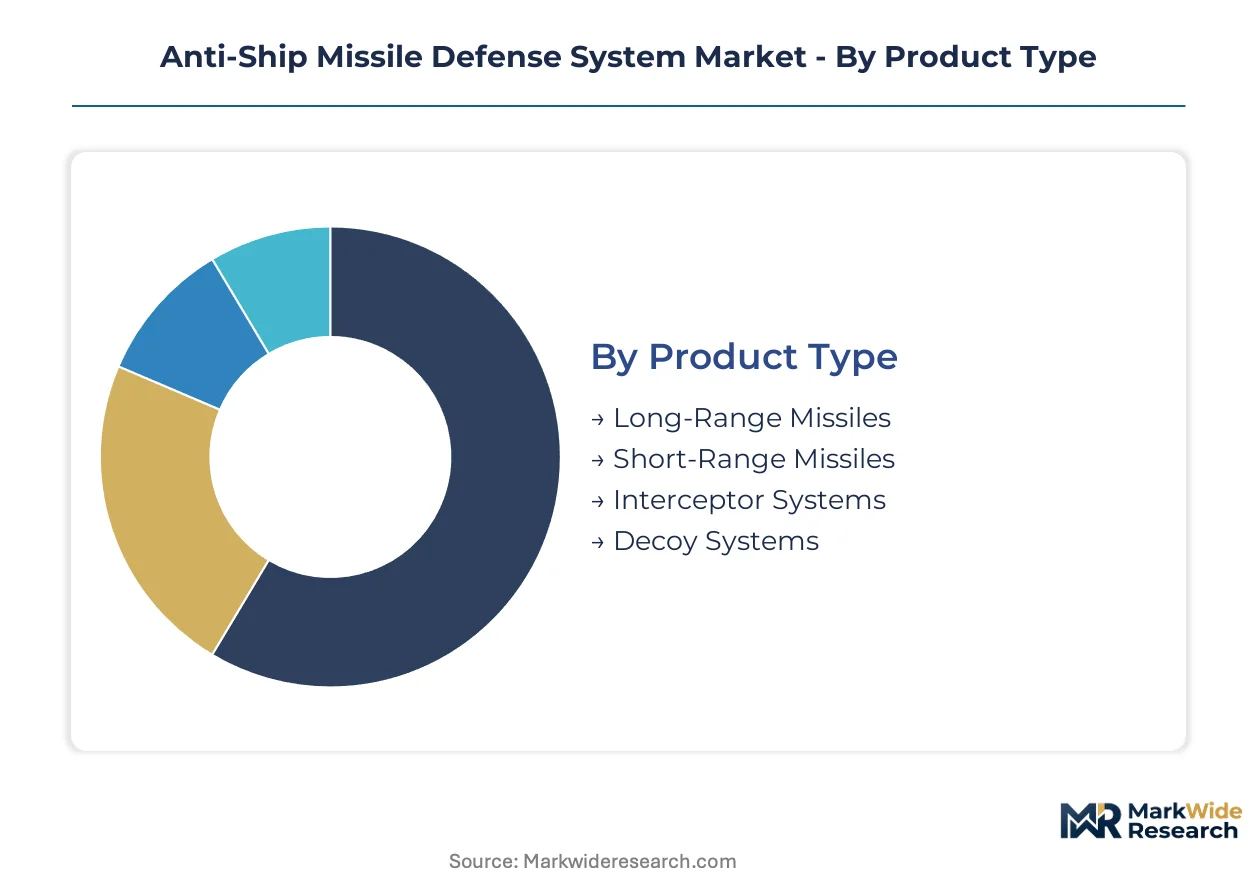
Segmentation reveals how procurement budgets fragment across kinetic and non-kinetic effector categories. Defense planners prioritize interceptor magazine depth against saturation threats while accelerating directed-energy and decoy investments for cost-per-engagement economics.
Product Type:
Acquisition officers weight unit cost against kill probability when allocating between layered defense tiers.
- Interceptor Systems:Vertically launched missiles with active radar seekers and fire control infrastructure command dominant procurement value. The US Navy's distributed maritime operations doctrine hardens requirements for networked launchers across allied surface combatants.
- Decoy Systems:Expendable offboard countermeasures including RF seduction decoys and infrared suppressors achieve concentrated margins. Royal Australian Navy and Japan Maritime Self-Defense Force procurement programs prioritize saturation-attack countermeasures with magazine depths exceeding traditional inventory assumptions.
- Long-Range Missiles:Area-defense interceptors with boost-phase engagement envelopes.
- Short-Range Missiles:Point-defense systems for terminal-phase threat neutralization.
Volume sits with Interceptor Systems; growth tilts toward Decoy Systems.
Technology:
Platform operators select sensor-effector pairings based on electronic warfare contestedness and atmospheric conditions.
- Radar Systems:Active electronically scanned arrays with gallium nitride transmit-receive modules deliver track custody against Mach 2+ sea-skimming threats. NATO STANAG 4156 interoperability specifications now incorporate power consumption benchmarks favoring GaN over legacy gallium arsenide architectures.
- Electro-Optical Systems:Passive infrared seekers and staring arrays enable targeting resilience in RF jamming environments. Software-defined processing modularizes upgrade pathways through firmware rather than hardware replacement.
- Guided Missile Technology:Dual-mode seekers combining radar and infrared channels.
- Decoy Technology:Expendable RF and IR countermeasures with programmable threat libraries.
Revenue concentrates in Radar Systems; Electro-Optical Systems are climbing the fastest.
End User:
Budget authority and operational risk tolerance shape procurement specifications across institutional buyer categories.
- Naval Forces:Fleet operators mandate integrated sensor-to-shooter architectures with Aegis combat system compatibility. The US Navy's net-zero operational emissions mandate hardens requirements for energy-efficient subsystems aboard surface combatants.
- Defense Contractors:Prime integrators manage subsystem qualification against NIST cybersecurity standards and UK Defence Science and Technology Laboratory test protocols.
- Coast Guards:Constabulary maritime services with limited air defense requirements.
- Maritime Security Agencies:Port and critical infrastructure protection operators.
Procurement volume centers on Naval Forces; qualification pathway demand flows through Defense Contractors.
Deployment:
Mobility requirements and engagement geometry determine platform selection for threat coverage.
- Mobile Platforms:Surface combatants with vertical launch systems and integrated mast sensor suites. Indo-Pacific navies facing China's A2/AD investments prioritize distributed fleet architectures with embarked defense capabilities.
- Offshore Installations:Fixed oil and gas platforms with dedicated point-defense batteries.
- Onshore Installations:Coastal defense batteries with over-the-horizon radar cueing.
- Fixed Platforms:Permanent infrastructure with hardened sensor and interceptor magazines.
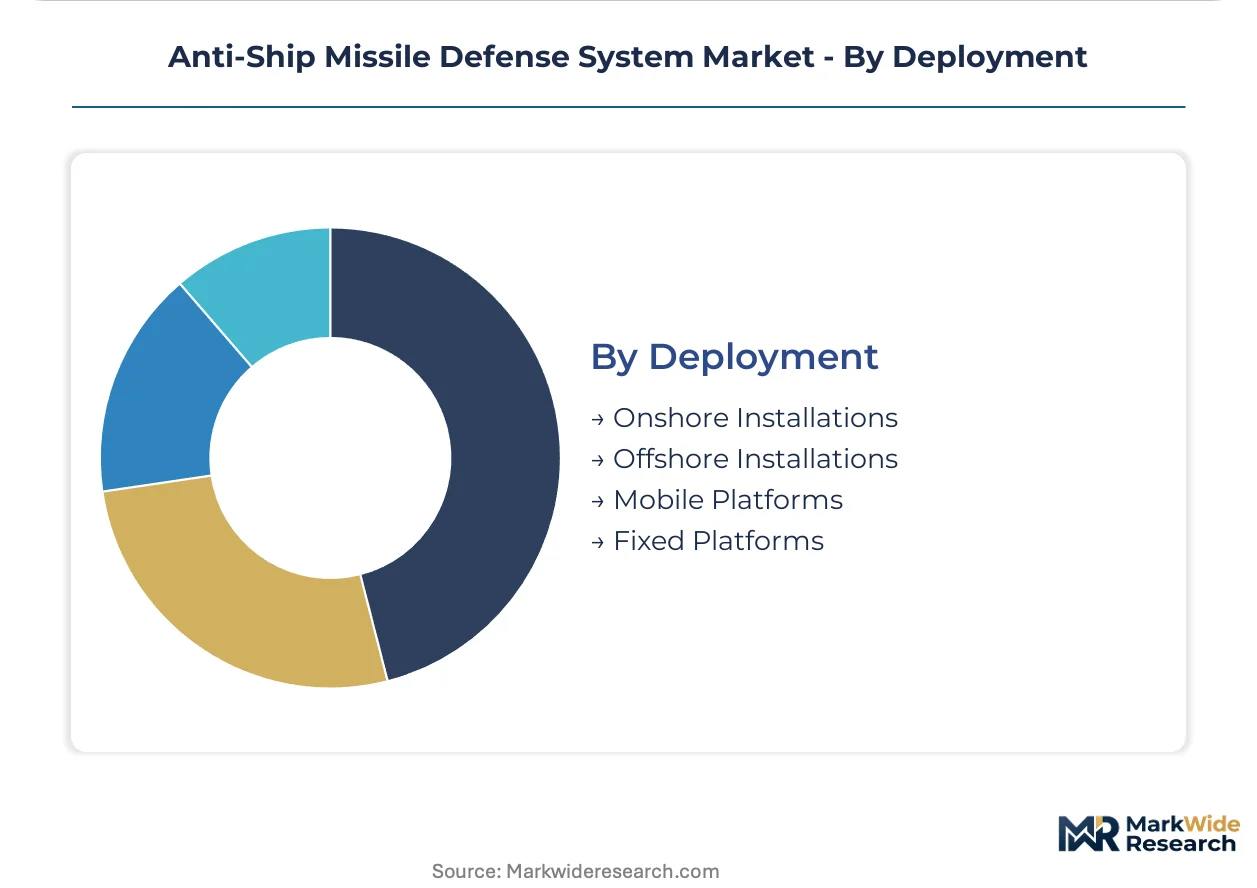
Investment gravity rests with Mobile Platforms; infrastructure hardening lifts Fixed Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington DC anchors procurement gravity for layered naval defense architectures, with Pentagon acquisition offices shaping requirements that cascade through allied fleet modernization programs worldwide.
United States
The US Navy's distributed maritime operations doctrine mandates networked sensor-to-shooter architectures across surface combatants. NIST cybersecurity standards govern weapon system software supply chains, adding qualification rigor for subsystem integrators. The Missile Defense Agency in Huntsville, Alabama coordinates test protocols with allied laboratories, anchoring transatlantic qualification pathways.
United Kingdom
Royal Navy fleet recapitalization drives demand for integrated interceptor and decoy systems aboard Type 26 and Type 31 frigates. The Defence Science and Technology Laboratory at Porton Down shapes test and evaluation standards that influence NATO STANAG 4156 interoperability specifications. Glasgow's shipbuilding corridor concentrates combat system integration activity for forthcoming surface combatant programs.
Japan
Japan Maritime Self-Defense Force procurement prioritizes saturation-attack countermeasures with expanded magazine depths against regional threat proliferation. METI industrial policy coordinates gallium nitride substrate supply security for domestic AESA radar manufacturing. The Kanto region around Yokohama hosts prime integrator facilities supporting Aegis-compatible destroyer modernization.
Australia
Royal Australian Navy Hunter-class frigate and AUKUS submarine programs accelerate layered defense subsystem procurement. Defence export control frameworks align with US International Traffic in Arms Regulations for technology transfer compliance. South Australia's Osborne shipbuilding precinct concentrates combat system integration work for forthcoming surface combatant construction.
South Korea
Republic of Korea Navy KDDX destroyer program drives indigenous combat system development with foreign subsystem integration. MFDS defense acquisition regulations govern offset requirements for imported missile defense technologies. Busan's marine industrial cluster hosts shipyard facilities integrating domestic and imported sensor-effector architectures.
Anti-Ship Missile Defense System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across combat system integration and directed-energy subsystems, with interceptor manufacturing occupying intermediate margin tiers. The vendor base clusters around three strategic archetypes: prime integrators with Aegis heritage, gallium nitride radar specialists, and expendable decoy manufacturers. Consolidation pressure concentrates among sensor subsystem suppliers facing qualification timeline compression. Dominant competitive moves include strategic partnerships for directed-energy weapon co-development and geographic expansion through NATO allied procurement channels.
Within the prime integrator tier, Lockheed Martin Corporation and Raytheon Technologies Corporation represent archetypal positions anchored by combat system integration heritage and dense R&D investment portfolios respectively. Northrop Grumman Corporation exemplifies the electronic warfare and airborne early warning specialization vector. These three US-based corporations occupy positions that shape procurement specifications across NATO and Indo-Pacific fleet modernization programs through their involvement in qualification protocol development and standards-setting activity.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| MBDA |
| General Dynamics Corporation |
| Leonardo |
| Rafael Advanced Defense Systems |
| Others |
Supply Flow & Price Mechanics
The US Navy's net-zero operational emissions mandate gates qualified supply for energy-efficient radar and directed-energy subsystems, restricting premium-tier pricing access to vendors with gallium nitride architectures and NIST-certified software supply chains.
Pricing Analysis
Value-based pricing anchored to kill probability against saturation attacks dominates procurement, with interceptor magazine depth commanding premium tiers. Price differentiation rests on STANAG 4156 interoperability certification and gallium nitride radar performance benchmarks. Cost compression in electro-optical sensor tiers is intensifying as software-defined processing modularizes upgrade pathways. Naval procurement offices exhibit lowest price sensitivity for terminal-phase point-defense systems, while coast guard and maritime security agencies face strict budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with US and Japanese manufacturers controlling gallium nitride substrate feedstock for AESA radar transmit-receive modules. Critical inputs draw from specialized foundries in Japan, compound semiconductor facilities in the United States, and fire control software development centers in the United Kingdom. Tariff exposure on gallium nitride substrates creates procurement risk for European and Indo-Pacific integrators. Distribution runs through prime combat system integrators with Aegis heritage, though decoy procurement is fragmenting into direct acquisition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
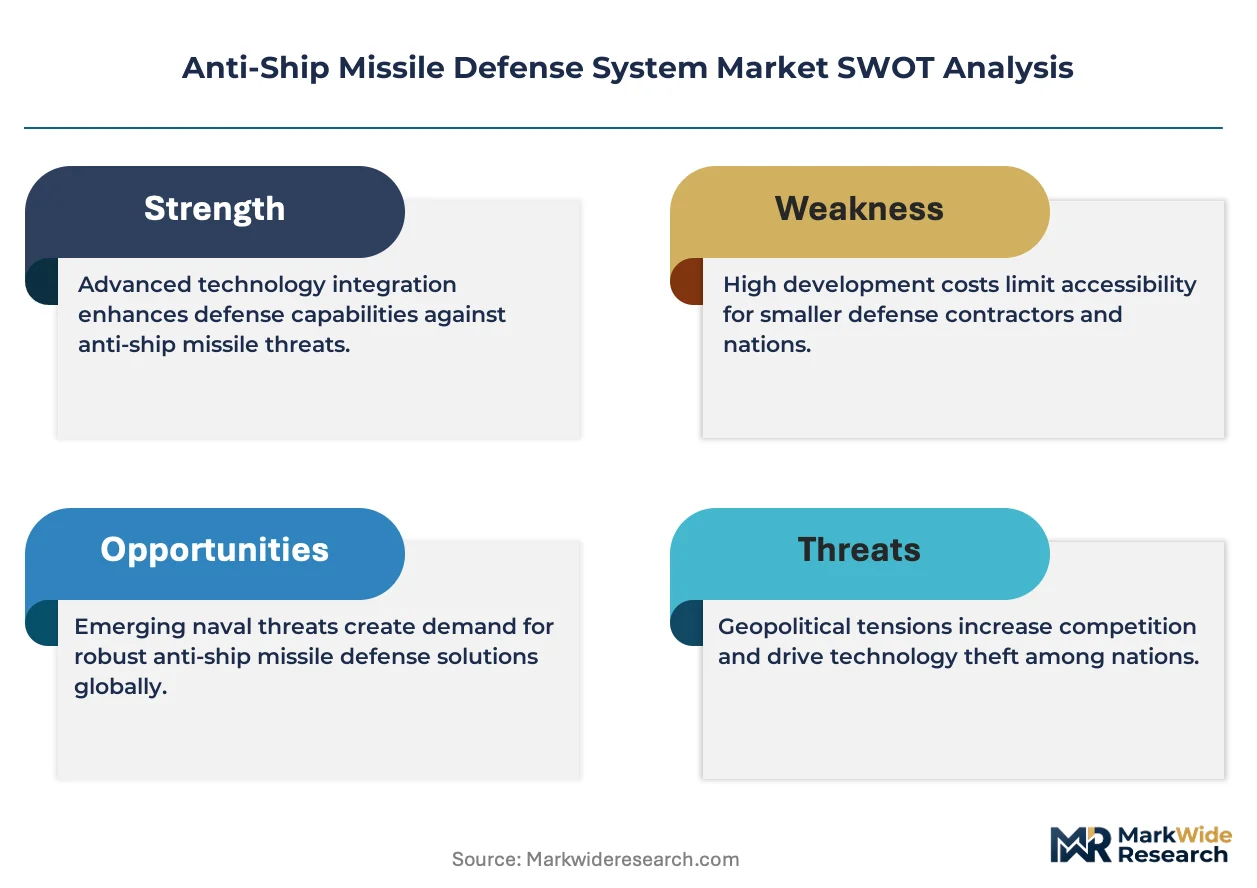
This market is a consolidation play as NIST cybersecurity compliance timelines force weaker subsystem suppliers out of qualification pathways.
For Market Incumbents: To counter hypersonic glide vehicle tracking limitations, Lockheed Martin and Raytheon Technologies should deepen backward integration into gallium nitride substrate supply and accelerate firmware-defined radar processing R&D. Channel control through Aegis combat system backward compatibility requirements protects installed base revenue against emerging directed-energy specialists. For New Entrants and Emerging Players: UK Defence Science and Technology Laboratory test protocol coordination with the US Missile Defense Agency opens a window for non-allied suppliers meeting STANAG 4156 standards. Expendable offboard decoy architectures represent the most penetrable white space, with direct procurement channels displacing bundled prime contracts. A go-to-market angle targeting Royal Australian Navy and Japan Maritime Self-Defense Force saturation-attack countermeasure programs bypasses incumbent combat system integration barriers. For Investors and Strategic Acquirers: Directed-energy weapon maturation achieving megawatt-class laser output is the leading indicator that soft-kill economics will displace kinetic interceptor volume. Long-term viability favors gallium nitride radar specialists and electro-optical sensor developers with software-defined processing capabilities. Acquisition targets should exhibit NIST cybersecurity certification and UK-US test protocol qualification. Watch gallium nitride substrate supply security negotiations between METI and US defense procurement offices as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Directed-Energy Weapon Co-Development | Megawatt-class laser arrays enable cost-per-shot economics competitive with kinetic interceptors for US Navy distributed maritime operations. |
| Gallium Nitride Substrate Supply Security | Backward integration into compound semiconductor manufacturing mitigates single-source vulnerability for AESA radar module production. |
| Software-Defined Radar Processing | Firmware upgrade pathways compress obsolescence cycles and enable third-party algorithm integration for NATO STANAG 4156 compliance. |
| Expendable Decoy Direct Procurement | Unbundled acquisition channels capture concentrated margins in Royal Australian Navy and Japan Maritime Self-Defense Force saturation-attack programs. |
| NIST Cybersecurity Certification Investment | Weapon system software supply chain qualification reduces 18-24 month timeline barriers for non-incumbent subsystem suppliers. |
Methodological Framework
Independent corroboration across program executive interviews, defense procurement officer consultations, and subsystem engineering director dialogues underwrites the qualitative findings. Primary fieldwork engaged naval fleet modernization planners, Aegis combat system integration leads, gallium nitride radar manufacturing specialists, and expendable decoy program managers. Secondary validation drew from US Department of Defense budget justification materials, NATO STANAG documentation, UK Defence Science and Technology Laboratory test protocols, and METI industrial policy filings. Bottom-up segment sizing triangulated against top-down defense expenditure allocation analysis.
Comparable-period anchoring to historical fleet recapitalization cycles and threat proliferation timelines structured the projection framework. The model segmented across interceptor systems, decoy systems, radar systems, and electro-optical systems by technology; naval forces, defense contractors, and maritime security agencies by end user; and mobile platforms versus fixed installations by deployment. CAGRs derived from procurement pipeline visibility, qualification timeline compression, and directed-energy weapon maturation curves. Hypersonic threat envelope expansion and distributed maritime operations doctrine implementation served as primary demand-side forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state laser weapon integration would alter the outlook. Forecasts reflect procurement commitment assumptions, regulatory compliance timeline stability, and allied defense spending continuity. Deviation in gallium nitride substrate supply security or NIST cybersecurity standard enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Combat Management System Market