
 LEO Satellite System Market | 2026-2036
LEO Satellite System Market Size, Share, and Industry Trends Forecast 2026-2036
LEO Satellite System Market Insights
Modular payload configurations is restructuring buyer procurement patterns across the LEO satellite value chain. SpaceX leverages full-stack vertical integration from rocket launch to terminal manufacturing, capturing margin at every layer. Lockheed Martin Corporation anchors defense-grade mission assurance protocols, sustaining premium positioning with Pentagon and NATO customers. OneWeb competes through dedicated polar orbit coverage, differentiating service for maritime and aviation routes where geostationary latency fails.
A LEO satellite system denotes spacecraft operating in orbits between 160 and 2,000 kilometers altitude, utilizing Ku-band, Ka-band, or laser inter-satellite links to achieve round-trip latency under 50 milliseconds for real-time applications. These systems primarily deliver broadband internet, Earth observation data, and positioning services to commercial and government end users. Communication systems dominate current constellation deployments, though Earth observation payloads command higher per-unit pricing due to specialized sensor integration. Synthetic aperture radar segments are expanding fastest, as all-weather imaging capability attracts defense and environmental monitoring budgets that optical sensors cannot satisfy.
The FCC governs U.S. orbital licensing and spectrum coordination, while the EU AI Act and CSRD increasingly shape European operator data governance and sustainability disclosure obligations. ITU frequency allocation treaties constrain market access for non-compliant constellations, creating regulatory moats for early filers. Stakeholders must monitor spectrum auction dynamics and debris mitigation rulemaking, as these will determine which constellation architectures achieve viable unit economics before capital constraints force consolidation.
Market Dynamics
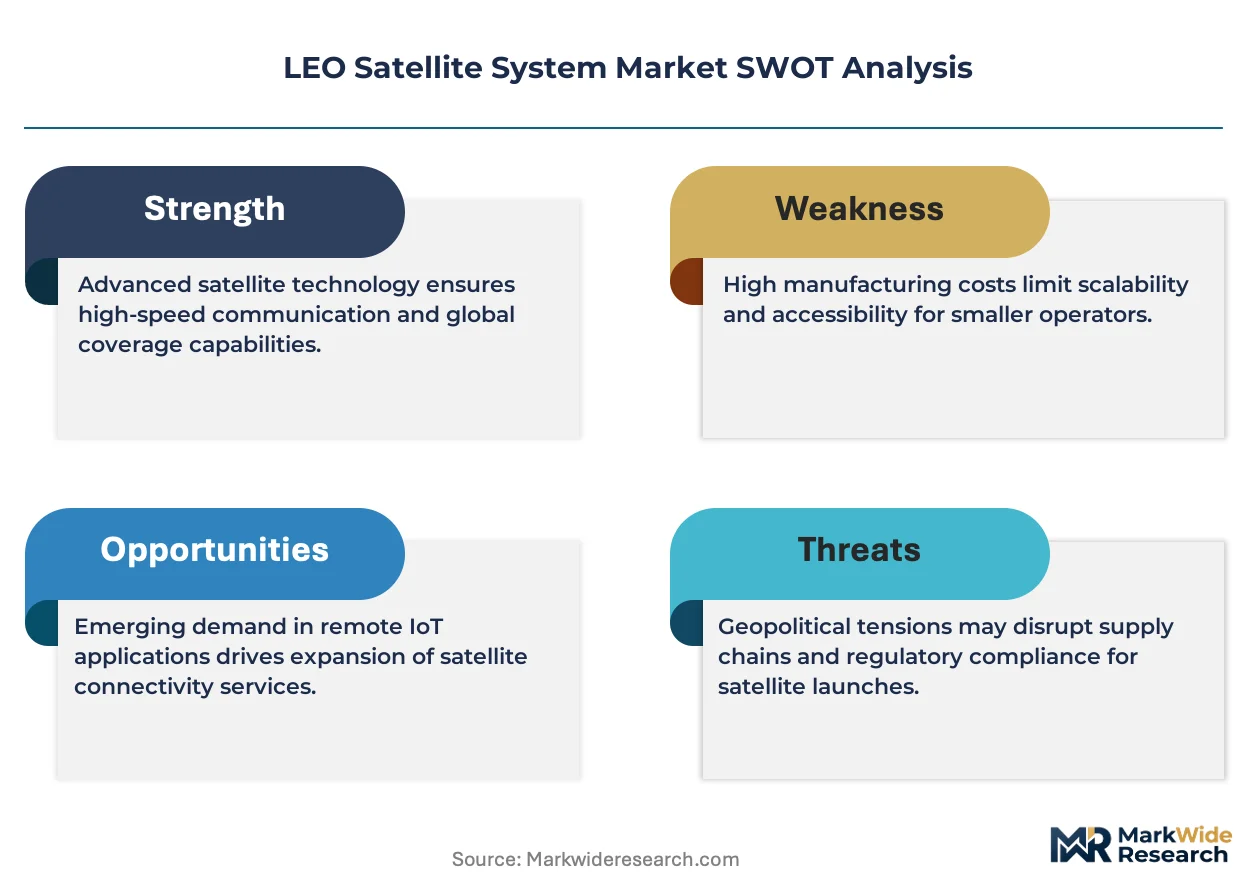
Modular payload configurations are restructuring procurement patterns across the LEO satellite value chain, forcing operators to choose between standardized bus architectures and custom mission-specific designs. This architectural divergence is compressing supplier margins while fragmenting the vendor base into specialized subsystem providers.
Growth Catalysts
- FCC Streamlined Licensing:The FCC's expedited small satellite licensing framework accelerates orbital slot allocation timelines, reducing regulatory friction for constellation operators seeking rapid deployment windows.
- India's Rural Broadband Initiative:The BharatNet program and expanding ground station partnerships are generating dedicated procurement pipelines for LEO connectivity infrastructure across underserved districts.
- Laser Inter-Satellite Links:Optical crosslink technology eliminates ground station dependency for data routing, enabling true mesh network architectures that slash operational costs for polar coverage routes.
Market Restraints
- Launch Capacity Bottlenecks:Concentrated access to heavy-lift vehicles from a limited supplier base creates scheduling constraints and pricing volatility for constellation deployment timelines.
- Spectrum Coordination Complexity:ITU filing precedence rules and national licensing fragmentation generate multi-year approval cycles that delay service commercialization for late entrants.
- Debris Mitigation Compliance:Mandatory post-mission disposal requirements and collision avoidance protocols impose propulsion system mass penalties that reduce payload capacity per spacecraft.
Strategic Opportunities
- Synthetic Aperture Radar Convergence:All-weather SAR imaging payloads are penetrating defense and environmental monitoring budgets that optical sensors cannot access, commanding premium per-unit pricing.
- Maritime Route Coverage:Dedicated polar orbit segments address latency failures on transoceanic shipping lanes where geostationary systems cannot deliver real-time navigation and crew welfare communications.
- EU CSRD Sustainability Disclosure:European operator obligations for orbital debris transparency and end-of-life planning create first-mover advantages for constellations with certified circular design protocols.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in phased array antenna design and Ka-band propagation modeling commands salary premiums that strain mid-tier operator staffing budgets.
- Ground Segment Integration Complexity:Legacy teleport infrastructure requires costly gateway retrofits to interoperate with proprietary modem protocols and beam-hopping schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LEO Satellite System Market |
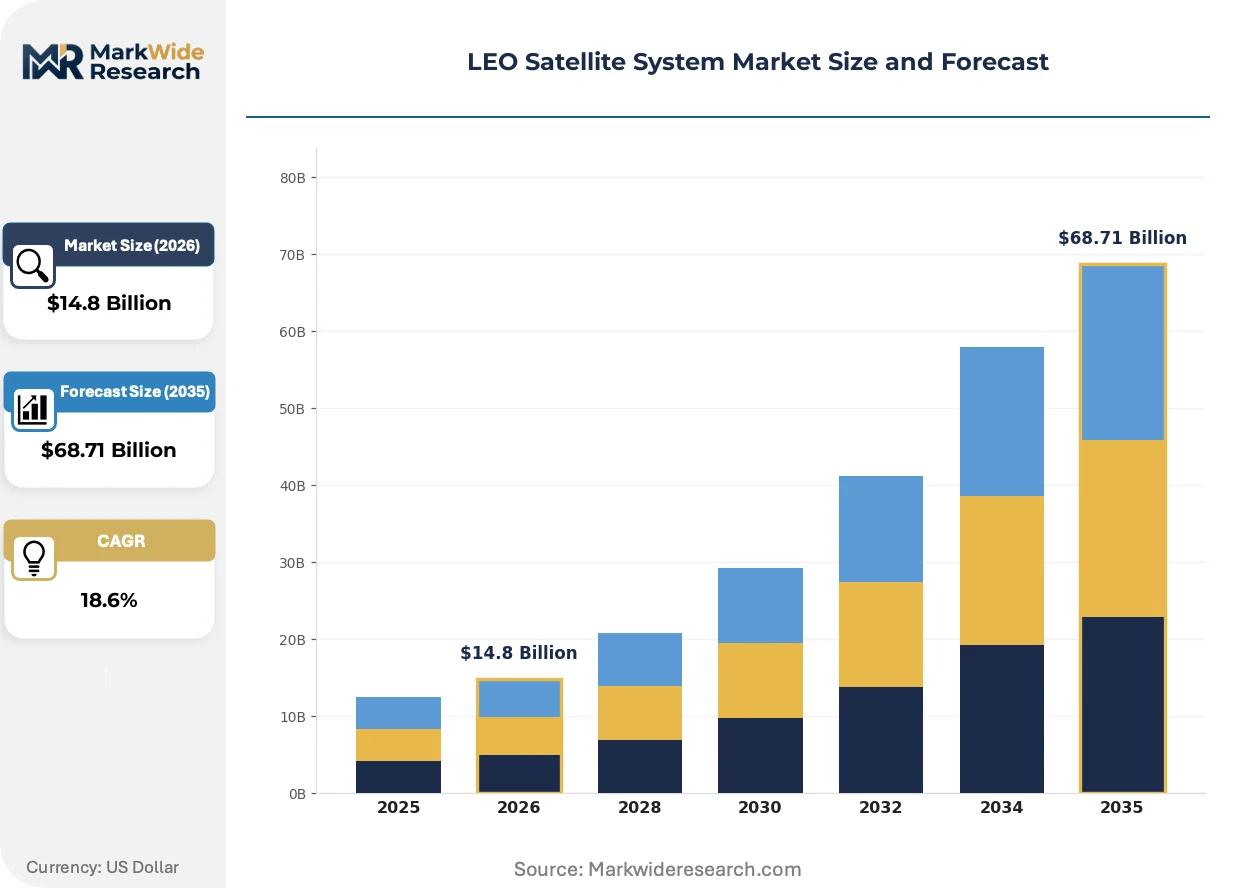
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Communication, Earth Observation, Navigation, Scientific Research, Technology Demonstration, Space Tourism Payload Technology: Optical Sensors, Synthetic Aperture Radar, Radio Frequency Transceivers, Laser Communication, Multispectral Imagers, Magnetometers End User: Telecom Operators, Defense Agencies, Environmental Agencies, Research Institutions, Satellite Internet Providers, Data Analytics Firms Service Offering: Data Transmission, Remote Sensing, Positioning & Timing, Scientific Data Services, Disaster Monitoring, Broadband Internet Access |
| Companies Covered | SpaceX, Lockheed Martin Corporation, Airbus Defence and Space, Thales Alenia Space, Northrop Grumman, OneWeb, Planet Labs PBC, OHB SE, China Aerospace Science and Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LEO Satellite System Market Trends and Innovations
Active beamforming and software-defined radio architectures are displacing fixed-pattern hardware, enabling dynamic spectrum reuse and real-time capacity reallocation across coverage footprints. This shift demands new supplier competencies in digital signal processing and thermal management at scale.
Software-defined payloads are expanding into mission planning workflows, allowing operators to reconfigure sensor suites and communication modes via orbital software updates rather than hardware replacement. Defense agencies and Earth observation providers are adopting this capability fastest, compressing satellite replacement cycles from seven years to three-year technology refresh intervals. The technology is expanding into commercial maritime surveillance contracts where seasonal coverage requirements shift between fishing monitoring and route optimization.
The EU AI Act's risk classification framework for autonomous satellite operations is mandating algorithmic transparency and human-in-the-loop protocols for collision avoidance systems. European constellation operators must now document decision pathways for autonomous maneuvering, creating compliance overhead that favors larger players with dedicated regulatory affairs functions. Synthetic aperture radar missions with automated target recognition face the strictest scrutiny, driving partnerships between satellite operators and European AI audit firms.
Consolidated procurement by national broadband agencies is displacing fragmented enterprise contracts as the dominant demand channel. India's Universal Service Obligation Fund and similar vehicles in Indonesia and the Philippines now aggregate rural connectivity demand into multi-year, multi-satellite awards that exclude smaller constellation operators lacking balance sheet scale. This concentration is most visible in Southeast Asia, where telecom operators are scaling deployments through government-backed anchor tenancy agreements rather than direct retail subscriber acquisition.
LEO Satellite System Market Segmentation
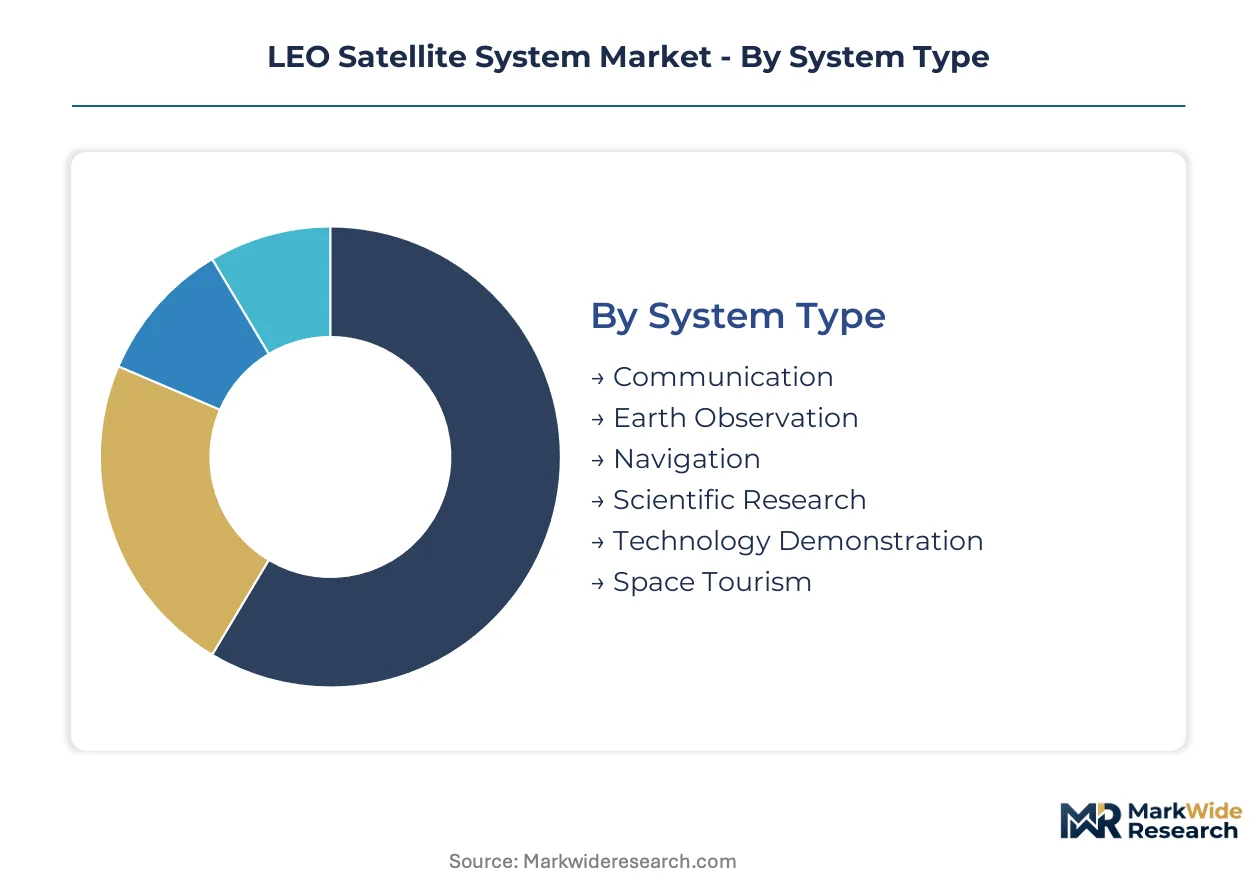
LEO satellite procurement decisions pivot on orbital altitude, payload mass, and regulatory compliance requirements. System architects must balance standardized bus designs against mission-specific customization, with each segmentation dimension imposing distinct supplier qualification criteria and lifecycle cost structures.
System Type:
Capital allocation intensity separates constellation strategies, with recurring launch cadence and ground infrastructure requirements dictating buyer budget profiles.
- Communication:Constellations deploy phased array antennas and inter-satellite laser links to deliver sub-50ms latency broadband. India's BharatNet rural connectivity initiative and Southeast Asian telecom operator anchor tenancy agreements concentrate procurement volumes here.
- Earth Observation:Specialized sensor platforms capture multispectral and radar imagery for defense intelligence and environmental monitoring. All-weather synthetic aperture radar capability commands premium unit economics that optical sensors cannot match.
- Navigation:Augmentation payloads enhance GNSS precision for aviation and maritime applications requiring centimeter-level accuracy.
- Scientific Research:Custom orbital configurations support atmospheric chemistry, ionospheric studies, and space weather monitoring missions.
- Technology Demonstration:Risk-tolerant platforms validate novel propulsion, power, or communication subsystems before operational deployment.
- Space Tourism:Crew-rated capsules and habitation modules operate at lower altitudes with enhanced deorbit safety margins.
Volume sits with Communication; growth tilts toward Earth Observation.
Payload Technology:
Sensor modality determines addressable market breadth, with weather-independent and nighttime operational capability expanding contractable use cases.
- Optical Sensors:Electro-optical imagers deliver sub-meter resolution for agriculture and urban planning. Performance degrades under cloud cover, limiting defense and tropical zone contracts.
- Synthetic Aperture Radar:Active microwave systems penetrate clouds and darkness for persistent surveillance. Pentagon and NATO environmental monitoring budgets favor this technology for Arctic and maritime domain awareness.
- Radio Frequency Transceivers:Ku-band and Ka-band systems enable direct-to-consumer broadband terminals.
- Laser Communication:Optical crosslinks eliminate ground station routing for polar coverage routes.
- Multispectral Imagers:Narrowband filters distinguish crop health and mineral signatures for precision agriculture.
- Magnetometers:Vector field sensors map geomagnetic anomalies for geophysical exploration.
Deployment scale favors Radio Frequency Transceivers; technology refresh rates run highest for Synthetic Aperture Radar.
End User:
Contract structure and payment security vary sharply across buyer categories, with sovereign-backed procurement offering longer visibility than commercial subscriptions.
- Telecom Operators:National carriers aggregate rural connectivity demand into multi-year awards. Indonesia and Philippines universal service funds now require balance sheet scale that excludes smaller constellation ventures.
- Defense Agencies:Classified mission requirements mandate Pentagon and NATO mission assurance protocols. Lockheed Martin sustains premium positioning through hardened supply chains and ITAR-compliant manufacturing.
- Environmental Agencies:Climate monitoring contracts require long-term data continuity guarantees.
- Research Institutions:Grant-funded missions prioritize scientific return over commercial durability.
- Satellite Internet Providers:Direct-to-consumer retail models demand mass-manufactured terminal cost reduction.
- Data Analytics Firms:Downstream value extraction depends on proprietary algorithm development.
Contract value concentrates with Defense Agencies; subscriber growth accelerates fastest for Satellite Internet Providers.
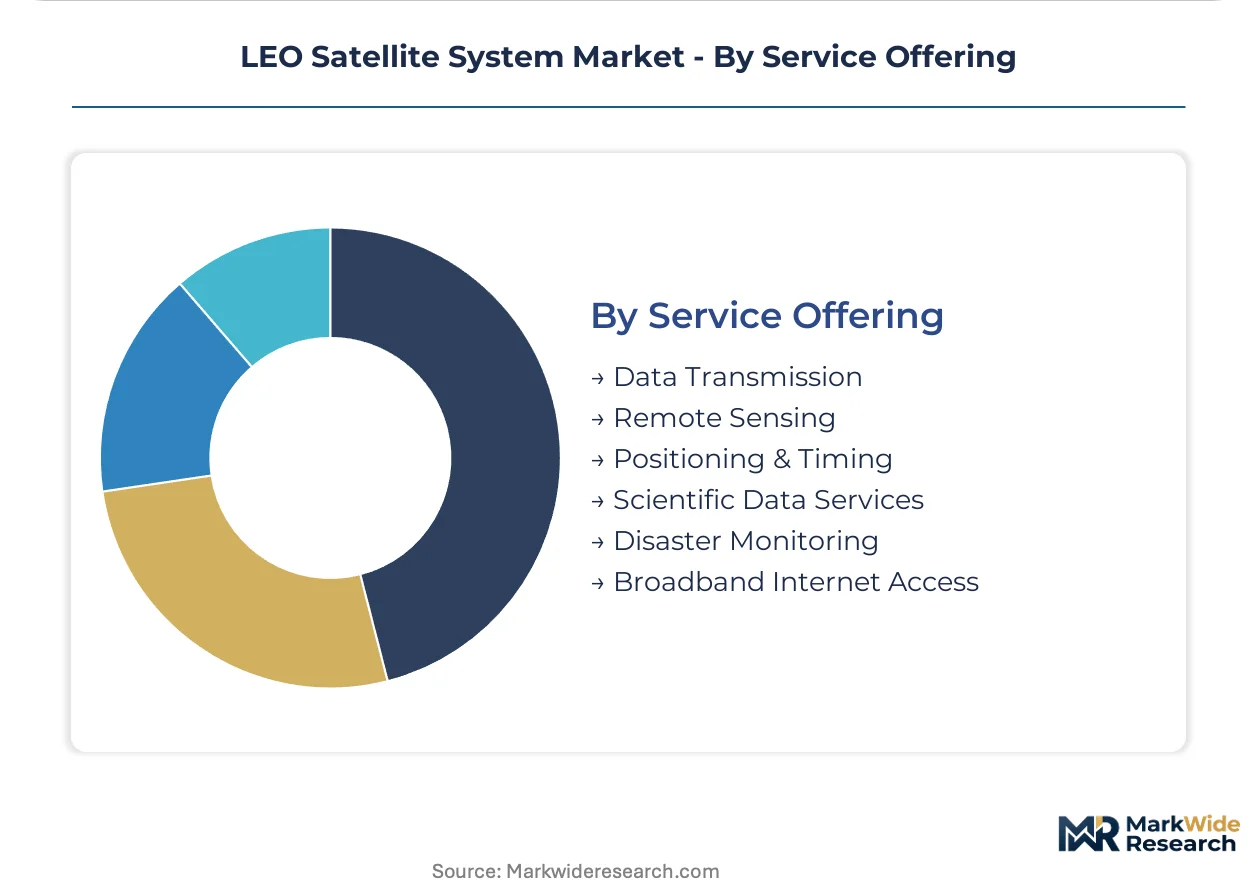
Service Offering:
Revenue model stability diverges between recurring subscription services and project-based analytics deliverables.
- Data Transmission:Backbone connectivity for maritime, aviation, and remote enterprise networks. FCC streamlined licensing accelerates orbital slot allocation for operators targeting this segment.
- Remote Sensing:Imagery and analytics subscriptions for agriculture, insurance, and defense intelligence. EU CSRD sustainability disclosure mandates create first-mover advantages for operators with certified circular design protocols.
- Positioning & Timing:Precision navigation augmentation for autonomous systems and financial networks.
- Scientific Data Services:Curated datasets for climate modeling and space weather prediction.
- Disaster Monitoring:Rapid tasking for flood, fire, and seismic event response.
- Broadband Internet Access:Consumer and SME connectivity in underserved districts.
Recurring revenue stability favors Data Transmission; margin expansion potential runs strongest for Remote Sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration tilts toward established aerospace clusters, while demand generation spreads across emerging connectivity markets. Regulatory frameworks diverge sharply between streamlined commercial licensing regimes and stringent defense-grade protocols. Capital deployment tracks government-backed rural broadband programs and polar route maritime coverage gaps.
United States
FCC streamlined licensing accelerates orbital slot allocation for constellation operators, reducing deployment timelines. The Pentagon and NATO mission assurance protocols sustain premium procurement channels for defense-grade spacecraft. California's aerospace corridor hosts vertically integrated launch-to-terminal manufacturing operations that compress production cycles.
India
BharatNet rural broadband initiative generates dedicated procurement pipelines for LEO connectivity infrastructure across underserved districts. TRAI spectrum coordination and expanding ground station partnerships streamline operator market entry. Karnataka and Telangana host emerging satellite manufacturing clusters serving domestic and export demand.
Germany
EU CSRD sustainability disclosure mandates create first-mover advantages for constellations with certified circular design protocols. The EU AI Act's risk classification framework imposes algorithmic transparency requirements for autonomous satellite operations. Bavaria and Bremen anchor European payload integration and optical sensor development capabilities.
United Kingdom
OneWeb's polar orbit coverage strategy addresses maritime and aviation latency failures where geostationary systems underperform. UK Space Agency funding mechanisms support synthetic aperture radar payload development for defense intelligence applications. Scotland's spaceport infrastructure enables dedicated small satellite launch cadence independent of heavy-lift bottlenecks.
China
MIIT spectrum allocation and national satellite internet program drive constellation deployment scale. China Aerospace Science and Technology Corporation anchors state-backed manufacturing capacity for broadband and Earth observation spacecraft. Beijing-Tianjin-Hebei corridor concentrates optical inter-satellite link development and ground segment integration expertise.
LEO Satellite System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across segmented procurement channels. Defense agencies favor established contractors with ITAR-compliant supply chains and hardened manufacturing protocols, while commercial broadband operators prioritize launch cost reduction and terminal manufacturing scale. Three archetypes dominate: vertically integrated launch-to-service providers, modular payload subsystem specialists, and defense-grade mission assurance contractors. Competitive moves concentrate on spectrum filing precedence acquisition and ground station partnership networks.
Within the defense-grade tier, Lockheed Martin Corporation and Northrop Grumman exemplify established contractors sustaining premium positioning through Pentagon and NATO procurement channels. SpaceX occupies a position at the vertically integrated extreme, controlling launch, spacecraft manufacturing, and terminal production within a single corporate structure. Among European-based operators, Airbus Defence and Space and Thales Alenia Space represent the transnational consortium model, leveraging multi-country supply chains and dual-use technology transfer agreements.
| Leading Market Players |
|---|
| SpaceX |
| Lockheed Martin Corporation |
| Airbus Defence and Space |
| Thales Alenia Space |
| Northrop Grumman |
| OneWeb |
| Planet Labs PBC |
| OHB SE |
| China Aerospace Science and Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Full-stack vertical integration from launch vehicles through terminal manufacturing anchors both supply security and pricing power for dominant constellation operators. SpaceX's captive control over Falcon 9 launch cadence and Starlink terminal production compresses procurement cycles while insulating margins from supplier pricing volatility that fragments smaller competitors.
Pricing Analysis
Cost-down pressure on broadband service tiers accelerates as SpaceX's mass-manufactured terminals undercut legacy geostationary hardware economics. Three-tier pricing structure across premium maritime, standard enterprise, and economy consumer levels differentiates by latency guarantees and installation support. Defense-grade mission assurance protocols command substantial premiums over commercial service levels. Telecom operators in Southeast Asia exhibit highest price sensitivity due to government-funded rural connectivity mandates with fixed budget envelopes.
Supply Chain Analysis
RF engineering talent scarcity in California and Bavaria constrains phased array antenna production scaling for second-tier constellation operators. Manufacturing concentrates in the United States, Germany, and China, with optical inter-satellite link components drawing from specialized photonics suppliers in the Beijing-Tianjin-Hebei corridor. Gallium nitride power amplifiers and radiation-hardened field-programmable gate arrays represent critical single-source vulnerabilities. Distribution runs through national broadband agency procurement channels rather than direct retail subscriber acquisition in emerging connectivity markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation operators face a vertical-integration race where launch cost control and terminal manufacturing scale determine viable unit economics. Winners will consolidate upstream rocket production or downstream subscriber equipment supply.
For Market Incumbents: Deploy spectrum filing precedence acquisition to lock orbital slots ahead of ITU coordination deadlines. Incumbents should accelerate ground station partnership networks in India and Southeast Asia before BharatNet procurement windows close to emerging entrants with leaner balance sheets. Laser inter-satellite link deployment represents the critical capability lever for polar route coverage differentiation.
For New Entrants and Emerging Players: FCC streamlined licensing in the United States opens a window for rapid constellation deployment without multi-year regulatory delays facing late ITU filers. New entrants should target synthetic aperture radar payloads for defense and environmental monitoring contracts where optical sensor limitations create addressable white space. Partnerships with European AI audit firms offer go-to-market positioning for EU AI Act compliance.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense-grade mission assurance contractors with ITAR-compliant supply chains and Pentagon procurement relationships. Long-term viability favors operators with demonstrated launch cost reduction and sustainable debris mitigation protocols. The signal to watch is consolidation pressure from capital constraints forcing sub-scale constellation architectures toward acquisition or bankruptcy.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Inter-Satellite Link Deployment | Eliminates ground station dependency for polar maritime routes, slashing operational costs for OneWeb and competitors. |
| Synthetic Aperture Radar Payload Expansion | Penetrates Pentagon and NATO environmental monitoring budgets that cloud-limited optical sensors cannot access. |
| EU CSRD Circular Design Certification | Creates first-mover advantage for European operators facing mandatory orbital debris transparency disclosures. |
| India Ground Station Partnership Network | Secures BharatNet rural broadband procurement pipeline through TRAI-coordinated spectrum access. |
| Vertical Launch-to-Terminal Integration | SpaceX captures margin at every layer from Falcon 9 production to Starlink manufacturing, compressing competitor economics. |
Research Methodology
Document review covered FCC licensing databases, ITU frequency coordination filings, and ESA procurement records, complemented by interviews with constellation program managers, satellite bus engineers, ground station operators, and national broadband agency procurement directors. Secondary validation drew from Pentagon budget justifications, EU Space Programme documents, and commercial launch manifests. Bottom-up unit economics modeling triangulated against top-down market sizing from disclosed constellation deployment plans.
Historical launch cost trajectories cross-referenced against panel input from launch service providers and satellite manufacturers informed the analytical framework across the analysis window. Segmentation dimensions modeled include system type, payload technology, end user category, and service offering. CAGRs derived from deployment schedule phasing and terminal manufacturing scale assumptions, with specific inputs from disclosed Starlink subscriber growth and OneWeb maritime contract values.
Caveats apply where launch capacity bottlenecks, spectrum coordination delays, or debris mitigation rulemaking could materially shift the outlook for constellation unit economics. Forecasts reflect documented deployment schedules and disclosed procurement pipelines rather than speculative demand projections. Material deviation in FCC licensing timelines or ITU enforcement priorities warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Commercial Satellite Launch Service Market
Satellite
US Remote Sensing Technology Market
Satellite
China Satellite Connectivity Market
Satellite
Global Broadband Satellite Services Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Satellite Operation Service Market
Satellite
Reconnaissance Satellite Market
Satellite
Russia Satellite Communications Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
LEO and GEO Satellite Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Remote Sensing Satellite Market
Satellite
Military Satellite Market