
 Naval Gas Turbine Market | 2026-2036
Naval Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Gas Turbine Market Foresight
Long-term service agreements covering hot-section refurbishment and predictive diagnostics is broadening revenue models beyond original equipment sales. GE Vernova leverages its distributed service network to sustain recurring revenue from installed marine turbine fleets. Rolls-Royce anchors its position through integrated power and propulsion packages for surface combatants. Mitsubishi Heavy Industries differentiates via in-house production of advanced blade alloys and casting capabilities.
Naval gas turbines are aeroderivative or industrial-frame engines modified for maritime propulsion, typically delivering 25 to 50 megawatts per unit and operating on distillate marine fuels or naval distillate to achieve power-to-weight ratios critical for high-speed naval operations. Heavy-duty turbines dominate installed base revenue due to their use in destroyer and cruiser main propulsion, while hybrid-cycle technology represents the fastest-growing segment as navies seek fuel efficiency gains without sacrificing sprint speed. Closed-cycle configurations command premium positioning for submarine air-independent propulsion applications where thermal signature management determines mission survivability.
The U.S. Navy's Naval Sea Systems Command enforces MIL-STD-167 vibration standards and MIL-S-901 shock requirements that shape turbine mounting and isolation system design. EMA's environmental standards for European defense procurement, alongside IMO Tier III NOx regulations administered by flag-state authorities, constrain engine combustion architecture choices. Stakeholders must monitor how evolving undersea warfare requirements redistribute investment between open-cycle surface combatant turbines and closed-cycle submarine propulsion systems.
Market Dynamics
Frigate modernization programs across NATO navies are consolidating procurement around medium-duty turbine configurations, while IMO Tier III NOx mandates force combustion architecture redesigns across the installed base.
Growth Catalysts
- EMA defense procurement standards:European naval modernization mandates are accelerating fleet-wide propulsion upgrades across surface combatant classes.
- Hybrid-cycle architectures:Fuel efficiency requirements for sustained cruising operations are driving adoption of combined-cycle turbine systems.
- South Korean shipbuilding cluster:DSME and HHI yards are concentrating demand for indigenous and licensed turbine production.
Market Restraints
- Superalloy supply concentration:Single-source dependence for advanced blade castings limits production flexibility and creates input cost volatility.
- MIL-S-901 shock certification:Extended qualification timelines for new turbine mounting systems delay platform integration.
- Closed-cycle submarine systems:Air-independent propulsion alternatives face thermal management constraints that cap power density.
Strategic Opportunities
- Long-term service agreements:Predictive diagnostics and hot-section refurbishment contracts are displacing transactional spare parts sales.
- Distillate-compatible hybrid systems:Dual-fuel architectures enable compliance with evolving flag-state emission requirements without infrastructure overhaul.
- Undersea warfare pivot:Thermal signature management priorities are redirecting investment toward closed-cycle submarine propulsion development.
Industry Challenges
- Precision casting skill gaps:Turbine blade foundry expertise concentrates at a handful of facilities, constraining workforce scaling.
- Legacy platform integration:New turbine generations must interface with existing reduction gear and shafting systems designed for prior power curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Gas Turbine Market |
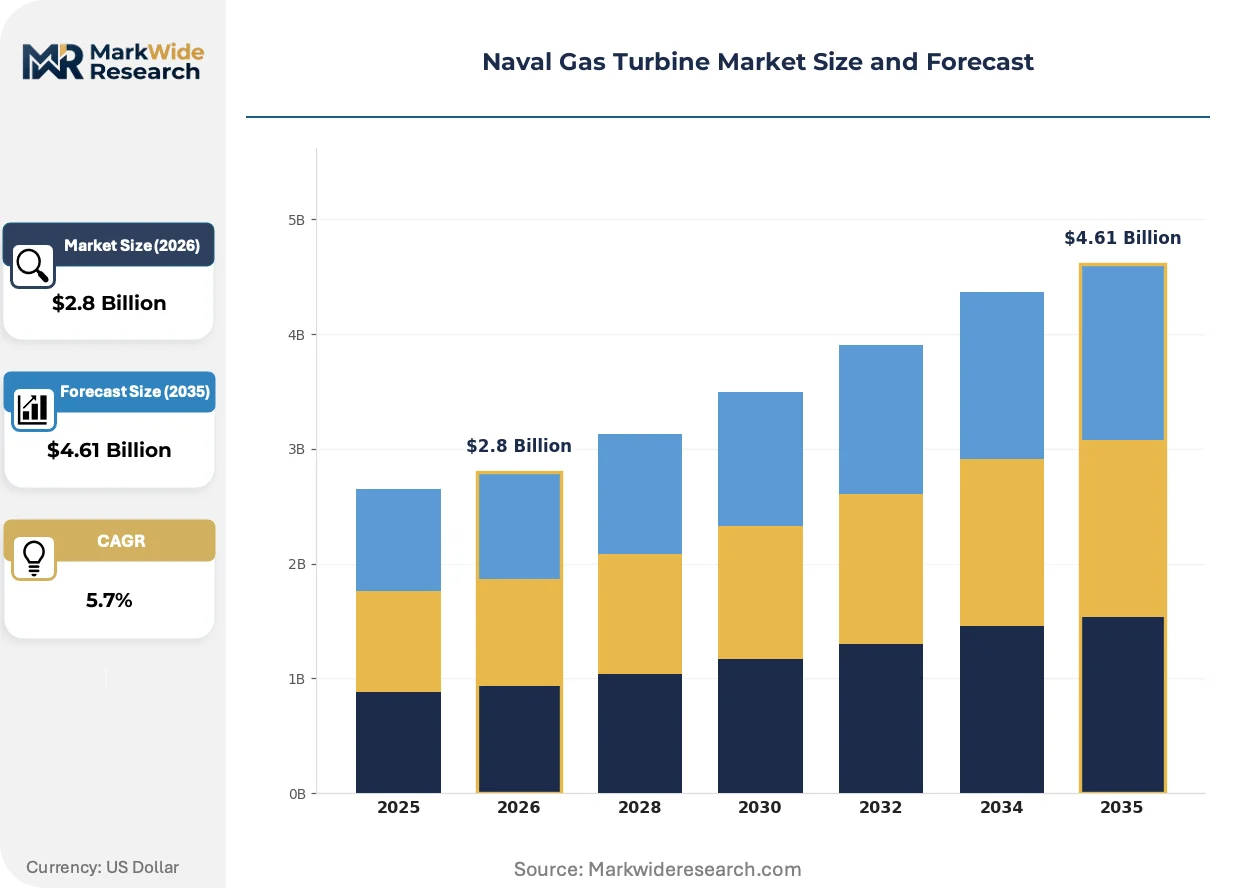
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Heavy-duty, Medium-duty, Low-duty, High-speed Application: Naval Ships, Submarines, Auxiliary Vessels, Power Generation Technology: Closed Cycle, Open Cycle, Hybrid, Combined Cycle End User: Defense Forces, Naval Contractors, Government Agencies, Research Institutions |
| Companies Covered | Kawasaki Heavy Industries, Ltd, GE Vernova, General Electric Company, Vericor, Rolls-Royce, Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries, Ltd., Hindustan Aeronautics Limited, IHI Power Systems Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Gas Turbine Market Shifts & Advancements
Maritime propulsion engineering is converging on architectures that balance sprint performance with sustained efficiency, reshaping how navies specify power systems for multi-mission surface combatants.
Additive manufacturing for turbine hot-section components is expanding into repair and replacement part production. Naval maintenance depots in the United States and United Kingdom are qualifying laser-deposited superalloy structures for blade restoration. This distributed repair capability is expanding into field-level maintenance, compressing turnaround times for deployed fleets.
IMO Tier III NOx regulations administered by flag-state authorities are mandating selective catalytic reduction or lean-premixed combustion for new-build turbines. European navies operating in Emission Control Areas face the strictest compliance timelines. Destroyer and frigate programs in Germany and France are prioritizing engines with integrated after-treatment systems.
Performance-based logistics contracts are displacing traditional time-and-material service arrangements. Royal Navy and Royal Australian Navy sustainment frameworks now tie contractor payments to availability metrics rather than parts delivery. This incentive realignment is most visible in the United Kingdom's Type 26 frigate support structure, where turbine availability guarantees drive predictive maintenance investment.
Naval Gas Turbine Market Segmentation
Naval gas turbine procurement patterns diverge sharply between surface combatant programs requiring sustained power output and submarine applications demanding thermal signature suppression. Platform-specific operational profiles dictate divergent specifications across power density, fuel flexibility, and shock tolerance requirements.
Type:
Platform displacement and mission endurance requirements separate buyers into distinct procurement tiers with incompatible technical specifications.
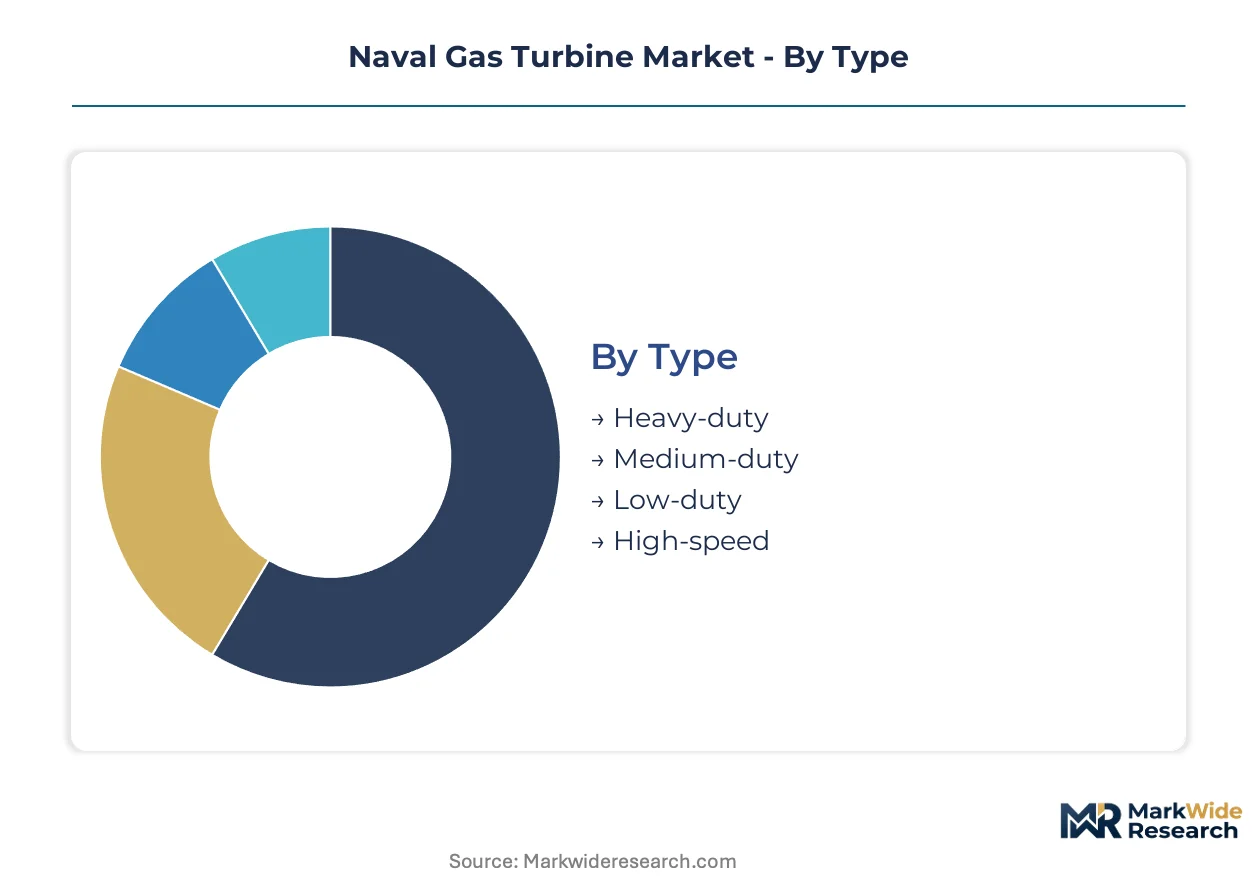
- Heavy-duty:Industrial-frame turbines rated above 35 megawatts dominate destroyer and cruiser main propulsion installations. Demand concentrates in U.S. Navy Arleigh Burke-class modernization and Japan Maritime Self-Defense Force Maya-class programs, where shock-hardened mounting systems under MIL-S-901 certification extend qualification timelines.
- Medium-duty:Aeroderivative configurations delivering 20-35 megawatts anchor frigate propulsion architectures. NATO modernization programs across Germany, France, and Italy are consolidating procurement around standardized medium-duty specifications to achieve fleet commonality.
- Low-duty:Compact turbines below 20 megawatts serve auxiliary vessel and patrol craft applications.
- High-speed:Lightweight derivatives optimized for rapid acceleration support littoral combatant and fast attack craft missions.
Volume sits with Heavy-duty configurations; growth tilts toward Medium-duty standardization across allied fleet programs.
Application:
Operational environment constraints create irreconcilable design priorities between submerged and surface propulsion architectures.
- Naval Ships:Surface combatant propulsion systems prioritize power-to-weight ratios for sprint speed and sustained cruising efficiency. South Korean DSME and HHI yards are concentrating demand for indigenous turbine production aligned with KDX-III destroyer and FFX-III frigate programs.
- Submarines:Closed-cycle configurations for air-independent propulsion face thermal management constraints that cap power density. Investment is redirecting toward thermal signature suppression technologies as undersea warfare priorities intensify.
- Auxiliary Vessels:Replenishment and support ships utilize commercial-derivative turbines with reduced shock requirements.
- Power Generation:Shore-based naval facility applications employ industrial-frame turbines with stationary mounting configurations.
Revenue concentrates in Naval Ships; expansion accelerates most quickly in Submarine closed-cycle development.
Technology:
Combustion architecture selection determines compliance pathways against tightening IMO NOx mandates and thermal signature requirements.
- Hybrid:Combined-cycle systems integrating gas turbines with waste heat recovery achieve fuel efficiency gains without sacrificing sprint capability. European navies operating in Emission Control Areas are prioritizing hybrid architectures for Type 26 and FDI frigate programs to meet EMA environmental standards.
- Closed Cycle:Sealed combustion systems enable submarine air-independent propulsion with minimal exhaust signature. Thermal management limitations restrict power output, constraining deployment to auxiliary propulsion roles.
- Open Cycle:Conventional configurations dominate existing surface combatant installed bases requiring combustion redesign for Tier III compliance.
- Combined Cycle:Integrated steam bottoming cycles maximize thermal efficiency for sustained operations.
Installed base remains Open Cycle; technology investment tilts toward Hybrid configurations.
End User:
Contracting authority and funding mechanisms create distinct procurement rhythms and specification authority patterns.
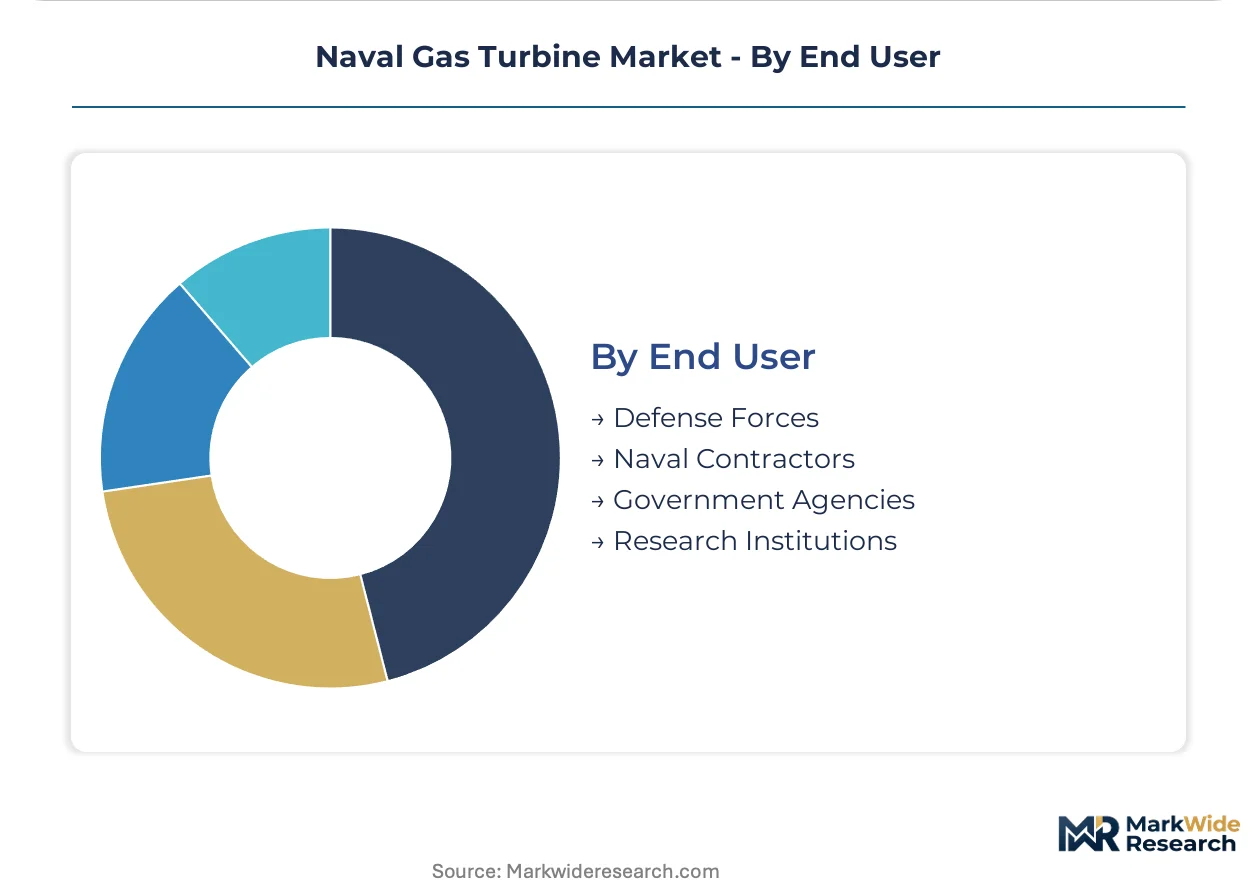
- Defense Forces:National naval services exercise direct specification authority over combatant propulsion systems. The U.S. Naval Sea Systems Command enforces MIL-STD-167 vibration standards that shape turbine mounting and isolation system design across supplier base.
- Naval Contractors:Shipyard integrators manage licensed production and subsystem procurement for export programs. South Korean yards are expanding indigenous turbine assembly capabilities under technology transfer arrangements.
- Government Agencies:Coast guard and maritime security organizations procure commercial-derivative configurations with reduced military specifications.
- Research Institutions:Naval laboratories fund advanced combustion and materials development programs.
Procurement volume rests with Defense Forces; contractor-led production is gaining share fastest in export market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in South Korea and Japan while procurement demand clusters in NATO naval modernization programs. Shipyard capacity in East Asia supplies turbine-integrated propulsion packages to European and American fleet renewal initiatives.
United States
Arleigh Burke-class destroyer modernization and Constellation-class frigate construction drive heavy-duty turbine demand. The Naval Sea Systems Command enforces MIL-S-901 shock certification that shapes supplier qualification timelines. Procurement flows through General Dynamics and Huntington Ingalls yards in Virginia and Mississippi.
South Korea
KDX-III destroyer and FFX-III frigate programs anchor indigenous turbine assembly expansion. DSME and HHI yards in Geoje and Ulsan concentrate licensed production under technology transfer arrangements. The Defense Acquisition Program Administration prioritizes local content thresholds for combatant propulsion systems.
Germany
F126 frigate and Type 212CD submarine programs sustain medium-duty and closed-cycle turbine demand. EMA environmental standards mandate Tier III NOx compliance for surface combatants operating in Emission Control Areas. Thyssenkrupp Marine Systems in Kiel and Wolgast coordinates propulsion integration for NATO export programs.
Japan
Maya-class destroyer and 30FFM frigate procurement supports aeroderivative turbine production. The Ministry of Defense accelerates fleet-wide propulsion upgrades under National Defense Program Guidelines. Mitsubishi Heavy Industries in Nagasaki and Kobe anchors indigenous heavy-duty turbine manufacturing for Maritime Self-Defense Force programs.
United Kingdom
Type 26 frigate and Dreadnought submarine programs drive hybrid-cycle and closed-cycle system investment. The Ministry of Defence employs performance-based logistics contracts tying contractor payments to turbine availability metrics. BAE Systems Surface Ships in Glasgow integrates Rolls-Royce propulsion packages for Royal Navy and export customers.
Naval Gas Turbine Market Competitive Landscape
Top-tier vendors anchor integrated power and propulsion packages, while mid-tier specialists concentrate on component supply and licensed assembly. The vendor base stratifies between full-system integrators and foundry-dependent component fabricators. Two strategic archetypes dominate: aeroderivative engine specialists with aviation heritage and industrial-frame turbine builders with heavy manufacturing footprints. Competitive moves center on long-term service agreement expansion and hot-section refurbishment network buildout.
Within the integrated systems tier, GE Vernova and Rolls-Royce occupy positions spanning surface combatant propulsion through submarine power systems. Mitsubishi Heavy Industries exemplifies the vertically integrated archetype through captive blade alloy casting capabilities. Bharat Heavy Electricals Limited represents the licensed production model, assembling turbines under technology transfer for indigenous naval programs.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries, Ltd |
| GE Vernova |
| General Electric Company |
| Vericor |
| Rolls-Royce |
| Bharat Heavy Electricals Limited |
| Mitsubishi Heavy Industries, Ltd. |
| Hindustan Aeronautics Limited |
| IHI Power Systems Co. Ltd. |
| Others |
Supply & Pricing Matrix
Precision casting skill gaps in the United States and Japan widen labor-cost differentials between premium MIL-S-901 certified turbine assemblies and standard commercial-derivative units. This workforce concentration compresses margins for foundry-dependent fabricators while amplifying pricing power for vertically integrated producers with in-house blade alloy capabilities.
Pricing Analysis
Margin tightening in heavy-duty turbine configurations reflects superalloy input cost volatility and extended shock certification timelines. Three-tier pricing structure across premium certified, standard military-grade, and commercial-derivative levels separates buyers by mission-critical tolerance. Price differentiation hinges on MIL-S-901 shock certification tier and hot-section refurbishment bundling. Cost-down pressure on medium-duty frigate turbines accelerates because NATO standardization programs consolidate procurement volumes. Export licensees in South Korea exhibit highest price sensitivity; U.S. Naval Sea Systems Command direct procurement shows lowest.
Supply Chain Analysis
Single-source vulnerability sits with advanced nickel-based superalloy castings concentrated in the United States, Japan, and United Kingdom foundries. Raw material dependencies span cobalt-chrome alloys, single-crystal casting feedstock, and ceramic core materials. Supply chain risk centers on precision casting workforce constraints that cap foundry throughput regardless of capital investment. Distribution runs through naval shipyard integrators and defense contractor procurement channels rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where IMO Tier III NOx mandates and MIL-S-901 shock certification erect barrier-to-entry moats for qualified producers. Regulatory qualification timelines measured in years rather than months protect incumbent positions while stranding non-compliant capital.
For Market Incumbents:Hedge against superalloy supply concentration by securing long-term offtake agreements with Japanese and U.S. foundry operators. Expand predictive diagnostics service networks to capture recurring revenue from installed marine turbine fleets as original equipment sales plateau. Defensive priority centers on hot-section refurbishment capability buildout that locks in depot-level maintenance relationships.
For New Entrants and Emerging Players:Additive manufacturing for blade restoration represents a technology-first wedge into aftermarket service contracts where qualification barriers are lower than new-build turbine certification. White-space targets concentrate on South Korean licensed production partnerships and European Emission Control Area retrofit programs. Most penetrable entry point sits with field-level laser-deposited repair services for deployed NATO fleets.
For Investors and Strategic Acquirers:Re-rating potential sits with vertically integrated turbine producers given hybrid-cycle technology investment acceleration across European frigate programs. Long-term viability framing favors asset-light service network operators over capital-intensive foundry operators. Acquisition target archetype: precision casting specialists with MIL-S-901 qualified capacity. Signal to watch: performance-based logistics contract award velocity in Royal Navy and Royal Australian Navy programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Section Refurbishment Network Expansion | GE Vernova leverages distributed service depots to sustain recurring revenue from installed marine turbine fleets. |
| Hybrid-Cycle Technology Licensing | Rolls-Royce anchors Royal Navy Type 26 frigate programs with integrated power and propulsion packages. |
| Indigenous Turbine Assembly Partnership | South Korean DSME and HHI yards expand licensed production under technology transfer arrangements. |
| Additive Manufacturing Qualification | Naval maintenance depots in the United States and United Kingdom compress turnaround times for deployed fleets. |
| Performance-Based Logistics Contracting | United Kingdom's Type 26 frigate support structure ties contractor payments to turbine availability metrics. |
Research Methodology
Document review covered naval procurement databases, IMO regulatory filings, and defense contractor technical disclosures, complemented by interviews with program managers at Naval Sea Systems Command, propulsion engineers at DSME and HHI, and aftermarket service directors at turbine OEMs. Secondary validation drew from customs trade data, SEC 10-K filings, and NATO defense procurement reports. Bottom-up installation data triangulated against top-down fleet modernization budget allocations.
Cross-referencing historical turbine delivery patterns with expert panel input on frigate modernization timelines shaped the projection framework. Segmentation modeling covered platform type, duty rating, combustion architecture, and end-user contracting authority across the analysis window. CAGRs derived from shipyard orderbook analysis and defense ministry procurement announcements. Industry-specific forecast inputs included KDX-III and FFX-III program schedules and Type 26 export contract velocity.
Several conditions sit outside the modeled scope, including classified submarine propulsion specifications and unannounced naval vessel programs. Forecasts reflect assumptions about NATO fleet commonality timelines and South Korean local content threshold enforcement. Specific risk factors that could revise projections encompass superalloy supply disruptions, shock certification standard revisions, and undersea warfare priority shifts redirecting investment toward closed-cycle systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Marine Radar Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Military Frigate Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Global Naval Vessel MRO Market