
 UAV Battery Market | 2026-2036
UAV Battery Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Battery Market Analysis
Defense procurement agencies is redrawing the UAV battery demand map as military drone programs displace consumer photography as the primary volume driver. Shenzhen Grepow Battery Co Ltd. leverages its proximity to Shenzhen's electronics manufacturing cluster to dominate high-discharge rate cell production for tactical drones. EaglePicher Technologies LLC anchors the North American defense supply chain with qualified solid-state designs for extended-loiter missions. Amperex Technology Limited competes aggressively on energy density metrics for commercial delivery platforms.
UAV batteries are electrochemical energy storage systems engineered for extreme power-to-weight ratios, typically employing lithium polymer or lithium-ion chemistries with discharge rates exceeding 5C and operating voltages between 11.1V and 22.2V to sustain rotor lift and avionics loads during flight. The lithium polymer segment leads current production volumes due to its form-factor flexibility and superior discharge characteristics, while the above 5000 mAh capacity tier captures the fastest growth as beyond-visual-line-of-sight missions require multi-hour endurance. Delivery services as an end-user category concentrates investment in fast-charging architectures, whereas the surveillance segment prioritizes silent thermal signatures and extended cycle life over peak power output.
FAA Part 107 and emerging Remote ID requirements in the United States, alongside EASA's drone-specific airworthiness standards in Europe, are tightening cell certification protocols and mandating traceable supply chains for flight-critical components. China's MIIT enforces GB standard compliance for domestic UAV power systems, creating divergent technical specifications that fragment cross-border product strategies. Battery stakeholders must monitor evolving airspace integration rules, as regulatory acceptance of autonomous beyond-visual-line-of-sight operations will determine whether endurance investments translate into addressable commercial demand.
Market Dynamics
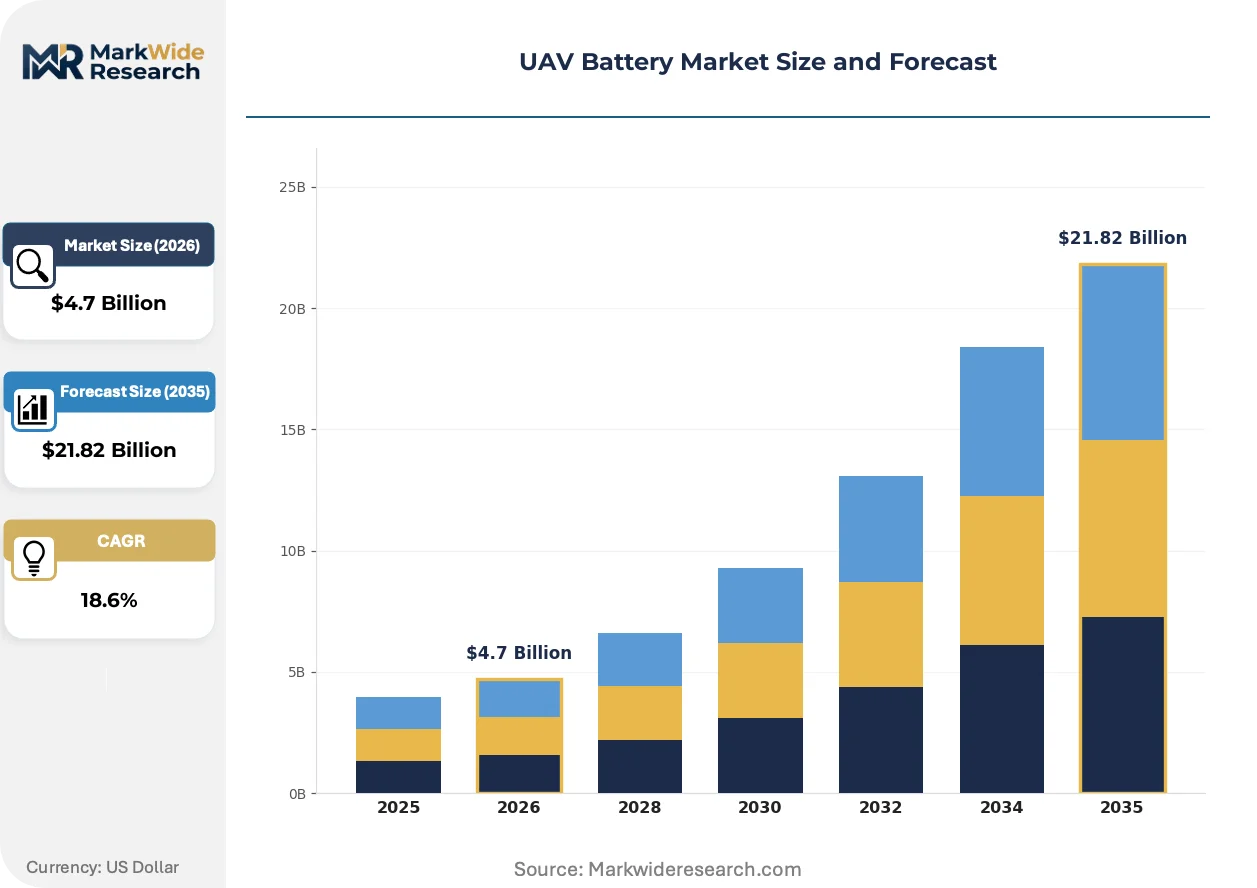
Military procurement agencies now dominate volume planning as defense ministries accelerate drone fleet modernization, compressing development cycles and demanding qualified solid-state architectures for extended-loiter missions.
Growth Catalysts
- Defense procurement acceleration:Military drone programs in the United States and China are absorbing high-discharge rate lithium polymer cells for tactical reconnaissance platforms, with procurement timelines shortening from 36 to 18 months.
- Remote ID mandates:FAA Part 107 and EASA drone-specific airworthiness standards are forcing battery traceability investments that improve supply chain reliability for flight-critical power systems.
- Solid-state electrolyte breakthroughs:Silicon-anode manufacturing advances are extending flight endurance thresholds beyond 5000 mAh for beyond-visual-line-of-sight commercial delivery routes.
Market Restraints
- Cobalt and lithium price volatility:Raw material input costs for cathode active materials fluctuate with DRC mining output and Chilean brine extraction constraints, compressing cell manufacturer margins.
- Shenzhen supply concentration:DJI's supplier ecosystem and domestic cell production in China create single-geography dependency risk for global OEM procurement strategies.
- GB standard fragmentation:China's MIIT enforces divergent technical specifications for domestic UAV power systems that complicate cross-border product certification and inventory management.
Strategic Opportunities
- Indian defense modernization:The country's unmanned aerial vehicle procurement programs under the Ministry of Defence represent underpenetrated demand for qualified high-discharge battery suppliers outside Chinese supply chains.
- Fast-charging architecture convergence:Silicon carbide power electronics paired with lithium titanate anodes are opening sub-15-minute recharge windows for commercial delivery fleet operators.
- Autonomous BVLOS regulatory tailwinds:FAA certification pathways for beyond-visual-line-of-sight operations will unlock multi-hour endurance investments currently stranded by operational restrictions.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturers face acute shortages of solid-state electrolyte specialists and thermal management engineers capable of qualifying defense-grade architectures.
- Dual-use export control complexity:ITAR and EAR regulations governing military drone battery shipments create licensing delays that extend order-to-delivery cycles by 4-6 months for international defense contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Battery Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium Polymer, Lithium-Ion, Nickel Cadmium, Nickel Metal Hydride End User: Aerospace, Agriculture, Surveillance, Delivery Services Capacity: Below 1000 mAh, 1000-3000 mAh, 3001-5000 mAh, Above 5000 mAh Weight: Lightweight, Medium Weight, Heavy Weight, Ultra-Lightweight |
| Companies Covered | SolidEnergy Systems Corporation, Shenzhen Grepow Battery Co Ltd., Amperex Technology Limited, Zhejiang Gens Ace Technology Co. Ltd., EaglePicher Technologies LLC, Skydio Inc., Genspow GmbH, Intelligent Energy Holdings plc, Yuneec International Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Battery Market Emerging Trajectories
Solid-state architectures and silicon-anode chemistries are compressing traditional lithium-ion development roadmaps, while regulatory acceptance of autonomous flight operations determines whether endurance investments translate into commercial demand.
Silicon-anode lithium-ion cells are displacing conventional graphite anode designs in high-endurance UAV applications. Defense procurement agencies in the United States and China are qualifying these architectures for 3+ hour loiter missions previously requiring liquid-fuel propulsion. The technology is displacing hybrid-electric powertrains in the 10-25 kg payload class, collapsing the performance gap between battery and combustion endurance.
EASA's drone-specific airworthiness standards and FAA Part 107 Remote ID requirements are mandating traceable supply chains for flight-critical battery components. Cell manufacturers must now document cathode material provenance and thermal runaway test data across batch records. Commercial delivery platforms in Europe face the strictest compliance timelines, with certification cycles extending 8-12 months for new cell introductions.
Defense ministries are consolidating procurement through national security frameworks that bypass traditional distributor channels. Battery suppliers now negotiate directly with military procurement agencies, disintermediating the electronics component distributors that historically managed UAV power system sales. This channel compression is most visible in the United States and Israel, where classified program requirements demand cleared facility manufacturing and direct OEM relationships.
UAV Battery Market Segmentation
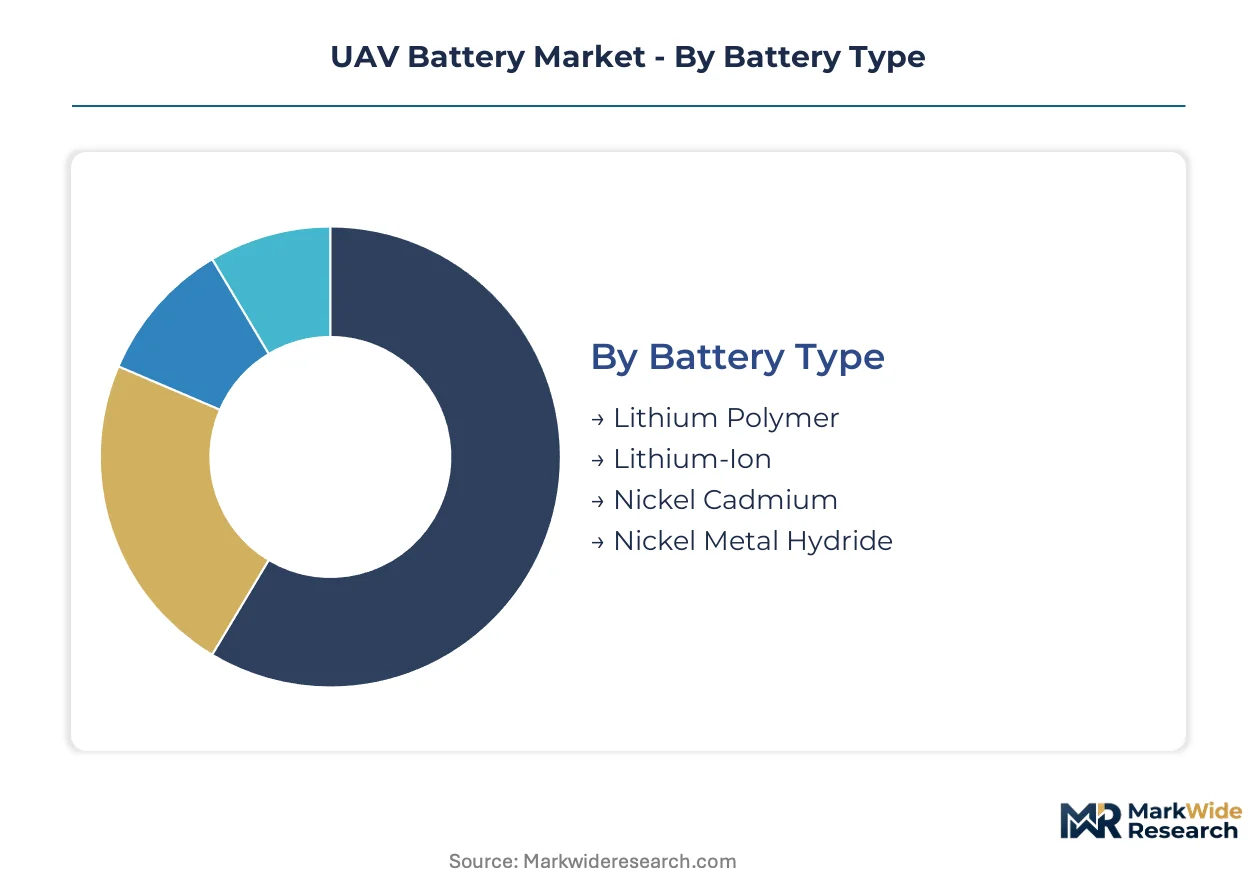
UAV battery segmentation reveals divergent technical requirements across mission profiles. Defense procurement, commercial delivery, and consumer photography each demand distinct electrochemical architectures, creating parallel supply chains with limited component interchangeability.
Battery Type:
Lithium polymer cells face substitution pressure from solid-state architectures in extended-endurance applications, while nickel-based chemistries confront displacement by lithium-ion in cost-sensitive consumer segments.
- Lithium Polymer:Flexible pouch construction enables custom form factors with discharge rates exceeding 5C. Military drone programs in the United States absorb high volumes for tactical reconnaissance platforms requiring rapid power delivery.
- Lithium-Ion:Cylindrical and prismatic formats deliver superior energy density for commercial delivery routes. China's DJI ecosystem sources predominantly from Shenzhen suppliers for photography drones.
- Nickel Cadmium:Ruggedized aviation-grade cells persist in legacy military platforms requiring extreme temperature tolerance.
- Nickel Metal Hydride:Hobbyist and training drone segments favor this chemistry for cost predictability amid raw material volatility.
Lithium polymer retains volume leadership; lithium-ion holds the steepest expansion curve.
End User:
Cost tier stratification separates defense-grade qualification investments from consumer electronics pricing pressures.
- Aerospace:Manned-unmanned teaming programs demand MIL-STD-810G qualified cells with traceable supply chains. FAA certification timelines extend 18-24 months for new battery introductions.
- Surveillance:Silent thermal signatures and extended cycle life outweigh peak power requirements. Border patrol agencies in Israel prioritize low-acoustic signatures for covert observation missions.
- Agriculture:Crop-spraying platforms require IP67-rated enclosures resisting chemical corrosion.
- Delivery Services:Fleet operators in Europe invest in fast-charging architectures under EASA drone-specific airworthiness standards.
Surveillance commands premium pricing; delivery services are expanding most quickly.
Capacity:
Volume concentration shifts upward as beyond-visual-line-of-sight missions displace short-range consumer applications.
- Above 5000 mAh:Silicon-anode manufacturing advances enable 3+ hour loiter missions. Defense procurement agencies qualify these architectures for persistent surveillance replacing liquid-fuel propulsion.
- 3001-5000 mAh:Commercial inspection drones balance endurance with payload flexibility. Energy sector operators in Norway deploy these cells for offshore wind turbine maintenance.
- 1000-3000 mAh:Photography drones dominate this tier with 20-30 minute flight durations.
- Below 1000 mAh:Racing drones and toy segments concentrate demand for ultra-high discharge rates.
Below 3000 mAh retains shipment volume; above 5000 mAh gains share fastest.
Weight:
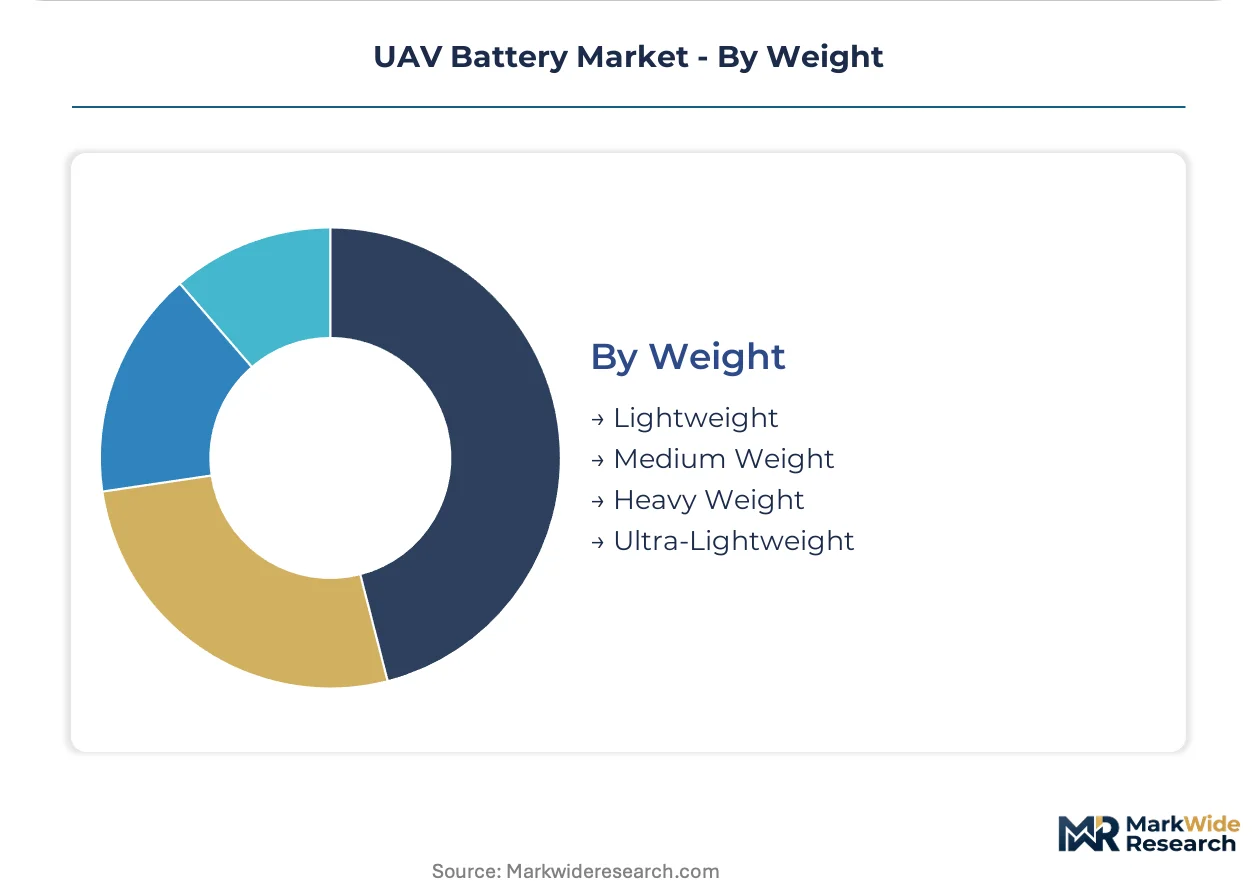
Application requirements dictate mass thresholds that segment manufacturing capabilities and pricing tiers.
- Ultra-Lightweight:Sub-50 gram cells enable insect-scale surveillance platforms. DARPA-funded programs in the United States push graphene-anode research for micro-air-vehicle endurance.
- Lightweight:Consumer photography drones prioritize this category for agility and portability. Chinese manufacturers achieve cost advantages through automated pouch-cell assembly.
- Medium Weight:Agricultural spraying platforms require structural reinforcement for chemical payload integration.
- Heavy Weight:Cargo delivery drones above 25 kg payload class demand reinforced thermal management systems.
Lightweight dominates unit shipments; ultra-lightweight shows the steepest technology investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell manufacturers supply defense procurement agencies across the United States, Israel, and India, creating a trade corridor that concentrates production in Shenzhen while end-use qualification occurs in buyer-country military laboratories.
United States
DOD drone fleet modernization programs absorb high-discharge lithium polymer cells for tactical reconnaissance platforms. FAA Part 107 Remote ID requirements mandate traceable supply chains for flight-critical battery components. EaglePicher Technologies LLC anchors the North American defense supply chain from its Missouri operations with cleared-facility manufacturing.
China
MIIT enforces GB standard compliance for domestic UAV power systems, creating divergent technical specifications that fragment cross-border product strategies. DJI's supplier ecosystem in Shenzhen concentrates high-volume cell production for consumer photography and commercial inspection drones. Zhejiang Gens Ace Technology Co. Ltd. operates from manufacturing clusters in Hangzhou and Ningbo.
Israel
Border patrol agencies prioritize low-acoustic signature batteries for covert observation missions along contested frontiers. The national defense procurement framework channels UAV battery demand through classified program offices rather than commercial distributors. Tel Aviv-area engineering firms specialize in thermal management systems for extended-loiter platforms.
India
Ministry of Defence unmanned aerial vehicle procurement programs represent underpenetrated demand for qualified suppliers outside Chinese supply chains. BIS certification requirements for imported power systems extend qualification timelines for foreign cell manufacturers. Bengaluru and Hyderabad host emerging drone assembly clusters seeking localized battery sourcing.
Germany
EASA drone-specific airworthiness standards impose the strictest compliance timelines for commercial delivery platforms, with certification cycles extending 8-12 months for new cell introductions. Industrial inspection operators in Bavaria deploy medium-capacity cells for offshore wind turbine maintenance. Munich-area engineering consultancies specialize in thermal runaway containment system design.
UAV Battery Market Vendor Landscape
Player mix skews toward vertically integrated cell manufacturers and defense-qualified system integrators, with limited interchangeability between commercial and military supply chains. The vendor base separates into three tiers: Shenzhen-based high-volume producers serving consumer and commercial segments, North American defense contractors with cleared-facility manufacturing, and European specialists in fuel-cell hybrid architectures. Consolidation pressure concentrates among mid-scale commercial suppliers facing margin compression from raw material volatility. Capacity expansion and direct military procurement relationships constitute the dominant competitive moves.
Among Shenzhen-based producers, Shenzhen Grepow Battery Co Ltd. and Amperex Technology Limited exemplify the high-volume archetype serving DJI's ecosystem and commercial delivery platforms. EaglePicher Technologies LLC occupies a position within the defense-qualified tier, representing the North American supplier base with established relationships to military procurement agencies. These three anchors illustrate the geographic and end-use segmentation that prevents direct competition across tiers.
| Leading Market Players |
|---|
| SolidEnergy Systems Corporation |
| Shenzhen Grepow Battery Co Ltd. |
| Amperex Technology Limited |
| Zhejiang Gens Ace Technology Co. Ltd. |
| EaglePicher Technologies LLC |
| Skydio Inc. |
| Genspow GmbH |
| Intelligent Energy Holdings plc |
| Yuneec International Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between defense procurement agencies and qualified cell manufacturers lock in both cathode material supply access and price visibility across volatile lithium and cobalt markets. These agreements compress distributor margins while securing volume commitments for solid-state electrolyte production lines in Missouri and Shenzhen.
Pricing Analysis
Silicon-anode lithium-ion cells command a 40-60% premium over conventional graphite-anode designs, while nickel metal hydride persists in hobbyist segments at economy positioning. Three-tier pricing structure across defense-qualified, commercial-grade, and consumer-economy levels separates MIL-STD-810G certified batches from DJI ecosystem cells. Pricing pressure stems from DRC mining output fluctuations compressing cathode active material costs. Delivery services in Europe show highest price sensitivity due to EASA certification overhead, whereas aerospace programs absorb premiums for traceable supply chains.
Supply Chain Analysis
Inventory cycles for high-discharge lithium polymer cells stretch 16-20 weeks as defense procurement agencies front-load qualified cell orders ahead of FAA certification deadlines. Manufacturing concentrates in China, South Korea, and the United States, with Shenzhen pouch-cell assembly feeding DJI's ecosystem and EaglePicher's Missouri operations serving classified programs. Raw material flows draw from Chilean brine extraction and DRC cobalt mining, exposing margins to commodity price volatility. Distribution runs through direct military procurement channels in Israel and the United States, disintermediating traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAV battery market is emerging from a cyclical trough as defense procurement agencies accelerate drone fleet modernization programs, compressing order-to-delivery cycles from 36 to 18 months.
For Market Incumbents: Compound defensive moats by deepening backward integration into silicon-anode manufacturing and securing cleared-facility certifications for ITAR-controlled programs. Solid-state electrolyte R&D investments and direct relationships with military procurement agencies in the United States and Israel offset margin compression from Shenzhen high-volume competitors. For New Entrants and Emerging Players: FAA Part 107 fast-track certification for beyond-visual-line-of-sight battery architectures opens white-space in commercial delivery platforms underserved by defense-qualified incumbents. India's Ministry of Defence procurement programs represent the most penetrable geography, with BIS compliance timelines creating entry barriers that favor early movers establishing Bengaluru assembly partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among defense contractors with multi-year military procurement frameworks and captive silicon-anode supply. Long-term viability favors vertically integrated cell manufacturers with thermal management engineering depth and cleared-facility footprints. Watch FAA certification pathway announcements for autonomous BVLOS operations as the inflection signal unlocking stranded endurance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Defense Qualification Investment | MIL-STD-810G certification opens direct procurement channels with U.S. and Israeli military agencies. |
| Silicon-Anode Manufacturing Scale-Up | Captive production of high-energy-density cells collapses endurance gaps with liquid-fuel propulsion. |
| Fast-Charging Architecture Development | Silicon carbide power electronics paired with lithium titanate anodes target sub-15-minute recharge windows. |
| Indian Market Localization | Bengaluru and Hyderabad assembly clusters reduce qualification timelines for Ministry of Defence programs. |
| Solid-State Electrolyte R&D Partnership | Collaboration with DARPA-funded programs accelerates qualification for 3+ hour loiter missions. |
Methodological Framework
Cross-validation between primary interviews with defense procurement officers and secondary analysis of FAA certification databases anchors the qualitative findings on regulatory acceptance timelines. The research program combined discussions with cell manufacturer R&D directors, military program managers, and commercial fleet operators alongside customs trade records, SEC filings from listed battery suppliers, and EASA airworthiness directive archives. Bottom-up cell shipment estimates and top-down defense budget allocation analysis were triangulated to validate volume assumptions.
Sensitivity analysis on lithium and cobalt price trajectories tested margin resilience across silicon-anode and solid-state production lines. The forecast framework modeled segmentation across battery chemistry, end-use application, capacity tier, and weight class, with CAGRs derived from defense procurement acceleration curves and commercial delivery fleet expansion patterns. Inputs included DOD drone modernization budget disclosures, DJI supplier ecosystem shipment data, and EASA Remote ID compliance timelines.
Decision-makers should treat outputs as directional under sustained defense procurement acceleration and stable raw material supply assumptions; material deviation in Chinese export controls or DRC mining disruptions would warrant model refresh. Forecasts reflect these base conditions without claiming predictive precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Solar-Powered UAV Market
UAV
Europe Tactical UAV Market
UAV
Rc Helicopter Market
UAV
Global Electric Drone Market
UAV
Global Inspection Drones Market
UAV
Commercial Drone-Enabled Services Market
UAV
Drone Motors Market
UAV
Ultra-Long Endurance Drone Market
UAV
Drone Leasing Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Micro Drone Market
UAV
Latin America Small UAV Market
UAV
UAV Drones Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Global Target Drone Market
UAV
Middle-East and Africa Small UAV Market