
 Naval Artillery System Market | 2026-2036
Naval Artillery System Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Artillery System Market Analysis
Gunsmith and systems engineering talent scarcity is reorganizing production timelines across Western shipyards. BAE Systems leverages its British manufacturing heritage to sustain complex naval gun mount programs. Rheinmetall AG anchors European supply through specialized naval ammunition handling lines. Elbit Systems Ltd. competes in fire control integration for smaller surface combatants.
Naval artillery systems encompass shipboard guns, guided projectile launchers, and associated targeting electronics engineered for maritime strike and area denial missions. Modern 127mm and 155mm naval guns achieve ranges exceeding 100 kilometers through precision-guided munitions with GPS-assisted terminal guidance. Gun mount and fire control system categories command the strongest margin pools due to integration complexity and software dependency. Surface vessel platforms dominate procurement volumes, while submarine-launched precision strike configurations represent the fastest-expanding segment as navies pursue undersea standoff capability.
FDA export controls, ITAR frameworks, and national defense acquisition regulations shape cross-border technology transfer and foreign military sales eligibility. The EU AI Act and NATO standardization agreements increasingly govern autonomous targeting and sensor fusion architectures in next-generation naval gun systems. Stakeholders must weigh sovereign content requirements against interoperability mandates when configuring supply chains for multi-national fleet programs.
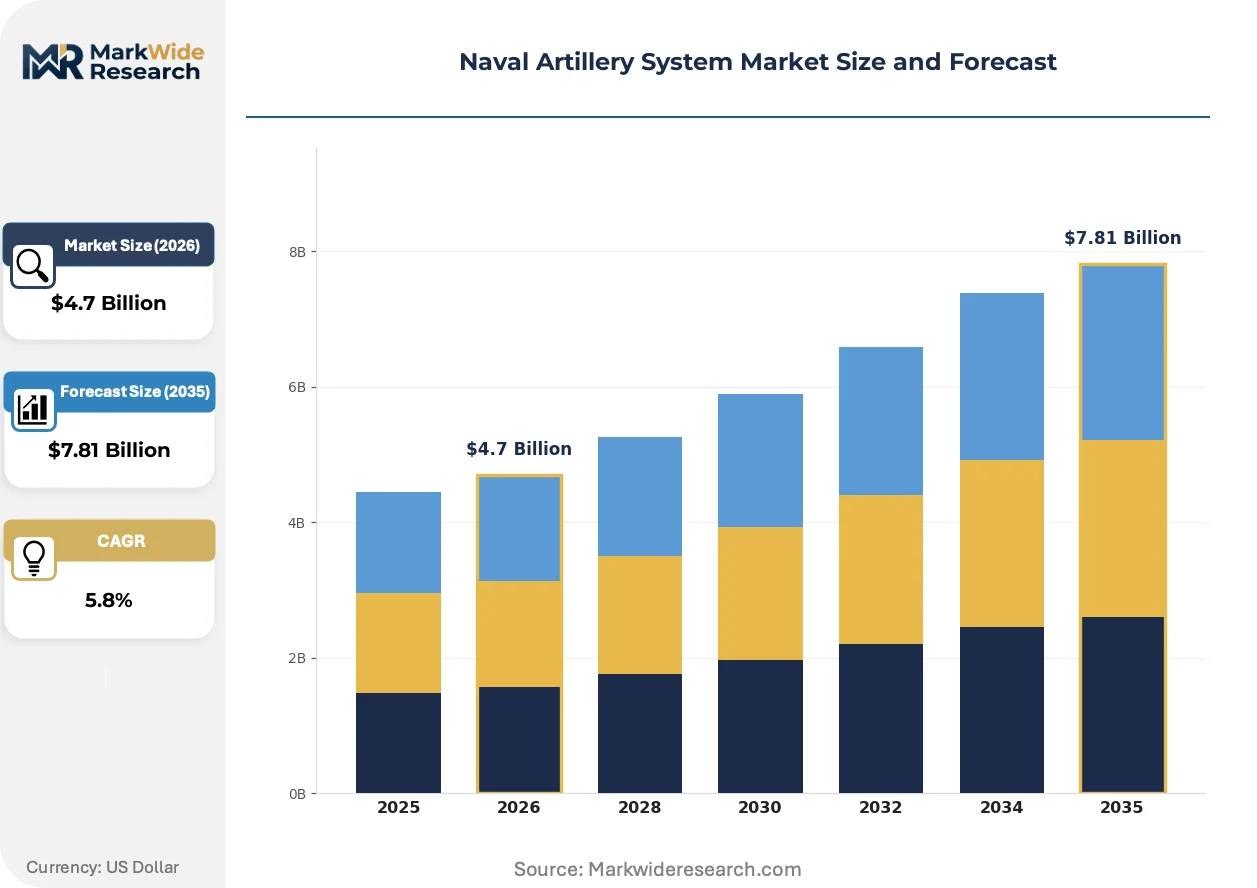
Market Dynamics
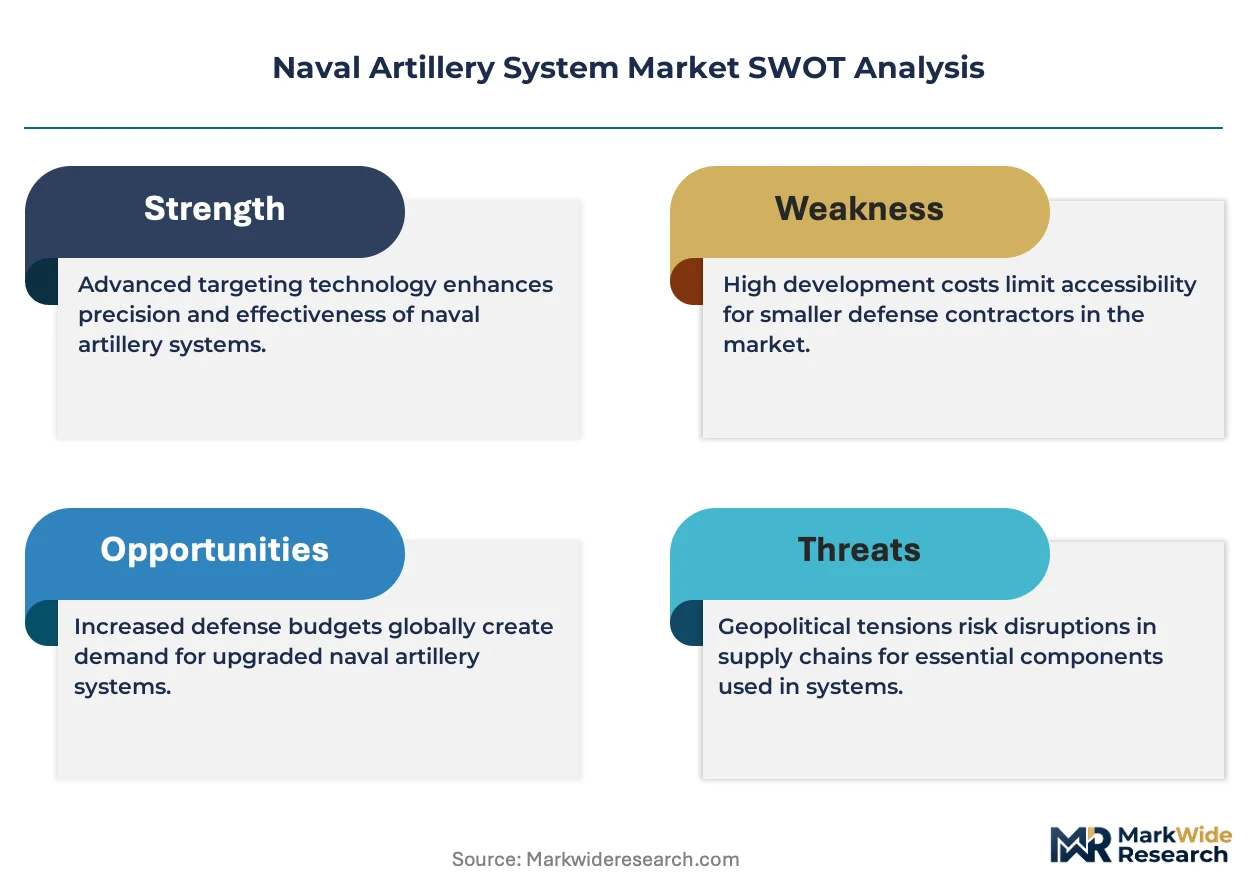
Extended-range precision munitions are compressing the traditional range-performance tradeoff that governed naval gun procurement for decades, forcing integrators to reconfigure fire control architectures around GPS-assisted terminal guidance packages.
Growth Catalysts
- Indo-Pacific Maritime Disputes:Territorial tensions in the South China Sea and East China Sea are accelerating coastal defense investments among littoral navies. Surface combatant modernization programs prioritize shore-strike capability.
- NATO Standardization Mandates:Allied interoperability requirements under STANAG agreements are driving integrated fire control procurement across European fleets. Common ammunition handling standards reduce logistics fragmentation.
- Dual-Use Ammunition Lines:Rheinmetall and BAE Systems are repurposing land artillery manufacturing capacity for naval guided projectile production. Shared tooling lowers unit economics for precision munitions.
Market Restraints
- Tungsten Supply Concentration:Penetrator cores and kinetic energy projectile components depend on Chinese tungsten processing dominance. Export licensing volatility disrupts long-term contracting.
- ITAR Classification Friction:US State Department export controls delay technology transfer for integrated gun mount systems. Foreign military sales eligibility reviews extend delivery timelines by 18-24 months.
- Hypersonic Missile Substitution:Naval strike missions increasingly migrate to hypersonic cruise missiles for targets beyond 300 kilometers. Gun systems face mission overlap in the 100-200 kilometer band.
Strategic Opportunities
- Submarine-Launched Configurations:Undersea standoff strike represents the fastest-expanding platform segment. Virginia-class and Astute-class follow-on programs specify vertical payload tube compatibility.
- EU Defense Fund Allocation:The European Defence Fund's 2021-2027 envelope prioritizes maritime domain awareness and strike systems. Collaborative procurement mechanisms reduce national budget fragmentation.
- AI-Assisted Targeting Convergence:Sensor fusion algorithms and automated threat prioritization are merging with legacy fire control hardware. Retrofit kits open upgrade revenue streams in aging Oliver Hazard Perry and Krivak-class hulls.
Industry Challenges
- Gunsmith Talent Scarcity:Complex naval gun mount engineering requires specialized metallurgical and ballistics expertise. Western shipyards compete for a shrinking pool of qualified systems integrators.
- Legacy Fire Control Integration:New guided munitions must interface with 1980s-era analog computing architectures aboard many active frigates. Middleware development consumes disproportionate program resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Artillery System Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Gun Mounts, Missile Systems, Fire Control Systems, Ammunition Handling Systems Platform: Surface Vessels, Submarines, Coast Guard, Naval Bases End User: Naval Forces, Defense Contractors, Government Agencies, Foreign Military Sales Payload Capacity: Lightweight, Medium, Heavy, Ultra-Heavy |
| Companies Covered | BAE Systems, Lockheed Martin Corporation, General Dynamics Corporation, Rheinmetall AG, Nexter Group, Elbit Systems Ltd., Mandus Group, Northrop Grumman Corporation, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Artillery System Market Emerging Trajectories
Precision-guided projectile technology is collapsing the historical separation between naval guns and missile systems, creating hybrid strike architectures that challenge traditional platform classification and procurement categories.
Ramjet-assisted 155mm shells are supplanting rocket-boosted alternatives in next-generation naval gun programs. The US Navy's Advanced Gun System and comparable European efforts favor air-breathing propulsion for sustained supersonic flight. This propulsion choice is compressing the cost-per-shot gap with tactical missiles while preserving magazine depth advantages.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on autonomous targeting systems. Naval fire control software incorporating machine learning for threat prioritization must now document decision pathways. European integrators are responding by segregating AI-enabled and conventional targeting modes within the same mount architecture.
Fleet operators are consolidating maintenance contracts under original equipment manufacturers rather than national arsenals. BAE Systems and Rheinmetall are capturing multi-decade through-life support agreements that bundle ammunition supply, mount overhaul, and fire control software updates. This pattern is most pronounced in NATO's northern tier, where Denmark, Norway, and Poland have adopted unified support frameworks for their new frigate classes.
Naval Artillery System Market Segmentation
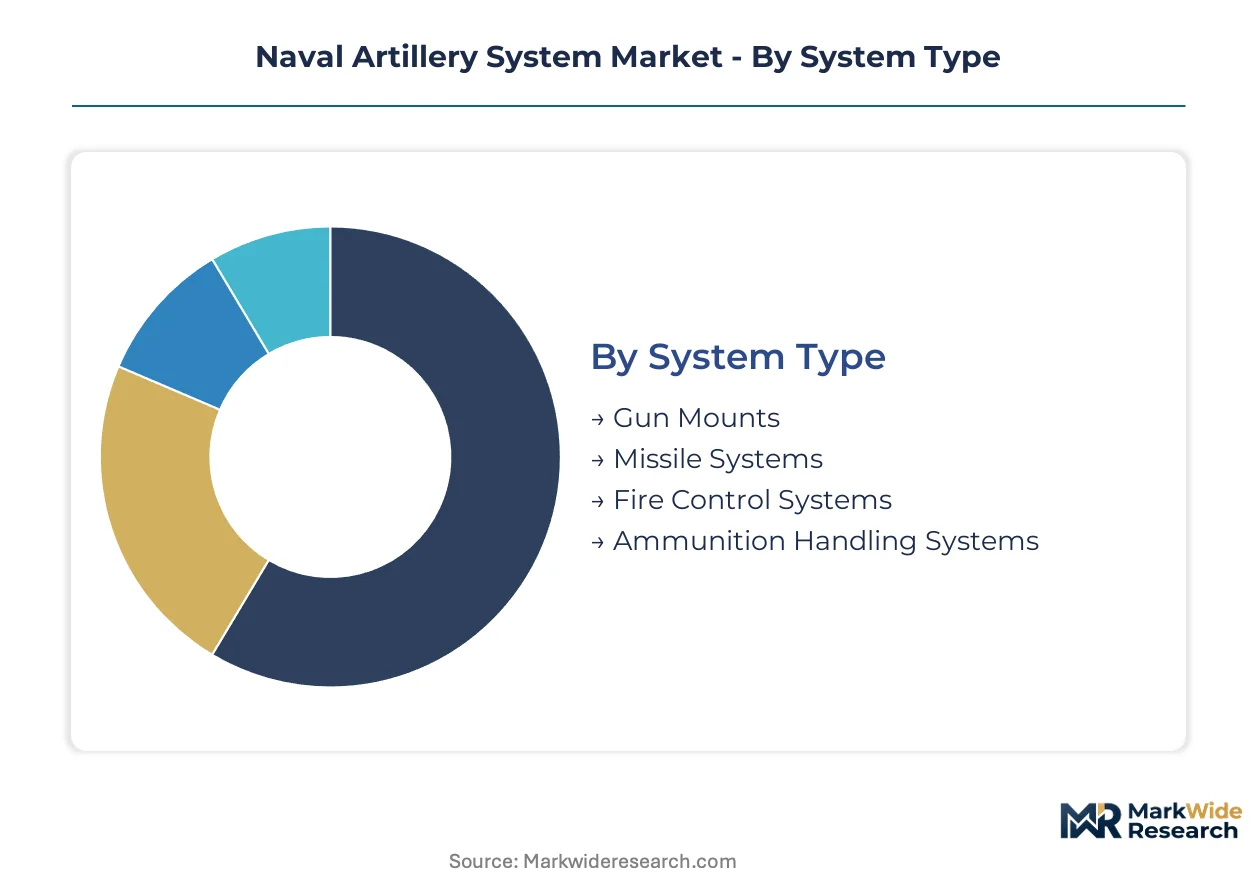
Segmentation in naval artillery systems reveals how procurement priorities diverge between legacy fleet sustainment and next-generation strike architectures. Each dimension—system type, platform, end user, and payload capacity—maps to distinct contracting channels, technical specifications, and sovereign content requirements that shape vendor selection and pricing.
System Type:
Gun mounts and fire control systems concentrate in domestic European and North American procurement, while ammunition handling systems and missile systems flow more heavily through foreign military sales channels to Indo-Pacific navies.
- Gun Mounts:Stabilized naval gun mounts integrate recoil absorption, elevation drives, and ammunition feed mechanisms rated for sustained firing cycles. Demand clusters in US and British surface combatant modernization programs, where STANAG 4425 compatibility mandates drive integrated procurement.
- Fire Control Systems:Sensor fusion architectures combining radar, electro-optical tracking, and ballistic computers enable precision engagement against moving maritime targets. German and French naval electronics integrators dominate this segment through NATO interoperability requirements.
- Missile Systems:Vertical launch and canister-based naval strike systems extend range envelopes beyond conventional gun artillery.
- Ammunition Handling Systems:Automated magazine and feed mechanisms optimize crew safety and firing rates aboard compact hulls.
Gun mounts command the established base. The steepest expansion runs through fire control systems.
Platform:
Platform segmentation separates high-volume surface vessel programs from specialized submarine configurations, with coast guard and naval base applications occupying distinct budgetary and operational lanes.
- Surface Vessels:Frigates and destroyers host the majority of installed naval artillery capacity, with 127mm and 155mm gun systems standard on major combatants. Japanese and Australian fleet expansion programs concentrate demand in this segment.
- Submarines:Vertical payload tube compatibility for precision strike munitions is specified in Virginia-class and Astute-class follow-on programs. Undersea launch architectures require pressure-resistant canister designs and specialized fire control interfaces.
- Coast Guard:Patrol cutters and offshore vessels prioritize lightweight, manually operated gun systems for law enforcement and interdiction missions.
- Naval Bases:Fixed coastal defense batteries protect strategic harbors and chokepoints with shore-based gun and missile emplacements.
Surface vessels anchor current procurement volumes. Submarines are gaining share fastest through undersea standoff strike requirements.
End User:
End user segmentation distinguishes sovereign naval procurement from contractor-led integration and foreign military sales channels, each with distinct contracting timelines and technology transfer restrictions.
- Naval Forces:National navies specify integrated weapon systems through defense ministry acquisition offices, with British, American, and Japanese surface fleets driving program scale.
- Defense Contractors:Prime integrators procure subsystem components for incorporation into platform-level contracts, creating tiered supply relationships with gun mount and fire control specialists.
- Government Agencies:Coast guard and maritime security organizations acquire lighter systems through civilian procurement frameworks.
- Foreign Military Sales:US State Department-administered FMS channels deliver standardized configurations to allied navies, with ITAR classification extending delivery timelines.
Naval forces retain the dominant share. Foreign military sales are climbing the fastest as Indo-Pacific allies accelerate fleet modernization.
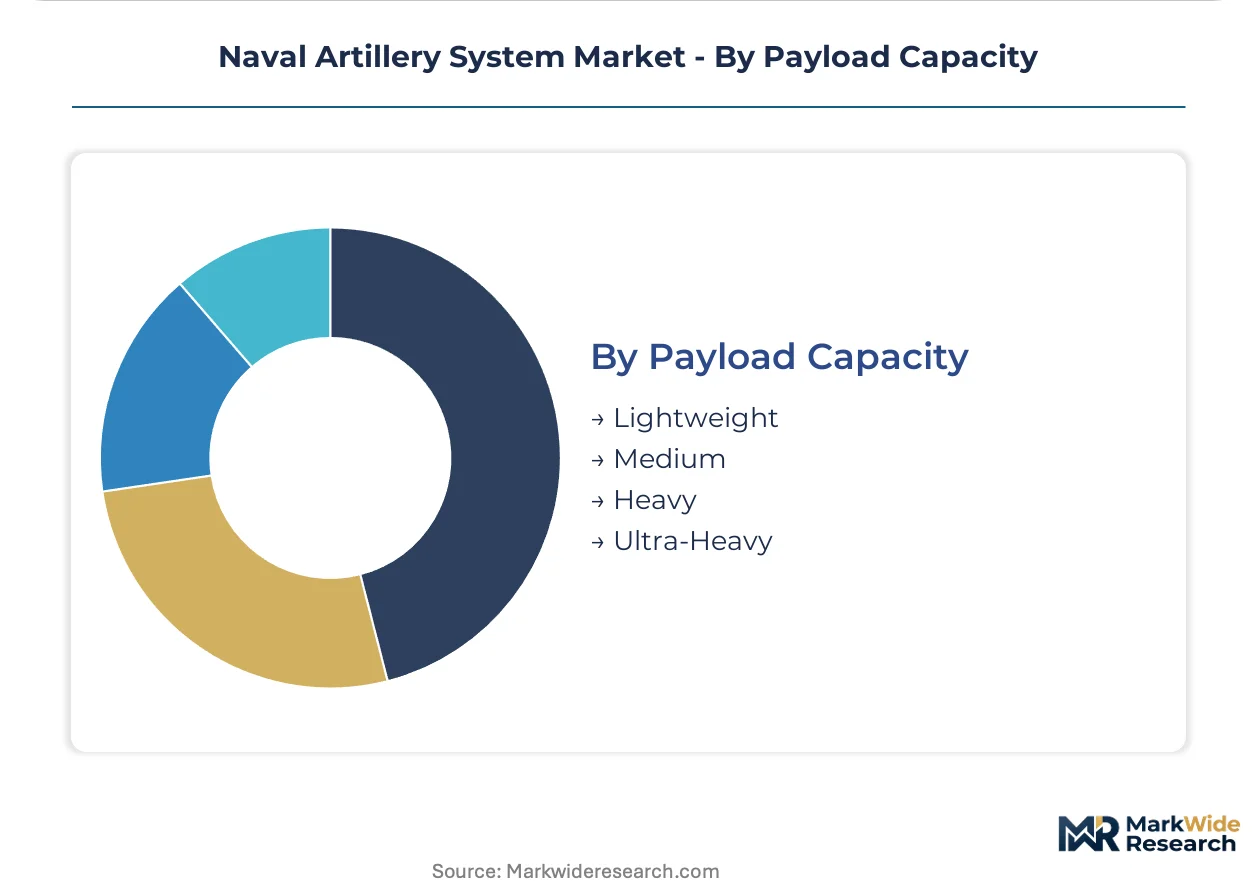
Payload Capacity:
Payload segmentation aligns with mission profiles ranging from patrol craft self-defense to battleship-caliber shore bombardment, with weight classes determining mount stabilization requirements and ammunition logistics.
- Medium:76mm to 127mm gun systems balance rate of fire and destructive effect for general-purpose frigates. Italian and Dutch shipyards specify this class for their latest multipurpose combatant designs.
- Heavy:155mm naval guns and extended-range guided projectiles achieve ranges exceeding 100 kilometers through precision guidance. US and British next-generation destroyer programs concentrate investment here.
- Lightweight:20mm to 57mm autocannons serve patrol and interception missions aboard compact hulls.
- Ultra-Heavy:Experimental railgun and advanced gun system prototypes push projectile energies beyond conventional chemical propulsion limits.
Medium payloads dominate active fleet composition. Heavy systems are expanding most quickly through precision-guided munition integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US State Department ITAR frameworks govern technology transfer eligibility for integrated naval gun systems, extending foreign military sales timelines by 18-24 months and reshaping procurement patterns across allied fleets.
United States
Virginia-class and Columbia-class submarine programs specify vertical payload tube compatibility for precision strike munitions, driving undersea launch architecture demand. The Navy's Advanced Gun System program anchors surface combatant modernization. Industrial concentration centers on Washington and Virginia shipyards, where BAE Systems and General Dynamics sustain complex mount production lines.
Germany
Rheinmetall AG operates specialized naval ammunition handling lines repurposed from land artillery capacity, lowering guided projectile unit economics. NATO STANAG standardization mandates under the EU Defence Fund drive integrated fire control procurement across European fleets. The Kiel and Hamburg maritime clusters host subsystem integration facilities serving Danish, Norwegian, and Polish frigate programs.
United Kingdom
British manufacturing heritage sustains complex naval gun mount programs for Type 26 and Type 31 frigate classes. Ministry of Defence acquisition offices specify sovereign content requirements against interoperability mandates. The Glasgow and Portsmouth shipyard regions concentrate gunsmith talent scarce across Western defense industries.
Japan
Maritime Self-Defense Force fleet expansion prioritizes 127mm naval gun systems for multipurpose destroyer programs amid East China Sea territorial tensions. METI industrial policy coordinates precision-guided munition development with domestic heavy industry. The Nagasaki and Yokohama shipbuilding regions integrate fire control architectures for Mogami-class frigates.
Australia
Hunter-class frigate procurement under the SEA 5000 program imports gun mount and fire control systems through AUKUS technology sharing frameworks. The Royal Australian Navy's surface fleet modernization concentrates shore-strike capability requirements. South Australian shipyard infrastructure at Osborne supports through-life support agreements bundling ammunition supply and software updates.
Naval Artillery System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in naval artillery contracting. Prime integrators capture multi-decade through-life support agreements that bundle ammunition supply, mount overhaul, and fire control software updates. Three archetypes dominate: legacy shipyard-affiliated manufacturers with captive naval programs, independent subsystem specialists focused on fire control and guided munitions, and diversified defense conglomerates leveraging land artillery crossover. Consolidation pressure runs through capacity expansion in precision-guided projectile lines and strategic partnerships for submarine-launched configuration development.
Within the integrated systems tier, BAE Systems and Rheinmetall AG anchor European supply chains through British and German manufacturing heritage respectively. Elbit Systems Ltd. occupies a specialist position in fire control integration for compact surface combatants. These three exemplify divergent strategic postures: shipyard-captive production versus independent subsystem export versus niche electronics focus.
| Leading Market Players |
|---|
| BAE Systems |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Rheinmetall AG |
| Nexter Group |
| Elbit Systems Ltd. |
| Mandus Group |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Multi-decade through-life support agreements bundle ammunition supply, mount overhaul, and fire control software updates into single-contract structures that lock in price visibility for NATO navies while guaranteeing supply access for integrators. BAE Systems and Rheinmetall capture these arrangements across Danish, Norwegian, and Polish frigate programs, compressing procurement friction and stabilizing margin pools against raw material volatility.
Pricing Analysis
Long-term offtake contracts dominate naval artillery procurement, with sovereign navies committing to decade-spanning ammunition supply and maintenance schedules. Price differentiation rests on STANAG certification tier and sovereign content thresholds, with NATO-compliant systems commanding premiums over export-configured alternatives. Cost compression in guided projectile lines is intensifying because Rheinmetall and BAE Systems repurpose shared land artillery tooling for naval production. Foreign military sales channels show highest price sensitivity due to ITAR-driven delivery timeline extensions, while domestic European procurement demonstrates lowest sensitivity through sovereign capability mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites tungsten concentrate flows from Chinese processing dominance to European penetrator core manufacturers. Naval artillery supply chains draw from German precision engineering clusters, British gunsmith heritage regions, and Japanese heavy industrial bases. Dependencies center on tungsten for kinetic energy projectiles, specialized steel alloys for gun barrels, and gallium arsenide for fire control sensor arrays. Single-source vulnerability concentrates in Chinese rare earth processing. Distribution runs through prime integrator-led subsystem contracting rather than direct national arsenal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Naval artillery sits in early-cycle expansion as undersea standoff strike architectures penetrate Virginia-class and Astute-class follow-on programs. Submarine-launched precision configurations represent the fastest-advancing platform segment, creating white-space for specialized canister and fire control developers.
For Market Incumbents: Consolidate gunsmith talent pools through captive apprenticeship pipelines in Glasgow and Portsmouth shipyard regions, defending against scarcity-driven cost escalation. Backward integration into tungsten alloy processing mitigates Chinese supply concentration risk. Capacity reservation agreements with Australian and Japanese fleet expansion programs secure volume visibility through AUKUS and bilateral frameworks. For New Entrants and Emerging Players: Anchor in submarine-launched configuration development, the most penetrable segment given Virginia-class and Astute-class payload tube specifications. Fire control middleware for 1980s-era analog architectures aboard active Oliver Hazard Perry and Krivak-class hulls offers second white-space target. Go-to-market through retrofit kit partnerships with national maintenance depots bypasses prime integrator capture. For Investors and Strategic Acquirers: Capital is best deployed toward fire control software specialists with NATO STANAG certification and AI-assisted targeting capabilities, positioned for retrofit upgrade cycles and next-generation integrated architectures. Long-term viability hinges on through-life support contract capture rather than discrete system sales. Watch submarine vertical payload tube specification rates across US and British programs as inflection indicator for canister demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Guided Projectile Manufacturing Scale-Up | Rheinmetall's repurposed land artillery lines lower unit economics for precision naval munitions. |
| Submarine Launch Architecture Development | Pressure-resistant canister designs for Virginia-class payload tubes open fastest-expanding platform segment. |
| AI-Assisted Targeting Retrofit Kits | Sensor fusion algorithms merge with legacy fire control hardware aboard aging Oliver Hazard Perry hulls. |
| Multi-Decade Through-Life Support Agreements | BAE Systems bundles ammunition supply and software updates across Danish and Norwegian frigate programs. |
| Tungsten Supply Chain Backward Integration | Captive alloy processing mitigates Chinese concentrate dominance for penetrator core production. |
Methodological Framework
A spread of perspectives from naval program executives at defense ministries, shipyard integration engineers, fire control software architects, and precision munition procurement officers converged on the working assumptions underlying this analysis. Secondary validation drew from NATO STANAG documentation, EU Defence Fund allocation disclosures, US State Department FMS licensing records, and Japanese METI industrial policy filings. Bottom-up segment sizing triangulated against top-down fleet modernization budget aggregates.
Segmentation dimensions modeled span system type, platform category, end-user procurement channel, and payload capacity class across the analysis window. CAGRs were derived from installed base replacement cycles, precision-guided munition penetration curves, and submarine launch architecture adoption rates. Forecast inputs incorporated ITAR licensing timeline distributions, EU AI Act algorithmic transparency compliance costs, and tungsten export licensing volatility scenarios.
Decision-makers should treat outputs as directional under sustained Indo-Pacific maritime tension and NATO standardization mandate assumptions; material deviation in hypersonic missile substitution rates or Chinese rare earth export restrictions would warrant model refresh. Practitioners should keep alternative scenarios live as EU Defence Fund allocation priorities and AUKUS technology sharing frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Radar Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Fast Attack Craft (FAC) Market