
 Release Film for OCA Market | 2026-2036
Release Film for OCA Market Size, Share, and Industry Trends Forecast 2026-2036
Release Film for OCA Market Insights
The capital-intensity divergence between integrated petrochemical players and specialty film converters is reorganizing competitive tiers in release film supply. Mitsubishi Chemical leverages captive polyester resin production to anchor its position across high-clarity grades. SKC sustains Korean domestic demand through backward integration into base film extrusion. Nitto Denko Corporation differentiates via proprietary silicone coating chemistry that commands premium positioning in optical-grade applications.
Release film for OCA denotes a thin, dimensionally stable carrier substrate coated with precisely controlled release agents, enabling clean separation from optically clear adhesive after lamination to display stacks. Base films typically employ polyethylene terephthalate or polyimide structures with surface energies calibrated between 30-40 dynes per centimeter to ensure predictable peel behavior without adhesive residue transfer. Polymeric and silicone product types dominate current volume, though silicone-coated variants capture disproportionate margin pools due to tighter release-force tolerances required for foldable display modules. The electronics industry vertical absorbs the majority of output, while automotive-grade specifications for curved infotainment screens represent the fastest-expanding demand pocket.
REACH registration requirements in Europe and EPA oversight of silicone volatile organic compound emissions in the United States constrain formulation choices and regional supply qualifications. Japan's METI enforces JIS standards for optical film dimensional stability that effectively gate market access for imported release liners. South Korea's MFDS and Taiwan's national standards body impose parallel traceability protocols for materials contacting consumer-facing displays. Stakeholders must monitor regulatory divergence between Asian manufacturing hubs and Western end-markets when siting coating capacity and qualifying alternative release chemistries.
Market Dynamics
Foldable display penetration is forcing silicone-coated release film specifications toward tighter release-force tolerances, compressing qualification cycles and favoring coating specialists with captive resin control.
Growth Catalysts
- Foldable smartphone lamination:Samsung Display and BOE Technology are scaling tri-fold panel production, requiring ultra-low release-force films that prevent adhesive deformation during delamination.
- REACH SVHC screening:ECHA's expanding candidate list is accelerating substitution of fluorinated release agents with silicone alternatives qualified for European electronics supply chains.
- Taiwanese OCA tape clustering:Taichung Science Park hosts concentrated precision coating capacity, generating localized demand for dimensional-stable PET substrates.
Market Restraints
- Silicone monomer volatility:D4 and D5 cyclosiloxane feedstock costs fluctuate with energy-intensive German and Chinese chlorosilane production, squeezing coating margins.
- Korean base film oligopoly:SKC and Kolon Industries control over 60% of regional PET film extrusion, creating supply security risks for downstream converters.
- Dimensional stability ceiling:Conventional PET structures face thermal expansion limits above 150°C, constraining their use in high-temperature automotive curing processes.
Strategic Opportunities
- Indian display assembly:Vedanta-Foxconn and Tata Electronics are building smartphone lamination lines in Gujarat and Karnataka, creating first-mover qualification windows for release film suppliers.
- Automotive curved infotainment:Tier-1 integrators including Bosch and Continental are specifying optical-grade release liners for free-form display bonding in premium vehicle cabins.
- EU Green Deal alignment:CSRD reporting requirements are pressuring electronics OEMs to document Scope 3 emissions, favoring suppliers with verified recycled-content substrate programs.
Industry Challenges
- Cleanroom coating technician scarcity:Precision silicone deposition requires Class 1000 environment expertise concentrated in Japanese and Korean engineering workforces, limiting greenfield facility staffing.
- Dual certification timelines:Simultaneous MFDS traceability and JIS dimensional stability qualification extends product approval cycles to 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Release Film for OCA Market |
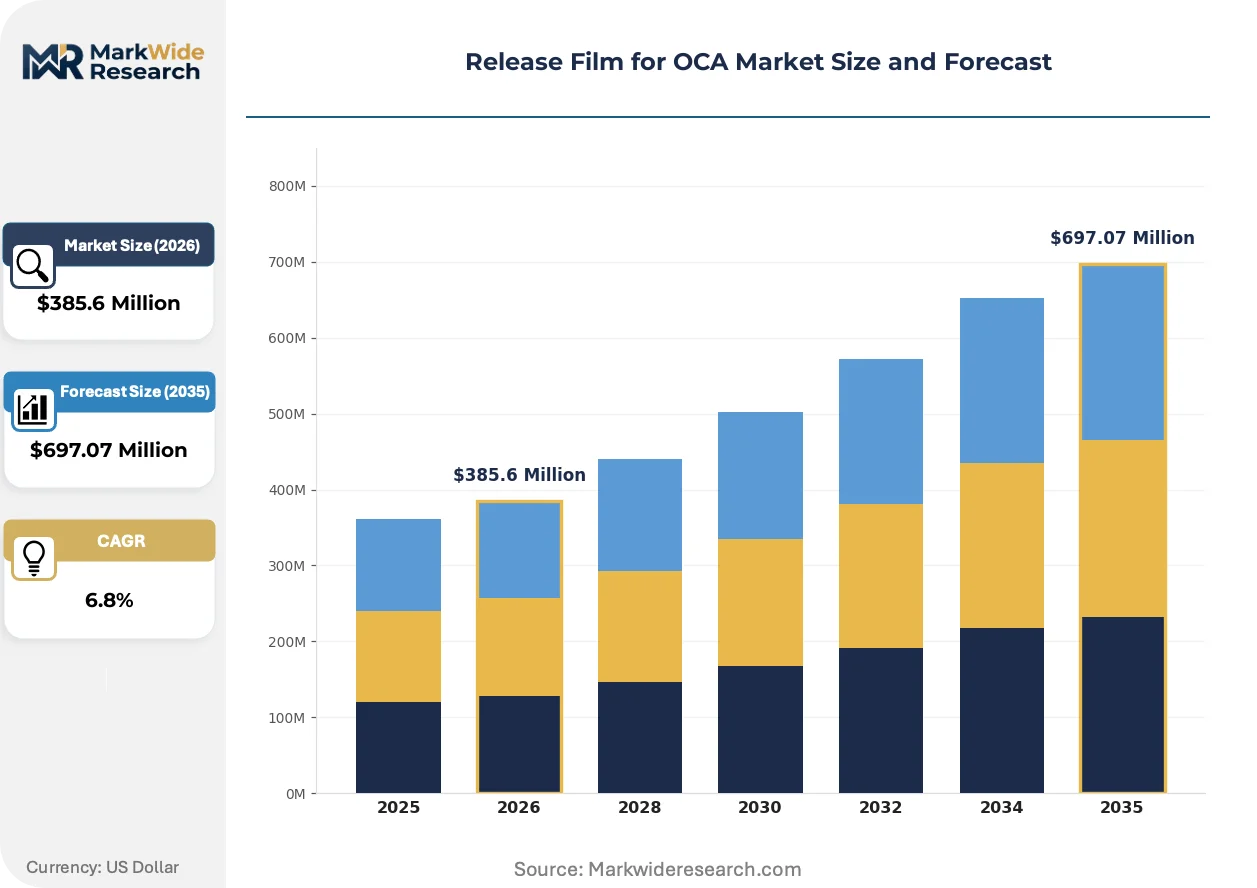
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Polyester, Acrylic, Silicone Formulation: Adhesive-Free, Dual-Sided, Coated, Laminated Industry Vertical: Electronics, Automotive, Aerospace, Packaging End User: Manufacturers, Assemblers, Distributors, Retailers |
| Companies Covered | Taiwan Nippa, Mitsubishi Chemical, SKC, Kiseung Inc, Zacros, Youl Chon, Nanya Plastics, Nitto Denko Corporation, Great Rich Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Release Film for OCA Market Trends and Innovations
Silicone chemistry advancement and procurement centralization are restructuring how release specifications propagate from adhesive formulators to substrate suppliers.
Fluorosilicone hybrid coatings is bifurcating the performance tier structure for foldable applications. Samsung Display and Huawei's device divisions are specifying these formulations for ultra-low surface energy requirements below 25 dynes per centimeter. The technology is bifurcating margin pools between premium foldable-grade suppliers and commodity smartphone-lamination providers.
EPA silicone VOC emission guidelines are constraining solvent-based coating processes in North American manufacturing. Formulators are accelerating waterborne silicone emulsion development, though cure speed penalties persist. Automotive display laminators in Michigan and California are qualifying Asian-imported pre-coated films to bypass domestic emission compliance costs.
Consolidated procurement through display panel OEMs is displacing distributor-centric purchasing for high-volume smartphone programs. BOE, Tianma, and Visionox are mandating direct supplier relationships with documented batch traceability. The shift is most visible in South Korea, where Samsung Display's vendor reduction programs have halved qualified release film sources since 2022.
Release Film for OCA Market Segmentation
Release film specifications diverge sharply across downstream applications, with material chemistry and coating architecture determining qualification access to high-margin display lamination programs. Understanding segment-level technical requirements illuminates why certain substrate-coating combinations command premium positioning while others face commoditization pressure.
Product Type:
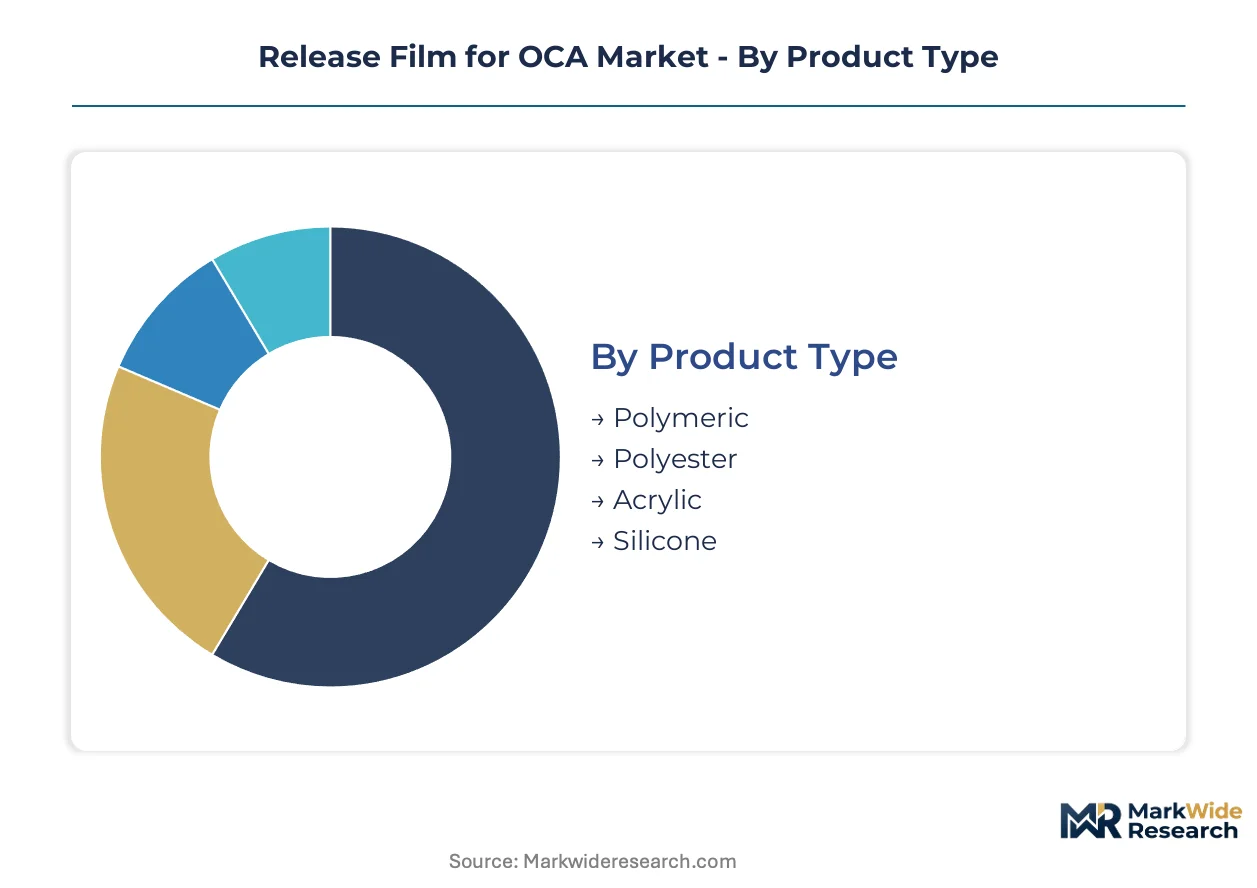
Silicone-coated variants capture disproportionate margin pools due to tighter release-force tolerances required for foldable display modules, while polymeric alternatives compete on cost in high-volume smartphone programs.
- Silicone:Fluorosilicone hybrid formulations achieve surface energy below 25 dynes per centimeter, qualifying for Samsung Display and Huawei tri-fold panel specifications where ultra-low release force prevents adhesive deformation during delamination.
- Polymeric:Standard silicone-polymer blends dominate mid-tier smartphone lamination, with release forces calibrated between 30-40 dynes per centimeter for predictable peel behavior without residue transfer in high-speed assembly lines.
- Polyester:PET-based structures provide dimensional stability for optical-grade applications, though thermal expansion limits above 150°C constrain automotive curing process adoption.
- Acrylic:Waterborne emulsion variants are emerging as EPA-compliant alternatives to solvent-based silicone coatings, despite cure speed penalties affecting throughput in North American manufacturing.
The dominant share belongs to Silicone, while Acrylic is closing the gap fastest as regulatory pressure accelerates formulation substitution.
Formulation:
Coating architecture complexity directly correlates with qualification barriers and pricing power, with multi-layer structures commanding substantial premiums over single-sided alternatives.
- Coated:Precision silicone deposition in Class 1000 cleanroom environments enables the tightest release-force tolerances, with proprietary chemistry from Japanese and Korean specialists differentiating premium supply tiers.
- Dual-Sided:Symmetric release coatings on both substrate faces serve specialized OCA tape constructions where adhesive layers require protection during slitting and rewinding operations.
- Laminated:Multi-ply structures combining PET base films with functional interlayers address dimensional stability requirements for large-format automotive infotainment bonding.
- Adhesive-Free:Virgin substrate surfaces with controlled surface energy suit low-tack applications where minimal contamination risk outweighs release precision needs.
Coated formulations hold the largest volume position, though Dual-Sided is expanding most quickly as OCA tape complexity increases.
Industry Vertical:
Electronics manufacturing concentrates demand for optical-grade specifications, while automotive applications impose the steepest technical escalation trajectories for thermal and dimensional performance.
- Electronics:Smartphone display lamination absorbs majority output, with Samsung Display, BOE, and Tianma mandating direct supplier relationships and documented batch traceability that halves qualified release film sources.
- Automotive:Curved infotainment screens specified by Bosch and Continental for premium vehicle cabins require free-form display bonding capabilities that exceed conventional PET thermal limits.
- Aerospace:Avionics display applications demand extended temperature range performance with minimal outgassing, though qualification cycles extend 18-24 months for new market entrants.
- Packaging:General industrial applications tolerate wider release-force tolerances, competing primarily on unit economics rather than optical clarity metrics.
Electronics commands the dominant revenue share, while Automotive is gaining share fastest as display integration accelerates across vehicle cabins.
End User:
Procurement centralization through panel OEMs is restructuring purchasing patterns, with direct manufacturer relationships displacing distributor-centric models for high-volume programs.
- Manufacturers:Integrated petrochemical players like Mitsubishi Chemical and SKC leverage captive resin production to anchor positions across high-clarity grades, controlling substrate supply for downstream converters.
- Assemblers:Display lamination specialists in South Korea and Taiwan generate localized demand for dimensional-stable PET substrates, with Taichung Science Park hosting concentrated precision coating capacity.
- Distributors:Inventory-holding intermediaries face margin compression as consolidated procurement through BOE, Visionox, and Tianma mandates documented supply chain transparency.
- Retailers:Aftermarket and spare parts channels serve repair ecosystem needs with less stringent qualification requirements than OEM supply chains.
Manufacturers retain the largest procurement volume, while Assemblers are climbing the fastest as display panel production regionalizes toward consumption markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes release film primarily for foldable display lamination, whereas Taiwan and Japan emphasize OCA tape export manufacturing and optical-grade substrate precision respectively. This consumption-mix differential shapes regional supply chain configurations and qualification priorities.
South Korea
Samsung Display's tri-fold panel production drives ultra-low release-force specifications for domestic OCA tape converters. MFDS traceability protocols mandate documented batch records for materials contacting consumer-facing displays. Gyeonggi Province hosts concentrated precision coating capacity serving both domestic demand and export markets.
Taiwan
Taichung Science Park clustering generates localized demand for dimensional-stable PET substrates among precision coating specialists. The national standards body enforces parallel traceability protocols aligned with major electronics OEM requirements. Tape manufacturers in central Taiwan supply lamination materials to display panel producers across East Asia.
Japan
METI-enforced JIS standards for optical film dimensional stability effectively gate market access for imported release liners. Domestic formulators emphasize proprietary silicone coating chemistry for premium optical-grade applications. Kansai region engineering workforces concentrate Class 1000 cleanroom expertise.
China
BOE Technology and Tianma scale display lamination lines requiring direct supplier relationships with documented supply chain transparency. MIIT oversees GB standards compliance for optical materials in consumer electronics manufacturing. Yangtze River Delta clusters absorb volume for both domestic smartphone assembly and export-oriented OCA tape production.
United States
EPA oversight of silicone volatile organic compound emissions constrains formulation choices for domestic coating operations. Automotive display laminators in Michigan and California qualify Asian-imported pre-coated films to bypass compliance costs. Midwest and West Coast electronics assembly operations source qualified materials through consolidated procurement channels.
Release Film for OCA Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in release film supply. Integrated petrochemical players leverage captive resin production to anchor positions across high-clarity grades, while coating specialists differentiate via proprietary silicone chemistry and cleanroom deposition capabilities. Strategic archetypes include backward-integrated substrate producers, formulation-focused coating houses, and precision tape converters with captive film sourcing. Dominant competitive moves encompass geographic expansion toward emerging display assembly hubs and portfolio diversification into automotive-grade specifications.
Among East Asian material suppliers, Mitsubishi Chemical, SKC, and Nitto Denko Corporation occupy positions spanning the integrated-to-specialist spectrum. Mitsubishi Chemical represents the petrochemical-integrated archetype with upstream control over polyester resin supply. SKC exemplifies regional base film production concentration with captive extrusion capabilities. Nitto Denko Corporation sits within the premium coating specialist tier, its market presence signaling the value commanded by proprietary release chemistry in optical-grade applications.
| Leading Market Players |
|---|
| Taiwan Nippa |
| Mitsubishi Chemical |
| SKC |
| Kiseung Inc |
| Zacros |
| Youl Chon |
| Nanya Plastics |
| Nitto Denko Corporation |
| Great Rich Technology |
| Others |
Pricing and Supply Chain Analysis
Fluorosilicone hybrid coating substitution for conventional silicone formulations is simultaneously shifting production geography toward Japanese and Korean specialty chemical houses and compressing margin pools for commodity-grade converters unable to access proprietary resin chemistry. This input transition concentrates pricing power among coating specialists with captive silicone monomer supply while forcing downstream assemblers to absorb qualification premiums for foldable-grade specifications.
Pricing Analysis
After-sales technical service contracts and formulation customization fees drive lifetime value beyond base film transactions. Three-tier pricing structure across premium, standard, and economy levels reflects release-force tolerance bands and cleanroom certification grades. Pricing pressure stems from Korean base film oligopoly concentration, squeezing converter margins. High-volume smartphone assemblers exhibit acute price sensitivity, whereas automotive display laminators prioritize dimensional stability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Busan and Kaohsiung ports constrain just-in-time delivery windows for European and North American display laminators. Supply concentrates in South Korea, Japan, and Taiwan, with raw material dependencies on D4/D5 cyclosiloxane feedstock and PET resin from German and Chinese chlorosilane production. Single-source vulnerability pervades silicone monomer supply given energy-intensive production concentration. Distribution runs through direct manufacturer relationships mandated by BOE, Samsung Display, and Tianma procurement centralization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Release film supply is increasingly a service-attach opportunity where formulation customization and joint qualification programs expand faster than commodity substrate volumes. Technical service contracts and collaborative R&D agreements with display panel OEMs now generate recurring revenue streams that outpace hardware-only growth trajectories.
For Market Incumbents: Compound defensive positioning through backward integration into silicone resin production and captive base film extrusion capacity. Korean and Japanese specialists face emerging threat from Chinese coating houses scaling fluorosilicone capabilities. Prioritize certification investment in MFDS traceability and JIS dimensional stability to extend qualification moats. For New Entrants and Emerging Players: Technical service gaps in Indian display assembly operations present accessible entry points where Vedanta-Foxconn and Tata Electronics lack established supplier relationships. Gujarat and Karnataka lamination lines offer the most penetrable geography. Pursue direct qualification partnerships with emerging panel producers rather than distributor channels. For Investors and Strategic Acquirers: Capital is best deployed toward coating specialists with proprietary silicone chemistry and established cleanroom infrastructure. Long-term viability hinges on automotive-grade specification diversification beyond smartphone saturation. Watch foldable display penetration rates as the primary inflection signal for premium release film demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Resin | Mitsubishi Chemical and SKC anchor margin control through captive monomer supply. |
| Automotive-Grade Specification Development | Bosch and Continental sourcing requirements exceed conventional PET thermal limits. |
| Indian Manufacturing Footprint Establishment | Vedanta-Foxconn Gujarat operations create first-mover qualification windows. |
| Fluorosilicone Hybrid Formulation R&D | Samsung Display tri-fold specifications demand surface energy below 25 dynes. |
| Waterborne Coating Process Transition | EPA VOC compliance pressures accelerate solvent-free technology substitution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating line engineers, OCA tape procurement managers, display panel quality directors, silicone formulator R&D leads, and automotive Tier 1 bonding specialists. Secondary validation drew from customs trade databases, SEC filings of listed petrochemical groups, ECHA REACH registration records, and JIS optical film standards documentation. Bottom-up volume estimates triangulated against top-down value projections derived from substrate resin pricing indices.
Across the analysis window, forecasts employed a segmented growth model disaggregated by coating chemistry type, formulation architecture, end-use vertical, and regional manufacturing cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating foldable display adoption curves and automotive display integration rates. Silicone monomer cost volatility and regulatory qualification timelines served as key sensitivity inputs.
Underlying assumptions cover stable Korean-Taiwanese supply chain continuity and REACH-compliant formulation substitution timelines, with deviation risk concentrated in Chinese chlorosilane production disruptions and EPA emission guideline enforcement intensity. Recalibration cycles align with material shifts in foldable panel commercialization and Indian display assembly ramp schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
MDO Films Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Thermoformed Tubs Market