
 Gift Wrapping Product Market | 2026-2036
Gift Wrapping Product Market Size, Share, and Industry Trends Forecast 2026-2036
Gift Wrapping Product Market Analysis
A capital-intensity divergence between automated packaging lines and artisanal craft production is reorganizing competitive tiers. DS Smith leverages integrated paper recycling and corrugation infrastructure across European markets. Hallmark Cards anchors premium seasonal collections through controlled retail shelf space and licensed character portfolios. Shenzhen Fuxiang Gifts & Packaging Co. Ltd. competes on volume flexibility for private-label e-commerce clients.
Gift wrapping products encompass decorative materials engineered for aesthetic presentation and protective containment of consumer goods, typically specified by basis weight for paper stocks, tensile strength for ribbons, and barrier properties for foil laminates. Their commercial purpose centers on enhancing perceived value, enabling brand communication at point of unboxing, and supporting retail differentiation. Wrapping paper and gift bags command the largest revenue pools, while decorative tape represents the fastest-expanding segment as social media unboxing content amplifies demand for distinctive finishing details. Fabric-based wrapping sustains premium positioning through reusability claims, though paper and plastic materials dominate unit economics across mass retail and e-commerce channels.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability thresholds, redirecting R&D investment toward fiber-based substrates and water-based inks. The US EPA guides state-level packaging waste policies, while China's GB standards govern food-contact safety for gift packaging with incidental product contact. REACH compliance in Europe and evolving state legislation in California and New York shape material substitution timelines. Stakeholders must monitor regulatory fragmentation between jurisdictions and decide whether to standardize formulations globally or manage regional SKUs.
Market Dynamics
E-commerce unboxing content is fragmenting demand into micro-batches of hyper-customized wrapping formats, forcing manufacturers to retool for shorter production runs without sacrificing unit economics.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating fiber-based substrate R&D, creating first-mover advantages for compliant suppliers.
- Shenzhen manufacturing cluster:Concentrated die-cutting and foil-stamping capacity enables 48-hour turnaround for private-label e-commerce orders.
- Water-based ink chemistry:Advances in barrier coatings eliminate plastic lamination requirements while preserving print fidelity for premium seasonal collections.
Market Restraints
- Pulp input volatility:Softwood fiber costs fluctuate with Nordic supply disruptions, compressing margin on standard-grade wrapping paper.
- Single-source foil dependency:Metallized PET film production concentrates in Chinese provinces vulnerable to energy rationing.
- REACH compliance timelines:Substance authorization delays extend reformulation cycles for European market entry.
Strategic Opportunities
- India retail modernization:Organized brick-and-mortar expansion creates shelf-space competition for branded gift bag portfolios.
- Reusable fabric wrapping:Furoshiki-inspired formats penetrate premium gifting segments through sustainability positioning.
- Social commerce integration:TikTok Shop and Instagram Checkout enable direct-to-consumer decorative tape bundles.
Industry Challenges
- Short-run tooling costs:Digital die-cutting equipment requires capital outlay that mid-tier converters struggle to justify.
- Cross-border labeling variance:Recycling symbol requirements differ between California's SB 343 and EU harmonized standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gift Wrapping Product Market |
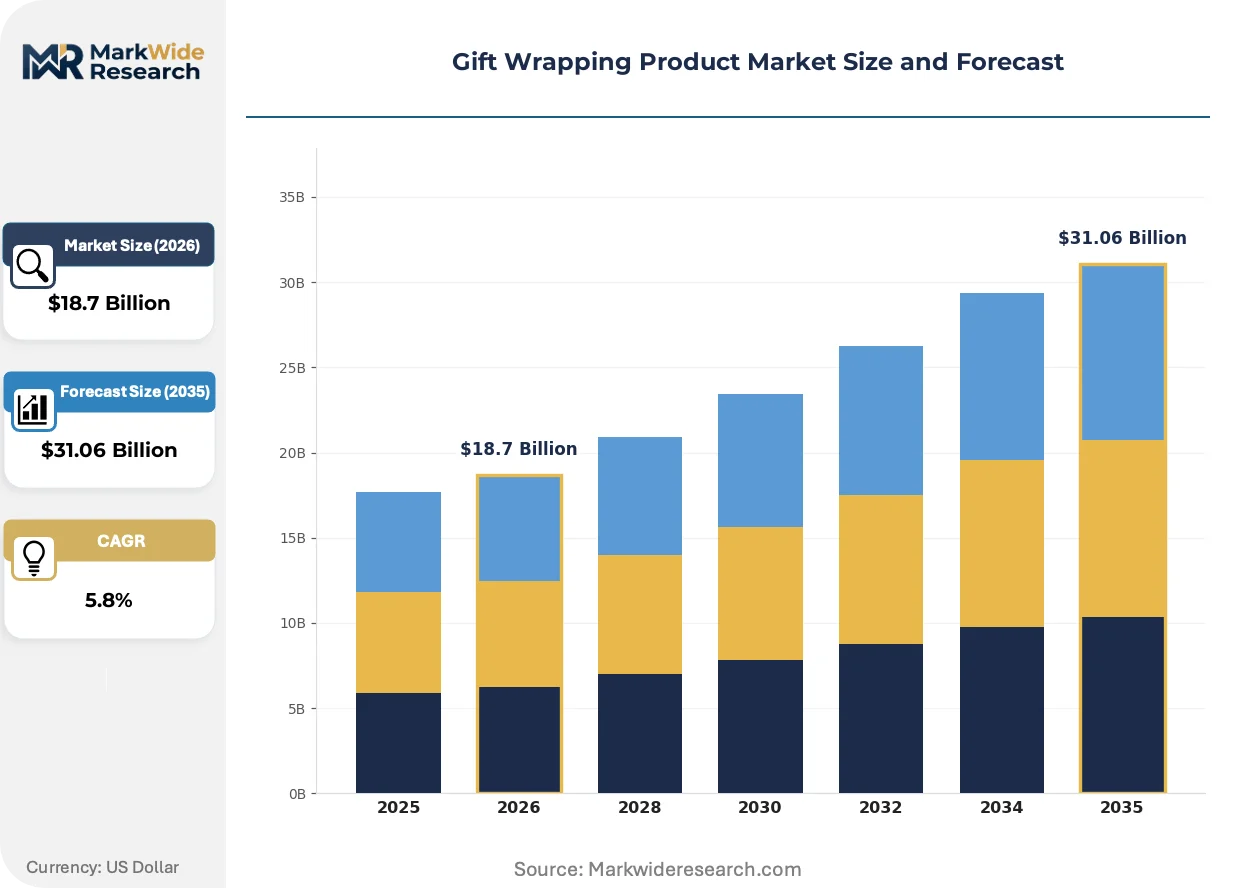
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrapping Paper, Gift Bags, Ribbon, Decorative Tape Material: Paper, Plastic, Fabric, Foil Size: Standard, Mini, Jumbo, Custom End User: Retailers, E-commerce, Corporate, Individual Consumers |
| Companies Covered | DS Smith, Card Factory plc, Hallmark Cards, Interpak, Smurfit Kappa Group, Mondi, Karl Knauer KG, Shenzhen Fuxiang Gifts & Packaging Co. Ltd., IG Design Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gift Wrapping Product Market Emerging Trajectories
Material science breakthroughs and platform-driven consumption patterns are collapsing traditional boundaries between industrial packaging and consumer-facing presentation layers.
Plantable seed paper embedded with wildflower and herb species is decomposing the single-use category boundary. Luxury cosmetics brands adopt these substrates for limited-edition launches, accepting higher per-unit costs to secure social media amplification. The technology is decomposing the distinction between packaging waste and product experience, forcing conventional mills to develop competing biodegradability credentials.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from food-contact gift packaging. European converters face 18-month reformulation windows to maintain shelf access. Premium chocolate and confectionery segments absorb compliance costs fastest, while mass-market suppliers delay investment pending clearer enforcement thresholds.
Subscription box curators now specify wrapping components as core product features rather than cost centers. Beauty and wellness verticals lead this specification shift, with unboxing video performance directly influencing reorder rates. North American direct-to-consumer brands drive the tightest customization requirements, demanding seasonal design rotations at quarterly intervals.
Gift Wrapping Product Market Segmentation
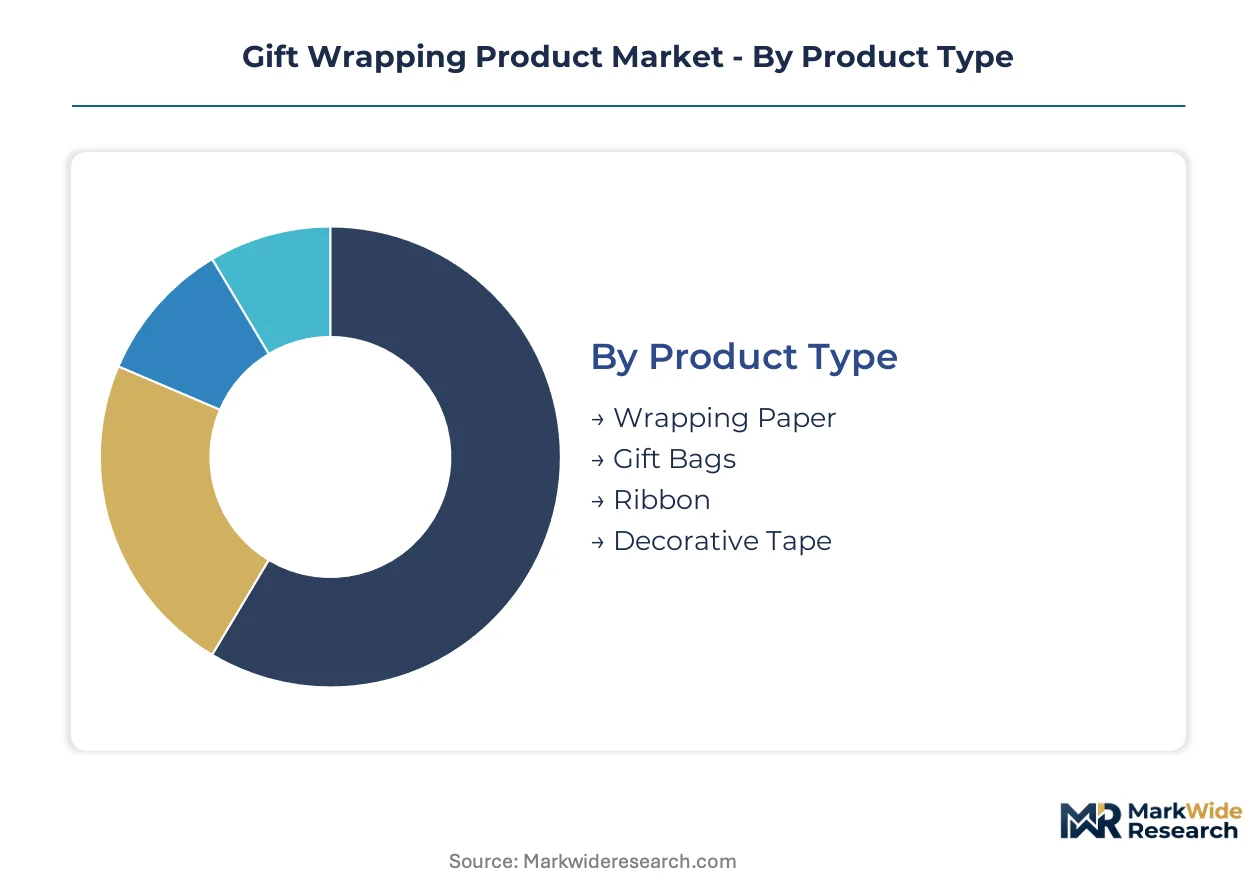
Segmentation in gift wrapping products determines compliance pathways, tooling investments, and margin structures. Regulatory thresholds on recyclability and food-contact safety split material choices, while e-commerce fulfillment requirements reshape size and format specifications.
Product Type:
REACH substance restrictions and extended producer responsibility mandates in Europe differentiate compliance burdens across formats, with food-contact applications facing the tightest reformulation timelines.
- Wrapping Paper:Specified by basis weight from 60 to 150 gsm, with kraft and coated stocks dominating mass retail. E-commerce unboxing specifications from Shenzhen cluster manufacturers drive demand for water-based ink compatibility and die-cutting precision.
- Gift Bags:Constructed from duplex board with twisted paper handles or ribbon reinforcements, specified by load capacity and burst strength. Retail shelf space competition in India and seasonal collection cycles in North America concentrate procurement decisions.
- Ribbon:Polyester satin and grosgrain grades specified by width and tensile strength, with wired-edge variants for floral applications. California SB 343 labeling requirements complicate multi-material construction.
- Decorative Tape:Washi and foil-faced variants gain share through social commerce bundling. TikTok Shop and Instagram Checkout enable direct-to-consumer seasonal rotations.
Wrapping paper handles the majority of throughput; decorative tape is expanding most quickly on share.
Material:
Cost tier stratification separates premium positioning from mass-market unit economics, with sustainability claims commanding measurable price premiums in direct-to-consumer channels.
- Paper:Unbleached kraft, coated art paper, and recycled-content stocks specified by FSC chain-of-custody certification. EU Packaging and Packaging Waste Regulation recyclability thresholds redirect R&D toward fiber-based barrier coatings.
- Plastic:Metallized PET films and BOPP laminates specified for moisture and grease resistance. Energy rationing vulnerability in Chinese production provinces concentrates supply risk.
- Fabric:Cotton, silk, and synthetic furoshiki formats penetrate premium gifting through reusability positioning. Higher per-unit costs limit penetration to cosmetics and luxury verticals.
- Foil:Aluminum and metallized polymer laminates specified for reflective properties and barrier performance. REACH authorization delays extend European market entry timelines.
Paper commands the volume base; fabric is climbing the fastest on sustainability-driven premiumization.
Size:
Application context determines format selection, with e-commerce fulfillment efficiency favoring standardized dimensions while retail display requirements drive jumbo and custom specifications.
- Standard:30x20 inch sheets and medium gift bags specified for general retail and personal gifting. High-volume die-cutting infrastructure in Shenzhen enables 48-hour turnaround for private-label orders.
- Mini:Compact formats for jewelry, cosmetics, and confectionery applications. Subscription box curators specify these as core product features rather than cost centers.
- Jumbo:Oversized sheets and bags for furniture, appliances, and bulk retail packaging. Limited converter capacity creates procurement bottlenecks during seasonal peaks.
- Custom:Bespoke dimensions for branded unboxing experiences and corporate gifting programs. Digital die-cutting equipment requirements strain mid-tier converter capital budgets.
Standard sizes absorb the production volume; custom formats are gaining share fastest through e-commerce specification.
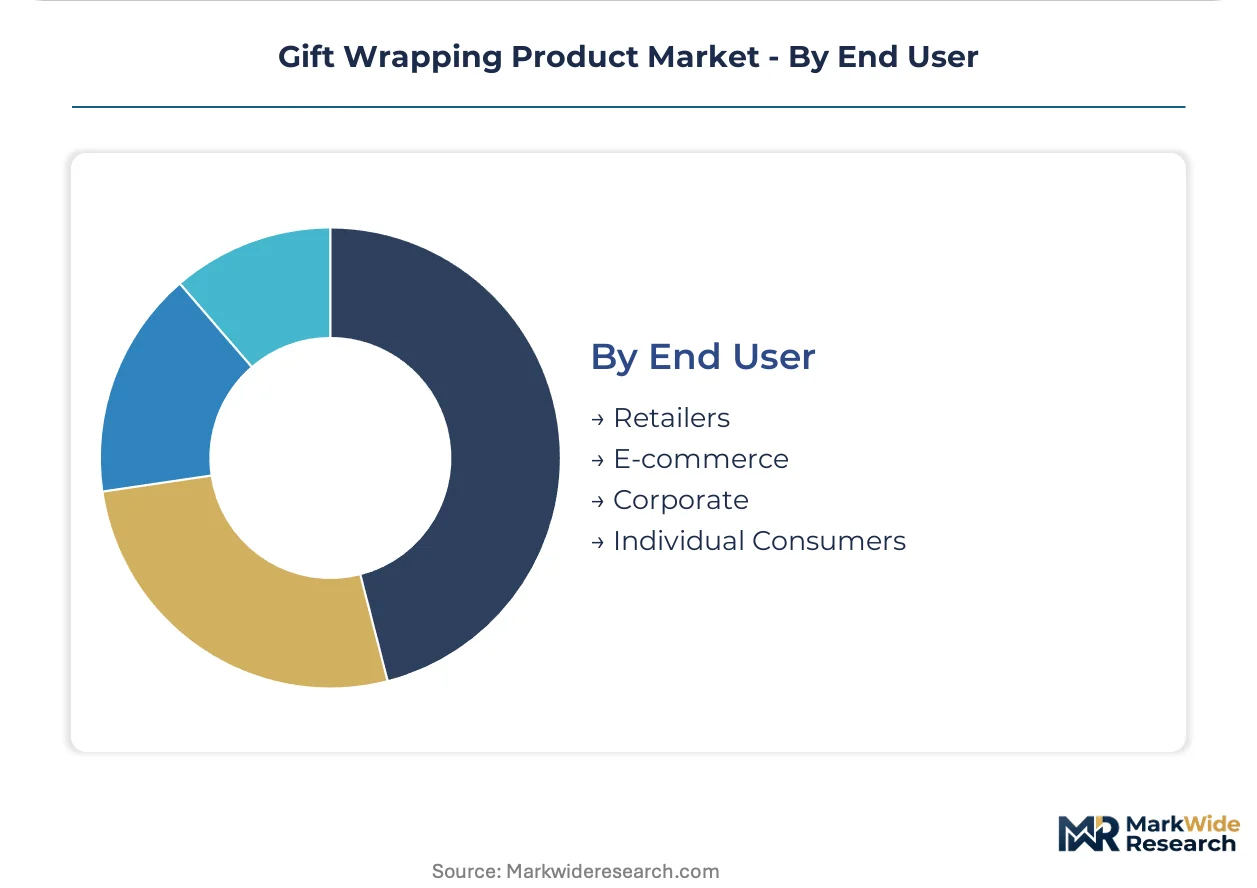
End User:
Customer type dictates order pattern, customization depth, and regulatory exposure, with corporate and e-commerce segments driving the tightest sustainability and traceability requirements.
- Retailers:Mass merchandisers and specialty chains specify seasonal collections with controlled shelf space allocation. Licensed character portfolios and exclusive designs anchor procurement decisions.
- E-commerce:Direct-to-consumer brands and marketplace sellers demand quarterly design rotations and unboxing-optimized formats. Video performance metrics directly influence reorder rates.
- Corporate:Branded gifting programs and employee recognition specifications require logo integration and volume flexibility. Extended producer responsibility compliance adds procurement complexity.
- Individual Consumers:Occasional purchasers through craft stores and online marketplaces. Price sensitivity limits penetration of premium sustainable formats.
Retailers move the largest volume; e-commerce is the steepest expansion trajectory on platform-driven consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies: mass-market consumers in India and Southeast Asia drive volume through value-tier formats, while Japanese and European buyers absorb premiums for certified sustainable substrates and reusable fabric systems.
United States
Direct-to-consumer beauty brands and subscription box curators specify wrapping components as core product features, with unboxing video performance directly influencing reorder rates. California SB 343 mandates recycling symbol standardization that complicates multi-material gift bag construction. Chicago and Dallas distribution hubs consolidate private-label inventory for e-commerce marketplace sellers.
Germany
Extended producer responsibility under the EU Packaging and Packaging Waste Regulation concentrates procurement decisions on fiber-based substrates with verified recyclability credentials. ECHA REACH substance restrictions eliminate per- and polyfluoroalkyl substances from grease-resistant coatings, forcing 18-month reformulation cycles for confectionery gift packaging. The Baden-Württemberg paper processing corridor anchors integrated recycling and corrugation infrastructure.
China
Shenzhen's manufacturing cluster enables 48-hour turnaround for private-label e-commerce orders through concentrated die-cutting and foil-stamping capacity. GB standards govern food-contact safety for gift packaging with incidental product contact. Domestic retail expansion in tier-two cities drives demand for seasonal wrapping paper collections beyond export-oriented production.
Japan
Furoshiki-inspired reusable fabric wrapping penetrates premium cosmetics and luxury gifting segments through sustainability positioning and cultural design heritage. METI guidelines on plastic resource circulation accelerate substitution toward paper-based alternatives. The Kansai region's textile heritage supports artisanal craft production alongside automated packaging lines.
India
Organized brick-and-mortar retail expansion creates shelf-space competition for branded gift bag portfolios in metropolitan markets. BIS certification requirements for paper products add compliance complexity for imported substrates. Maharashtra and Gujarat manufacturing zones develop domestic corrugation capacity to reduce dependence on Chinese die-cut supply.
Gift Wrapping Product Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on customization velocity and regional compliance expertise. The integrated tier controls captive paper recycling and corrugation infrastructure, while specialists concentrate on short-run digital finishing and licensed character portfolios. Two strategic archetypes dominate: fiber-based substrate innovators racing ahead of EU recyclability mandates, and agile converters exploiting Shenzhen's manufacturing cluster for e-commerce turnaround speed. Competitive moves center on backward integration into pulp supply and geographic expansion through distribution partnerships in underpenetrated retail markets.
Among European integrated players, DS Smith and Smurfit Kappa Group exemplify the fiber-based infrastructure archetype, with captive recycling loops and corrugation networks spanning multiple jurisdictions. Hallmark Cards occupies a position within the premium licensed-portfolio tier, anchoring seasonal collection cycles through controlled retail shelf space. Shenzhen Fuxiang Gifts & Packaging Co. Ltd. represents the volume-flexibility specialist archetype, leveraging Pearl River Delta manufacturing density for rapid private-label turnaround.
| Leading Market Players |
|---|
| DS Smith |
| Card Factory plc |
| Hallmark Cards |
| Interpak |
| Smurfit Kappa Group |
| Mondi |
| Karl Knauer KG |
| Shenzhen Fuxiang Gifts & Packaging Co. Ltd. |
| IG Design Group Plc |
| Others |
Supply Flow & Price Mechanics
Forty-eight-hour turnaround commitments from Shenzhen cluster manufacturers compress inventory cycles to sub-week levels, concentrating pricing power with converters who control die-cutting and foil-stamping capacity while forcing mid-tier competitors into spot-market pulp purchases.
Pricing Analysis
After-sales seasonal collection licensing drives lifetime value for premium gift wrapping portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified art paper from kraft stocks and uncoated commodity grades. Pricing pressure stems from softwood fiber cost volatility, with Nordic supply disruptions compressing margins on standard-grade wrapping paper. Mass-market retailers exhibit highest price sensitivity, while direct-to-consumer beauty brands absorb premiums for unboxing-optimized formats.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes expose inventory carrying cost vulnerabilities for European converters sourcing metallized films. Production concentrates in China, Germany, and the United States, with Shenzhen's Pearl River Delta anchoring die-cutting capacity and Baden-Württemberg hosting integrated recycling infrastructure. Raw material dependencies center on softwood pulp, metallized PET films, and water-based ink chemistries. Single-source foil dependency in Chinese energy-rationing provinces constitutes structural supply risk. Distribution runs through Chicago and Dallas hubs for North American e-commerce consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce platform consolidation among direct-to-consumer brands is shifting procurement leverage toward buyers who specify quarterly design rotations and unboxing performance metrics.
For Market Incumbents: Fortify backward integration into pulp supply to offset Nordic fiber volatility, and lock exclusive retail shelf space through licensed character portfolios before REACH reformulation deadlines eliminate non-compliant competitors. Water-based ink R&D investment serves as the critical defensive lever against substrate substitution threats. For New Entrants and Emerging Players: Anchor in India's organized retail expansion, where shelf-space competition for branded gift bags remains underdeveloped relative to metropolitan demand growth. Social commerce bundling of decorative tape through TikTok Shop and Instagram Checkout offers the most penetrable go-to-market angle for digital-native positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Packaging and Packaging Waste Regulation compliance timelines will strand non-compliant capacity and create acquisition opportunities for fiber-based substrate innovators. Watch for 18-month REACH authorization delays as the inflection signal for European market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber sourcing insulates margin from Nordic softwood volatility and ETS carbon pricing. |
| Water-Based Ink Chemistry Scale-Up | Eliminates plastic lamination requirements while preserving print fidelity for premium seasonal collections. |
| Social Commerce Direct-to-Consumer Launch | TikTok Shop and Instagram Checkout enable quarterly design rotations without retail shelf-space intermediation. |
| FSC Chain-of-Custody Certification Investment | Verified recyclability credentials unlock premium pricing tiers in EU and North American corporate gifting. |
| Shenzhen Manufacturing Cluster Partnership | Forty-eight-hour turnaround capability secures private-label e-commerce contracts from platform-native brands. |
Methodological Framework
Cross-validation between primary interviews with packaging converters, retail category buyers, and e-commerce supply chain managers and secondary validation through customs records, FSC certification databases, and EU regulatory filings anchors the qualitative findings. Conversations with plant managers at integrated paper mills, procurement leads at direct-to-consumer brands, and technical R&D directors at ink formulation specialists supplemented bottom-up demand modeling. Top-down triangulation against corrugation capacity databases and retail audit data ensured volume consistency.
Sensitivity analysis on pulp input costs and energy rationing scenarios frames the projection horizon. The analytical framework segments by product type, material substrate, size format, and end-user channel across the modeling period. CAGRs derive from trend extrapolation against historical capacity utilization and regulatory compliance investment cycles. E-commerce unboxing specification intensity and REACH substance restriction timelines serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and stable Asia-Europe logistics capacity; material deviation would warrant model refresh. Pulp price shocks, energy rationing in Chinese foil-producing provinces, or accelerated state-level packaging legislation in California and New York could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Card Films Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
Printed Aluminium Foil Packaging Market
Packaging Materials
Textile Packaging Market