
 Strip Pack Market | 2026-2036
Strip Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Strip Pack Market Analytics
Pharmacy-to-patient direct distribution is tilting toward unit-dose strip formats as mail-order fulfillment scales. Amcor PLC leverages its global film-laminate footprint to anchor supply for North American pharmacy networks. Constantia Flexibles Group GmbH competes through specialized aluminum-barrier lines for moisture-sensitive oral solids. ACG Pharmapack Private Limited dominates strip-pack exports from India with integrated blister-to-pouch conversion capabilities.
Strip pack denotes a single-unit or multi-unit pharmaceutical and consumer packaging format comprising heat-sealed foil, paper, or polymer laminates with tear-notched perforations for individual dose dispensing. The format typically employs cold-form or thermoform aluminum-PVC composites with moisture vapor transmission rates below 0.01 g/m²/day to protect hygroscopic APIs. Blister packs and sachets lead volume, with sachets recording the fastest expansion in nutraceutical powders and liquid unit doses where child-resistant tear profiles command margin premiums. Plastic and aluminum composites sustain the largest material share, though paper-based laminates are gaining ground in cosmetics sampling where sustainability credentials influence retailer procurement.
FDA 21 CFR Part 11 and DSCSA serialization requirements shape strip pack label integration and track-and-trace infrastructure investments. EMA's Falsified Medicines Directive and EU MDR technical documentation standards enforce tamper-evidence and patient-information-leaflet compliance across European supply chains. India's CDSCO and BIS packaging standards for export-oriented pharmaceutical units mandate specific barrier specifications for tropical-climate distribution. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and state-level packaging waste regulations in the US as these determine material substitution timelines and capital allocation for laminate recycling infrastructure.
Market Dynamics
Unit-dose serialization mandates from FDA and EMA are forcing pharmaceutical contract manufacturers to retrofit existing strip pack lines with integrated track-and-trace hardware, compressing capital cycles and favoring suppliers with turnkey compliance architectures.
Growth Catalysts
- Mail-order pharmacy fulfillment:North American pharmacy networks are scaling automated strip pack dispensing for direct-to-patient chronic disease management, driving volume for cold-form aluminum laminates.
- DSCSA serialization deadlines:FDA enforcement of unit-level traceability is compelling wholesale distributors to reject non-compliant strip packs, accelerating hardware upgrades across contract packaging operations.
- Thermoform barrier films:Next-generation polyethylene terephthalate glycol laminates with sub-0.005 g/m²/day moisture transmission rates are displacing legacy PVC for hygroscopic generic formulations in Indian export corridors.
Market Restraints
- Aluminum foil supply concentration:European smelter energy costs and Chinese export quotas on rolled aluminum products are creating input price volatility for laminate converters.
- EMA FMD verification infrastructure:Small-batch orphan drug manufacturers face disproportionate compliance burdens relative to serialization hardware costs, constraining product line diversity.
- Child-resistant tear-notch complexity:Multi-layer laminate structures required for pediatric safety certification extend validation timelines and reject rates during line qualification.
Strategic Opportunities
- Cosmetics sampling channel:Paper-based barrier laminates with bio-derived sealant layers are penetrating prestige beauty subscription boxes where sustainability credentials influence retailer procurement.
- India CDSCO tropical-climate specifications:Export-oriented pharmaceutical units require enhanced barrier specifications for high-humidity distribution, creating premium laminate tier demand.
- Nutraceutical powder sachets:Liquid and dry powder unit doses in tear-notched formats command margin premiums in direct-response wellness marketing channels.
Industry Challenges
- Serialization integration talent:Scarce expertise in combining track-and-trace software with heat-seal line mechanics is extending commissioning timelines for brownfield retrofit projects.
- Legacy blister-to-strip conversion:Pharmaceutical manufacturers with sunk investment in thermoform blister tooling face capital efficiency tradeoffs when migrating to pouch formats for compliance packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strip Pack Market |
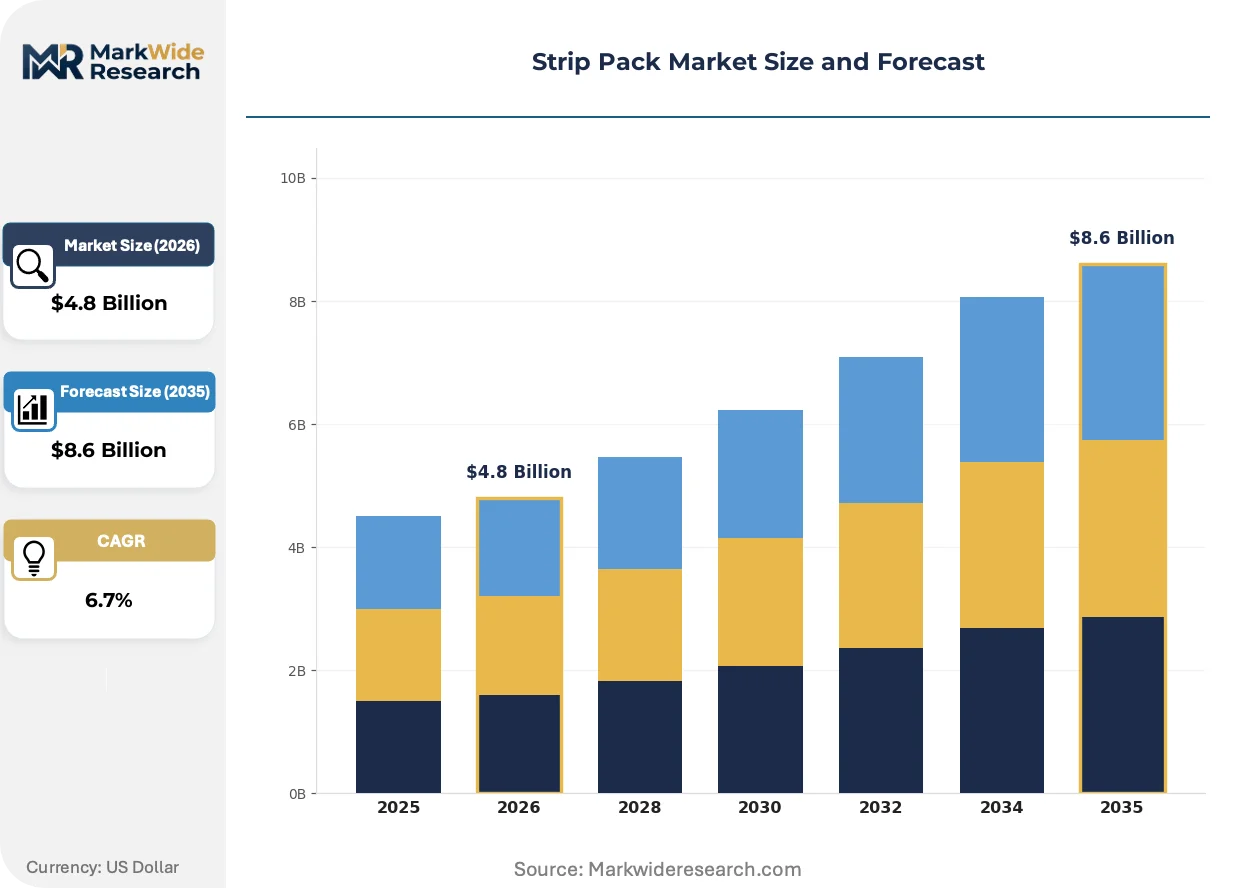
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pill Packs, Blister Packs, Sachets, Wraps Material: Plastic, Aluminum, Paper, Composites End User: Pharmaceuticals, Nutraceuticals, Consumer Goods, Cosmetics Distribution Channel: Online, Retail, Pharmacies, Others |
| Companies Covered | Constantia Flexibles Group GmbH, Amcor PLC, ACG Pharmapack Private Limited, Sonoco Products Company, Wasdell Packaging Limited, Bemis Company, Inc., Mikart, Inc., UFlex Limited, Klockner Pentaplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strip Pack Market Evolving Landscape
Digital printing and connected packaging technologies are virtualizing the strip pack value chain, collapsing lead times between artwork approval and production while enabling lot-specific patient engagement content.
Laser-marked serialization codes are replacing thermal-transfer ribbon printing on foil laminates, eliminating consumable changeover downtime and enabling real-time code verification against centralized databases. Large-volume generic manufacturers in India are adopting this technology fastest, driven by EU export compliance requirements. This shift is virtualizing quality assurance workflows, compressing manual inspection headcount while raising capital intensity for line automation.
EMA's Falsified Medicines Directive verification system is mandating end-to-end traceability across European pharmaceutical distribution, requiring strip pack converters to integrate aggregation software with warehouse management platforms. Contract manufacturers serving German pharmacy networks are absorbing the highest compliance costs due to early enforcement timelines. Cold-chain biologics in strip formats face the steepest adaptation curves, as existing barrier specifications must accommodate temperature-tracking sensor integration.
Direct procurement between pharmaceutical marketers and laminate converters is displacing traditional distributor intermediaries in North American mail-order channels, compressing pricing negotiation cycles and demanding just-in-time delivery guarantees. Pharmacy benefit managers with captive packaging operations are consolidating supplier relationships to three-film specifications maximum, forcing converters to absorb formulation customization costs. This concentration is most visible in Florida and Arizona retirement corridor fulfillment centers where chronic disease strip pack volumes anchor regional demand.
Strip Pack Market Segmentation
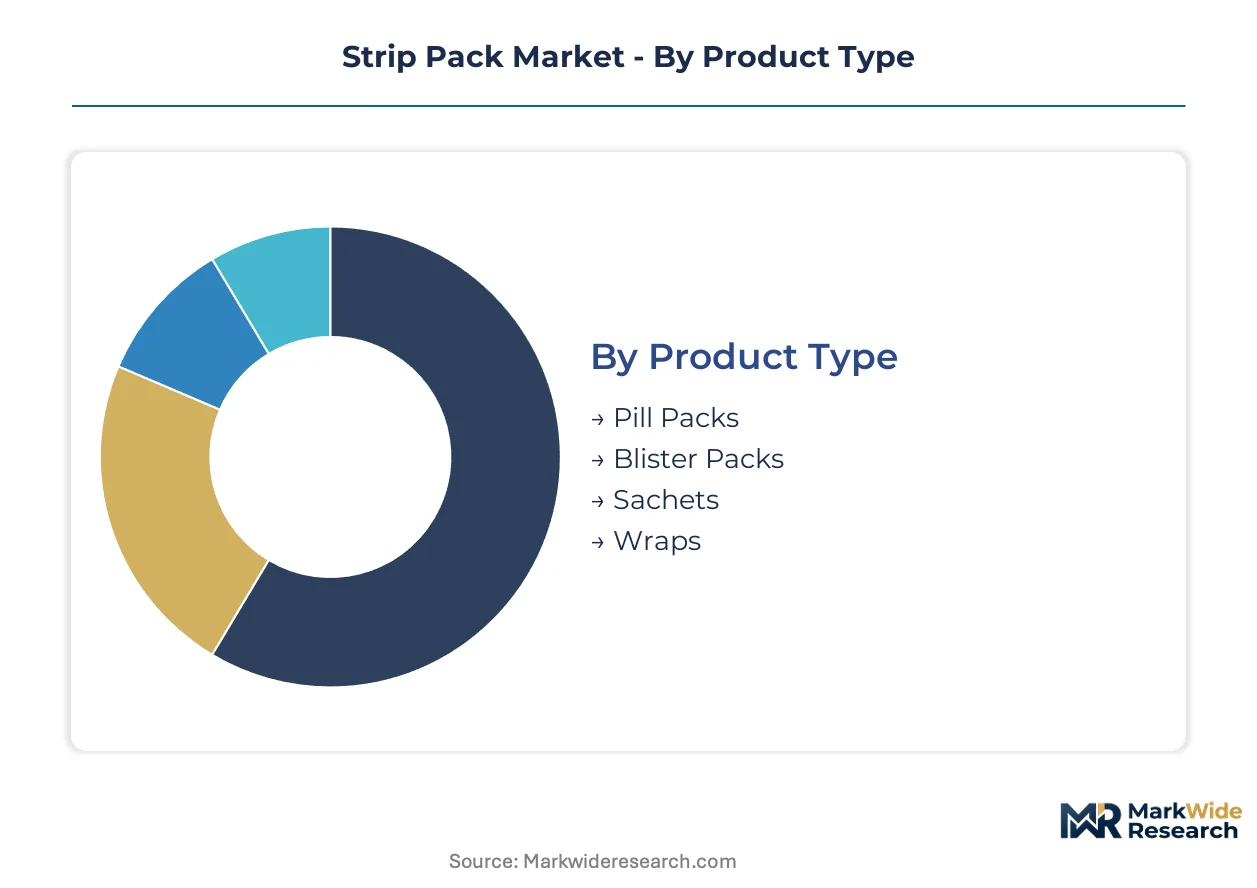
Strip pack segmentation reveals divergent technical requirements across pharmaceutical compliance, nutraceutical convenience, and cosmetic sampling channels. Each product configuration demands distinct barrier specifications, seal integrity profiles, and serialization integration levels that reshape supplier capability priorities.
Product Type:
After-sales service intensity varies sharply across product types, with sachet lines requiring frequent format changeover support and blister pack installations demanding sustained validation engineering.
- Blister Packs:Thermoformed or cold-formed cavities sealed against foil lidding dominate oral solid dose protection with moisture vapor transmission rates below 0.01 g/m²/day. North American mail-order pharmacy networks concentrate demand for calendar-compliant compliance packaging where patient adherence drives prescription renewal economics.
- Sachets:Three-side-seal or four-side-seal pouches with tear-notched perforations accommodate powders, liquids, and semi-solids where unit-dose portability commands premium positioning. Indian nutraceutical exporters and direct-response wellness marketers are scaling sachet volumes fastest for tropical-climate distribution requiring enhanced barrier specifications.
- Pill Packs:Multi-dose card formats with individual blister cavities arranged in calendar configurations serve chronic disease management programs.
- Wraps:Single-layer or laminated film enclosures for bulk oral solids and medical devices prioritize cost efficiency over barrier performance.
By volume, blister packs lead. By growth pace, sachets are ahead.
Material:
Cost tier stratification separates aerospace-grade aluminum laminates from commodity polymer alternatives, with composite structures commanding mid-tier positioning through functional customization.
- Composites:Multi-layer aluminum-PVC, aluminum-PE, or paper-foil-polymer laminates integrate barrier, print, and sealant functions in single-web constructions. German pharmaceutical contract manufacturers specify composite structures for EMA FMD-compliant serialization where laser-marking compatibility and tamper-evidence must coexist.
- Aluminum:Rolled annealed foil in thicknesses from 20-50 micron provides absolute moisture, light, and gas barrier for hygroscopic APIs. European smelter energy costs and Chinese export quotas are compressing margin structures for converters dependent on virgin foil supply.
- Plastic:Mono- or multi-layer polyethylene, polypropylene, or PET structures serve cost-sensitive applications with moderate barrier requirements.
- Paper:Kraft or glassine-based laminates with bio-derived sealant layers penetrate cosmetics sampling and sustainable packaging mandates.
Composites capture the largest volume share. Paper-based alternatives are climbing the fastest as retailer sustainability procurement criteria harden.
End User:
Application-driven specification divergence separates pharmaceutical cGMP validation requirements from nutraceutical speed-to-market priorities and cosmetic aesthetic demands.
- Pharmaceuticals:FDA 21 CFR Part 11 and DSCSA serialization mandates enforce unit-level traceability, tamper-evidence, and patient-information integration. US wholesale distributors now reject non-compliant strip packs, forcing contract manufacturers to absorb hardware retrofit costs.
- Nutraceuticals:Powder and liquid unit doses in tear-notched formats command margin premiums in subscription wellness channels where child-resistant certification and convenience positioning coexist.
- Consumer Goods:Single-serve condiments, sweeteners, and personal care samples prioritize cost minimization and shelf presence.
- Cosmetics:Prestige beauty sampling and travel-size formats demand paper-based barrier laminates with print quality and sustainability credentials that influence retailer procurement decisions.
Pharmaceuticals anchor volume demand. Cosmetics represents the steepest expansion trajectory as sampling economics shift toward subscription models.
Distribution Channel:
Customer type fragmentation separates automated pharmacy fulfillment infrastructure from retail shelf replenishment and direct-to-consumer logistics.
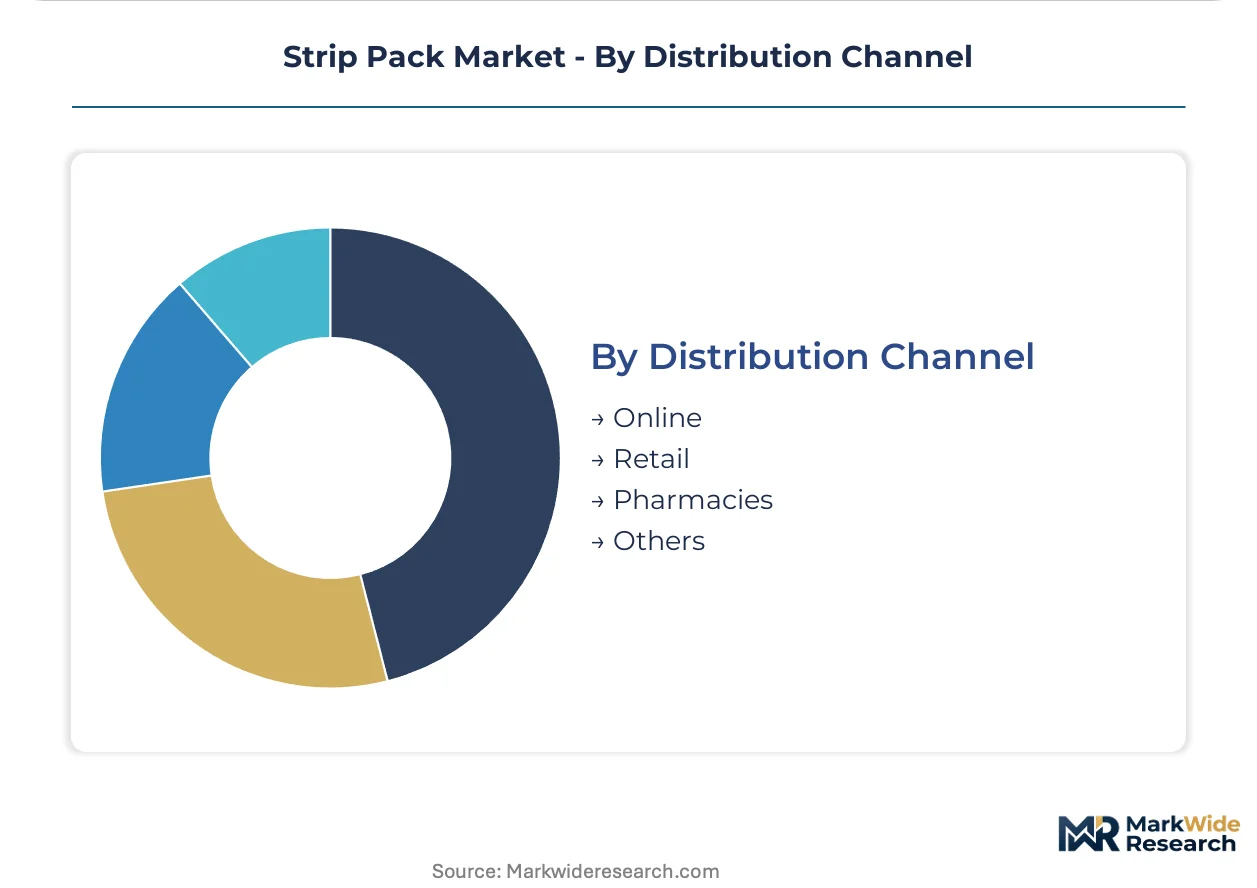
- Pharmacies:Mail-order and specialty pharmacy networks in Florida and Arizona retirement corridors drive automated strip pack dispensing for chronic disease management. Pharmacy benefit managers with captive packaging operations are consolidating supplier relationships to maximum three-film specifications.
- Online:Direct-to-patient and direct-to-consumer channels compress lead times and demand just-in-time delivery guarantees from laminate converters.
- Retail:Mass merchandiser and convenience store replenishment prioritizes case-level efficiency and promotional packaging flexibility.
- Others:Hospital and clinical trial supply chains require lot-level traceability without full serialization infrastructure.
Pharmacies dominate current volume. Online channels are gaining share fastest as patient and consumer direct procurement normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA serialization deadlines and FDA track-and-trace mandates are redistributing pharmaceutical packaging investment toward jurisdictions with integrated compliance infrastructure. Contract manufacturers in Germany and India are capturing disproportionate capital flows as regulatory enforcement tightens across foil-laminate formats.
United States
Mail-order pharmacy fulfillment in Florida and Arizona retirement corridors drives automated strip pack dispensing for chronic disease management. FDA DSCSA unit-level traceability requirements now compel wholesale distributors to reject non-compliant packaging, accelerating hardware retrofits across contract packaging operations in these states.
Germany
Pharmaceutical contract manufacturers around Düsseldorf and Munich are scaling cold-form aluminum-barrier lines for moisture-sensitive oral solids. EMA Falsified Medicines Directive verification infrastructure imposes aggregation software requirements that small-batch orphan drug manufacturers struggle to absorb, consolidating volume among larger converters.
India
Export-oriented pharmaceutical units in Gujarat and Maharashtra require CDSCO-mandated tropical-climate barrier specifications for high-humidity distribution corridors. Integrated blister-to-pouch conversion capabilities in Ahmedabad and Mumbai anchor generic strip pack exports to European and African markets.
China
Rolled aluminum supply concentration in Shandong and Henan provinces faces export quota pressures and energy cost volatility from European smelter disruptions. Domestic laminate converters are securing captive foil supply through backward integration into upstream rolling operations.
Switzerland
Precision barrier laminate development for cold-chain biologics concentrates around Basel and Zurich pharmaceutical clusters. Swissmedic technical documentation standards enforce tamper-evidence specifications that exceed baseline EU requirements, creating premium tier demand for sensor-integrated strip formats.
Strip Pack Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: global film-laminate platforms with integrated serialization architecture, specialized aluminum-barrier specialists serving moisture-sensitive formulations, and regional contract manufacturers competing on tropical-climate compliance certification. The dominant competitive moves involve capacity expansion in Indian export corridors and strategic partnerships between laminate converters and pharmacy benefit managers with captive packaging operations.
Within the integrated global platform tier, Amcor PLC and Constantia Flexibles Group GmbH exemplify divergent specialization vectors—one leveraging scale across North American pharmacy networks, the other anchoring European compliance through dedicated aluminum-barrier engineering. ACG Pharmapack Private Limited occupies a position among India-based integrated manufacturers, representing the export-oriented archetype with captive blister-to-pouch conversion capabilities. These three entities collectively illustrate how regulatory geography determines competitive positioning: North American mail-order scale, European barrier precision, and Indian tropical-climate export certification each command distinct capability premiums.
| Leading Market Players |
|---|
| Constantia Flexibles Group GmbH |
| Amcor PLC |
| ACG Pharmapack Private Limited |
| Sonoco Products Company |
| Wasdell Packaging Limited |
| Bemis Company, Inc. |
| Mikart, Inc. |
| UFlex Limited |
| Klockner Pentaplast |
| Others |
Value Network & Pricing Analysis
Undercapacity in European aluminum foil rolling capacity following energy cost spikes is forcing laminate converters to accept longer lead times and pass through input volatility, compressing margin buffers across mid-tier suppliers while concentrating pricing power among integrated multinationals with captive raw material access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates strip pack procurement, with premium tiers commanding spreads for EMA FMD-compliant laser-marking compatibility and tropical-climate certification. Price differentiation rests on barrier performance grade and serialization integration depth, with FDA 21 CFR Part 11 validation tiers separating contract manufacturers. Cost compression in standard-grade aluminum-PVC laminates is intensifying because Indian export corridors are scaling thermoform PET-G displacement of legacy materials. Pharmacy benefit managers with captive packaging operations exhibit lowest price sensitivity due to adherence program economics, while generic exporters in Gujarat face acute cost pressure on spot purchases.
Supply Chain Analysis
Contract manufacturing concentration among German pharmaceutical packagers around Düsseldorf and Mumbai-based integrated converters anchors global strip pack capacity, with ACG Pharmapack and Constantia Flexibles holding dominant positions in their respective regulatory corridors. Geographic supply concentration centers on Germany, India, and China, with Chinese rolled foil from Shandong feeding laminate converters across Asia-Pacific. Raw material dependencies draw from aluminum smelter output, polymer resin supply, and specialty adhesive formulations. Single-source vulnerability in European aluminum foil supply creates structural exposure to energy cost shocks. Distribution runs through direct procurement channels between pharmaceutical marketers and laminate converters, displacing traditional distributor intermediaries in North American mail-order pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of serialization-integrated heat-seal engineering talent is constraining brownfield retrofit timelines and creating capability premiums for suppliers with turnkey compliance architectures, fundamentally reshaping competitive mobility in this market.
For Market Incumbents: Entrench market position through backward integration into aluminum foil rolling capacity to insulate margin structures from European energy cost volatility and Chinese export quota uncertainty. Prioritize certification investment in CDSCO tropical-climate specifications to capture premium tier demand from Indian generic exporters facing high-humidity distribution requirements. Channel control through exclusive supply agreements with pharmacy benefit managers' captive packaging operations provides defensive moats against emerging regional competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in cosmetics sampling channels where paper-based barrier laminates with bio-derived sealant layers command sustainability premiums from prestige beauty subscription box retailers. Target nutraceutical powder sachets for direct-response wellness marketers, where child-resistant tear-notch certification and convenience positioning support margin capture. A go-to-market angle anchored in rapid format changeover support services addresses unmet needs among small-batch orphan drug manufacturers struggling with EMA FMD verification infrastructure burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated contract manufacturers with captive blister-to-pouch conversion capabilities and long-term supply agreements with pharmacy benefit managers. Long-term viability over the next decade hinges on regulatory compliance infrastructure depth rather than commodity laminate production scale. Acquisition targets should emphasize German or Indian contract manufacturers with proven EMA FMD and FDA DSCSA serialization integration. The critical signal to watch is wholesale distributor rejection rates for non-compliant strip packs, which indicate enforcement intensity and compliance investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Hardware Retrofit | Enables FDA DSCSA compliance for contract manufacturers serving US wholesale distributors. |
| Backward Integration into Foil Rolling | Insulates margin structures from European smelter energy cost volatility and supply quota restrictions. |
| Tropical-Climate Certification Investment | Captures premium tier demand from Indian generic exporters targeting high-humidity African and Asian markets. |
| Laser-Marking Technology Adoption | Eliminates thermal-transfer consumable downtime while satisfying EU FMD traceability mandates for foil laminates. |
| Direct Procurement Channel Development | Displaces distributor intermediaries in North American mail-order pharmacy fulfillment corridors. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical contract manufacturing executives, regulatory affairs specialists at laminate converters, pharmacy benefit manager procurement directors, and serialization systems integrators, and refined through secondary validation against FDA DSCSA guidance documents, EMA FMD implementation reports, CDSCO packaging standard notifications, and customs trade data on aluminum foil imports. Bottom-up demand modeling across blister pack, sachet, pill pack, and wrap configurations was triangulated with top-down market sizing from identified supplier capacity announcements.
Demand-supply-balance dynamics across the analysis window were modeled through segmented projections by product type, material composite structure, end-use application, and regional regulatory cluster, with CAGRs derived from regression analysis of historical volume trajectories and forward-looking capacity expansion announcements. Forecast inputs incorporated pharmaceutical serialization mandate enforcement timelines, mail-order pharmacy fulfillment infrastructure buildouts in Florida and Arizona retirement corridors, and Indian generic export volume trends to European and African markets.
Sensitivities concentrate around aluminum foil price volatility from European energy cost shocks, DSCSA enforcement timeline acceleration or delay, and CDSCO tropical-climate specification revisions. Forecasts reflect assumptions on regulatory compliance cost absorption by contract manufacturers and serialization hardware commissioning timelines. Quarterly review of wholesale distributor rejection rates for non-compliant packaging, European smelter capacity utilization, and Indian export corridor volume data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Printed Aluminium Foil Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
EPE Liner Market
Packaging Materials
VCI Packaging Market