
 Stretch Packaging Market | 2026-2036
Stretch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Packaging Market Outlook
The stretch packaging sector is rebalancing between premium engineered films and commodity polyethylene wraps. Dow Inc. leverages its upstream resin integration to control feedstock costs across North American operations. Sealed Air Corporation differentiates through proprietary nanolayer coextrusion technology that reduces film gauge without sacrificing load containment. Berry Global anchors its position via massive blown film capacity and direct supply relationships with big-box retailers.
Stretch packaging encompasses elastic plastic films, primarily linear low-density polyethylene with metallocene catalyst enhancement, manufactured through cast or blown extrusion processes to provide unitization and protection for palletized goods during transit and storage. Machine stretch film commands the dominant volume position due to warehouse automation penetration, while pre-stretched film captures the fastest growth trajectory by cutting material consumption per pallet. Polyethylene maintains overwhelming material share, though polypropylene gains traction in high-clarity retail-facing applications where optical properties matter.
The EPA regulates plastic waste streams under the Resource Conservation and Recovery Act, while ISO 9001 and ASTM D4649 govern film performance specifications and quality management systems for industrial packaging procurement. California's SB 54 mandates source reduction and recycling targets that reshape film formulation requirements for suppliers serving West Coast distribution networks. Stakeholders must monitor how extended producer responsibility frameworks evolve across multiple states and whether chemical recycling infrastructure scales sufficiently to meet post-consumer content thresholds without compromising film clarity or elongation properties.
Market Dynamics
Automated warehouse systems are compressing film specification tolerances as fulfillment centers demand consistent machine-grade performance across high-speed wrapping lines. This operational imperative is forcing converters to prioritize gauge uniformity and puncture resistance over raw material cost minimization.
Growth Catalysts
- E-commerce fulfillment automation:Distribution centers in Germany and the Netherlands are installing robotic palletizing systems that require pre-stretched films with predictable elongation profiles.
- EU Packaging and Packaging Waste Regulation:Recycled content mandates for plastic films are accelerating demand for certified circular polyethylene grades across European manufacturing supply chains.
- Metallocene catalyst technology:Advanced polymerization processes enable down-gauging without load containment degradation, cutting resin consumption per pallet.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracking margins fluctuate with crude oil benchmarks, squeezing converter profitability during energy price spikes.
- Blown film capacity concentration:North American resin integration favors integrated petrochemical players over independent film processors.
- Mechanical recycling limitations:Contamination from multi-layer films and adhesive residues degrades post-consumer polyethylene quality for stretch film reprocessing.
Strategic Opportunities
- India's organized retail expansion:Cold chain infrastructure investments by Reliance Retail and BigBasket are creating demand for breathable stretch films for perishable palletization.
- Chemical recycling scale-up:Pyrolysis and depolymerization facilities in Belgium and the Netherlands promise food-grade recycled content without clarity loss.
- Pre-stretched film penetration:Manual wrapping operations in Southeast Asian logistics hubs remain underconverted from conventional hand-wrap formats.
Industry Challenges
- Extrusion technician scarcity:Blown film line operators with gauge control expertise command premium wages in industrial packaging clusters around Düsseldorf.
- Multi-layer coextrusion capex:Nanolayer equipment for seven-layer films requires capital commitments that strain mid-tier converters.
- Extended producer responsibility compliance:Fee structures and reporting obligations vary across German federal states, complicating national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Packaging Market |
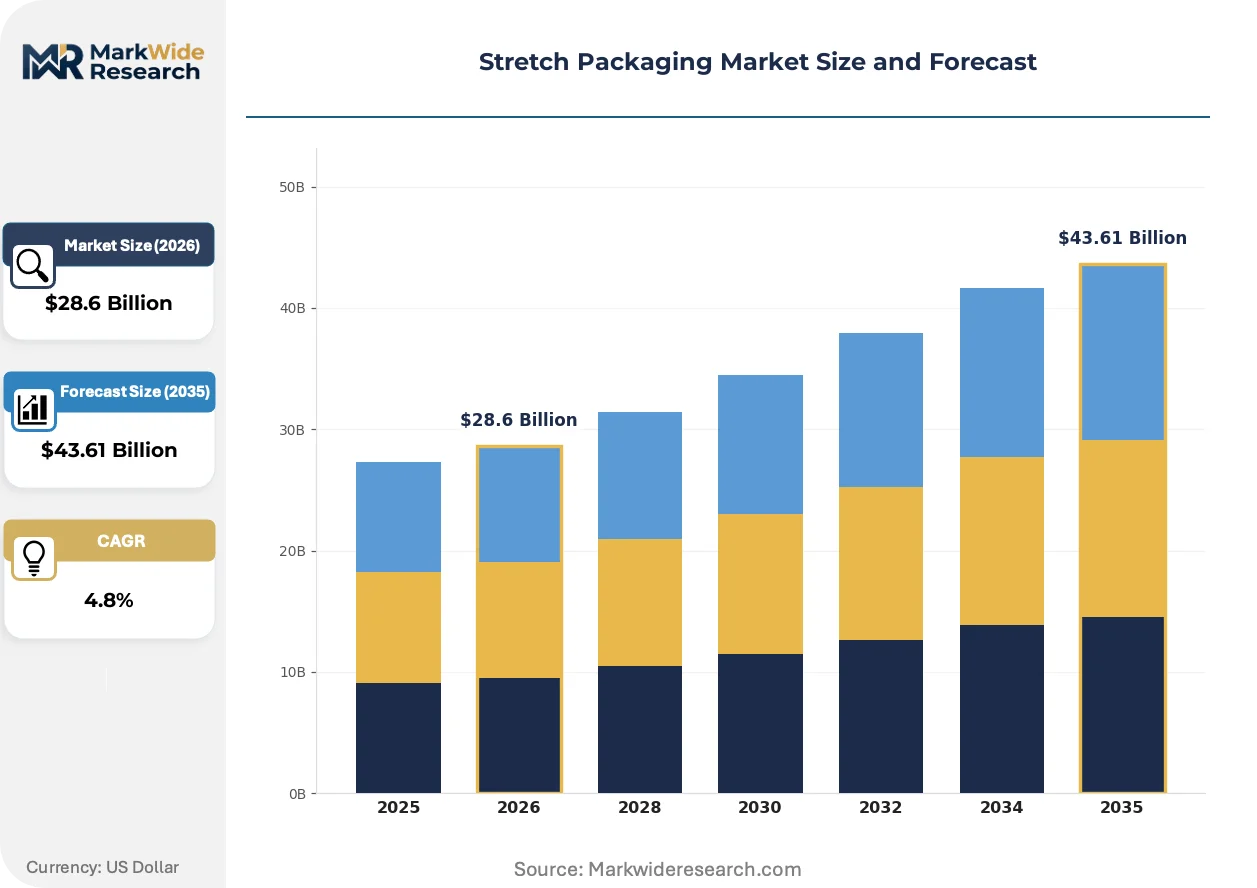
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-stretched Film, Hand Stretch Film, Machine Stretch Film, Stretch Hood Material: Polyethylene, Polypropylene, PVC, Others End User: Food & Beverage, Consumer Goods, Pharmaceuticals, Industrial Products Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Berry Global, Amcor plc, Dow Inc., Sealed Air Corporation, Sigma Plastics Group, Intertape Polymer Group, Mondi Group, AEP Industries Inc., Paragon Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Packaging Market Strategic Shifts
Film engineering is converging with automation requirements as warehouse operators prioritize throughput consistency over unit cost reduction. Technical specifications are tightening around machine compatibility rather than standalone material performance.
Multi-layer coextrusion with nanolayer architecture is unifying puncture resistance and clarity in a single film structure. Cold storage distributors in the Benelux region are specifying these grades for frozen food palletization. The technology is unifying previously separate premium and standard product tiers into consolidated specifications that satisfy both retail presentation and industrial load containment demands.
REACH restrictions on intentionally added microplastics are compelling film formulators to eliminate slip agents and anti-block additives that fragment during use. Industrial packaging procurement teams in France and Italy are now requiring additive-free certifications for films entering closed-loop warehouse systems. Machine stretch film categories face the steepest reformulation costs due to their reliance on processing aids for high-speed unwinding.
Consolidated procurement through third-party logistics providers is compressing supplier rosters as DHL Supply Chain and XPO Logistics centralize stretch film purchasing across multi-site warehouse networks. Regional distributors in Poland and the Czech Republic are losing direct access to end-users as national contracts displace local sourcing relationships. Food and beverage manufacturers with pan-European distribution footprints are driving this concentration most aggressively.
Stretch Packaging Market Segmentation
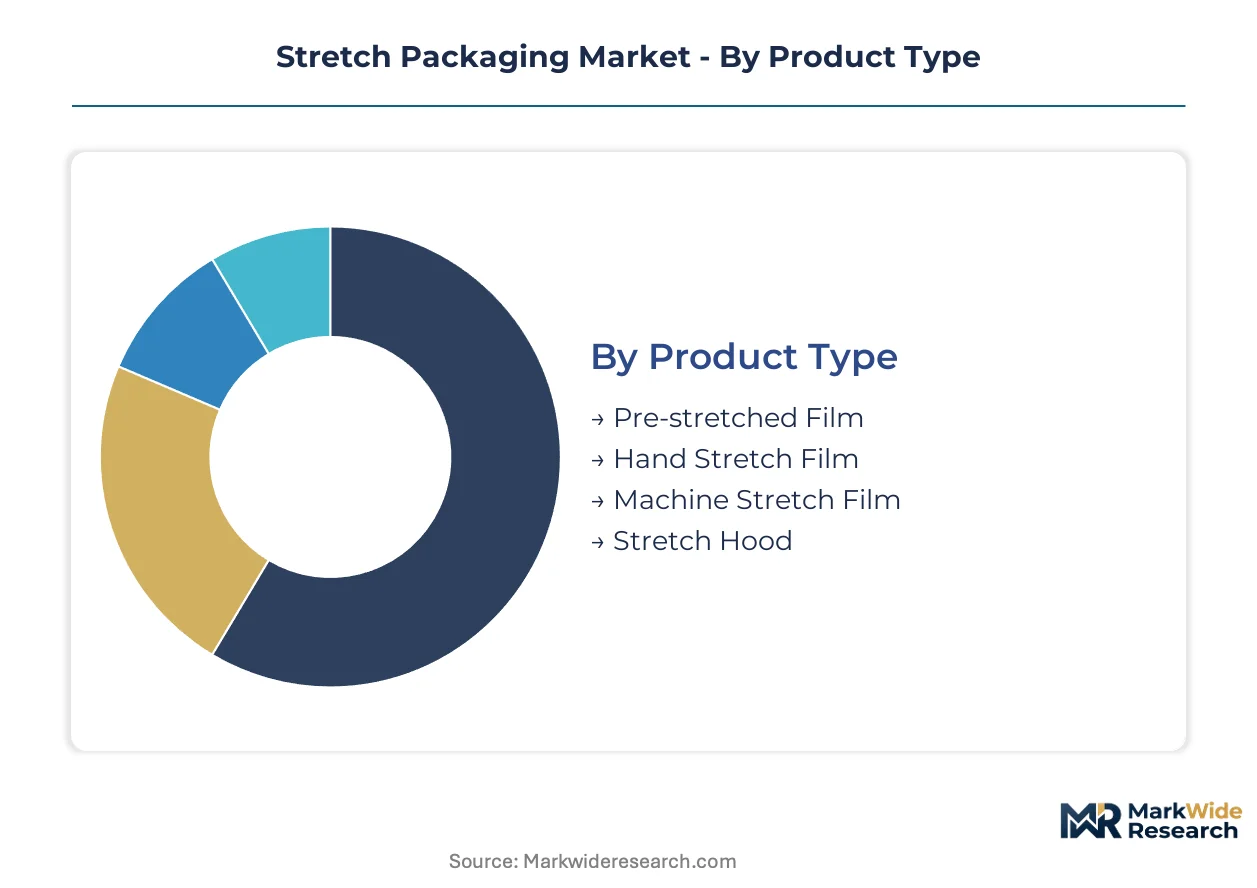
Stretch packaging procurement decisions increasingly hinge on automation compatibility and material compliance rather than unit cost alone. Warehouse operators are segmenting their film specifications by equipment interface requirements and regulatory exposure, forcing converters to align product portfolios with distinct operational profiles rather than generic performance tiers.
Product Type:
Equipment upgrade cycles are displacing legacy hand-wrap operations as distribution centers automate palletizing lines and demand films with calibrated elongation profiles.
- Machine Stretch Film:Linear low-density polyethylene formulations with metallocene catalyst enhancement deliver gauge uniformity for high-speed wrapping lines. German fulfillment centers around Düsseldorf specify these grades for robotic palletizing systems that require predictable load containment. The segment anchors volume demand from automated warehouse networks.
- Pre-stretched Film:Factory-stretched rolls reduce material consumption per pallet by 30-40% compared to conventional wraps. Cold chain distributors in the Netherlands favor these grades for frozen food logistics where film consistency affects throughput. The format gains share fastest among sustainability-focused procurement teams.
- Hand Stretch Film:Conventional cast extrusion grades serve manual wrapping operations in smaller logistics hubs.
- Stretch Hood:Tubular film systems for unitized pallet coverage in bulk chemical and construction material distribution.
Machine stretch film sits at the top of the volume ranking, with pre-stretched film climbing the fastest.
Material:
Polymer selection stratifies by clarity requirements and recycling infrastructure access, with circular content mandates reshaping procurement specifications.
- Polyethylene:Blown and cast extrusion of linear low-density grades dominates industrial packaging due to puncture resistance and elongation recovery. EU Packaging and Packaging Waste Regulation recycled content thresholds are accelerating demand for certified circular polyethylene across European manufacturing supply chains.
- Polypropylene:Cast film clarity suits retail-facing applications where optical properties affect shelf presentation. Italian food distributors specify these grades for palletized display shipments requiring barcode scanning through film layers.
- PVC:Remains in niche pharmaceutical applications requiring specific barrier properties.
- Others:Bio-based and compostable formulations for specialized closed-loop systems.
Polyethylene commands the dominant material position, while polypropylene expands most quickly in premium retail logistics.
End User:
Customer segmentation reflects divergent regulatory exposure and automation maturity across supply chain tiers.
- Food & Beverage:Cold chain palletization demands breathable films and FDA-compliant formulations for perishable distribution. California SB 54 source reduction mandates reshape film specifications for West Coast beverage distribution networks.
- Industrial Products:Heavy-load containment drives specification toward high-puncture machine grades for metal and machinery exports. German automotive component suppliers around Hamburg specify reinforced films for intercontinental container shipments.
- Consumer Goods:E-commerce fulfillment centers prioritize pre-stretched formats for dimensional weight optimization.
- Pharmaceuticals:Serialization compatibility and cleanroom handling requirements govern film selection for drug distribution.
Food and beverage generates the largest segment volume, with consumer goods gaining share fastest from e-commerce automation.
Distribution Channel:
Channel structure concentrates around national logistics contracts that displace regional distributor relationships.
- Direct Sales:National accounts with DHL Supply Chain and XPO Logistics centralize procurement across multi-site warehouse networks. Direct relationships enable specification customization for automated lines.
- Offline:Regional distributors in Poland and Czech Republic retain access to mid-tier converters serving smaller manufacturing operations.
- Online:Digital procurement platforms for standardized hand-wrap grades in spot purchasing.
- Retail:Big-box store channels for small-volume warehouse and light industrial users.
Direct sales sits at the top of the volume ranking, with online channels climbing the fastest among decentralized logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blown film technicians with gauge control expertise command premium wages in industrial packaging clusters around Düsseldorf and Hamburg, anchoring European supply capacity. German automotive component suppliers and Dutch cold chain distributors drive specification intensity for machine-grade and pre-stretched formats.
Germany
Automotive component exports and e-commerce fulfillment automation generate concentrated demand for high-puncture machine films. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that reshape converter formulations. Industrial packaging clusters around Düsseldorf and Hamburg serve as export logistics hubs for European manufacturing supply chains.
United States
Beverage distribution networks and big-box retail procurement drive volume demand for cast and blown polyethylene films. California's SB 54 imposes source reduction and recycling targets that reshape film specifications for West Coast suppliers. Resin-integrated operations along the Gulf Coast anchor North American feedstock cost structures.
Netherlands
Frozen food logistics and robotic palletizing systems require pre-stretched films with predictable elongation profiles. REACH restrictions on intentionally added microplastics compel additive-free certifications for closed-loop warehouse systems. Cold storage distributors in the Benelux region specify nanolayer grades for retail-facing palletization.
India
Organized retail expansion and cold chain infrastructure investments by Reliance Retail and BigBasket create demand for breathable stretch films for perishable palletization. BIS standards govern film performance specifications for industrial packaging procurement. Logistics hubs in Maharashtra and Karnataka remain underconverted from conventional hand-wrap formats.
China
E-commerce fulfillment center automation and export manufacturing generate scale demand for machine-grade stretch films. GB standards and MIIT regulations govern plastic film quality and environmental compliance. Yangtze River Delta packaging clusters serve domestic distribution and intercontinental container shipment markets.
Stretch Packaging Market Competitive Environment
Top-tier vendors anchor resin-integrated and nanolayer technology positions, while mid-tier converters compete on regional service relationships and specialized gauge capabilities. The vendor base stratifies across three archetypes: upstream petrochemical players with captive polyethylene supply, engineered film specialists with proprietary coextrusion technology, and volume processors with massive blown film capacity. Dominant competitive moves include backward integration into resin production and strategic partnerships with third-party logistics providers for national contract consolidation.
Among North American resin-integrated players, Dow Inc. and Berry Global exemplify upstream control strategies that stabilize feedstock cost positions. Sealed Air Corporation occupies a position within the engineered film tier, representing proprietary technology differentiation. These three companies anchor the competitive structure through distinct capability configurations rather than overlapping market approaches.
| Leading Market Players |
|---|
| Berry Global |
| Amcor plc |
| Dow Inc. |
| Sealed Air Corporation |
| Sigma Plastics Group |
| Intertape Polymer Group |
| Mondi Group |
| AEP Industries Inc. |
| Paragon Films |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation recycled content mandates gate qualified supply for certified circular polyethylene grades, restricting premium-tier pricing access to converters with chemical recycling partnerships and mass-balance certifications. Buyers without circular content requirements face commoditized pricing pressure from resin-integrated competitors with captive feedstock positions.
Pricing Analysis
Service bundling separates national contract holders from spot purchasers, with DHL Supply Chain and XPO Logistics securing specification customization alongside volume discounts. Three-tier pricing structure across premium nanolayer, standard machine-grade, and economy hand-wrap levels reflects certification grade and automation compatibility. Price differentiation stems from metallocene catalyst access and gauge uniformity guarantees. Margins are tightening due to ethylene feedstock volatility, with independent converters most exposed and resin-integrated players least sensitive.
Supply Chain Analysis
Warehouse-distribution layer consolidation concentrates procurement through third-party logistics hubs in Germany, the Netherlands, and the United States. Supply draws from blown film capacity clusters in Germany, the United States, and China, with resin feedstock anchored in Gulf Coast petrochemical operations and Middle Eastern naphtha-cracking complexes. Raw material dependencies center on linear low-density polyethylene resin, metallocene catalysts, and slip agent additives. Single-source vulnerability runs through concentrated resin supply from integrated petrochemical majors. Distribution runs through direct national accounts and regional distributor networks serving mid-tier manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as warehouse automation penetration shifts procurement specifications toward machine-grade films with calibrated elongation profiles and predictable load containment performance.
For Market Incumbents: Cement resin-integrated cost positions through backward integration into circular polyethylene supply chains, defending against specialty converters with chemical recycling partnerships. Prioritize nanolayer coextrusion R&D investments to maintain specification leadership against emerging Asian equipment suppliers. Channel control through direct national logistics contracts anchors volume retention.
For New Entrants and Emerging Players: Capture underconverted manual wrapping operations in Indian logistics hubs around Maharashtra and Karnataka, where cold chain infrastructure investments outpace automated film supply. Target breathable stretch film formulations for perishable palletization as the most penetrable segment. Pursue white-label manufacturing partnerships with European distributors seeking additive-free certifications under REACH restrictions.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier blown film specialists with gauge control expertise because extrusion technician scarcity in Düsseldorf and Hamburg clusters creates capability premiums. Five-to-ten-year viability hinges on chemical recycling infrastructure scaling. Watch pyrolysis facility commissioning announcements in Belgium and the Netherlands as inflection indicators for circular content supply security.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Circular Resin | Secures qualified feedstock for EU Packaging and Packaging Waste Regulation compliance without clarity degradation. |
| Nanolayer Coextrusion Capacity Addition | Unifies puncture resistance and optical clarity for Benelux frozen food distributors requiring retail-facing palletization. |
| Chemical Recycling Partnership | Enables food-grade recycled content claims that command premium positioning against mechanical recycling limitations. |
| Pre-stretched Film Format Expansion | Captures sustainability-focused procurement teams seeking material consumption reduction per pallet load. |
| Direct Logistics Provider Contracting | Locks out regional distributors as DHL Supply Chain and XPO Logistics consolidate multi-site purchasing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blown film plant managers, procurement leads at beverage distributors, technical R&D directors at resin suppliers, and warehouse operations heads at third-party logistics providers with secondary validation from customs trade data, SEC filings of packaging converters, EU regulatory submissions, and ASTM performance standard documentation. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures.
Segment-weighting across product type, material grade, end-use industry, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating automation penetration rates and recycled content mandate phase-in schedules. Industry-specific inputs included metallocene catalyst adoption curves and pre-stretched film conversion ratios in European distribution networks.
Ethylene price volatility, chemical recycling facility commissioning delays, and extended producer responsibility fee structure variations across German federal states are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market