
 Flexible Detergent Packaging Market | 2026-2036
Flexible Detergent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Detergent Packaging Market Foresight
The EU Green Deal is shifting material sourcing priorities across European detergent packaging supply chains, forcing converters to certify recycled content thresholds. Amcor plc leverages its global film manufacturing network to supply laminated pouches with verified post-consumer resin streams. Mondi Group anchors Central European production through integrated kraft paper and barrier film operations. Berry Global Inc. competes in North American refill pack segments through blown film capacity scaled for high-output detergent customers.
Flexible detergent packaging comprises multi-layer polymer films, aluminum foil laminates, and emerging biodegradable substrates engineered to contain liquid, powder, and single-dose formulations while resisting moisture ingress and chemical permeation. Pouches and refill packs command the largest volume share as brands pursue source reduction and e-commerce-compatible formats that minimize dimensional weight. Biodegradable films represent the fastest-expanding material category, though polyethylene laminates retain margin concentration due to established conversion economics and printability. Household detergents drive the dominant application share, with industrial cleaners presenting higher barrier specification requirements that sustain premium pricing tiers.
The EPA regulates volatile organic compound emissions from adhesive lamination processes in US-based flexible packaging conversion, while REACH restricts phthalate plasticizers and specific solvent chemistries across European supply chains. India's BIS enforces migration limits for food-contact-grade films that parallel detergent packaging safety benchmarks, creating compliance overlap for multi-use converters. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content verification protocols as these mechanisms increasingly determine market access and customer qualification criteria.
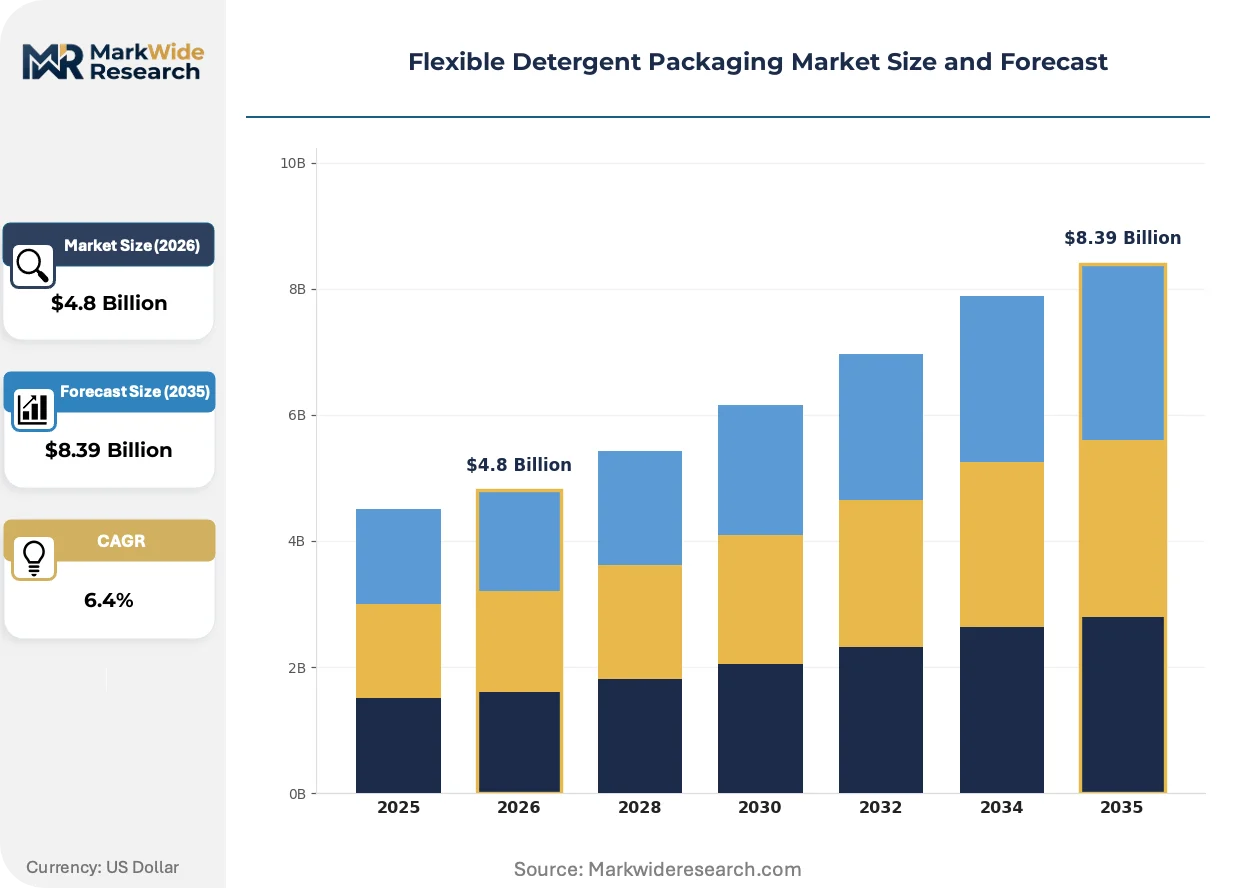
Market Dynamics
Post-consumer recycled content mandates are compressing raw material availability while forcing converters to requalify entire film formulations, creating a supply bottleneck that favors integrated resin producers with verified circular streams.
Growth Catalysts
- EU Green Deal recycled content thresholds:Packaging converters across Germany, France, and Italy must certify 30% post-consumer resin in flexible films, pulling demand toward approved recyclers with EFSA-compliant wash streams.
- Single-dose pod penetration:Urban households in Mumbai, Bangalore, and Delhi NCR are substituting loose powder with pre-measured pods, requiring high-barrier water-soluble film laminates that command premium conversion economics.
- Water-soluble PVA film technology:Dissolvable pod housings eliminate secondary packaging and reduce shipping weights by 60% versus rigid bottles, rewriting fulfillment cost structures for e-commerce detergent channels.
Market Restraints
- Multi-layer film recyclability:Polyethylene-nylon-EVOH laminates used in refill pouches lack mechanical recycling pathways, exposing brands to extended producer responsibility fees under France's Citeo scheme and Italy's CONAI framework.
- Aluminum foil price volatility:High-barrier detergent pouches depend on foil laminates subject to LME aluminum swings and energy-intensive smelting constraints in China and Russia.
- Competing rigid formats:Post-consumer recycled HDPE bottles from Unilever and Henkel's self-manufacturing units retain shelf presence in European mass retail, limiting flexible pouch slot expansion.
Strategic Opportunities
- Rural India sachet upgrade:Unbranded 5-rupee detergent sachets dominate village retail; organized trade expansion into tier-three cities creates pull for printed laminated pouches with tamper-evident features.
- Industrial cleaner concentrate packs:Hospitality and food service sectors in the US and Germany are adopting high-strength refill pouches that dilute at point-of-use, reducing transport volumes and storage footprints.
- Biodegradable substrate convergence:PLA-PBAT blends and cellulose-based films are achieving moisture barriers sufficient for powder detergents, opening regulatory tailwinds under Italy's plastic tax exemptions for compostable packaging.
Industry Challenges
- Migration testing complexity:India's BIS and the EU's REACH impose overlapping additive and solvent restrictions on food-contact-grade films that converters must duplicate for detergent applications, extending qualification timelines by 8-14 months.
- Legacy filling line retrofit costs:Powder detergent plants built for rigid bottle formats require volumetric pouch filling systems with nitrogen flush capabilities, demanding capital outlays that strain mid-tier contract packagers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Detergent Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Pouches, Sachets, Bags, Wraps, Refill Packs Material: Polyethylene, Polypropylene, Aluminum Foil, Laminates, Biodegradable Films Application: Household Detergents, Industrial Cleaners, Laundry Bars, Dishwashing Liquids, Automotive Cleaners End User: Manufacturers, Distributors, Retailers, Wholesalers, Private Label Brands |
| Companies Covered | Amcor plc, Mondi Group, Berry Global Inc., Sealed Air Corporation, Huhtamaki Oyj, Sonoco Products Company, Constantia Flexibles Group GmbH, Coveris Holdings S.A., ProAmpac LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Detergent Packaging Market Shifts & Advancements
Flexible detergent packaging is undergoing material substitution and format convergence as sustainability mandates collide with e-commerce logistics requirements, producing hybrid structures that balance barrier performance with end-of-life credentials.
Water-soluble polyvinyl alcohol films engineered for single-dose pods are rewriting unit-dose manufacturing economics. Procter & Gamble and Reckitt Benckiser have converted European and North American liquid detergent lines to pod-dominant output. The technology is compressing secondary packaging requirements and enabling direct-to-consumer subscription formats that bypass traditional retail slotting fees.
REACH restrictions on phthalate plasticizers and specific solvent adhesives are forcing European converters to validate water-based lamination chemistries. Industrial consequence includes reduced line speeds and higher energy consumption for drying stages. Germany's detergent packaging supply chain is responding through collaborative testing consortia led by Fraunhofer institutes to qualify compliant barrier structures without aluminum foil.
E-commerce fulfillment specifications are reshaping primary packaging design priorities. Amazon's Frustration-Free Packaging guidelines and similar standards from German retailers Otto and Zalando are displacing glossy multi-color gravure prints with matte flexography and reduced ink coverage. Urban Indian consumers receiving detergent via Flipkart and BigBasket now expect stand-up pouches with resealable zippers that survive last-mile handling, a specification rarely demanded in traditional kirana store channels.
Flexible Detergent Packaging Market Segmentation
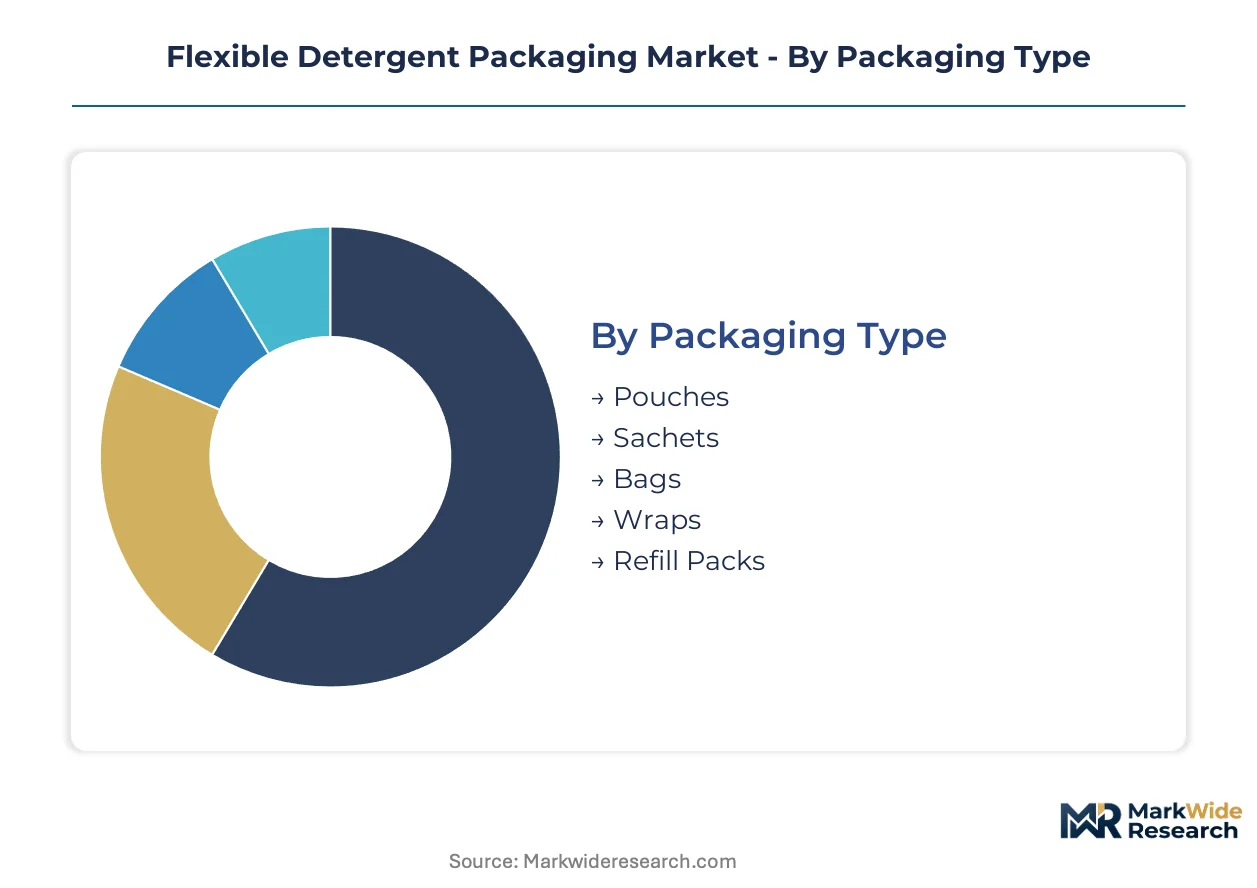
Flexible detergent packaging segmentation reveals how format, material, and channel choices cascade through supply chains. Each dimension carries distinct conversion economics and regulatory exposure that shape converter qualification requirements.
Packaging Type:
Standalone formats dominate high-volume detergent applications while embedded systems serve niche dispensing configurations.
- Pouches:Stand-up and flat pouches combine multi-layer barrier films with resealable zipper closures for liquid and powder detergents. Demand clusters in Indian tier-two cities where organized retail expansion replaces loose powder with branded pouch formats.
- Sachets:Single-use laminated film packets contain pre-measured detergent doses for price-sensitive consumers. Rural India absorbs billions of 5-rupee sachets annually through kirana stores, though environmental levies under extended producer responsibility frameworks are compressing margins.
- Bags:Gusseted and pillow bags handle bulk institutional detergent shipments with lower unit costs than rigid containers. Commercial laundries in Germany and hospitality sectors in the US specify high-capacity bags with tear-resistant seals.
- Wraps:Flow-wrapped films encase laundry bars and solid detergent blocks for moisture protection. African and Southeast Asian markets sustain wrap demand where bar formats retain household penetration.
- Refill Packs:Spouted pouches enable bottle reuse programs that brands deploy to meet EU Green Deal source-reduction targets. French and Italian consumers encounter refill stations in mass retail where Citeo and CONAI fees penalize single-use rigid packaging.
Volume placements concentrate in pouches; the faster expansion belongs to refill packs.
Material:
Cost tiers separate commodity polymers from certified circular and biodegradable alternatives that command qualification premiums.
- Polyethylene:LDPE and LLDPE films provide cost-efficient sealing layers and outer print substrates for detergent pouches. European converters face EFSA-compliant recycled content mandates that restrict virgin PE sourcing.
- Polypropylene:Biaxially oriented PP delivers stiffness and clarity for windowed detergent packaging with premium shelf presence. Italian converters favor cast PP for high-speed form-fill-seal lines serving private label brands.
- Aluminum Foil:6-12 micron foil laminates create absolute moisture and gas barriers for powder detergent shelf-life extension. LME price volatility and energy-intensive smelting in China and Russia transmit cost shocks through converter quotations.
- Laminates:Coextruded and adhesive-laminated multi-layer structures combine PE, nylon, and EVOH for tailored barrier performance. REACH solvent restrictions force German converters toward water-based adhesive systems with reduced line speeds.
- Biodegradable Films:PLA-PBAT blends and cellulose-based substrates achieve compostability certification under Italy's plastic tax exemption scheme. Industrial cleaner brands in Germany pilot biodegradable pouches for closed-loop hospitality supply chains.
Polyethylene laminates anchor volume placements; biodegradable films are climbing the fastest as regulatory tailwinds strengthen.
Application:
Customer type segmentation distinguishes mass-market household consumption from specification-intensive industrial procurement.
- Household Detergents:Laundry liquids, powders, and pods in flexible formats serve daily consumer cleaning routines. Indian e-commerce platforms Flipkart and BigBasket specify stand-up pouches with resealable zippers for last-mile durability.
- Industrial Cleaners:Concentrated formulations for food service, healthcare, and manufacturing demand higher chemical resistance and puncture strength. German hospitality suppliers specify refill pouches that dilute at point-of-use to reduce transport volumes.
- Laundry Bars:Solid detergent blocks in flow-wrap packaging persist in African, South Asian, and Latin American markets where water access constraints favor low-foam formats.
- Dishwashing Liquids:Viscous formulations require spouted pouches with controlled dispensing and drip-free closures. US mass retail channels display dishwashing refills adjacent to primary bottles to capture brand-loyal replenishment.
- Automotive Cleaners:Solvent-based degreasers and wash formulations demand specialized barrier films resistant to hydrocarbon permeation. Professional detailing shops in the US and Germany purchase bulk flexible packs with chemical-resistant fittings.
Household detergents capture volume placements; industrial cleaners sustain the steepest expansion trajectory as concentrate formats penetrate commercial channels.
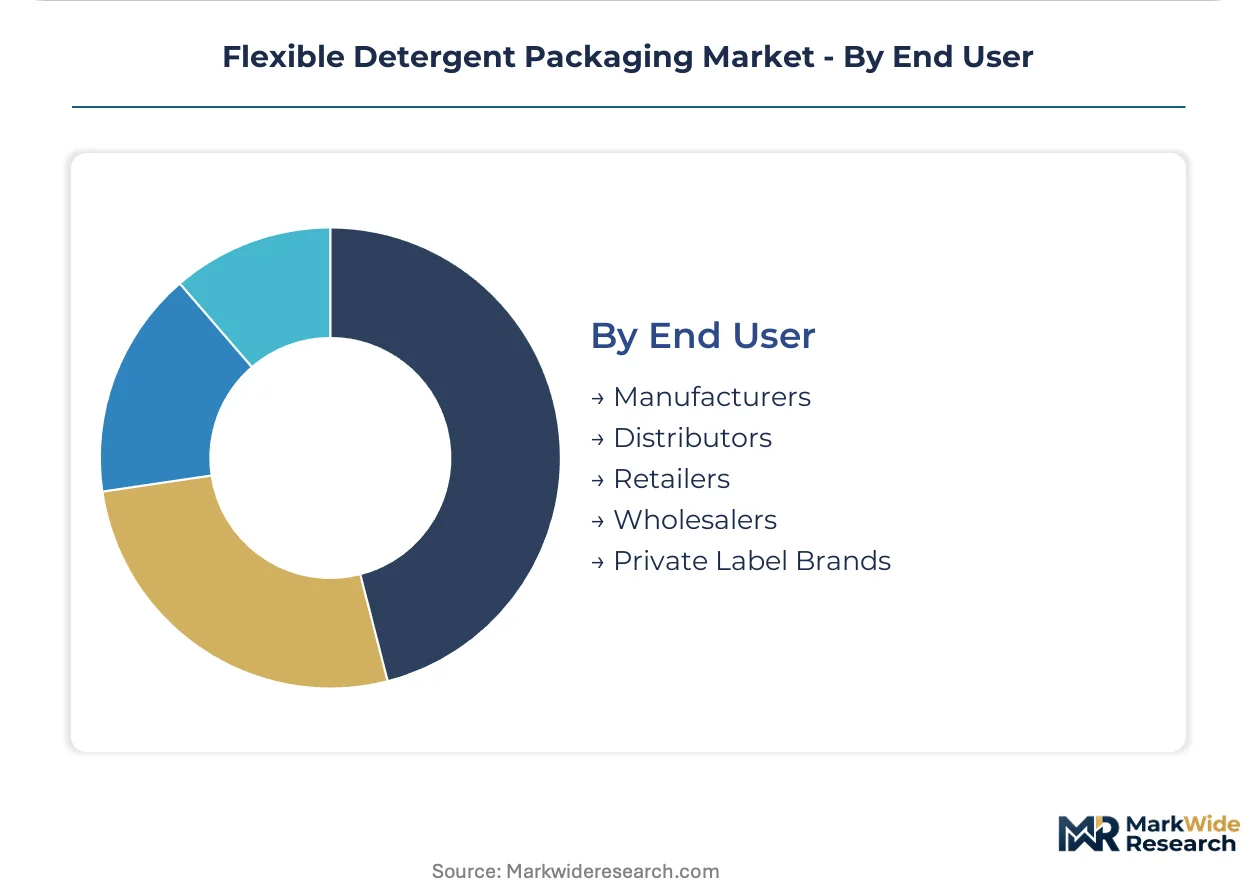
End User:
Supply concentration varies across converter-direct manufacturer relationships versus fragmented retail and wholesale distribution.
- Manufacturers:Procter & Gamble, Unilever, and Reckitt Benckiser operate captive packaging specifications with approved converter lists. These stakeholders drive material innovation through collaborative development agreements for water-soluble pod films.
- Distributors:Regional logistics operators aggregate detergent packaging from multiple converters for brand portfolio consolidation. Indian distributors manage sachet-to-pouch format transitions as rural trade modernizes.
- Retailers:Mass merchants and e-commerce platforms impose packaging specifications that include Amazon Frustration-Free guidelines and German retailer sustainability scorecards.
- Wholesalers:Cash-and-carry operators supply independent retailers with unbranded or private label detergent in basic pouch formats. Price pressure limits material specification to commodity PE laminates.
- Private Label Brands:Retailer-owned detergent lines source flexible packaging through competitive tender processes that prioritize cost over barrier performance. German discounters Aldi and Lidl specifications shape Central European converter output.
Manufacturers anchor volume placements; private label brands are gaining share fastest as retail consolidation accelerates specification standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors flexible detergent packaging demand through its dense network of contract packagers serving Unilever and Reckitt Benckiser's Indian operations, while the city's port infrastructure enables resin imports that feed Maharashtra's converting cluster.
United States
EPA regulations on volatile organic compound emissions from adhesive lamination processes shape converter operations across the Midwest and Southeast. E-commerce fulfillment specifications from Amazon and Walmart are displacing traditional gravure printing with reduced-ink flexography. Chicago-area converters supply spouted refill pouches for Procter & Gamble's direct-to-consumer subscription channels.
Germany
REACH restrictions on phthalate plasticizers and solvent chemistries force validation of water-based lamination systems. Fraunhofer institutes coordinate industry consortia to qualify aluminum-foil-free barrier structures. The Rhine-Main corridor hosts integrated film producers supplying laminated pouches with verified post-consumer resin streams to Henkel's Düsseldorf operations.
India
BIS migration limits for food-contact-grade films create compliance overlap for multi-use converters serving detergent applications. Organized retail expansion into Bangalore and Delhi NCR accelerates pouch adoption in tier-two cities. Gujarat's petrochemical corridor supplies virgin PE and PP resins to converters in Ahmedabad and Surat producing printed laminated pouches.
France
Citeo extended producer responsibility fees penalize multi-layer film formats lacking mechanical recycling pathways. Mass retail refill stations in Paris and Lyon deploy spouted pouches to meet EU Green Deal source-reduction targets. The Lyon region concentrates blown film capacity serving private label detergent brands for Carrefour and Auchan.
Italy
CONAI framework levies and plastic tax exemptions for compostable packaging drive biodegradable film pilot programs. Cast PP production in Lombardy serves high-speed form-fill-seal lines for private label brands. Bologna-area converters test PLA-PBAT blend pouches for industrial cleaner concentrate packs targeting closed-loop hospitality supply chains.
Flexible Detergent Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification tiers, with integrated resin producers commanding qualification premiums over toll converters dependent on spot resin markets. The vendor base spans global film manufacturers with captive polymer operations, regional converters serving single-country brand portfolios, and specialized water-soluble film developers. Three archetypes dominate: integrated multinationals with verified circular resin streams, mid-tier regional specialists with flexible equipment configurations, and technology-focused developers of biodegradable substrates. Competitive moves concentrate on recycled content certification partnerships and water-based lamination capacity retrofits.
Among integrated multinationals, Amcor plc and Mondi Group exemplify the premium-tier archetype through global film manufacturing networks and integrated kraft paper operations. Berry Global Inc. occupies a position within the North American refill pack segment. These three entities anchor the competitive structure by representing distinct geographic and capability specializations—Australian-registered Amcor with laminated pouch supply chains, Austrian-anchored Mondi with Central European production integration, and US-incorporated Berry with blown film capacity scaled for high-output detergent customers.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Berry Global Inc. |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Constantia Flexibles Group GmbH |
| Coveris Holdings S.A. |
| ProAmpac LLC |
| Others |
Supply & Pricing Matrix
EU Green Deal recycled content thresholds gate qualified supply access and premium-tier pricing power for detergent packaging converters across Germany, France, and Italy. Brands without EFSA-compliant resin streams face exclusion from mass retail procurement lists, compressing margins for toll-dependent operators while integrated producers capture qualification premiums.
Pricing Analysis
Barrier performance throughput anchors value-based pricing tiers in detergent flexible packaging. Three-tier pricing structure across premium, standard, and economy levels separates water-soluble pod films with nitrogen flush compatibility from commodity PE laminates and unprinted sachet substrates. Certification investment for REACH-compliant solvent-free adhesives is forcing cost compression in mid-tier European supply chains. Private label brands at German discounters exhibit highest price sensitivity; P&G and Unilever captive specifications tolerate premium barrier investments.
Supply Chain Analysis
Freight cost differentials between resin import routes through Rotterdam and Mumbai reshape converter location economics for detergent pouch supply. Raw material supply concentrates in China for PVA water-soluble films, Saudi Arabia for virgin PE feedstocks, and Germany for specialty adhesive chemistries. LME aluminum volatility from energy-intensive Russian and Chinese smelting transmits price shocks through high-barrier foil laminate quotations. Distribution runs through brand-direct converter relationships for multinational detergent manufacturers, with spot-market toll converters serving fragmented Indian private label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU extended producer responsibility fee structures are compressing weaker converters without verified circular resin streams, accelerating consolidation toward integrated multinationals with EFSA-compliant wash stream partnerships.
For Market Incumbents: Deploy water-based lamination capacity retrofits to preempt REACH solvent restriction enforcement across German and French supply chains. Capture recycled content certification partnerships with approved European recyclers to defend against emerging Asian competitors with virgin-only resin access. Prioritize nitrogen-flush pouch filling line integration in India to serve Unilever and Reckitt Benckiser's organized retail expansion. For New Entrants and Emerging Players: Compostable film technology for Italy's plastic tax exemption segment offers lowest competitive density among European sustainability mandates. Target rural India's tier-three city sachet-to-pouch upgrade corridor where organized trade penetration lags branded format adoption. Pursue hospitality sector closed-loop supply chain pilots for industrial cleaner concentrate packs as the entry wedge. For Investors and Strategic Acquirers: First-mover water-soluble film patent filings in India are the leading indicator that pod format penetration is approaching inflection velocity. Mid-tier European converters with stranded solvent-based lamination assets face stranded capacity risk over the medium-term horizon. Acquisition candidates center on regional Indian converters with BIS-certified multi-use film capacity and established Unilever supply relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Lamination Retrofit | REACH solvent restrictions in Germany force line-speed trade-offs for compliant barrier structures. |
| Recycled Content Certification Partnership | EFSA-compliant resin streams unlock EU Green Deal procurement access for premium-tier converters. |
| Rural India Pouch Conversion Program | Tier-three city organized retail expansion displaces unbranded sachet formats with printed laminates. |
| Compostable Film Pilot Scale-Up | Italy's plastic tax exemptions for certified compostable packaging create regulatory tailwinds. |
| Direct-to-Consumer Subscription Format | Amazon Frustration-Free guidelines reshape primary packaging design for e-commerce detergent channels. |
Research Methodology
Multi-period observation of resin price volatility, converter capacity utilization, and regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with flexible packaging plant managers, detergent brand procurement leads, polymer resin traders, and retail category buyers. Secondary validation drew from ECHA REACH substance restriction updates, BIS food-contact migration limit notifications, EU Green Deal implementation guidance, and customs trade data for PE and PP resin flows. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
Input-output matrices mapped detergent packaging demand across format type, barrier specification tier, and regional regulatory cluster to generate volume and value projections. Modeled segmentation spanned packaging format, material substrate, application intensity, and end-user procurement archetype. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce penetration rates and sustainability mandate compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike scenarios or accelerated biodegradable substrate substitution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market