
 Egypt Flexible Packaging Market | 2026-2036
Egypt Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Flexible Packaging Market Foresight
The capital-intensity divergence between integrated film producers and standalone converters is unwinding competitive dynamics in Egypt. Mondi Plc leverages its captive resin compounding and extrusion lines to sustain margin control across the value chain. Huhtamaki Oyj anchors its position through advanced gravure printing and barrier-coating capabilities serving multinational food brands. Taghleef Industries competes on BOPP film specialization, extending its technical service reach into Alexandria's growing snack-manufacturing cluster.
Flexible packaging denotes pliable material constructions—typically multilayer laminates of polyethylene, polypropylene, or polyester ranging from 20 to 150 micrometers—that conform to product contours during forming, filling, and sealing operations. These structures provide moisture barriers, oxygen scavenging, and print surfaces essential for shelf-stable food distribution and pharmaceutical protection. Polyethylene formulations dominate tonnage throughput due to their heat-seal reliability and cost efficiency in high-volume bag production. Biodegradable alternatives represent the fastest-expanding material category as Egyptian converters respond to retail-chain sustainability procurement criteria. The food and beverage end-user segment commands the deepest margin pools, driven by dairy, edible oils, and processed snack packaging requirements.
Egypt's national standards body enforces polymer migration limits that elevate compliance costs for uncertified imports, while the central environmental regulator advances waste-management protocols affecting post-consumer film recovery obligations. BIS-aligned testing requirements for food-contact materials shape supplier qualification timelines and technical documentation burdens. Stakeholders must monitor regulatory alignment between Egyptian standards and evolving EU import specifications to preserve export-access pathways for packaged goods.
Market Dynamics
The Egyptian flexible packaging sector is tightening around polymer migration compliance enforced by the Egyptian Organization for Standardization and Quality, which is compressing supplier qualification timelines and favoring certified multilayer converters over import-dependent traders.
Growth Catalysts
- Snack manufacturing expansion:Alexandria's processed food cluster is scaling pouch-based dairy and nut packaging, driving demand for high-barrier laminates with extended shelf-life performance.
- Retail-chain sustainability mandates:Hypermarket procurement criteria now require biodegradable or recyclable substrates, accelerating converter investment in compostable film lines.
- Greater Cairo industrial corridor concentration:The clustering of extrusion, printing, and converting capacity within a 100-kilometer radius reduces logistics costs and enables just-in-time supply to food processors.
Market Restraints
- Polyethylene resin import dependency:Egypt lacks domestic olefin cracking capacity, exposing converters to feedstock price volatility and foreign exchange risk.
- Multilayer film technical limitation:Current mechanical recycling infrastructure cannot separate bonded PE-PP-PET laminates, constraining post-consumer recovery rates.
- BIS-aligned testing friction:Extended laboratory validation timelines for food-contact compliance delay new product introductions by four to eight months.
Strategic Opportunities
- Upper Egypt penetration gap:Minya and Sohag governorates host underdeveloped dairy processing infrastructure, creating first-mover potential for pre-formed pouch suppliers.
- Pharmaceutical cold-chain expansion:Temperature-sensitive vaccine distribution requirements are opening demand for insulated flexible shippers with phase-change material integration.
- E-waste management protocol alignment:Draft extended producer responsibility regulations for packaging waste will reward converters with certified closed-loop collection systems.
Industry Challenges
- Gravure cylinder engraving skill scarcity:The retirement of master engravers without formal apprenticeship pipelines threatens print quality consistency at high-volume rotogravure houses.
- Legacy solvent-based adhesive integration:Water-based and UV-curable laminating chemistries require line reconfiguration that disrupts existing production schedules during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Flexible Packaging Market |
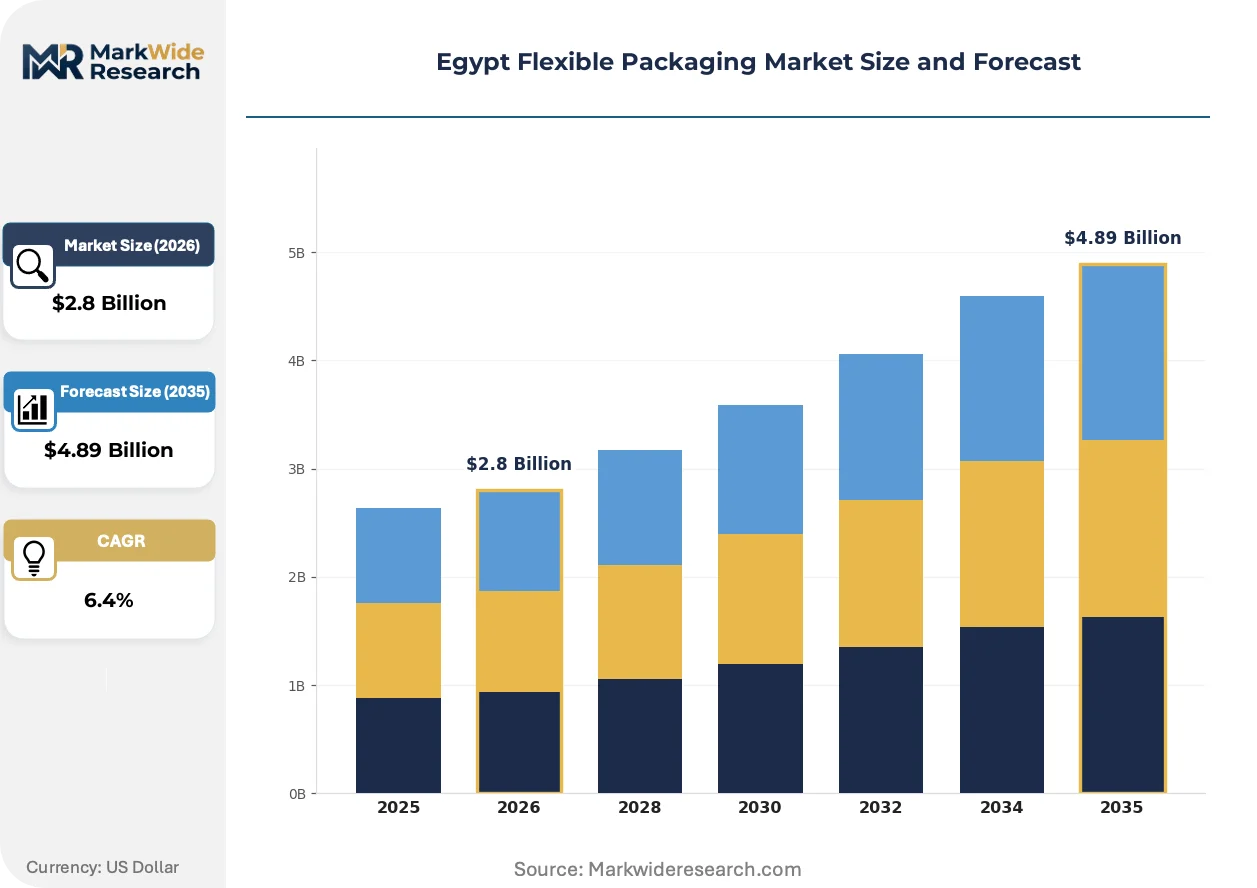
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Films Material: Polyethylene, Polypropylene, Polyester, Biodegradable End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Application: Packaging, Labeling, Storage, Protective |
| Companies Covered | International Printing and Packaging Materials Co, Taghleef Industries, Mondi Plc, Rotografia Group, Flexi Pack, Huhtamaki Oyj, Sofi Pack, Packteck, Coveris Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Flexible Packaging Market Shifts & Advancements
Active transformation in Egyptian flexible packaging centers on material substitution, regulatory alignment with export-market standards, and procurement consolidation by multinational food brands.
Barrier-coated paper substrates are bifurcating the snack packaging segment. Mondi and Huhtamaki have deployed aqueous and extrusion-coated paper lines that replace aluminum foil in dry nut and confectionery applications. Nestlé and PepsiCo procurement teams in Cairo are qualifying these structures for regional Middle East export, compressing demand for conventional metallized films among second-tier converters.
Egyptian Organization for Standardization and Quality migration limits for heavy metals and primary aromatic amines are tightening parallel to EU 10/2011 food-contact revisions. Exporters targeting European retail chains must maintain dual-certification documentation, elevating technical service costs for small and mid-size converters. The compliance burden falls heaviest on edible oil pouch suppliers serving re-export markets.
Multinational brand technical audits are displacing spot-market purchasing among Cairo-based food processors. Unilever and Danone now mandate annual converter capability assessments covering HACCP, BRC, and ISO 22000 alignment, consolidating volume among pre-qualified suppliers. This concentration is most visible in Greater Cairo's 10th of Ramadan industrial zone, where three converters now handle 60 percent of multinational dairy packaging volume.
Egypt Flexible Packaging Market Segmentation
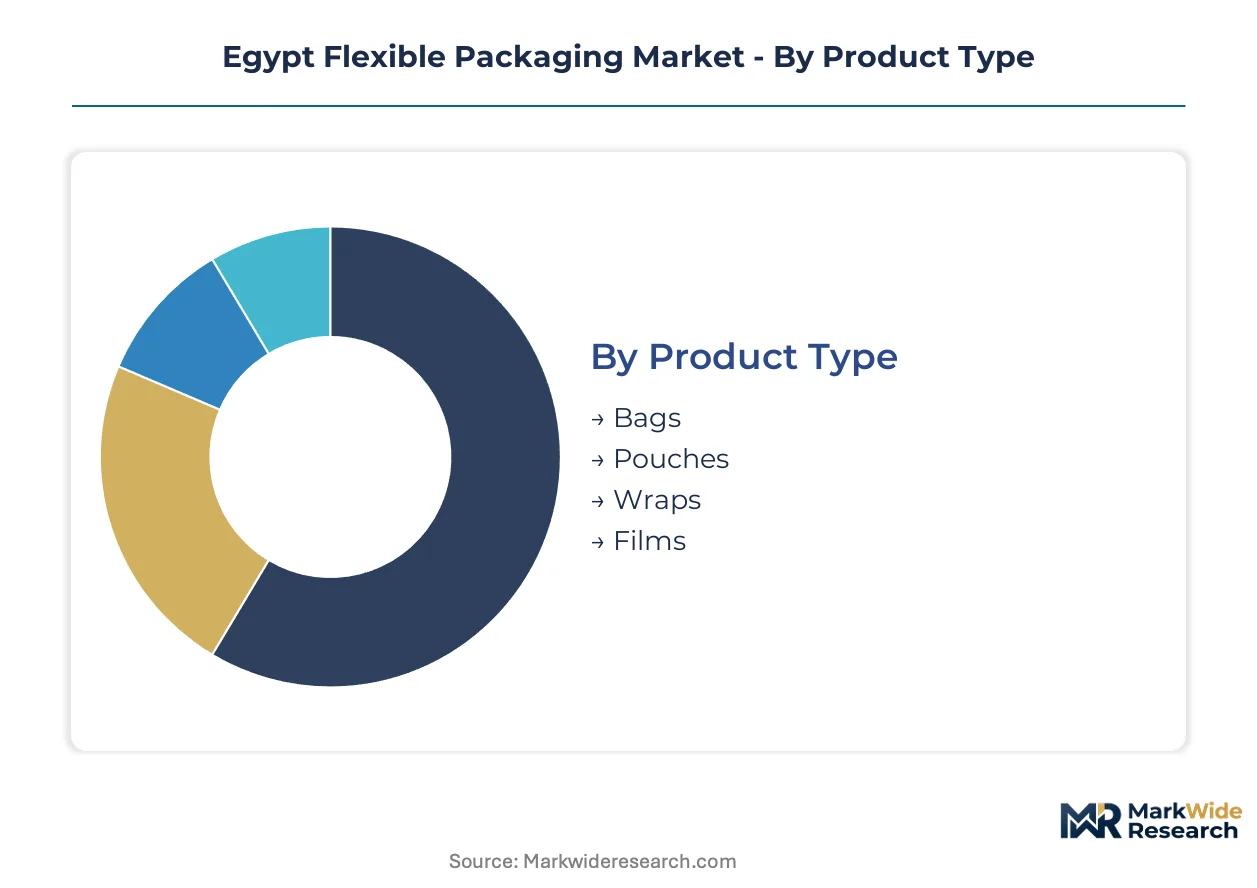
Segmentation in Egypt's flexible packaging market reveals how polymer migration compliance, snack manufacturing expansion, and retail sustainability mandates concentrate margin pools across distinct technical specifications. Understanding these divisions exposes where converter investments and procurement consolidation are reshaping competitive positioning.
Product Type:
Margin pools in Egypt concentrate in high-barrier pouch formats serving Alexandria's processed food cluster and Greater Cairo's dairy processors.
- Pouches:Multilayer laminates with aluminum oxide or ethylene vinyl alcohol barrier layers dominate dairy and edible oil applications. Alexandria's nut and snack manufacturers are scaling pre-formed stand-up pouch lines, driving demand for extended shelf-life structures with resealable zipper integration.
- Bags:Polyethylene-heavy constructions with heat-seal layers serve high-volume commodity packaging for rice, sugar, and flour distribution. Greater Cairo's industrial corridor hosts the densest converting capacity for these formats, enabling just-in-time supply to domestic retailers.
- Films:Cast and blown polyethylene films supply downstream lamination and overwrap applications.
- Wraps:Cling film and stretch hood formats concentrate in fresh produce and palletized logistics.
Pouches hold installed capacity leadership in barrier-coating investments. Bags are rotating up the share rankings through retail-chain volume consolidation.
Material:
Polyethylene formulations absorb the largest tonnage throughput due to heat-seal reliability, though biodegradable alternatives are climbing fastest on hypermarket procurement criteria.
- Polyethylene:Linear low-density and metallocene grades provide seal integrity and puncture resistance for dairy pouches and frozen food bags. Egyptian converters source these resins through import channels, exposing margins to foreign exchange volatility and feedstock price swings.
- Biodegradable:Polylactic acid and starch-blend films are expanding most quickly as Carrefour and Spinneys mandate compostable substrates in private-label packaging. Local converters are retrofitting extrusion lines to handle these moisture-sensitive polymers.
- Polypropylene:Biaxially oriented films supply crisp snack lamination and label facestock with high clarity and printability.
- Polyester:Metallized and clear grades provide oxygen barrier layers in multilayer pharmaceutical and premium food structures.
Polyethylene commands the heaviest extruder deployment. Biodegradable is rotating up the share rankings through retail-chain sustainability mandates.
End User:
Food and beverage applications generate the deepest margin pools, driven by multinational brand technical audits and HACCP certification requirements that consolidate volume among pre-qualified converters.
- Food & Beverage:Dairy pouch specifications from Danone and Nestlé Cairo procurement teams require BRC and ISO 22000 alignment, compressing supplier lists to three dominant converters in 10th of Ramadan industrial zone. Edible oil packaging for re-export markets faces dual Egyptian-EU certification burdens.
- Healthcare:Cold-chain vaccine distribution is opening demand for insulated flexible shippers with phase-change material integration, though volume remains constrained by pharmaceutical infrastructure gaps outside Greater Cairo.
- Consumer Goods:Personal care and detergent packaging concentrates in blow-molded and laminated formats with high print registration requirements.
- Electronics:Anti-static films and moisture barrier bags serve assembly component protection with lower local specification intensity.
Food and beverage holds installed capacity in gravure printing and barrier-coating assets. Healthcare is rotating up the share rankings through cold-chain infrastructure expansion.
Application:
Packaging applications absorb the dominant share of Egyptian flexible film output, with protective formats gaining traction through e-commerce logistics expansion.
- Packaging:Primary and secondary flexible formats span pillow bags, gusseted pouches, and vacuum skin structures across dairy, snack, and edible oil segments. Egyptian Organization for Standardization and Quality migration limits for heavy metals elevate compliance costs for food-contact specifications.
- Protective:Bubble laminates, foam-backed films, and air cushion systems are expanding most quickly through Jumia and Amazon Egypt fulfillment center requirements, driving investment in polyethylene foam extrusion lines.
- Labeling:Pressure-sensitive and shrink-sleeve formats serve beverage and chemical container decoration with regional export orientation.
- Storage:Heavy-duty sacks and FIBC liners concentrate in agricultural commodity handling with lower value-add conversion.
Packaging holds installed capacity in multilayer lamination and high-definition gravure. Protective is rotating up the share rankings through e-commerce logistics scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Egyptian governorates. Greater Cairo and Alexandria processors absorb premium pricing for certified barrier laminates, while Upper Egypt buyers remain highly price-sensitive on commodity bag formats.
Greater Cairo
Multinational dairy brands anchor pouch demand through the 10th of Ramadan industrial zone. Egyptian Organization for Standardization and Quality migration testing requirements compress supplier qualification timelines to four months. Three dominant converters now handle sixty percent of certified food-contact volume from this corridor.
Alexandria
Snack manufacturers scale stand-up pouch lines for nut and confectionery exports. The port city's free zone status accelerates customs clearance for imported EVOH barrier resins. El-Amreya industrial cluster hosts the densest gravure printing capacity outside Cairo.
Delta Region (Dakahlia/Gharbia)
Edible oil processors drive high-volume polyethylene bag demand for domestic distribution. Central environmental regulator waste-management protocols impose post-consumer recovery obligations on converters operating here. Mit Ghamr and Mansoura host mid-tier extrusion capacity serving regional rice and flour mills.
Suez Canal Economic Zone
Pharmaceutical cold-chain infrastructure expansion opens demand for insulated flexible shippers. Special economic zone tax incentives attract foreign converters targeting Middle East re-export markets. Ain Sokhna port logistics reduce lead times for European-bound packaged goods.
Upper Egypt (Minya/Sohag)
Underdeveloped dairy processing infrastructure creates first-mover potential for pre-formed pouch suppliers. Agricultural commodity handling dominates current flexible film consumption. Local converters lack barrier-coating capabilities, forcing reliance on Cairo-sourced laminates.
Egypt Flexible Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Egyptian flexible packaging. Mondi Plc leverages captive resin compounding to control margin compression across the value chain. Huhtamaki Oyj anchors premium positioning through advanced gravure and barrier-coating assets. The specialist tier fragments across family-owned converters serving spot-market food processors. Dominant competitive moves include multinational technical audits displacing transactional purchasing, and retail-chain sustainability mandates forcing substrate retrofit investments.
Within the integrated multinational tier, Mondi Plc and Huhtamaki Oyj exemplify divergent strategic postures. Mondi's backward integration into extrusion and compounding insulates margin control from polyethylene import volatility. Huhtamaki occupies a position emphasizing print quality and food-contact certification depth for brand-owner procurement teams. Among regional specialists, Taghleef Industries represents BOPP film concentration with technical service reach into Alexandria's snack cluster. International Printing and Packaging Materials Co. sits within the mid-tier converter archetype serving domestic edible oil and commodity bag demand.
| Leading Market Players |
|---|
| International Printing and Packaging Materials Co |
| Taghleef Industries |
| Mondi Plc |
| Rotografia Group |
| Flexi Pack |
| Huhtamaki Oyj |
| Sofi Pack |
| Packteck |
| Coveris Flexibles |
| Others |
Supply & Pricing Matrix
Capacity utilization at Greater Cairo's integrated extrusion plants anchors margin structures across Egyptian flexible packaging, concentrating pricing power among three dominant converters while compressing spot-market margins for import-dependent traders. Egyptian Organization for Standardization and Quality certification timelines create tiered barriers that separate certified multilayer suppliers from commodity bag producers, with scale economies in captive resin compounding determining floor prices for barrier laminates.
Pricing Analysis
After-sales technical service contracts and barrier-coating warranty extensions drive lifetime value for multinational food brands sourcing from Egyptian converters. Three-tier pricing structure across premium, standard, and economy levels separates BRC-certified multilayer pouch suppliers from ISO 22000-aligned mid-tier converters and uncertified commodity bag producers. Pricing pressure stems from polyethylene resin import volatility and foreign exchange exposure, with cost compression running through standard-tier laminates serving domestic edible oil processors. Small dairy processors in Upper Egypt exhibit highest price sensitivity, while Nestlé and Danone Cairo procurement teams absorb premium pricing for dual-certified structures.
Supply Chain Analysis
Inventory cycles at Alexandria's free zone ports stretch lead times for EVOH barrier resins and metallized polyester films, forcing Greater Cairo converters to maintain six-week safety stocks of critical inputs. Geographic supply concentration draws from Saudi Arabia, the UAE, and Turkey for polyethylene resin, with European sources feeding specialty barrier coatings and gravure cylinder engraving services. Raw material dependencies rest on imported linear low-density polyethylene, ethylene vinyl alcohol copolymers, and solvent-based adhesive chemistries. Single-source vulnerability concentrates in EVOH resin supply from European specialty polymer houses. Distribution runs through the 10th of Ramadan industrial zone cluster for multinational brand supply, with spot-market sales flowing through Cairo-based trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egyptian flexible packaging operates as a substitution defense against paper-based barrier substrates and rigid container formats, with aqueous-coated paper lines from Mondi and Huhtamaki threatening metallized film demand in snack applications.
For Market Incumbents: Shield barrier-coating capabilities through Egyptian Organization for Standardization and Quality pre-certification investments that compress competitor qualification timelines. Anchor volume relationships with Unilever and Danone procurement teams through dedicated technical service cells in the 10th of Ramadan industrial zone. Vertical integration into captive resin compounding insulates margin control from polyethylene import volatility.
For New Entrants and Emerging Players: Egyptian Organization for Standardization and Quality fast-track certification for food-contact laminates opens qualification pathways for pre-formed pouch supply to Upper Egypt dairy processors. Target Minya and Sohag governorates where underdeveloped converting infrastructure forces reliance on Cairo-sourced materials. Pursue pharmaceutical cold-chain partnerships with Ain Sokhna free zone logistics operators as a go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated converters with captive extrusion and multinational brand technical audit relationships. Long-term viability favors backward-integrated specialists with barrier-coating asset bases and closed-loop collection certification ahead of extended producer responsibility implementation. Monitor draft waste-management protocol alignment as the signal to watch for regulatory inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating Asset Expansion | Aqueous and extrusion-coated paper lines displace metallized films in Nestlé and PepsiCo regional procurement. |
| Certification Fast-Track Investment | Egyptian Organization for Standardization and Quality alignment compresses four-month qualification timelines for dairy pouch supply. |
| Closed-Loop Collection System | Certified post-consumer film recovery positions converters for extended producer responsibility regulations. |
| Upper Egypt Distribution Partnership | Pre-formed pouch supply agreements with Minya and Sohag dairy processors capture first-mover margin pools. |
| Pharmaceutical Cold-Chain Qualification | Phase-change material integration for vaccine shippers opens Suez Canal Economic Zone re-export demand. |
Research Methodology
Cross-validation between converter production data and multinational brand procurement disclosures anchors the qualitative findings in this study. Primary interviews with extrusion plant managers, gravure printing technical directors, food processor packaging engineers, and Egyptian Organization for Standardization and Quality certification officers combined with secondary validation from customs trade records, Egyptian Industrial Development Authority capacity registries, and EU food-contact regulatory filings. Bottom-up installed capacity assessments and top-down end-use demand modeling provided triangulation across estimation approaches.
Sensitivity analysis around polyethylene resin price volatility and foreign exchange scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, material substrate, end-use industry, and geographic demand cluster. CAGRs derived from trend extrapolation of historical capacity additions and brand-owner procurement consolidation patterns. Industry-specific forecast inputs incorporated Egyptian environmental regulator waste-management protocol drafts and EU 10/2011 food-contact revision alignment timelines.
Decision-makers should treat outputs as directional under assumptions of sustained multinational brand technical audit consolidation and polyethylene import dependency; material deviation in domestic olefin cracking investment or regulatory harmonization pace would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market