
 India Flexible Packaging Market | 2026-2036
India Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Flexible Packaging Market Insights
Skilled converter workforce availability is reorganizing capacity expansion timelines across the India Flexible Packaging Market. Uflex Limited leverages its integrated film-to-pouch manufacturing footprint to dominate bulk supply contracts for domestic FMCG brands. Cosmo Films Ltd sustains technology leadership in specialty polyester films for pharmaceutical blister applications. Huhtamaki Oyj anchors premium quick-service restaurant packaging demand through its localized India operations.
India flexible packaging comprises multi-layer laminates, coextruded films, and printed substrates engineered to provide barrier protection against moisture, oxygen, and light while minimizing material weight versus rigid alternatives. These structures typically incorporate polyethylene, polypropylene, or polyester layers bonded through adhesive lamination or extrusion coating, serving primarily to extend shelf life and reduce logistics costs for consumer goods. Pouches and films command the largest share of product output, with pouches capturing premium margin pools in single-serve food and personal care formats while films underpin high-volume industrial wrapping. Biodegradable materials represent the fastest-expanding material category as brand sustainability mandates and regulatory pressure on conventional plastics intensify procurement shifts across end-user segments.
BIS certification requirements and India's Plastic Waste Management Rules shape substrate selection and recyclability claims, forcing converters to reformulate multi-layer structures or invest in mono-material compatibility. CDSCO guidelines for pharmaceutical packaging impose barrier performance and traceability standards that elevate technical entry costs for flexible formats in drug delivery. Stakeholders must monitor evolving Extended Producer Responsibility enforcement thresholds and state-level plastic bans to anticipate demand migration toward certified compostable and paper-based alternatives.
Market Dynamics
India's Plastic Waste Management Rules are forcing converters to dismantle multi-layer laminates and rebuild around mono-material or certified compostable substrates, compressing formulation timelines and elevating technical qualification costs for domestic suppliers.
Growth Catalysts
- Maharashtra-Gujarat polymer cluster concentration:Integrated film extrusion and printing infrastructure within 300 kilometers of Mumbai and Ahmedabad reduces logistics friction for FMCG procurement teams.
- FSSAI packaging safety mandates:Food-grade certification requirements for direct-contact materials are displacing informal converter capacity and consolidating volume toward BIS-accredited facilities.
- Biodegradable substrate R&D:PLA and PHA blends engineered for tropical humidity conditions are opening shelf-stable applications previously locked to conventional plastics.
Market Restraints
- Ethylene and propylene import dependence:Over 70 percent of polymer feedstock arrives via Middle East supply chains, exposing converters to rupee-dollar volatility and freight cost spikes.
- Multi-layer recyclability deadlock:Current mechanical recycling infrastructure cannot separate adhesive-bonded PET-PE-PP structures, limiting post-consumer collection economics.
- CDSCO pharmaceutical barrier standards:Blister foil oxygen transmission rate requirements below 0.5 cc/m²/day demand capital-intensive metallization equipment that sub-scale converters cannot access.
Strategic Opportunities
- Andhra Pradesh-Telangana food processing corridor:Emerging cold-chain infrastructure around Visakhapatnam and Hyderabad is generating first-mover demand for high-barrier vacuum pouches.
- Extended Producer Responsibility credit markets:PWM Rules enforcement is creating tradable compliance instruments that reward mono-material design adoption with offset revenue streams.
- Digital print-on-demand integration:HP Indigo and EFI single-pass systems converging with ERP-enabled short-run workflows are collapsing minimum order quantities for regional brand launches.
Industry Challenges
- Adhesive lamination technician scarcity:Solvent-based and solventless dry lamination expertise concentrates among aging workforces in Nashik and Vapi, constraining quality-controlled capacity expansion.
- BIS certification queue congestion:Testing laboratory backlog for migration and heavy metal compliance extends product launch timelines by four to six months for new substrate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Flexible Packaging Market |
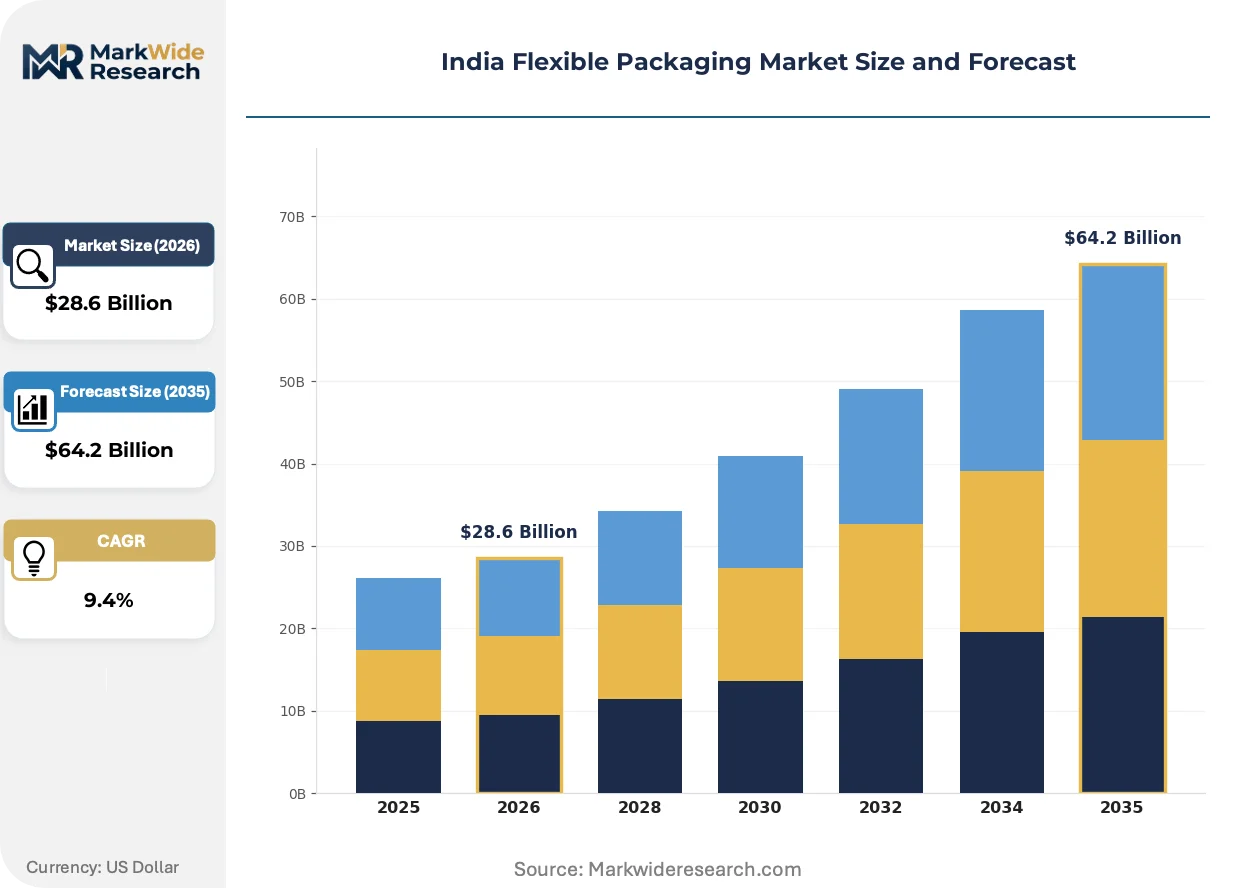
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Labels Material: Plastic, Paper, Aluminum Foil, Biodegradable End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Application: Packaging, Wrapping, Protection, Storage |
| Companies Covered | Huhtamaki Oyj, Mondi PLC, Uflex Limited, Constantia Flexibles, Cosmo Films Ltd, Amcor Plc, Berry Global Inc., Sonoco Products Company, Polyplex Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Flexible Packaging Market Trends and Innovations
Digital printing and mono-material design are converging to collapse run-length economics and recyclability certification timelines, while regulatory enforcement hardens around plastic waste accountability.
Water-based flexo and EB-cure ink systems are fragmenting solvent-based gravure dominance in snack and confectionery printing. Mid-tier FMCG brands with 50,000-200,000 unit runs are migrating to these platforms to avoid volatile organic compound compliance costs and accelerate artwork versioning. The shift is compressing pre-press lead times from two weeks to 48 hours and enabling regional flavor launches that were previously uneconomical.
India's Plastic Waste Management Rules 2022 amendments are mandating explicit recyclability labeling and EPR registration for all flexible packaging above 50 microns. Brand owners must now submit annual plastic waste collection and recycling plans to state pollution control boards, with penalties for non-compliance scaling to production halts. Pharmaceutical and personal care segments are responding fastest, reformulating blister and sachet structures around aluminum-paper or mono-PP alternatives to preserve market access.
Quick-commerce fulfillment networks are compressing packaging specification cycles from annual to quarterly reviews. Swiggy Instamart and Blinkit are demanding drop-resistant, leak-proof pouch formats with sub-gram weight targets to optimize delivery fleet payload efficiency. This behavior is most visible in Bengaluru and Delhi NCR, where 10-minute delivery density justifies custom pouch engineering investments that bypass traditional converter catalog standards.
India Flexible Packaging Market Segmentation
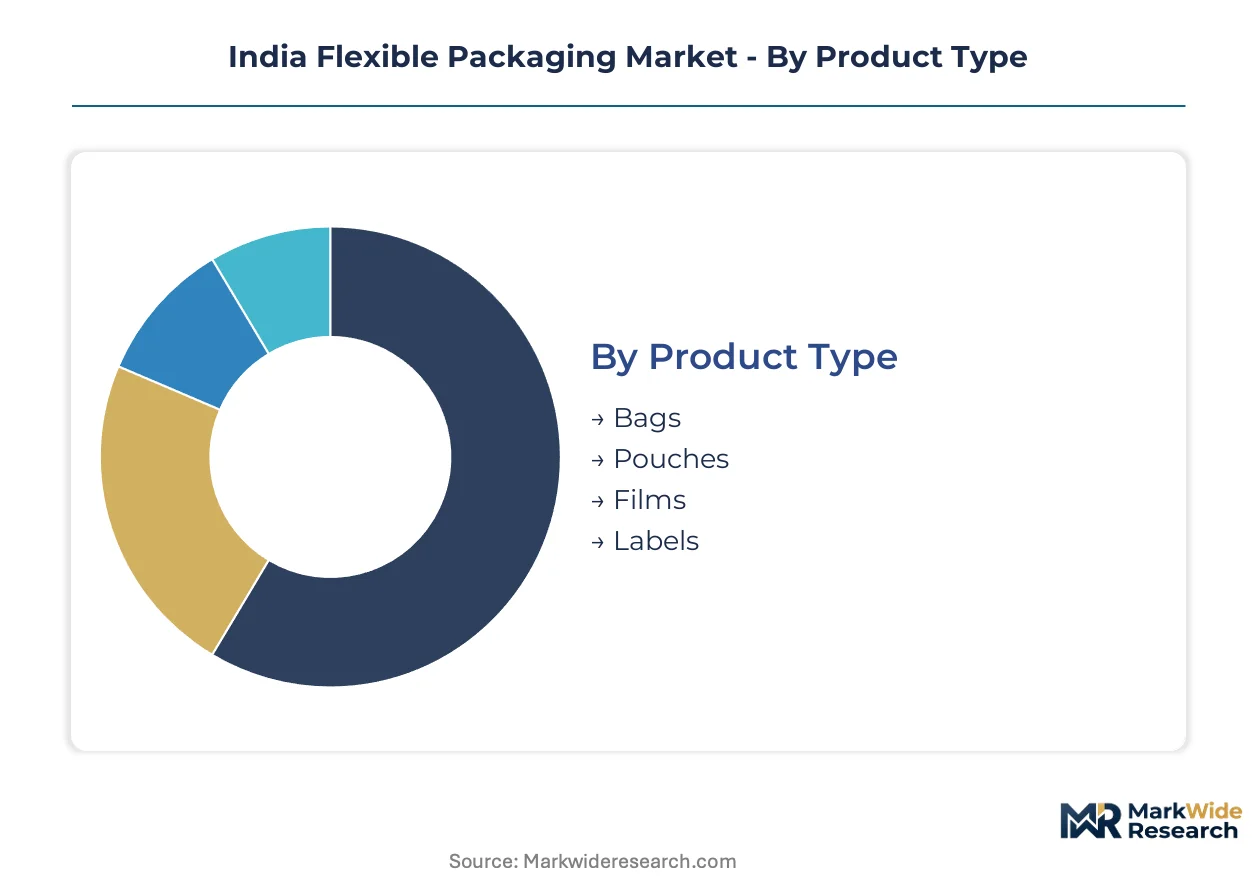
Segmentation in the India Flexible Packaging Market reveals how regulatory pressure, substrate innovation, and end-use specialization fragment procurement patterns across converters. Each dimension carries distinct compliance burdens and margin profiles that reshape competitive positioning.
Product Type:
BIS certification requirements for migration limits and heavy metal content create divergent qualification timelines across formats, with food-contact structures facing the strictest testing protocols.
- Pouches:Multi-layer laminates with zipper closures and spout fitments dominate single-serve food and personal care formats. Maharashtra-based FMCG brands are consolidating procurement toward BIS-accredited converters capable of solventless lamination to meet FSSAI direct-contact mandates.
- Films:Coextruded and oriented substrates provide the foundational barrier layers for downstream converting. Gujarat's polymer processing clusters around Ahmedabad supply blown and cast PE/PP films to industrial wrapping applications where cost-per-meter drives supplier selection.
- Bags:Side-gusseted and block-bottom configurations serve bulk dry goods and agricultural commodities. Demand concentrates in Punjab and Haryana grain markets where puncture resistance and moisture protection determine procurement.
- Labels:Pressure-sensitive and shrink-sleeve formats wrap contoured containers in beverage and pharmaceutical applications. CDSCO traceability requirements for drug packaging are elevating specification complexity beyond general industrial label standards.
Established volume favors Films; emerging adoption favors Pouches.
Material:
Cost tier stratification separates commodity polymer supply from premium substrate qualification, with import-dependent feedstock exposing mid-tier converters to rupee volatility.
- Plastic:Polyethylene, polypropylene, and polyester layers constitute the dominant substrate class through extrusion coating and adhesive lamination. Over 70 percent of resin arrives via Middle East supply chains, compressing margin buffers for non-integrated converters during freight spikes.
- Biodegradable:PLA and PHA blends engineered for tropical humidity conditions are opening shelf-stable applications previously locked to conventional plastics. Karnataka and Tamil Nadu brand mandates are accelerating pilot procurement despite 40-60 percent cost premiums over fossil-based alternatives.
- Paper:Kraft and glassine substrates provide grease-resistant and breathable barriers for dry food and confectionery. FSSAI coating compliance for direct food contact limits viable supplier pools to mills with BIS-accredited barrier treatments.
- Aluminum Foil:Metallized and plain foil layers deliver oxygen and light barriers for pharmaceutical blister packs and retort pouches. CDSCO oxygen transmission rate requirements below 0.5 cc/m²/day demand capital-intensive metallization equipment that sub-scale converters cannot access.
Cost efficiency concentrates procurement in Plastic; sustainability compliance is accelerating Biodegradable adoption fastest.
End User:
Application-specific barrier requirements and regulatory exposure segment converter capabilities across consumer-facing industries with diverging technical entry costs.
- Food & Beverage:Modified atmosphere packaging and high-barrier laminates extend shelf life for snacks, dairy, and ready-to-eat meals. Quick-commerce networks in Bengaluru and Delhi NCR are compressing specification cycles to quarterly reviews with sub-gram weight targets.
- Pharmaceuticals:Blister foils, sachets, and strip packs demand traceability, child-resistance, and barrier performance validated under CDSCO guidelines. Oxygen and moisture transmission specifications exclude generalist converters lacking metallization and cold-form foil capabilities.
- Personal Care:Stand-up pouches and sachets for shampoo, lotion, and detergent formats prioritize print quality and dispensing functionality. Premium brand owners are migrating toward mono-material structures to preempt EPR compliance costs under PWM Rules enforcement.
- Household:Industrial-scale bags and wraps for cleaning products and hardware emphasize puncture resistance and load-bearing capacity. Procurement concentrates among volume buyers in Gujarat and Maharashtra with annual contract structures that favor integrated film-to-bag manufacturers.
Volume concentration anchors Food & Beverage; regulatory barrier height favors Pharmaceuticals for margin extraction.
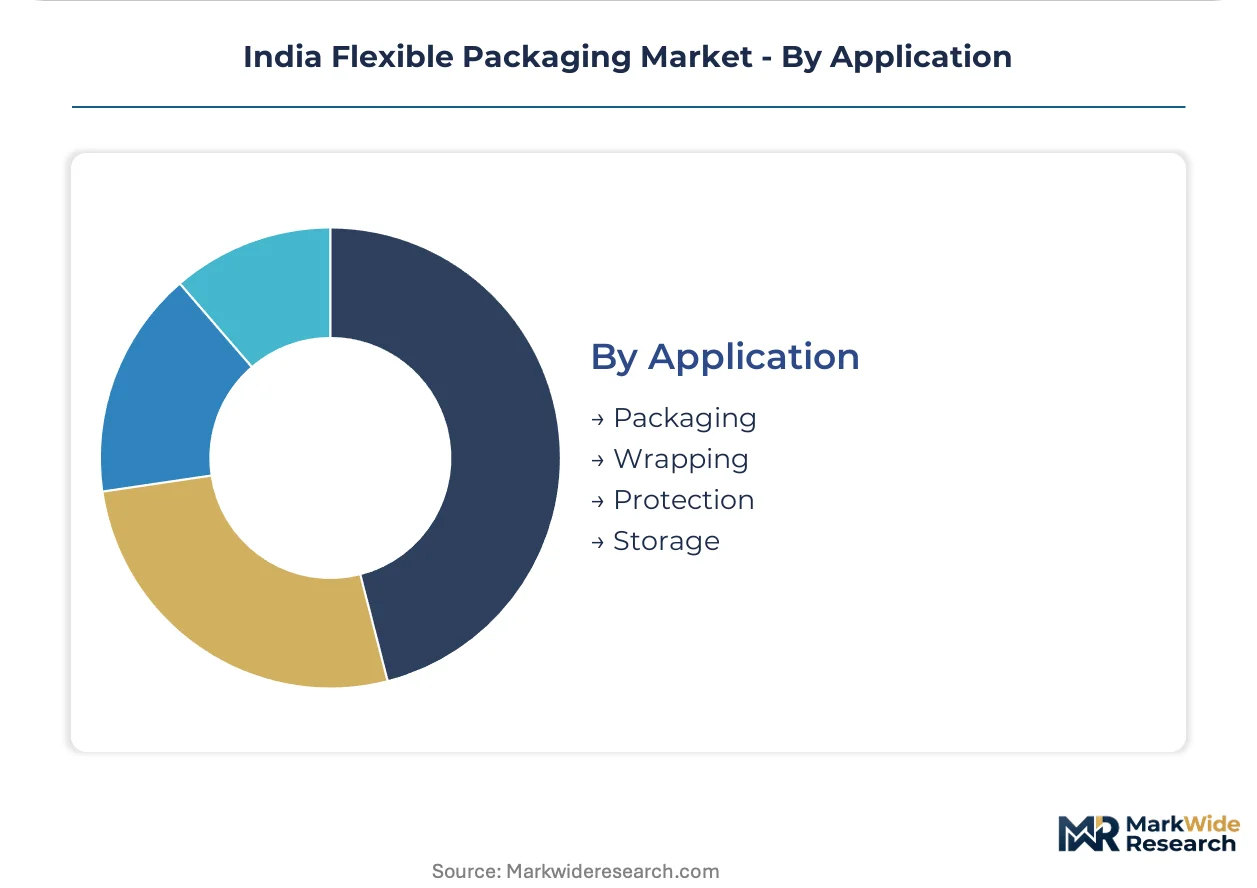
Application:
Functional performance requirements separate commodity wrapping from engineered protection, with shelf-life extension commanding premium pricing over basic containment.
- Packaging:Primary and secondary structures designed for retail presentation, shelf stability, and consumer convenience. Pouch and bag formats in this category carry the highest print and finishing specifications for brand differentiation at point-of-sale.
- Protection:Barrier-engineered laminates guarding against moisture, oxygen, UV, and mechanical damage during distribution. Pharmaceutical and electronics segments drive specification intensity here with validated performance documentation requirements.
- Wrapping:Stretch film, shrink film, and industrial bundling formats for palletization and unitization. Cost-per-meter optimization dominates procurement, with Gujarat's resin proximity enabling regional converter cost advantages.
- Storage:Bulk containment and long-duration preservation formats for agricultural and industrial commodities. Tamil Nadu and Andhra Pradesh cold-chain expansion is generating first-mover demand for vacuum and gas-flushed barrier structures.
Margin pools concentrate in Protection; volume scale favors Wrapping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI certification requirements and the Plastic Waste Management Rules concentrate converter capacity in states with established polymer processing infrastructure and FMCG headquarters proximity.
Maharashtra
Mumbai-based FMCG procurement teams drive demand for BIS-accredited solventless lamination capacity. FSSAI direct-contact mandates are displacing informal converters across Nashik and Thane industrial belts. Integrated film-to-pouch manufacturers near Mumbai-Pune corridor capture bulk supply contracts from domestic snack and dairy brands.
Gujarat
Ahmedabad polymer clusters supply blown and cast PE/PP films to industrial wrapping applications where cost-per-meter dominates supplier selection. BIS testing laboratory backlog for migration compliance extends product launch timelines for new substrate formulations. Dahej and Vadodara extrusion facilities anchor high-volume film output for downstream converting.
Karnataka
Bengaluru quick-commerce networks compress packaging specification cycles to quarterly reviews with sub-gram weight targets for 10-minute delivery optimization. State-level brand sustainability mandates accelerate pilot procurement of PLA and PHA blends despite 40-60 percent cost premiums. Mysuru and Tumakuru converting units serve regional personal care and food processing demand.
Andhra Pradesh
Visakhapatnam cold-chain infrastructure generates first-mover demand for high-barrier vacuum pouches in seafood and spice exports. Extended Producer Responsibility credit markets under PWM Rules enforcement reward mono-material design adoption with offset revenue streams. Vijayawada-Guntur food processing corridor attracts converter investment for gas-flushed barrier structures.
Tamil Nadu
Chennai pharmaceutical and personal care manufacturers reformulate blister and sachet structures around aluminum-paper or mono-PP alternatives to preempt EPR compliance costs. CDSCO oxygen transmission rate requirements below 0.5 cc/m²/day demand capital-intensive metallization equipment. Coimbatore converting clusters specialize in pharmaceutical-grade barrier laminates for domestic drug delivery.
India Flexible Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the India Flexible Packaging Market. Uflex Limited leverages captive resin sourcing and film extrusion assets to dominate bulk supply contracts, while Cosmo Films Ltd sustains technology leadership in specialty polyester substrates. The competitive terrain splits between scale-driven integrated converters, technology-focused specialty film producers, and regional quick-service restaurant packaging specialists. Capacity expansion and mono-material portfolio diversification constitute the dominant competitive moves as PWM Rules enforcement hardens.
Among integrated domestic converters, Uflex Limited occupies a position exemplifying backward control over resin through film extrusion assets. Cosmo Films Ltd represents the specialty film archetype with focused capabilities in pharmaceutical-grade polyester barriers. Huhtamaki Oyj anchors the multinational quick-service restaurant packaging tier through localized India operations serving premium foodservice demand.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Mondi PLC |
| Uflex Limited |
| Constantia Flexibles |
| Cosmo Films Ltd |
| Amcor Plc |
| Berry Global Inc. |
| Sonoco Products Company |
| Polyplex Corporation Limited |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day polymer resin inventory cycles at Maharashtra converters compress pricing power during rupee depreciation episodes, binding procurement costs to Middle East supply chain reliability and Mumbai-Ahmedabad logistics corridors.
Pricing Analysis
Ahmedabad-to-Mumbai spreads of four-to-six percent separate Gujarat film extrusion hubs from Maharashtra converting clusters, with freight and BIS certification premiums explaining the gap. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels stratifies the market, with FSSAI migration testing separating the top tier. Cost compression in standard grades intensifies as informal Nashik converters undercut accredited facilities. Quick-commerce buyers in Bengaluru demonstrate lowest price sensitivity, prioritizing sub-gram weight engineering over per-unit cost.
Supply Chain Analysis
Jawaharlal Nehru Port congestion and Red Sea freight volatility elevate inbound logistics costs for polyethylene and polypropylene cargoes originating from Saudi Arabia, Qatar, and Kuwait. Raw material dependencies center on ethylene, propylene, and polyester chip feedstocks. Single-source vulnerability concentrates in Dahej polymer terminal throughput capacity. Distribution runs through converter-direct relationships with FMCG procurement teams, bypassing distributor layers for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solventless lamination technician scarcity in Nashik and Vapi constrains quality-controlled capacity expansion, creating defendable positions for accredited facilities that have secured trained workforces.
For Market Incumbents: Compound BIS-accredited capacity in Maharashtra-Gujarat corridors to capture FSSAI-mandated volume migration from informal converters. Prioritize backward integration into blown film extrusion to buffer Middle East resin freight spikes. Defend against metallization-capable pharmaceutical specialists by acquiring cold-form foil technical expertise. For New Entrants and Emerging Players: Anchor in Andhra Pradesh-Telangana cold-chain corridors where vacuum pouch demand outruns qualified supply. Target Visakhapatnam seafood exporters and Hyderabad spice processors with gas-flushed barrier prototypes. Pursue digital print-on-demand partnerships with regional FMCG brands launching quarterly flavor variants. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because PWM Rules enforcement hardens annually and EPR credit markets reward early mono-material design adoption. Acquisition targets should display integrated film-to-pouch assets plus active BIS certification pipelines. The signal to watch is state pollution control board production halt penalties accelerating informal converter exit.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin conversion buffers Gujarat polymer clusters against freight volatility. |
| Solventless Lamination Capacity Expansion | FSSAI direct-contact mandates displace adhesive-based capacity in Maharashtra. |
| Mono-Material Portfolio Diversification | EPR credit market access under PWM Rules rewards recyclable substrate design. |
| Digital Print Platform Integration | HP Indigo systems collapse minimum order quantities for regional brand launches. |
| Pharmaceutical Barrier Certification | CDSCO oxygen transmission specifications exclude generalist converters from drug packaging. |
Research Methodology
A standing panel of converter operations managers, FMCG procurement directors, BIS laboratory technicians, and polymer resin traders provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews drew from flexible packaging plant heads in Nashik, Thane, and Ahmedabad industrial belts. Secondary sources encompassed FSSAI migration testing protocols, CDSCO pharmaceutical packaging guidelines, Plastic Waste Management Rules amendments, customs polymer import records, and state pollution control board EPR enforcement circulars. Bottom-up capacity estimates triangulated against top-down FMCG procurement spend analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated product type, material substrate, end-user industry, and application function dimensions. CAGRs derived from polynomial trend fitting to historical polymer consumption and converter revenue trajectories. Industry-specific inputs included BIS certification queue durations, quick-commerce packaging specification cycle compression, and EPR credit market liquidity assumptions.
Decision-makers should treat outputs as directional under stable rupee-dollar exchange and sustained PWM Rules enforcement intensity; material deviation would warrant model refresh. Polymer feedstock price spikes, state-level plastic ban extensions, or metallization equipment import tariff shifts could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market