
 Nigeria Flexible Plastic Packaging Market | 2026-2036
Nigeria Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Flexible Plastic Packaging Market Insights
Multilayer coextrusion technology is fragmenting legacy monolayer production across Nigerian converting plants. UFlex Limited leverages its integrated film manufacturing to supply branded converters in Lagos and Onitsha. PrimePak Industries Nigeria Ltd anchors its position through specialized shrink film lines serving beverage bottlers. Sonnex Packaging Nigeria Ltd competes by controlling distribution channels into the northern retail corridors.
Nigeria flexible plastic packaging encompasses polymer-based films, laminates, and formed containers typically below 250 microns thickness, engineered for barrier protection, shelf-life extension, and unit-dose convenience across supply chains. Stand-up pouches and shrink films command dominant volume positions, while bioplastics represent the fastest-growing material category as SON compliance pressures intensify. Polyethylene and polypropylene together occupy the core margin pool, though PVC faces structural decline amid pharmaceutical sector reformulation toward compliant alternatives.
SON standards, NAFDAC food-contact regulations, and the National Environmental Standards and Regulations Enforcement Agency (NESREA) waste directives collectively shape material specifications, import substitution incentives, and post-consumer accountability frameworks for domestic producers. Stakeholders must monitor evolving Extended Producer Responsibility mandates and bioplastic certification pathways to secure long-term market access.
Market Dynamics
Multilayer coextrusion technology is fragmenting legacy monolayer production across Nigerian converting plants, forcing capital retooling at Lagos and Kano facilities while SON compliance deadlines compress implementation timelines.
Growth Catalysts
- NAFDAC food-contact mandates:Stricter material certification requirements for polyethylene-based pouches are pulling compliant domestic capacity expansion ahead of import substitution timelines.
- Apapa port corridor exporters:Fast-moving consumer goods shipments through Lagos are accelerating specification standardization for barrier films meeting destination-market entry protocols.
- Bioplastic material innovation:Compostable film formulations are capturing shelf-space trials among beverage bottlers seeking NESREA waste directive alignment.
Market Restraints
- Polyethylene resin import dependency:Naira volatility against dollar-denominated feedstock contracts is compressing margin predictability for domestic converters.
- Monolayer asset strandedness:Legacy extrusion lines in northern Nigeria face accelerated obsolescence as multilayer specifications become default buyer requirements.
- PVC pharmaceutical displacement:Reformulation toward polypropylene alternatives in unit-dose packaging is structurally shrinking addressable volume for chlorinated film producers.
Strategic Opportunities
- Onitsha distribution hub penetration:Southeast Nigeria retail corridor consolidation is creating channel control openings for integrated film suppliers with captive logistics.
- Extended Producer Responsibility pre-positioning:NESREA post-consumer accountability frameworks are rewarding early compliance infrastructure investments with preferential licensing.
- Shrink film beverage diversification:Specialized collation films for carbonated soft drinks are migrating from imported to domestic specification development.
Industry Challenges
- Multilayer technician scarcity:Coextrusion die adjustment and layer ratio optimization skills are concentrated among a narrow workforce pool in Lagos industrial zones.
- SON certification timeline compression:Food-contact safety testing backlogs are extending product launch windows beyond seasonal demand cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Flexible Plastic Packaging Market |
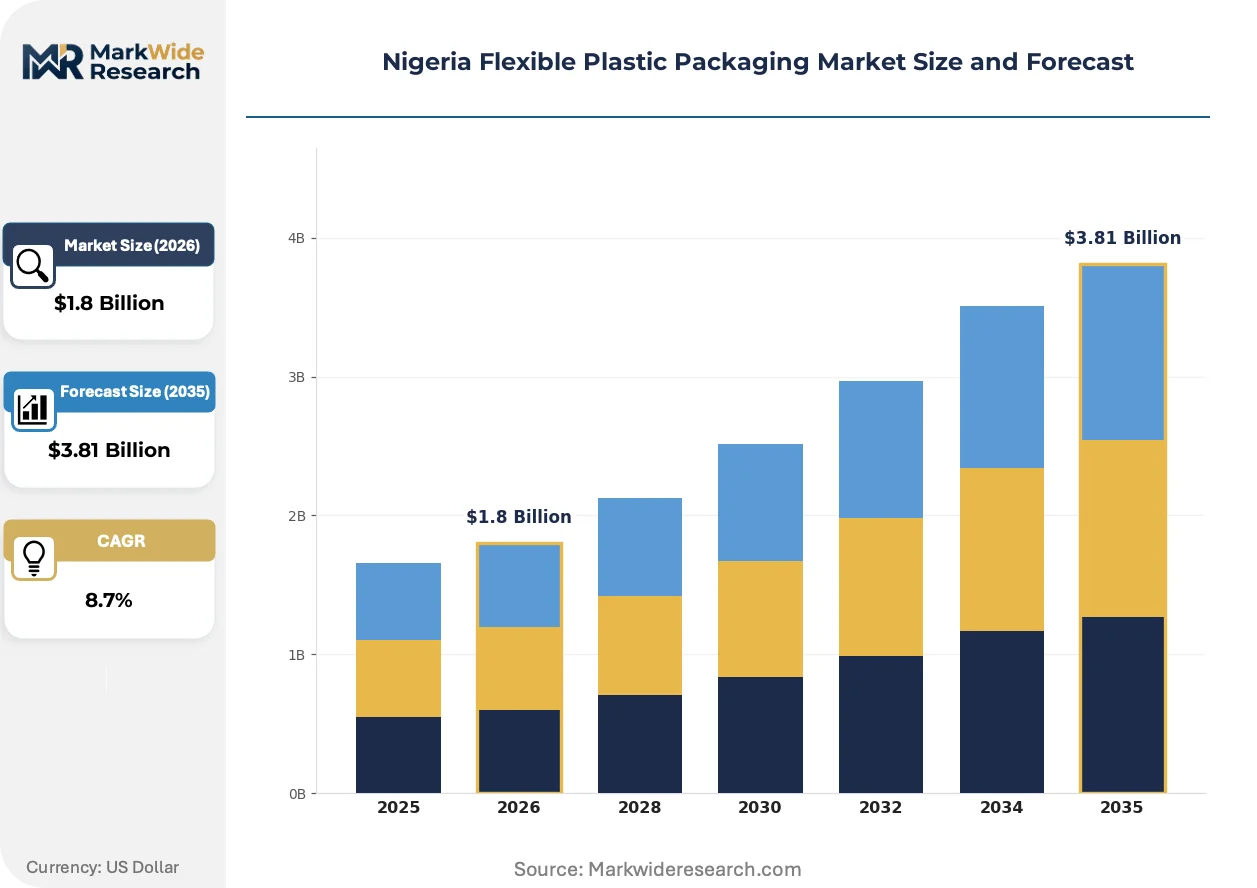
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Films, Bags, Wraps Application: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Goods Material Type: Polyethylene, Polypropylene, PVC, Bioplastics End User: Manufacturers, Retailers, Wholesalers, Exporters |
| Companies Covered | All Time Packaging, UFlex Limited, PrimePak Industries Nigeria Ltd, Sonnex Packaging Nigeria Ltd, Twinstar Industries, Flexipack Plastics Ltd, Tempo Paper Pulp & Packaging Ltd, Victor Oscar Company, Quantum Plastic Nigeria Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Flexible Plastic Packaging Market Trends and Innovations
Active barrier technology deployment and regulatory compliance automation are compressing traditional competitive advantages held by import-dependent converters across Nigerian flexible packaging.
Multilayer coextrusion with active oxygen scavenging layers is collapsing the shelf-life performance gap between domestic and imported barrier films. Beverage exporters operating through Apapa are specifying these structures for tropical climate resilience. The technology is collapsing premium pricing power previously held by European laminate suppliers.
SON material compliance digitization is forcing real-time batch traceability investments across Lagos converting clusters. Automated certificate-of-analysis generation is becoming a mandatory tender requirement for multinational fast-moving consumer goods procurement. Northern Nigeria flexible packaging distributors are consolidating supplier relationships to reduce audit burden duplication.
Exporter-driven specification harmonization is compressing domestic converter product variety. Fast-moving consumer goods buyers are consolidating film grades to simplify cross-border customs documentation. Kano-based pouch converters are responding by standardizing on five core polyethylene structures rather than maintaining legacy grade proliferation.
Nigeria Flexible Plastic Packaging Market Segmentation
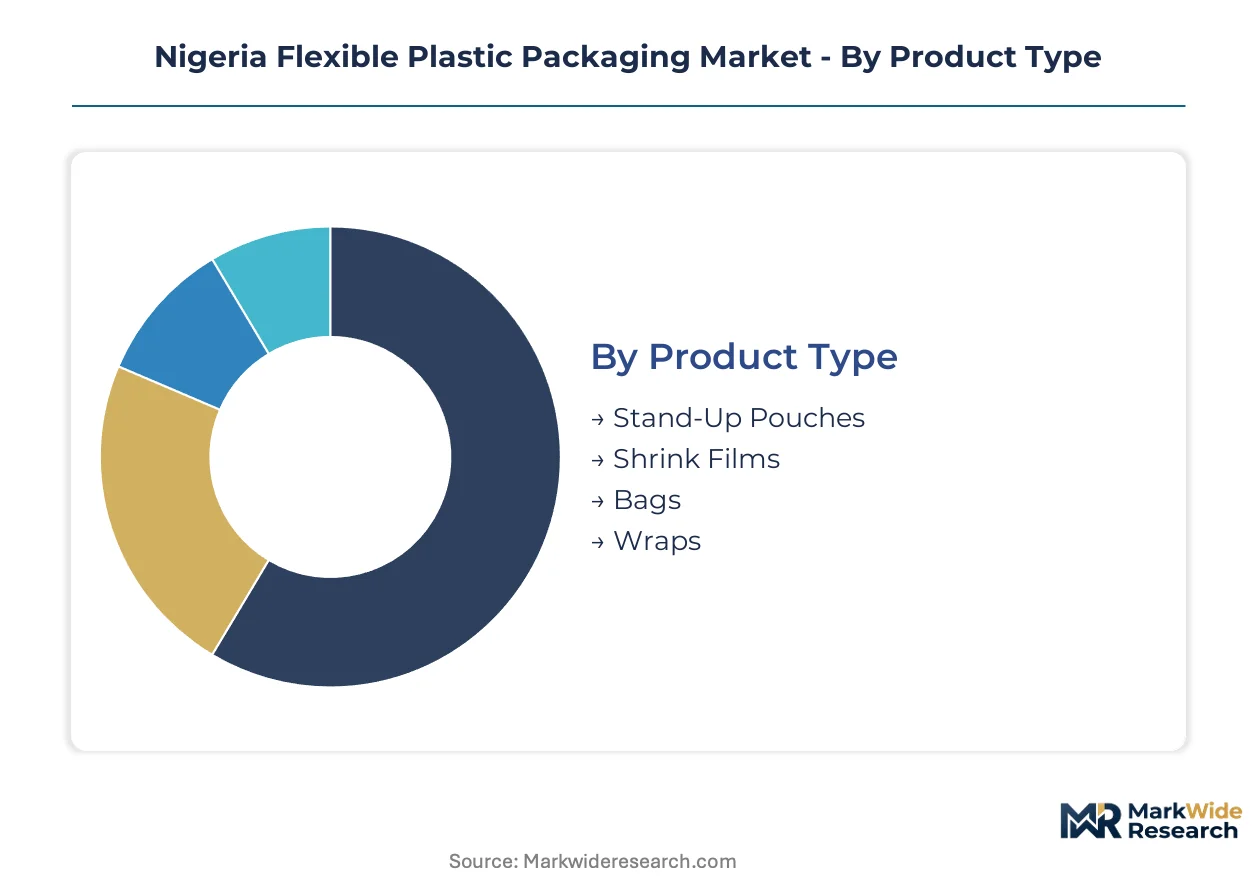
Segmentation in Nigeria flexible plastic packaging reveals how regulatory pressure and export corridor dynamics reshape procurement priorities across converter tiers. Material compliance tiers and distribution channel control determine margin capture more than volume scale alone.
Product Type:
Mature formats dominate current capacity utilization while emerging structures command premium positioning in Lagos and Kano converting clusters.
- Stand-Up Pouches:Multilayer polyethylene laminates with resealable zipper mechanisms. Apapa port corridor exporters specify these for spice and seasoning shipments to European Union markets requiring EFSA-aligned barrier performance.
- Shrink Films:Biaxially oriented polypropylene or polyethylene terephthalate glycol-modified formulations engineered for collation bundling. Beverage bottlers in Lagos industrial zones are migrating from imported to domestic specification development under SON compliance timelines.
- Bags:Monolayer and multilayer polyethylene configurations for bulk commodity handling.
- Wraps:Stretch and cling film variants for pallet stabilization and fresh produce protection.
Stand-Up Pouches retains volume leadership; Bioplastics holds the steepest expansion curve.
Application:
Cost tier stratification separates compliance-intensive segments from price-sensitive commodity packaging.
- Food & Beverage:Oxygen scavenging multilayer films and high-barrier laminates for tropical climate shelf-life extension. NAFDAC food-contact mandates are pulling compliant domestic capacity expansion ahead of import substitution timelines for Lagos-based processors.
- Personal Care:Sachet and pouch formats for shampoo and lotion unit-dose distribution. Northern Nigeria retail corridor consolidation is driving specification standardization among Kano and Onitsha distributors.
- Pharmaceuticals:Blister packs and strip packaging with child-resistant and senior-friendly features.
- Consumer Goods:Printed laminates for household product differentiation.
Food & Beverage anchors revenue concentration; Pharmaceuticals climbs fastest on reformulation compliance.
Material Type:
Supply concentration around polyolefin feedstocks shapes converter margin structures and SON certification pathways.
- Polyethylene:Low-density and linear low-density grades for flexible films and pouches. Naira volatility against dollar-denominated resin contracts compresses margin predictability for domestic converters sourcing through Lagos port corridors.
- Polypropylene:Cast and oriented film grades with superior clarity and stiffness. Pharmaceutical sector reformulation from PVC alternatives is structurally expanding addressable volume for propylene-based unit-dose solutions.
- PVC:Chlorinated film formulations facing displacement pressure from regulatory reformulation mandates.
- Bioplastics:Compostable and bio-based film formulations including polylactic acid and starch blends.
Polyethylene retains volume leadership; Bioplastics gains share fastest on NESREA waste directive alignment.
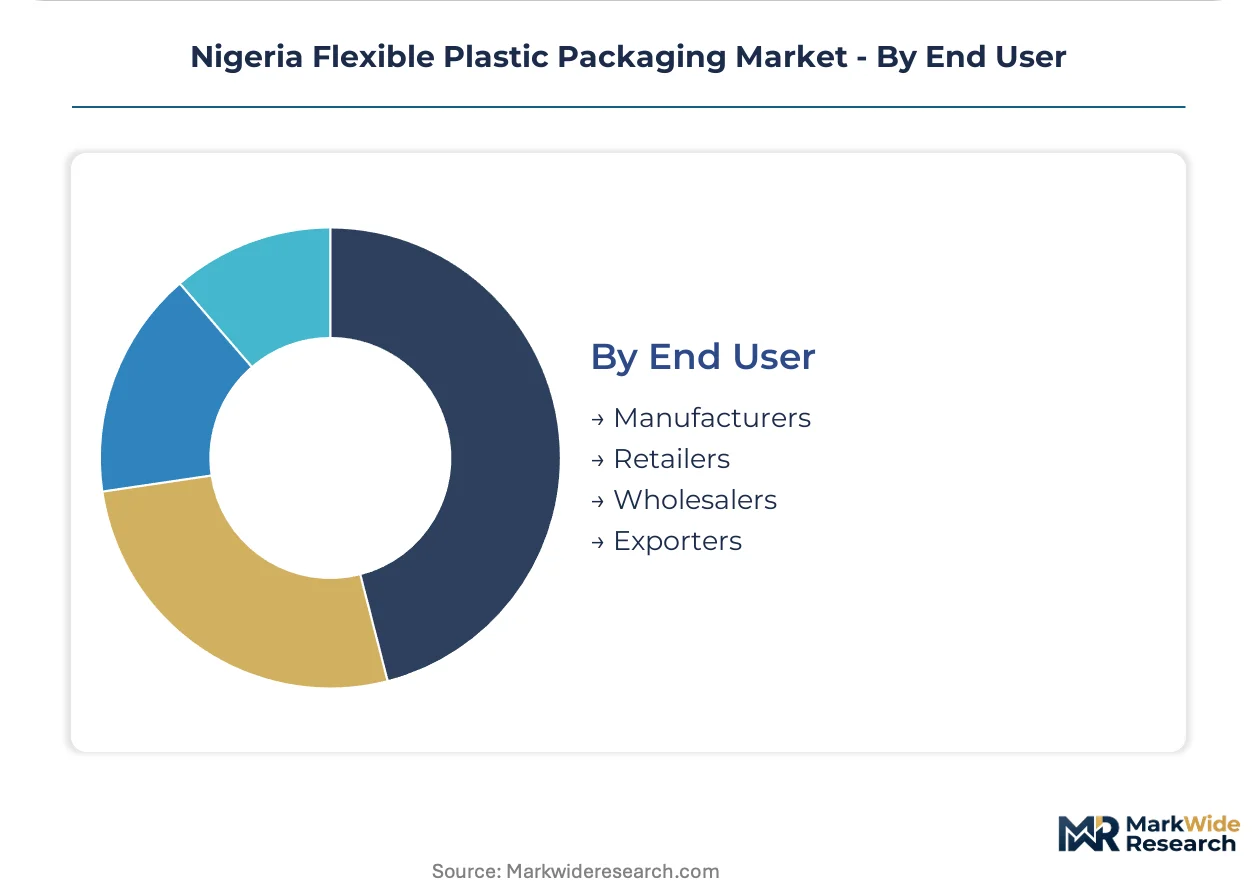
End User:
Customer type determines specification complexity and certification burden across the value chain.
- Manufacturers:Fast-moving consumer goods producers with integrated packaging operations. Automated certificate-of-analysis generation is becoming mandatory tender requirement for multinational procurement teams operating through Apapa.
- Retailers:Private label and store-brand packaging specifications for shelf differentiation. Southeast Nigeria retail corridor consolidation is creating channel control openings for integrated film suppliers with captive logistics into Onitsha.
- Wholesalers:Bulk commodity packaging for agricultural and industrial distribution.
- Exporters:Destination-market compliant barrier films for cross-border shipment.
Manufacturers retain volume leadership; Exporters holds the steepest expansion curve on specification harmonization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apapa port corridor shipments to European Union markets are driving specification standardization among Lagos-based converters, while northern retail corridors anchor domestic demand concentration.
Lagos Industrial Corridor
Fast-moving consumer goods exporters dominate polyethylene pouch procurement through Apapa port facilities. NAFDAC food-contact mandates require real-time batch traceability systems across Ikeja and Amuwo-Odofin converting clusters. Multilayer coextrusion lines at Lagos facilities are retooling ahead of SON compliance deadlines.
Kano Manufacturing Belt
Beverage bottlers and spice processors generate concentrated shrink film demand across northern Nigeria's largest industrial zone. NESREA waste directives are accelerating bioplastic trial adoption among Kano-based pouch converters. Legacy monolayer extrusion assets face strandedness as multilayer specifications become default buyer requirements.
Onitsha Distribution Hub
Southeast Nigeria retail corridor consolidation is creating channel control openings for integrated film suppliers with captive logistics. SON certification digitization is compressing product launch windows beyond seasonal demand cycles. Anambra State converting plants are standardizing on five core polyethylene structures to reduce audit burden duplication.
Aba Industrial Zone
Enugu and Abia State manufacturers supply printed laminates for household product differentiation across eastern markets. Polypropylene pharmaceutical reformulation is expanding addressable volume for propylene-based unit-dose solutions. Local converters are migrating from imported to domestic shrink film specification development.
Nigeria Flexible Plastic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented converter tier where integrated film manufacturing anchors premium positioning. The vendor base clusters around three strategic archetypes: integrated resin-to-film suppliers with captive logistics, specialized format converters focused on beverage and pharmaceutical niches, and distribution-anchored players controlling northern retail corridors. Competitive moves concentrate on multilayer technology licensing and backward integration into resin compounding to offset Naira-denominated margin volatility.
Among India-based integrated suppliers, UFlex Limited exemplifies the resin-to-film archetype with manufacturing presence serving West African markets. PrimePak Industries Nigeria Ltd and Sonnex Packaging Nigeria Ltd occupy positions within the domestic specialist tier, with the former representing beverage-focused format expertise and the latter anchoring distribution control into northern Nigeria retail corridors. These three players illustrate the competitive tension between foreign-integrated supply and domestic channel capture.
| Leading Market Players |
|---|
| All Time Packaging |
| UFlex Limited |
| PrimePak Industries Nigeria Ltd |
| Sonnex Packaging Nigeria Ltd |
| Twinstar Industries |
| Flexipack Plastics Ltd |
| Tempo Paper Pulp & Packaging Ltd |
| Victor Oscar Company |
| Quantum Plastic Nigeria Ltd |
| Others |
Pricing and Supply Chain Analysis
Apapa port corridor freight dynamics concentrate supply-side leverage among integrated resin importers while fragmenting downstream converter pricing power across Lagos and Kano industrial zones. Naira volatility against dollar-denominated polyethylene contracts compresses margin predictability for domestic pouch manufacturers serving NAFDAC-compliant food-contact segments.
Pricing Analysis
Multilayer coextrusion lines command premium pricing over legacy monolayer assets as SON compliance deadlines accelerate technology-generation turnover. Three-tier pricing structure across premium barrier laminates, standard polyethylene films, and economy-grade monolayer bags reflects certification-grade differentiation and volume-scale thresholds. Pricing pressure stems from resin import dependency feeding cost compression into mid-tier converter margins. Exporters through Apapa demonstrate lowest price sensitivity due to destination-market premium capture, while northern Nigeria agricultural packaging buyers exhibit highest elasticity.
Supply Chain Analysis
Import substitution incentives under SON material compliance frameworks restrict unverified resin flows while channeling feedstock procurement toward certified Middle Eastern and Asian suppliers. Nigerian flexible packaging draws from Saudi Arabian polyethylene, South Korean polypropylene, and Indian bioplastic resin streams. Single-source vulnerability concentrates around Apapa port clearing bottlenecks and Naira-denominated contract exposure. Distribution runs through captive logistics networks controlled by integrated film suppliers serving Onitsha and Kano retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible plastic packaging incumbents face substitution defense imperatives against bioplastic material innovation and NESREA waste directive alignment pressures from beverage bottlers seeking compostable alternatives.
For Market Incumbents: Entrench barrier technology leadership through backward integration into resin compounding to offset Naira volatility exposure. Prioritize SON certification digitization investments ahead of Extended Producer Responsibility licensing deadlines. Defend against bioplastic displacement by accelerating active oxygen scavenging layer deployment for tropical climate shelf-life extension. For New Entrants and Emerging Players: Northern Nigeria retail corridor underpenetration offers white-space access for integrated film suppliers with captive logistics into Kano spice and seasoning distribution channels. Target Onitsha consolidation momentum through specialized shrink film specification development for eastern beverage bottlers. Pursue coextrusion technology licensing partnerships to bypass multilayer technician scarcity concentrated in Lagos industrial zones. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational fast-moving consumer goods parent companies divesting non-core Nigerian packaging operations amid specification harmonization pressures. Five-to-ten-year viability hinges on regulatory compliance infrastructure ownership rather than volume scale alone. Monitor NESREA post-consumer accountability framework enforcement intensity as inflection signal for preferential licensing value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply hedges Naira-dollar volatility for Lagos-based converters. |
| Multilayer Coextrusion Technology Licensing | Active barrier deployment collapses shelf-life performance gap against European imports. |
| SON Compliance Digitization Investment | Automated certificate-of-analysis generation satisfies multinational FMCG procurement mandates. |
| Extended Producer Responsibility Pre-Positioning | Early compliance infrastructure secures preferential NESREA licensing for post-consumer accountability. |
| Onitsha Distribution Hub Penetration | Southeast Nigeria retail corridor consolidation rewards integrated suppliers with captive logistics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, SON certification registries, and NAFDAC food-contact compliance databases. Plant managers at Lagos and Kano converting facilities, procurement leads at Apapa port corridor exporters, distribution channel partners into Onitsha retail corridors, and technical R&D directors at resin compounding operations provided operational validation. Bottom-up capacity utilization estimates triangulate against top-down trade flow analysis.
Forecast inputs span material type segmentation across polyethylene, polypropylene, PVC, and bioplastic categories; product type dimensions including stand-up pouches, shrink films, bags, and wraps; and end-user stratification among manufacturers, retailers, wholesalers, and exporters. CAGRs derive from regression against resin price elasticity and regulatory compliance cost curves. Model sensitivity tests Naira volatility scenarios and SON certification timeline compression effects.
Macroeconomic conditions sit as an overlay; deviation in exchange rate stability, crude oil price trajectories, or import substitution policy intensity would shift the trajectory. Forecasts reflect documented assumptions regarding multilayer technology adoption rates and bioplastic cost parity timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Flexible Bottle Market