
 Flexible Packaging Paper Market | 2026-2036
Flexible Packaging Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Packaging Paper Market Analysis
The EU Packaging and Packaging Waste Regulation is rebalancing procurement criteria across European food and beverage supply chains. Mondi Plc leverages its integrated kraft paper operations to secure long-term contracts with quick-service restaurant chains. DS Smith anchors its competitive position through closed-loop recycled fiber networks spanning multiple converting sites. International Paper Company dominates North American containerboard-to-flexible conversion capacity for e-commerce mailers.
Flexible packaging paper comprises machine-finished or machine-glazed papers, typically 30–80 gsm, engineered for barrier properties through coating, lamination, or metallization to replace multi-layer plastic films. Kraft paper and coated paper segments lead volume, with laminated paper commanding premium pricing due to moisture and oxygen barrier requirements. Flexography occupies the largest share of printing technology adoption, while digital printing gains traction for short-run customized pouch orders in personal care applications.
EMA evaluates fiber-based food contact materials under updated Framework Regulation standards, while EPA rules on per- and polyfluoroalkyl substance restrictions influence coating chemistry choices in the United States. REACH compliance in Europe and FDA food contact notifications in the United States jointly determine which barrier coatings achieve commercial scale. Stakeholders must monitor evolving extended producer responsibility schemes and their impact on recycled content mandates before committing to capacity expansion.
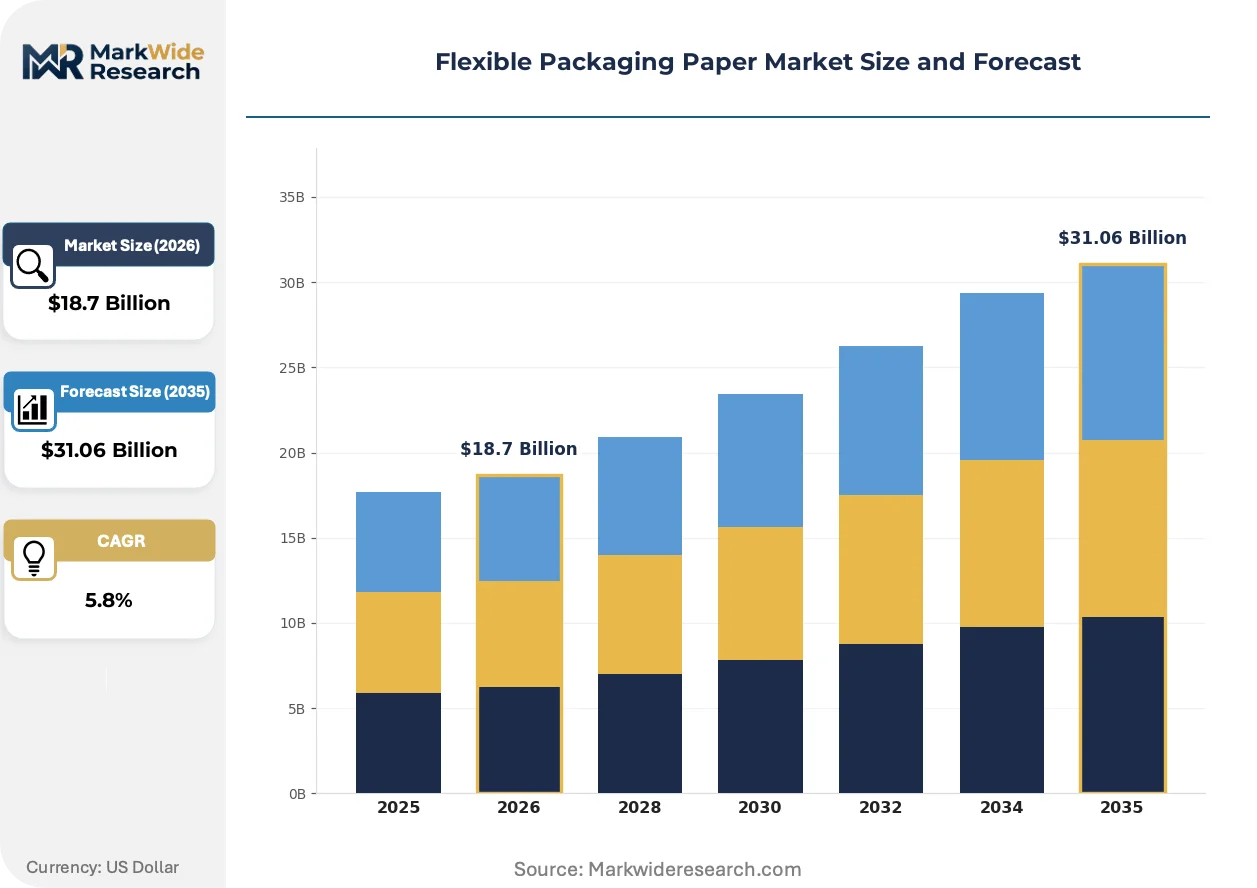
Market Dynamics
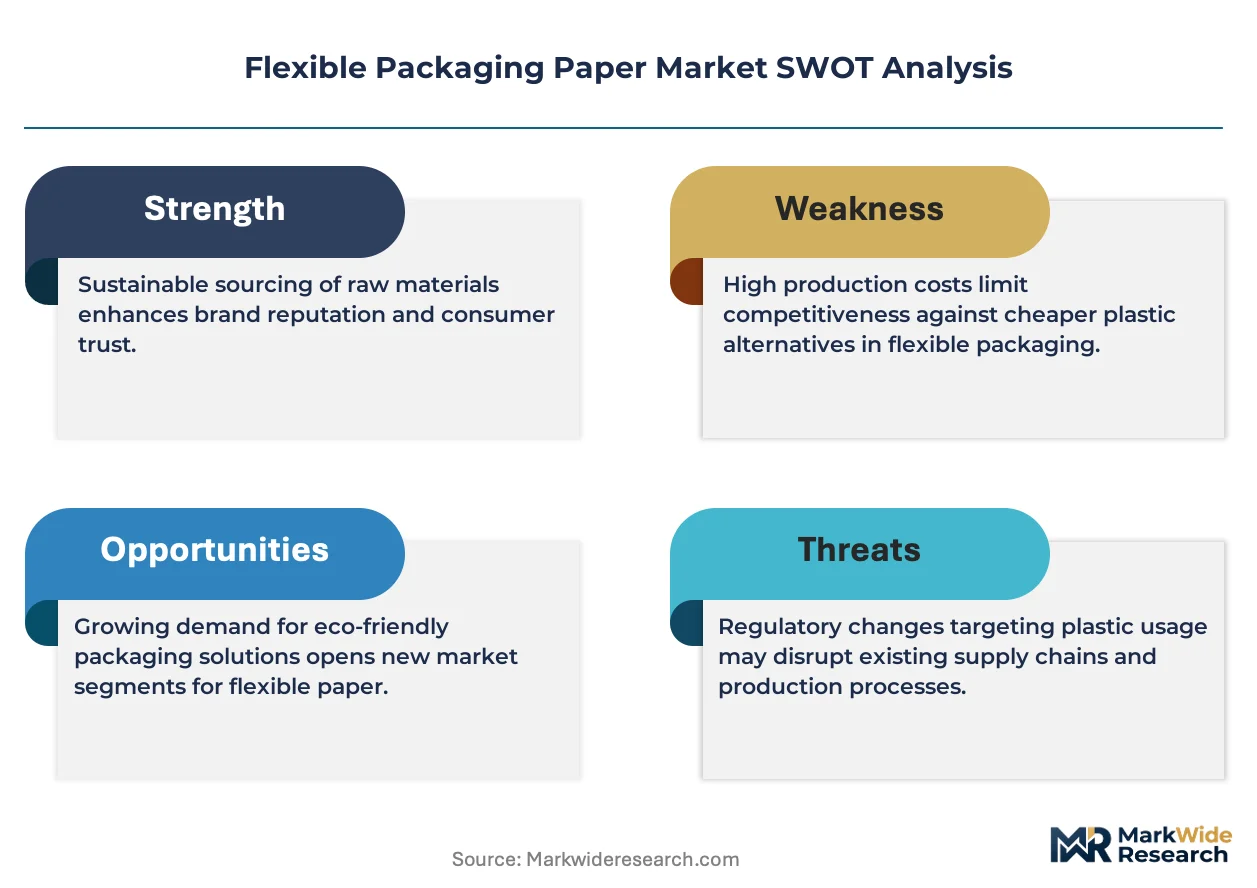
The EU Packaging and Packaging Waste Regulation is forcing food and beverage brands to eliminate multi-layer plastic pouches, redirecting procurement toward fiber-based barrier papers with certified coating chemistries. This regulatory compression is accelerating capital deployment into kraft paper conversion capacity and metallization lines.
Growth Catalysts
- Extended Producer Responsibility schemes:EU member states are implementing packaging waste fees that penalize plastic content, creating direct cost advantages for paper-based flexible formats in snack and frozen food applications.
- Quick-service restaurant chains:Major foodservice operators are mandating fiber-based packaging for takeaway pouches and sandwich wraps, specifying grease-resistant kraft papers with aqueous barrier coatings.
- Metallization technology:Vacuum-deposited aluminum layers on thin kraft substrates are achieving oxygen transmission rates competitive with plastic films, unlocking shelf-stable food categories.
Market Restraints
- Fluctuating softwood pulp prices:Kraft paper margins compress when northern bleached softwood kraft pulp spot prices spike, squeezing integrated and non-integrated converters alike.
- Barrier coating chemistry limitations:Fluoropolymer restrictions under EPA and REACH frameworks eliminate high-performance grease barriers, forcing reliance on less durable wax and clay alternatives for fatty food contact.
- Plastic film cost competitiveness:Oriented polypropylene and polyethylene remain 30-40% lower in unit cost for moisture-only barrier requirements, defending share in dry goods and textiles.
Strategic Opportunities
- Pharmaceutical blister alternatives:Push-through paper-based lidding materials for unit-dose medications represent an underdeveloped application with stringent but achievable barrier requirements.
- Digital printing convergence:Combination of inkjet deposition and in-line barrier coating is enabling economical short runs for personalized personal care sachets and promotional food samples.
- Closed-loop fiber networks:Investment in multi-site recycled pulp integration allows converters to guarantee post-consumer content percentages required by French and Italian packaging mandates.
Industry Challenges
- Food contact notification timelines:FDA review cycles for novel barrier coatings extend 18-24 months, delaying commercialization of bio-based alternatives to polyethylene extrusion layers.
- Flexographic prepress skill scarcity:Shortage of operators capable of managing extended color gamut workflows on absorbent paper substrates limits print quality consistency for brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Packaging Paper Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Bags, Pouches, Wraps, Laminated Paper End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Material: Recycled Paper, Coated Paper, Kraft Paper, White Paper Printing Technology: Flexography, Lithography, Digital Printing, Gravure |
| Companies Covered | International Paper Company, Mondi Plc, Amcor Plc, Smurfit Westrock, DS Smith, Sonoco Products Company, Sealed Air Corporation, ProAmpac, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Packaging Paper Market Emerging Trajectories
Barrier coating deposition methods and printing workflows are undergoing simultaneous transformation. These shifts are compressing minimum order quantities and altering how converters compete on speed versus scale.
Water-based polymer dispersions applied through curtain coating or slot-die extrusion are decentralizing flexible packaging production geography. Mid-size converters in Poland and the Czech Republic are installing compact metallization and coating lines that previously required centralized capital investment. This equipment democratization is enabling regional fulfillment of customized pouch orders with two-week lead times, compressing the advantage of large-scale Asian plastic film exporters.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorinated chemicals from grease-resistant food wraps. The regulation is redirecting coating development toward bio-wax and polysaccharide barriers, though these alternatives sacrifice performance in high-temperature applications. Frozen pizza and microwaveable popcorn segments are absorbing the most significant reformulation costs as they seek compliant replacements before enforcement deadlines.
Brand owners are consolidating supplier relationships around converters capable of certifying carbon footprint per pouch unit. This purchasing pattern is displacing fragmented spot-buying of commodity kraft rolls, instead favoring multi-year agreements with integrated paper-coating-printing operations. The shift is most visible in German and Dutch retail grocery chains, where sustainability scorecards now determine flexible packaging award decisions ahead of unit price.
Flexible Packaging Paper Market Segmentation
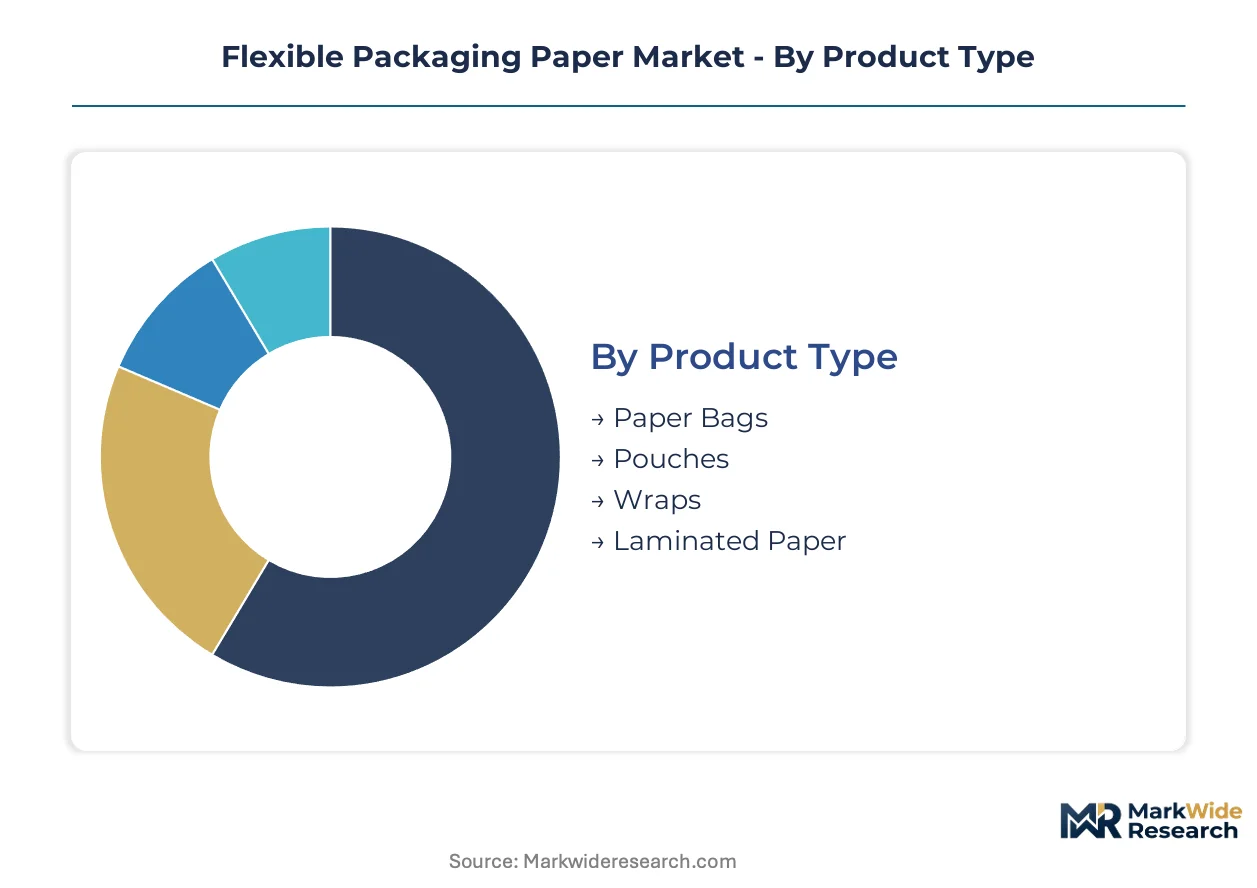
Segmentation in flexible packaging paper reveals divergent certification burdens and margin structures. Product formats and material grades carry distinct FDA, EFSA, and REACH compliance requirements that reshape procurement economics across end-use verticals.
Product Type:
FDA food contact notifications and EU Framework Regulation compliance obligations vary sharply by format, with liquid-contact applications demanding the most extensive barrier coating approvals.
- Pouches:Multi-layer structures with metallized or polymer-coated barriers dominate shelf-stable food applications. Stand-up pouch demand concentrates in German and Dutch retail chains specifying carbon footprint certification per unit.
- Laminated Paper:Composite structures bonding kraft to aluminum or bio-polymer films achieve oxygen transmission rates below 1 cc/m²/day. Premium pricing reflects moisture and grease barrier performance required for frozen pizza and microwaveable popcorn segments.
- Paper Bags:Single-ply or multi-wall constructions serve dry goods and quick-service restaurant takeaway, with aqueous coating chemistry replacing fluorinated barriers under EPA restrictions.
- Wraps:Thin-gauge machine-glazed papers for sandwich and confectionery applications prioritize grease resistance through clay or bio-wax barriers rather than high-barrier lamination.
Leading the category by volume: Paper Bags. Growing fastest: Laminated Paper.
End Use Industry:
Customer procurement patterns split between price-sensitive commodity buyers and sustainability-scorecard-driven retail chains, with the latter consolidating supplier relationships around integrated converters.
- Food & Beverage:The largest demand pool spans snack foods, frozen products, and quick-service restaurant formats. Extended Producer Responsibility fees in EU member states penalize plastic content, accelerating fiber-based conversion in France and Italy.
- Personal Care:Sachets and sample pouches favor digital printing for short-run customization. Inkjet deposition combined with in-line barrier coating enables two-week lead times for promotional campaigns.
- Pharmaceuticals:Unit-dose blister lidding and secondary packaging require stringent barrier performance. Push-through paper-based alternatives to aluminum-PVC structures remain underdeveloped but represent high-margin opportunities.
- Household Products:Detergent pods and cleaning wipes demand puncture resistance and moisture protection, with laminated kraft formats gaining share against multi-layer plastic films.
Food & Beverage commands the greatest volume concentration. Personal Care shows the steepest expansion trajectory as digital printing convergence accelerates.
Material:
Raw material selection determines both regulatory pathway and recycled content eligibility under French and Italian packaging mandates.
- Kraft Paper:Unbleached virgin or recycled fiber with high tear strength serves as the structural backbone for most flexible formats. Northern bleached softwood kraft pulp price volatility directly compresses converter margins.
- Coated Paper:Surface-sized or curtain-coated grades achieve grease and moisture resistance without full lamination. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation toward bio-wax and polysaccharide alternatives.
- Recycled Paper:Post-consumer content guarantees are becoming contract requirements for major retail grocery chains. Closed-loop fiber networks spanning multiple converting sites enable compliance verification.
- White Paper:Bleached grades for premium cosmetic and pharmaceutical applications carry higher unit costs but enable superior print reproduction on flexographic and lithographic presses.
Kraft Paper dominates tonnage. Coated Paper is gaining share fastest as barrier chemistry advances.
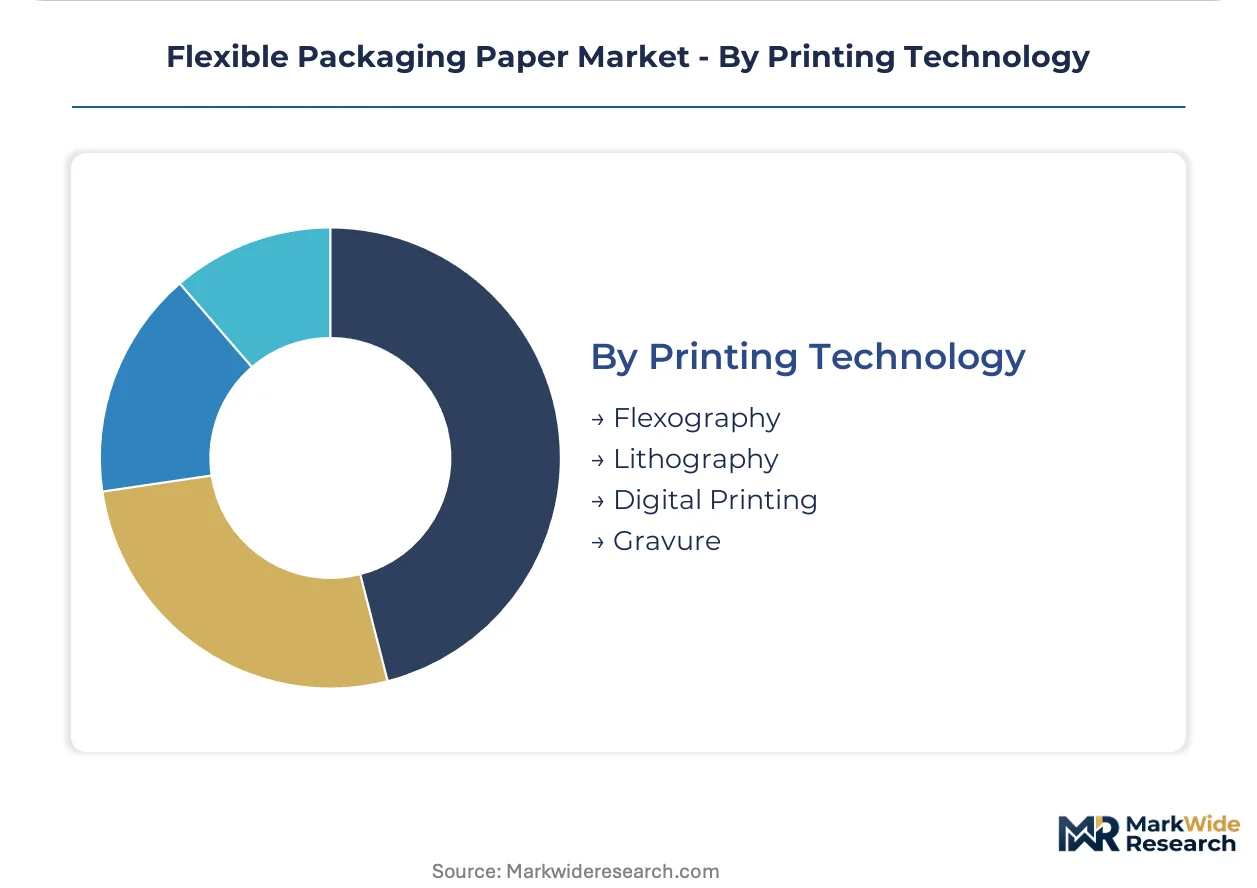
Printing Technology:
Equipment investment and prepress capability requirements create tiered competitive dynamics among converters.
- Flexography:Water-based and UV-curable ink systems on absorbent substrates remain the workhorse for high-volume food packaging. Extended color gamut workflows require scarce operator expertise, limiting quality consistency.
- Digital Printing:Inkjet and toner-based systems enable economical runs below 10,000 units for personalized personal care sachets. In-line barrier coating integration is compressing minimum order quantities.
- Lithography:Offset printing delivers premium image quality for cosmetic and pharmaceutical cartons and labels, though substrate flexibility constraints limit direct flexible packaging application.
- Gravure:Cylinder-based engraving achieves unmatched color consistency for long-run snack food and tobacco packaging, with high setup costs favoring volume concentration.
Flexography leads by installed capacity. Digital Printing is expanding most quickly as equipment democratization enables regional fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters around Hamburg and Bavaria dominate European flexible packaging paper capacity, with converting facilities clustered near major pulp terminals and quick-service restaurant supply chains.
Germany
Quick-service restaurant chains and retail grocery sustainability scorecards drive procurement of certified kraft pouches. The EU Packaging and Packaging Waste Regulation mandates fiber-based alternatives to multi-layer plastics. Hamburg hosts major converting operations where metallization lines process thin-gauge substrates for barrier applications.
United States
E-commerce mailer demand and frozen food packaging sustain containerboard-to-flexible conversion capacity. EPA restrictions on per- and polyfluoroalkyl substances reshape grease-resistant coating chemistry selection. Wisconsin and Georgia pulp corridors supply integrated kraft paper operations serving national quick-service networks.
France
Extended Producer Responsibility fees penalize plastic content in snack and frozen food formats. REACH compliance frameworks determine which barrier coatings achieve commercial scale for fatty food contact. The Île-de-France region concentrates brand owner procurement decisions favoring carbon-footprint-certified pouch suppliers.
China
Domestic quick-service expansion and export-oriented personal care sachet production absorb coated paper volumes. National standards under SAMR govern food contact material safety for laminated structures. The Yangtze River Delta hosts compact metallization line installations enabling regional fulfillment of customized orders.
India
Quick-service restaurant growth and organized retail expansion create demand for grease-resistant kraft formats. FSSAI food contact regulations align with evolving Framework Regulation standards for export-bound production. Maharashtra and Gujarat host emerging converting capacity serving both domestic consumption and Middle East export markets.
Flexible Packaging Paper Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification capability and integrated coating-printing operations. The vendor base stratifies between integrated pulp-to-pouch operators and non-integrated converters dependent on spot kraft purchases. Three archetypes dominate: integrated forest products conglomerates with captive pulp supply, specialty converters focused on metallized barrier applications, and diversified packaging groups leveraging multi-material technology platforms. Competitive moves concentrate on backward integration into kraft paper production and strategic partnerships securing coating chemistry intellectual property.
Among integrated European operators, Mondi Plc and DS Smith exemplify the pulp-captive archetype with multi-site converting networks. International Paper Company anchors North American capacity for containerboard-derived flexible formats. These three entities represent distinct geographic and structural positions within a market where certification breadth and coating chemistry access determine contract awards.
| Leading Market Players |
|---|
| International Paper Company |
| Mondi Plc |
| Amcor Plc |
| Smurfit Westrock |
| DS Smith |
| Sonoco Products Company |
| Sealed Air Corporation |
| ProAmpac |
| Huhtamaki Oyj |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between metallized barrier laminates and commodity kraft rolls splits procurement economics across German retail chains and Asian export converters. This tier separation manifests in long-term offtake agreements for carbon-footprint-certified pouch units versus spot-market volatility for uncoated paper grades, with supply chain configuration reinforcing these pricing bands through captive pulp integration at one extreme and fragmented toll-coating networks at the other.
Pricing Analysis
Barrier-performance pricing anchors contract negotiations, with oxygen transmission rates below 1 cc/m²/day commanding substantial premiums over moisture-only kraft formats. Price differentiation rests on EFSA food contact certification tier and metallization line throughput capacity, while cost compression in commodity uncoated grades intensifies due to northern bleached softwood kraft pulp spot volatility. Quick-service restaurant chains exhibit highest price sensitivity for standardized takeaway formats, whereas pharmaceutical blister alternatives demonstrate lowest sensitivity given stringent barrier requirements and limited qualified suppliers.
Supply Chain Analysis
Single-source vulnerability sits with Swedish and Finnish softwood pulp suppliers feeding integrated European kraft operations. Raw material dependencies encompass northern bleached softwood kraft pulp, aluminum metallization feedstock, and aqueous polymer barrier dispersions. Tariff exposure on coated paper imports into the European Union amplifies cost uncertainty for non-integrated converters. Distribution runs through multi-site converting networks anchored by Hamburg and Bavaria clusters, with regional fulfillment emerging from Poland and Czech Republic compact line installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation enforcement is accelerating consolidation as capital requirements for metallization and coating chemistry compliance eliminate marginal operators.
For Market Incumbents: To counter coating chemistry access fragmentation, secure captive supply through backward integration into kraft paper production and multi-year barrier formulation partnerships with REACH-compliant polymer suppliers. Anchor competitive position by expanding metallization capacity in Hamburg-adjacent clusters to serve quick-service restaurant chain sustainability scorecard requirements. For New Entrants and Emerging Players: Capture pharmaceutical blister alternative white space where push-through paper lidding remains underdeveloped and barrier performance thresholds are achievable without legacy fluoropolymer chemistry. Target personal care sachet segments in the Yangtze River Delta where digital printing convergence enables two-week lead time differentiation against established flexographic converters. For Investors and Strategic Acquirers: Re-rating potential sits with specialty metallized barrier converters given EPR scheme expansion and frozen food segment reformulation demand. Long-term viability favors acquisition of integrated paper-coating-printing operations with verified post-consumer content guarantees. Monitor FDA food contact notification approval timelines for bio-based polyethylene alternatives as inflection signal for coating chemistry competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber supply insulates margin compression from NBSK spot price spikes. |
| Metallization Line Capacity Expansion | Vacuum-deposited aluminum barriers unlock shelf-stable food categories requiring oxygen protection. |
| REACH-Compliant Coating Chemistry Partnership | Bio-wax and polysaccharide barrier access secures frozen pizza and popcorn segment contracts. |
| Closed-Loop Recycled Fiber Network Investment | Multi-site pulp integration guarantees post-consumer content percentages for French and Italian mandates. |
| Digital Printing and In-Line Barrier Integration | Inkjet deposition with curtain coating compresses minimum order quantities for promotional personal care campaigns. |
Methodological Framework
Document review covered EU regulatory filings, EPA substance restriction dockets, and FSSAI food contact standards, complemented by interviews with converting plant managers, quick-service restaurant procurement directors, barrier coating R&D leads, and retail grocery sustainability officers. Secondary validation drew from trade customs data, pulp price indices, and SEC disclosures of integrated forest products conglomerates. Bottom-up capacity assessments and top-down demand modeling were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs covering product type, end-use industry vertical, material grade tier, and printing technology adoption. Segmentation dimensions modeled encompassed barrier performance tier, certification pathway complexity, and regional regulatory cluster. CAGRs were derived through iterative reconciliation of supply-side capacity buildouts and demand-pull from EPR scheme implementation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulp price volatility, REACH enforcement timing on per- and polyfluoroalkyl substances, and FDA review cycle duration for novel barrier coatings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market