
 Asia Pacific Single-Use Packaging Market | 2026-2036
Asia Pacific Single-Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Single-Use Packaging Market Insights
Southeast Asian resin converters and Chinese film extruders is hardening supply security for brand owners across the region. Amcor Group GmbH leverages its regional laminating footprint to service multinational food clients. Huhtamaki Oyj anchors hot beverage cup supply through its India and China plants. Sealed Air Corporation differentiates via automated food packaging systems deployed with Australasian protein processors.
Asia Pacific single-use packaging encompasses disposable containment and wrapping systems engineered from thermoformed films, extruded foams, or molded fiber with barrier coatings for shelf-life extension and sanitary protection. These products serve food service, retail distribution, and e-commerce fulfillment where hygiene assurance and logistics efficiency override reusability considerations. Plastics maintains volume leadership across the region though biodegradable alternatives are capturing premium positioning in Japanese convenience retail and Australian food service. The food and beverage end user segment commands the deepest procurement pools while e-commerce application growth is reshaping void-fill and mailer specifications toward lighter gauge films.
China's MEE enforces extended producer responsibility frameworks that elevate compliance costs for non-recyclable formats. India's BIS and FSSAI jointly regulate food-contact material safety and labeling standards that determine import eligibility and domestic manufacturing specifications. Japan's METI circular economy roadmaps are redirecting R&D investment toward mono-material structures compatible with existing sorting infrastructure. Stakeholders must calibrate material portfolios against divergent national compliance trajectories rather than pursuing uniform regional product strategies.
Market Dynamics
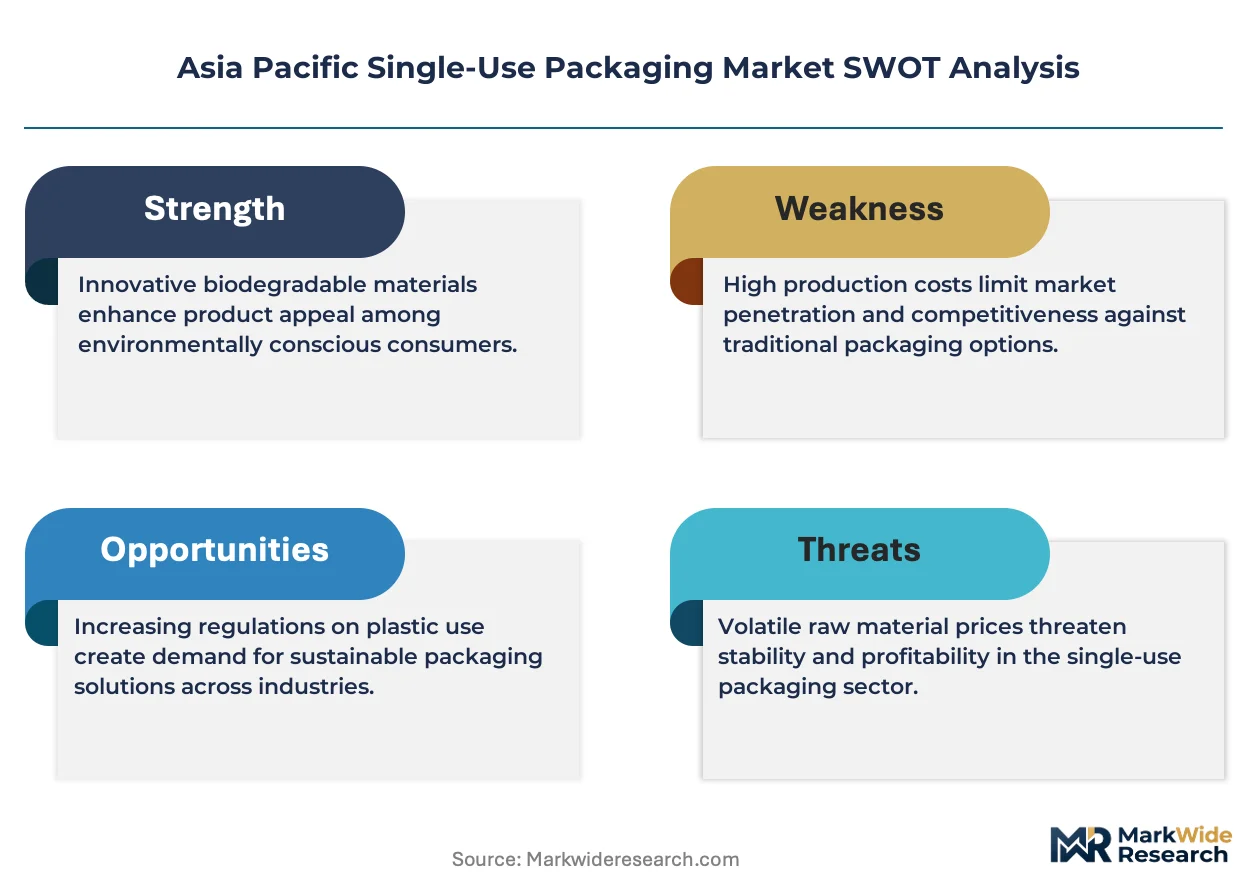
China's dual carbon goals and India's Plastic Waste Management Rules are forcing material recalibration across Asia Pacific single-use packaging, compressing virgin polymer demand while redirecting capital toward mono-material and fiber-based alternatives. Southeast Asian quick-service restaurant procurement is simultaneously scaling, creating divergent compliance and volume pressures.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian food service chains are scaling disposable container procurement to match outlet growth across Indonesia, Vietnam, and Thailand.
- India's urban retail corridor density:Modern trade penetration in Mumbai, Delhi, and Bangalore corridors is concentrating demand for pre-packaged food containment.
- Japan's METI circular economy roadmaps:These frameworks redirect R&D investment toward mono-material structures compatible with existing municipal sorting infrastructure.
Market Restraints
- Resin price volatility:Southeast Asian converters face margin compression from naphtha and propylene feedstock swings tied to regional refinery output.
- China's MEE extended producer responsibility:Compliance cost elevation for non-recyclable formats is forcing portfolio rationalization among multinational brand owners.
- Technical limitation in barrier performance:Molded fiber and PLA alternatives still fail moisture and oxygen specifications required for fresh protein distribution.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Modern trade and food service packaging intensity lags Thailand and Malaysia by substantial gaps, offering white space for format introduction.
- E-commerce fulfillment specification evolution:Void-fill and mailer demand is rotating toward lighter gauge films and paper-based cushioning across Australian and Japanese logistics networks.
- Australian food service biodegradable mandate trajectory:State-level procurement preferences are creating premium positioning for certified compostable alternatives in institutional catering.
Industry Challenges
- Mono-material conversion capex intensity:Retooling extrusion and laminating lines for recyclable single-polymer structures demands substantial capital commitment from mid-scale converters.
- FSSAI-BIS certification timeline compression:India's joint food-contact material safety and labeling standard enforcement is extending product approval cycles for import-dependent brand owners.
- Legacy multi-layer inventory stranding:Existing stock of non-recyclable laminated films faces accelerated obsolescence risk under divergent national compliance trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Single-Use Packaging Market |
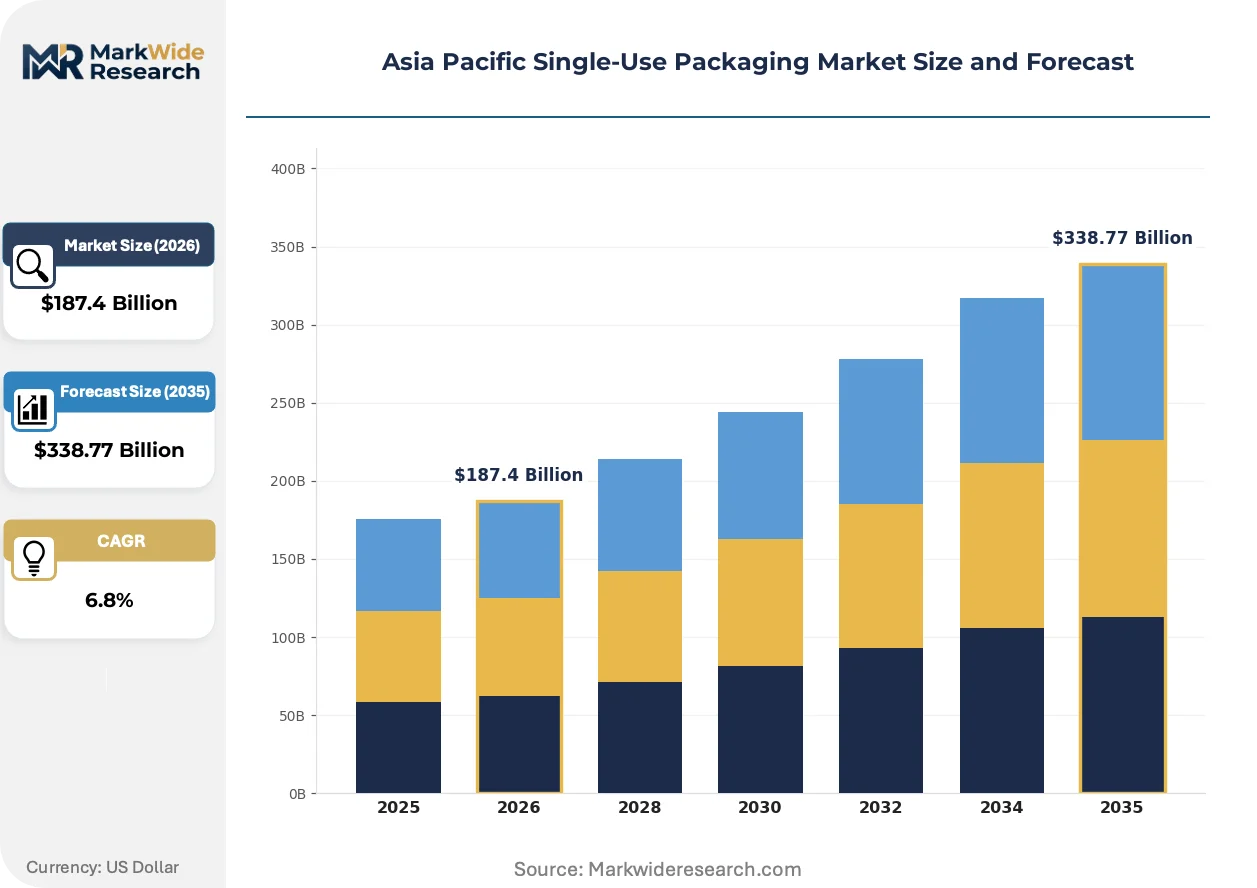
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Paper, Metal, Biodegradable End User: Food & Beverage, Cosmetics, Pharmaceuticals, Electronics Material: Polyethylene, Polypropylene, Paperboard, Aluminium Application: Retail, Food Service, E-commerce, Hospitality |
| Companies Covered | Berry Global Inc, Amcor Group GmbH, Huhtamaki Oyj, Hotpack Packaging Industries LLC, Graphic Packaging International, LLC, Sealed Air Corporation, Sonoco Products Company, Oji Holdings Corporation, Detpak - Detmold Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Single-Use Packaging Market Trends and Innovations
Active material science development and regulatory fragmentation are reshaping Asia Pacific single-use packaging toward modular, compliance-calibrated product architectures rather than uniform regional formats.
Water-based barrier coatings on molded fiber substrates are decentralizing the technical monopoly of multi-layer plastic laminates in fresh food containment. Japanese convenience retail chains and Australian ready-meal distributors are adopting these formats at accelerating pace. The shift is compressing demand for ethylene-vinyl alcohol copolymers and aluminum oxide metallization in chilled distribution.
China's MEE extended producer responsibility frameworks are elevating compliance costs for non-recyclable formats and forcing brand owners to pre-register packaging formats against recyclability tiers. Industrial consequence includes accelerated phase-out of black plastic trays and PVC labels in favor of detectable mono-polymer alternatives. Fresh produce and protein segments are responding fastest through specification changes in annual supplier contracts.
Food service procurement is consolidating toward direct converter relationships, bypassing traditional distribution intermediaries in Southeast Asian markets. Quick-service restaurant chains in Indonesia and Vietnam are establishing volume commitments with film extruders and thermoformers for customized container specifications. This pattern is most visible in poultry and seafood quick-service verticals where hygiene assurance and traceability requirements override price sensitivity.
Asia Pacific Single-Use Packaging Market Segmentation
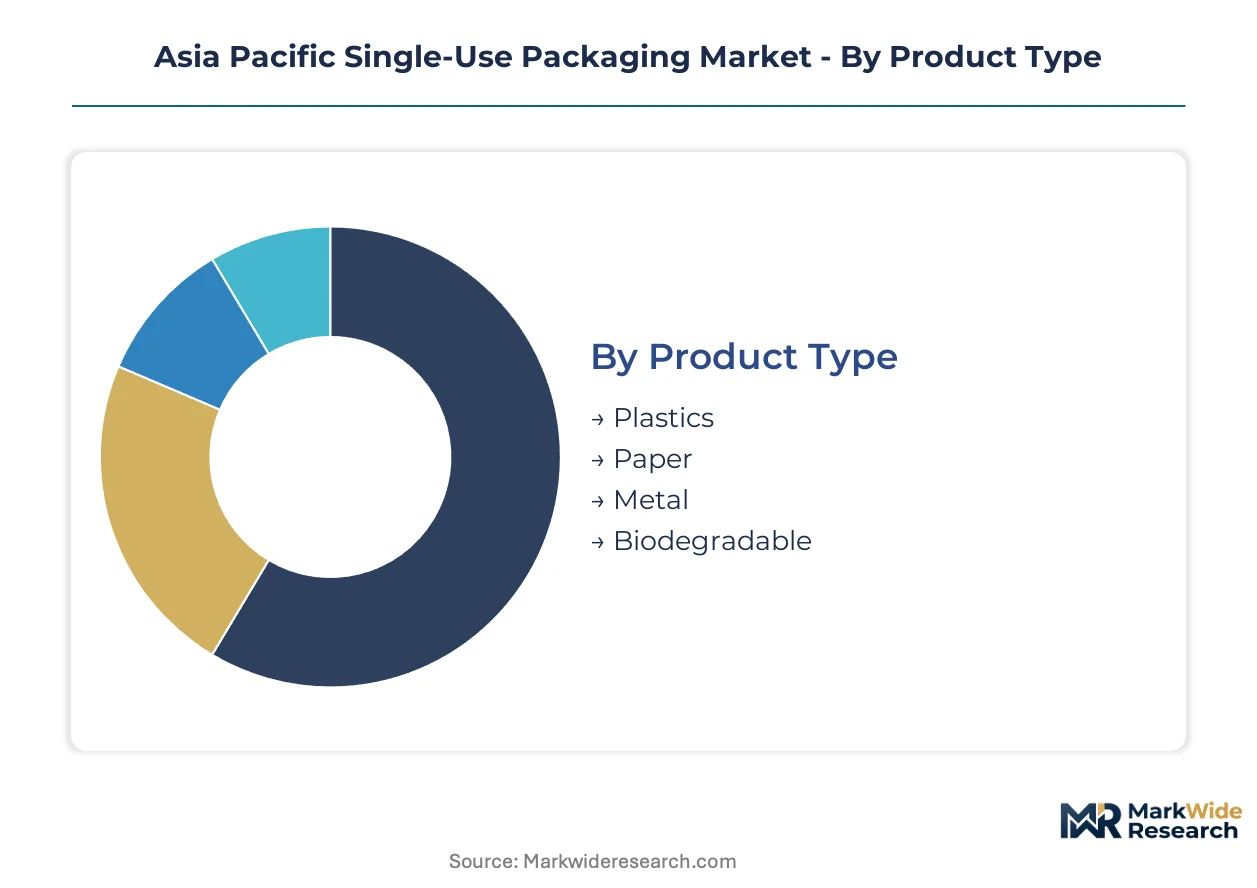
Material portfolios across Asia Pacific single-use packaging require granular calibration against divergent national compliance trajectories. Each segmentation dimension reveals distinct procurement patterns shaped by regulatory pressure and end-use specification intensity.
Product Type:
Standalone disposable formats dominate food service and retail distribution, while embedded barrier systems integrate into automated packaging lines for protein processing and pharmaceutical distribution.
- Plastics:Thermoformed films and extruded foams deliver moisture barriers and structural rigidity for fresh protein and ready-meal containment. Demand concentrates in Southeast Asian quick-service restaurant chains across Indonesia, Vietnam, and Thailand where outlet expansion outpaces reusable infrastructure investment.
- Paper:Molded fiber substrates with water-based barrier coatings are displacing multi-layer laminates in Japanese convenience retail and Australian ready-meal distribution. China's MEE extended producer responsibility frameworks accelerate this shift by elevating compliance costs for non-recyclable plastic formats.
- Metal:Aluminium trays and foils serve premium pharmaceutical and cosmetic applications requiring absolute light and oxygen exclusion.
- Biodegradable:PLA and PHA alternatives capture institutional catering procurement in Australian states with certified compostable mandates.
Volume placements concentrate in Plastics; the faster expansion belongs to Biodegradable.
End User:
Cost tier stratification separates high-specification containment from commodity disposable procurement across customer categories.
- Food & Beverage:The deepest procurement pools span quick-service restaurant networks, urban retail corridors in Mumbai and Delhi, and e-commerce fulfillment specifications. India's FSSAI-BIS joint enforcement on food-contact material safety extends product approval cycles for import-dependent brand owners.
- Cosmetics:Premium mono-material tubes and jars serve Japanese and South Korean beauty retail where shelf aesthetics override cost minimization.
- Pharmaceuticals:Blister packs and unit-dose pouches demand validated barrier performance against moisture and oxygen ingress.
- Electronics:Anti-static films and molded foam cushioning protect high-value components through Australasian and Japanese logistics networks.
Procurement scale peaks in Food & Beverage; Electronics climbs the fastest on e-commerce fulfillment specification evolution.
Material:
Supply concentration patterns differentiate between resin commodities with refinery-linked volatility and fiber substrates with agricultural feedstock exposure.
- Polyethylene:LDPE and LLDPE films dominate void-fill and mailer applications across Australian and Japanese e-commerce networks. Lighter gauge specifications are displacing heavier legacy formats as logistics operators optimize dimensional weight pricing.
- Polypropylene:Oriented films and injection-molded containers serve hot-fill and retort applications in Southeast Asian food processing. Margin compression from naphtha and propylene feedstock swings tied to regional refinery output constrains converter profitability.
- Paperboard:Folding cartons and foodservice containers leverage existing municipal sorting infrastructure compatibility under Japan's METI circular economy roadmaps.
- Aluminium:Foil laminates and trays retain niche positioning in pharmaceutical and premium food segments despite energy-intensive production profiles.
Consumption scale centers on Polyethylene; Paperboard gains share fastest on mono-material conversion mandates.
Application:
Customer type segmentation separates institutional procurement with traceability requirements from consumer-facing formats prioritizing shelf appeal.
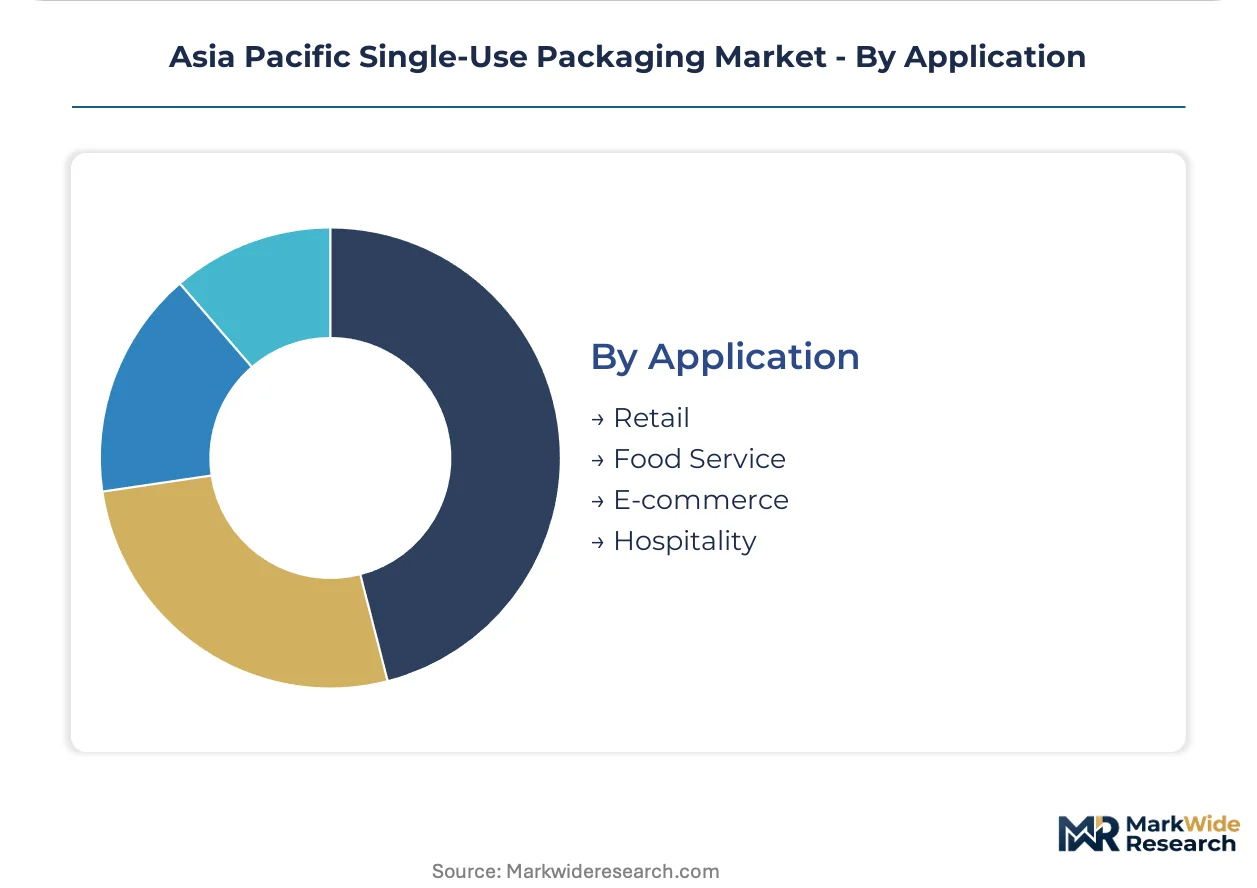
- Retail:Pre-packaged produce and protein containment drives specification intensity in India's modern trade corridors. Mumbai, Delhi, and Bangalore concentration creates demand density for barrier-coated formats.
- Food Service:Direct converter relationships are consolidating in Indonesia and Vietnam as quick-service restaurant chains bypass distribution intermediaries for customized container specifications.
- E-commerce:Void-fill and mailer demand rotates toward lighter gauge films and paper-based cushioning across Australian and Japanese logistics networks.
- Hospitality:Institutional catering in Australian states with biodegradable procurement preferences creates premium positioning for certified compostable alternatives.
Shipment value concentrates in Retail; E-commerce represents the steepest expansion trajectory on fulfillment specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock concentration along China's eastern seaboard and the Strait of Malacca supply corridor anchors manufacturing capacity for Asia Pacific single-use packaging. Regional resin production clusters determine converter economics across thermoformed and extruded formats.
China
Yangtze River Delta thermoformers supply quick-service restaurant chains with polypropylene containers for hot-fill applications. MEE extended producer responsibility frameworks force brand owners to pre-register packaging against recyclability tiers. Guangdong province converters accelerate phase-out of black plastic trays in favor of detectable mono-polymer alternatives for fresh produce distribution.
India
Mumbai-Delhi-Bangalore urban retail corridors concentrate demand for pre-packaged food containment in modern trade formats. BIS and FSSAI joint enforcement on food-contact material safety extends product approval cycles for import-dependent brand owners. Maharashtra state hosts the deepest procurement pools for barrier-coated flexible packaging serving protein processors.
Japan
Convenience retail chains in Tokyo-Osaka metropolitan corridors adopt water-based barrier coatings on molded fiber substrates at accelerating pace. METI circular economy roadmaps redirect R&D investment toward mono-material structures compatible with existing municipal sorting infrastructure. Kanto region converters compress demand for ethylene-vinyl alcohol copolymers in chilled distribution applications.
Vietnam
Ho Chi Minh City quick-service restaurant networks scale disposable container procurement to match outlet expansion across poultry and seafood verticals. National plastic waste management directives tighten material compliance timelines for food service procurement. Mekong Delta converters establish direct volume commitments with regional food service chains, bypassing traditional distribution intermediaries.
Australia
Sydney-Melbourne logistics networks rotate void-fill and mailer demand toward lighter gauge films and paper-based cushioning for e-commerce fulfillment. State-level procurement preferences in institutional catering create premium positioning for certified compostable alternatives. Victorian food service operators drive specification intensity for biodegradable mandates in quick-service and hospitality segments.
Asia Pacific Single-Use Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty barrier coatings and fiber-based alternatives. The market structure consolidates around multinational converters with integrated laminating and extrusion capabilities alongside regional specialists serving quick-service restaurant procurement. Three archetypes dominate: resin-integrated conglomerates with refinery-linked feedstock security, film extruders with direct food service relationships, and fiber substrate specialists capitalizing on mono-material conversion mandates. Competitive moves center on capacity expansion in Vietnam and Indonesia alongside portfolio diversification into detectable mono-polymer formats.
Among the named participants, Amcor Group GmbH and Huhtamaki Oyj represent the multinational converter archetype with regional laminating and beverage cup manufacturing footprints. Sealed Air Corporation exemplifies the automation-integrated tier through food packaging system deployment. These entities anchor competitive positioning without constituting an exhaustive market map.
| Leading Market Players |
|---|
| Berry Global Inc |
| Amcor Group GmbH |
| Huhtamaki Oyj |
| Hotpack Packaging Industries LLC |
| Graphic Packaging International, LLC |
| Sealed Air Corporation |
| Sonoco Products Company |
| Oji Holdings Corporation |
| Detpak - Detmold Group |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up resin converters across Southeast Asia are consolidating extrusion capacity to secure feedstock pricing power against naphtha volatility, while simultaneously unbundling technical service from base resin supply to capture premium pricing on compliance-certified grades.
Pricing Analysis
Service bundling separates technical consultation and barrier-coating formulation support from commodity resin supply, with Chinese and Indian converters charging separately for FSSAI-BIS pre-certification assistance. Three-tier pricing structure across premium, standard, and economy levels stratifies by recyclability tier and mono-material detectability, with China's MEE pre-registration requirements widening spreads between compliant and legacy formats. Pricing pressure stems from polypropylene margin compression as regional refinery output swings destabilize propylene feedstock costs. Quick-service restaurant chains in Indonesia and Vietnam exhibit highest price sensitivity, while Japanese convenience retail operators absorb premiums for METI-aligned mono-material specifications.
Supply Chain Analysis
Domestic-content mandates in India's Plastic Waste Management Rules and China's MEE extended producer responsibility frameworks are redirecting sourcing toward local extrusion and thermoforming capacity, displacing import-dependent supply relationships. Manufacturing gravity centers on China, India, and Vietnam, with Yangtze River Delta and Ho Chi Minh City clusters anchoring thermoformed container output. Feedstock draws from naphtha crackers along the Strait of Malacca and polyethylene resin from Saudi and Singaporean petrochemical complexes. Single-source vulnerability concentrates in metallized film and ethylene-vinyl alcohol barrier resin supply. Distribution runs through direct converter relationships in Southeast Asian food service, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where India's BIS-FSSAI joint enforcement and China's MEE pre-registration create regulatory moats favoring incumbents with dedicated certification infrastructure and local testing partnerships.
For Market Incumbents: Acquire stranded mono-material conversion assets in Vietnam and Indonesia to consolidate extrusion capacity ahead of regional compliance harmonization. Defend margin position by embedding FSSAI-BIS pre-certification services into annual supplier contracts, locking out import-dependent competitors facing extended approval cycles. Prioritize backward integration into water-based barrier coating formulation to capture premium positioning as Japanese and Australian procurement shifts away from multi-layer laminates. For New Entrants and Emerging Players: Fiber-based barrier coating platforms offer entry points into Australian institutional catering and Japanese convenience retail where certified compostable mandates outpace incumbent plastic converter adaptation. White space concentrates in Philippine and Vietnamese quick-service restaurant supply, where modern trade penetration lags Thailand and Malaysia by substantial gaps. Establish direct volume commitments with poultry and seafood chains, bypassing distribution intermediaries to secure specification influence before multinational converters consolidate relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Vietnamese and Indian thermoformers with stranded multi-layer inventory and urgent recapitalization needs, positioned for mono-material retooling under MEE and Plastic Waste Management Rule deadlines. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale, with acquisition targets requiring demonstrable BIS-FSSAI testing partnerships or METI-aligned R&D pipelines. Monitor China's detectable mono-polymer phase-out velocity as the signal indicating compliance-premium sustainability across the region.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Conversion Capacity Expansion | Retooling extrusion lines for MEE recyclability tiers captures premium positioning in Chinese fresh produce distribution. |
| Backward Integration into Barrier Coating Formulation | In-house water-based coating production secures margin control as Japanese convenience retail displaces metallized laminates. |
| Direct Converter Relationship Consolidation | Bypassing distributors in Indonesian and Vietnamese quick-service restaurant procurement locks in volume commitments. |
| Regulatory Certification Infrastructure Investment | Dedicated BIS-FSSAI testing partnerships create entry barriers against import-dependent brand owners in Indian urban retail. |
| Biodegradable Alternative Product Line Launch | Certified compostable formats capture Australian state-level institutional catering mandates ahead of incumbent adaptation. |
Research Methodology
Multi-period observation of resin price spreads, regulatory filing timelines, and quick-service restaurant outlet expansion anchored the trend analysis, supplemented by interviews with plant managers at Southeast Asian extrusion facilities, procurement leads at Indonesian and Vietnamese food service chains, technical R&D directors at barrier coating developers, and distribution channel partners across Australian logistics networks. Secondary validation drew from customs and trade data tracking polyethylene and polypropylene resin flows, MEE and BIS regulatory filings, SEC 10-K disclosures from listed packaging converters, and ACC regional production reports. Bottom-up volume estimates from converter capacity utilization and top-down demand calibration from end-use procurement patterns were triangulated to ensure consistency.
Segment-weighting across material type, end-use application, and geographic regulatory cluster shaped the analytical framework, with polyethylene, polypropylene, paperboard, and biodegradable alternatives modeled separately alongside food and beverage, cosmetics, pharmaceutical, and electronics end-use splits. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules across the analysis window. Industry-specific forecast inputs included MEE pre-registration compliance cost trajectories and FSSAI-BIS approval cycle extensions for import-dependent market participants.
Several conditions sit outside the modeled scope, including abrupt feedstock supply disruptions from Strait of Malacca logistics chokepoints, unilateral tariff escalations affecting resin trade flows, and technological breakthroughs in enzymatic recycling altering mono-material conversion economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market