
 Indonesia Flexible Plastic Packaging Market | 2026-2036
Indonesia Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Flexible Plastic Packaging Market Insights
Indonesian resin converters and multinational film producers is decoupling from traditional supply assumptions as domestic polymer output lags behind converter demand. Amcor PLC leverages its regional technical service network to secure long-term supply contracts with Southeast Asian brand owners. PT Berlina anchors its position through backward integration into blown film extrusion, reducing resin cost volatility. Mondi Group competes on sustainability credentials, offering recyclable mono-material structures that meet emerging retailer requirements.
Indonesia flexible plastic packaging encompasses multilayer films, pouches, and sleeves engineered from LDPE, HDPE, PET, and BOPP substrates, typically produced via coextrusion, lamination, or printing processes to deliver moisture barriers, oxygen resistance, and printability for shelf-ready presentation. Stand-up pouches capture premium margin pools as beverage and sauce brands shift from rigid containers to lightweight flexible formats. Roll stock dominates volume throughput, supplying form-fill-seal operations across Java's food processing corridor. BOPP films sustain growth in snack and confectionery wrapping, where clarity and stiffness drive replacement of cellophane and metallized alternatives.
BIS-equivalent Indonesian National Standards and the Ministry of Environment and Forestry's extended producer responsibility framework shape material choices, pushing converters toward recyclable or compostable film structures to maintain market access. The country's central bank and trade ministry monitor resin import flows, influencing working capital cycles for film producers dependent on polyethylene and polypropylene feedstock. Stakeholders must track enforcement timelines for plastic waste regulations and assess whether domestic resin capacity expansions alter import dependency ratios for key substrate grades.
Market Dynamics
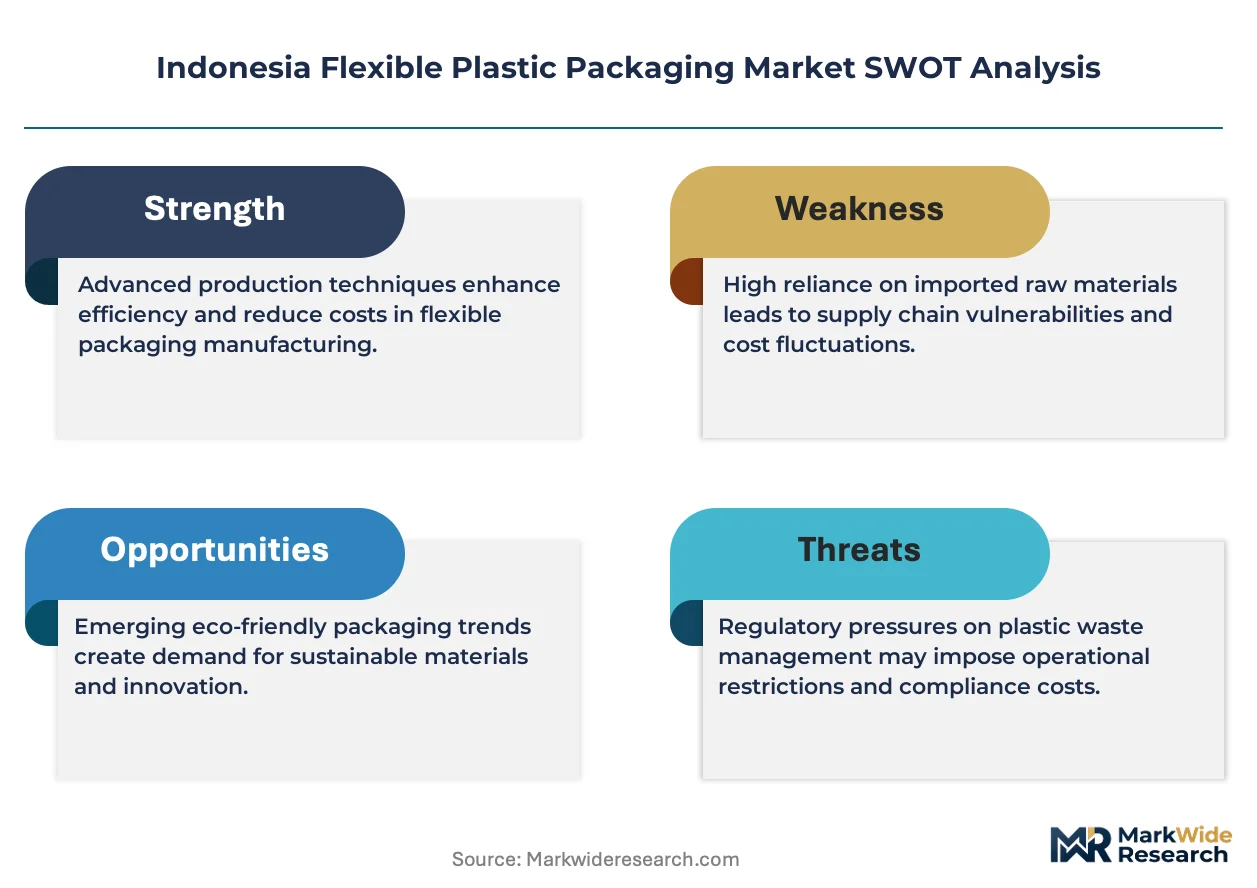
Indonesian flexible packaging converters face a structural squeeze between the Ministry of Environment and Forestry's tightening extended producer responsibility mandates and the persistent gap between domestic resin output and converter demand, forcing material substitution decisions ahead of cost parity.
Growth Catalysts
- EPR Regulatory Pressure:The Ministry of Environment and Forestry's extended producer responsibility framework mandates brand owners to fund collection infrastructure, accelerating demand for recyclable mono-material films that converters can certify compliant.
- Beverage Format Migration:Sauce and ready-to-drink brands across Java's food processing corridor are abandoning rigid bottles for stand-up pouches, creating pull for high-barrier coextruded structures with spout fitments.
- Snack Export Expansion:Indonesian palm oil-based snack manufacturers targeting halal-certified export markets require BOPP and metallized films with extended shelf-life performance, sustaining investment in multilayer lamination capacity.
Market Restraints
- Resin Import Dependency:Domestic polyethylene and polypropylene production lags converter requirements, exposing film producers to working capital cycles dictated by central bank monitoring of resin import flows and currency volatility.
- Collection Infrastructure Gaps:Post-consumer flexible film recovery rates remain minimal outside Java's industrial corridor, limiting the feedstock availability mechanical recyclers need to achieve viable scale for food-contact approved regranulate.
- Cellulose Alternative Competition:Paper-based flexible packaging with barrier coatings is capturing premium shelf space in European export channels where retailers enforce plastic reduction timelines ahead of Indonesian converter readiness.
Strategic Opportunities
- Sumatra and Sulawesi Penetration:Converting capacity concentrates on Java, leaving food processing clusters in Medan and Makassar underserved for technical film supply and local technical service coverage.
- Compostable Film Certification:BIS-equivalent Indonesian National Standards for industrial compostability remain sparsely adopted, offering first-mover positioning for converters achieving certification ahead of mandatory biodegradability windows.
- Digital Print Convergence:Combination of narrow-web flexography with inline spectrophotometric color management enables shorter run lengths for regional brand owners, collapsing minimum order quantities that previously favored gravure imports.
Industry Challenges
- Barrier Chemist Scarcity:Formulation expertise for oxygen-scavenging and moisture-barrier adhesive layers concentrates with senior technical staff at multinational film producers, constraining domestic converter R&D velocity.
- Legacy Equipment Retrofit Burden:Solvent-based lamination lines predominate across Indonesia's converting base, requiring substantial capex for aqueous or solventless adhesive conversion to meet volatile organic compound emission thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Flexible Plastic Packaging Market |
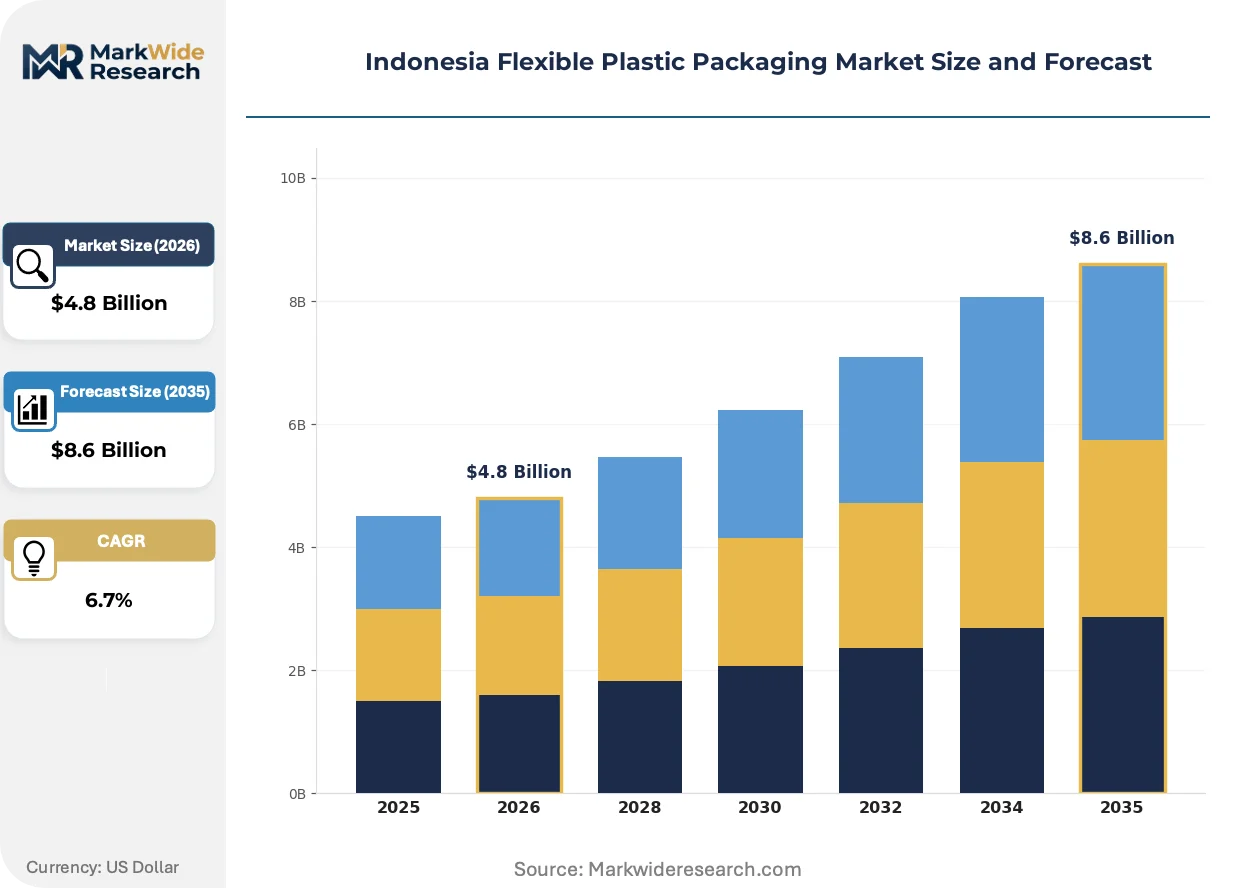
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Sleeves, Lay-Flat Bags, Roll Stock Material: LDPE, HDPE, PET, BOPP Application: Food & Beverage, Personal Care, Healthcare, Household End User: Manufacturers, Retailers, Distributors, E-Commerce |
| Companies Covered | Amcor PLC, PT Toppan Indonesia Printing, Sonoco Products Company, PT ePac Flexibles Indonesia, Primajaya Eratama, PT Berlina, Mondi Group, Constantia Flexibles, SWC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Flexible Plastic Packaging Market Trends and Innovations
Material science advances and enforcement timelines for plastic waste regulations are compressing the viable technology set for Indonesian converters, privileging solutions that satisfy both performance specifications and emerging retailer sustainability requirements.
Mono-material polyethylene structures with ethylene-vinyl alcohol coextrusion barriers are rewriting the technical feasibility of recyclable high-performance packaging. Instant noodle and cooking oil brands in Surabaya and Jakarta are specifying these films for pilot line trials. The shift is collapsing the historical trade-off between barrier performance and mechanical recyclability that favored complex multilayer constructions.
The Ministry of Environment and Forestry's extended producer responsibility implementation roadmap imposes phased waste collection targets on brand owners above specified revenue thresholds. Film converters must document recyclability or compostability credentials to maintain supply relationships with affected packaged goods manufacturers. Mid-tier converters without certification partnerships face exclusion from tender processes for multinational brand owner contracts.
Brand owner technical buyers are consolidating supplier panels and demanding form-fill-seal roll stock with integrated track-and-trace coding capabilities. Traditional trading houses serving regional processors are losing share to direct converter relationships supported by regional technical service teams. The pattern is most pronounced in Bekasi and Tangerang industrial zones where beverage co-packers operate at scale.
Indonesia Flexible Plastic Packaging Market Segmentation
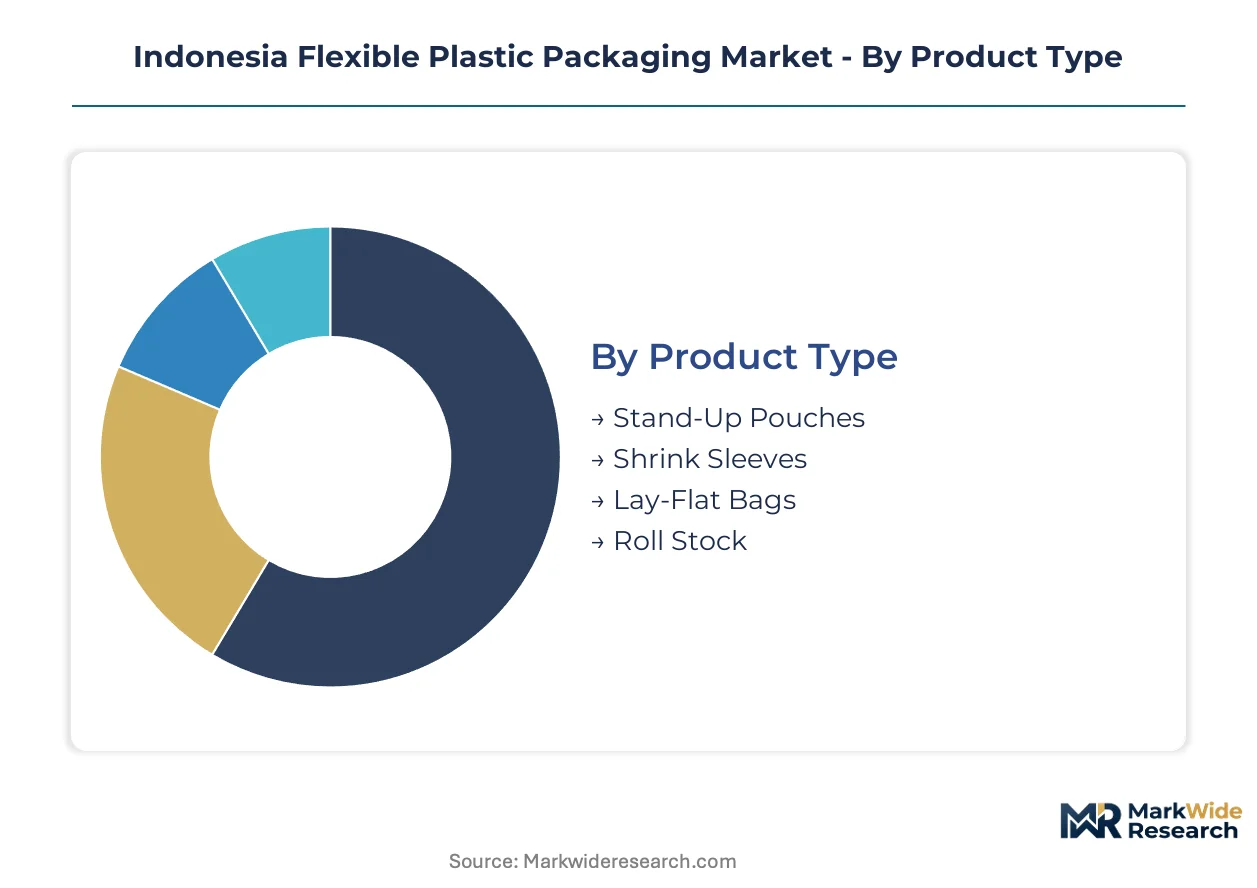
Indonesian converters configure production lines around specific product geometries and material specifications that determine barrier performance, filling speeds, and shelf-ready presentation. Segment boundaries are hardening as brand owners consolidate supplier panels around certified film structures that satisfy Ministry of Environment and Forestry extended producer responsibility mandates.
Product Type:
Stand-alone pouch formats compete with continuous roll-fed systems for placement on Java's form-fill-seal lines, with integration depth varying by brand owner scale and technical service requirements.
- Stand-Up Pouches:Coextruded or laminated structures with bottom gussets and optional spout fitments deliver shelf stability and consumer convenience. Beverage and sauce manufacturers in Bekasi and Tangerang industrial zones are specifying high-barrier versions with ethylene-vinyl alcohol layers for oxygen-sensitive contents.
- Roll Stock:Continuous web formats supply high-speed form-fill-seal operations across Java's food processing corridor, dominating volume throughput through economies of scale and minimal changeover downtime.
- Shrink Sleeves:Heat-contractable films conform to irregular container geometries for 360-degree decoration and tamper evidence.
- Lay-Flat Bags:Simple two-seal constructions serve bulk commodity and institutional foodservice channels where cost minimization outweighs shelf presentation requirements.
Volume placements concentrate in roll stock; the faster expansion belongs to stand-up pouches.
Material:
Substrate selection traces directly to barrier requirements, mechanical recyclability credentials, and resin cost exposure under Indonesia's import-dependent supply structure.
- BOPP:Biaxially oriented polypropylene films deliver optical clarity, stiffness, and moisture barrier for snack and confectionery wrapping. Palm oil-based snack manufacturers targeting halal-certified export markets specify metallized BOPP variants for extended shelf-life performance.
- LDPE:Low-density polyethylene dominates multilayer coextrusion as the sealant layer and provides the foundation for recyclable mono-material structures now specified by instant noodle and cooking oil brands in Surabaya and Jakarta.
- PET:Polyester films contribute dimensional stability and printability to lamination structures for premium personal care applications.
- HDPE:High-density polyethylene serves heavy-duty shipping sacks and industrial liners where puncture resistance and load-bearing capacity take priority over optical properties.
LDPE commands the largest volume position; BOPP is climbing the fastest as snack export requirements intensify.
Application:
End-use sector specifications diverge sharply on barrier performance, regulatory compliance burden, and sustainability certification requirements.
- Food & Beverage:Oxygen and moisture barrier specifications, halal certification, and Ministry of Environment and Forestry recyclability documentation dominate procurement criteria. This segment absorbs the majority of technical film innovation and converter R&D investment.
- Personal Care:Laminated structures with premium print quality and fragrance barrier properties serve shampoo, conditioner, and cosmetic sampler formats.
- Healthcare:Sterile barrier films and child-resistant packaging structures face stringent validation requirements and extended qualification timelines.
- Household:Detergent and cleaning product pouches prioritize chemical resistance and cost minimization over optical clarity or shelf differentiation.
Food and beverage anchors volume demand; healthcare presents the steepest expansion trajectory as domestic pharmaceutical manufacturing scales.
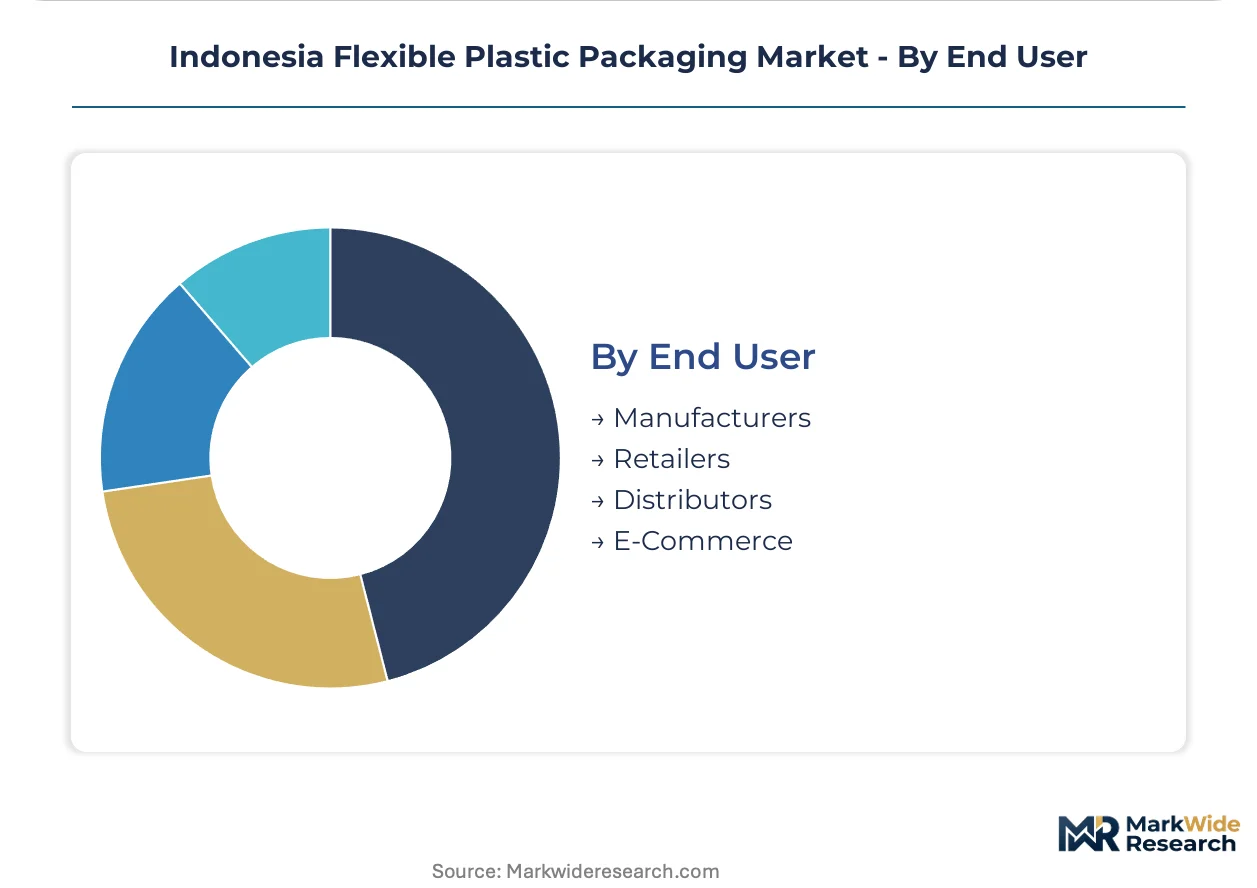
End User:
Customer type determines order configuration, technical service intensity, and contract structure across Indonesia's converting base.
- Manufacturers:Brand owners and co-packers with direct converter relationships specify custom film structures, demand integrated track-and-trace coding, and consolidate supplier panels around certified sustainability credentials.
- Retailers:Private label programs and shelf-ready packaging specifications drive standardized pouch formats with shorter lead times and volume commitment flexibility.
- Distributors:Trading houses serving regional processors outside Java's industrial corridor are losing share to direct converter relationships as technical service requirements intensify.
- E-Commerce:Protective mailer and void-fill formats prioritize puncture resistance and lightweighting for last-mile cost optimization.
Manufacturers represent the dominant volume channel; e-commerce is gaining share fastest as fulfillment infrastructure expands beyond Java.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene and polypropylene feedstock availability concentrates on Java's northern coast, where import terminals and converting clusters align to minimize resin logistics costs.
Java
Instant noodle manufacturers in Surabaya and Bekasi drive laminated film demand for oxygen-sensitive seasonings. The Ministry of Environment and Forestry's extended producer responsibility mandates push brand owners toward recyclable mono-material specifications. Tangerang industrial zone hosts beverage co-packers converting rigid formats to stand-up pouches with spout fitments.
Sumatra
Palm oil-based snack exporters in Medan require metallized BOPP films with extended shelf-life barriers for halal-certified Middle Eastern markets. The country's national standards body evaluates industrial compostability certifications for emerging biodegradable alternatives. Converting capacity remains underdeveloped relative to food processing scale, forcing reliance on Java-based suppliers.
Sulawesi
Seafood processors in Makassar specify high-barrier vacuum pouches for frozen export shipments to East Asian markets. Central bank monitoring of resin import flows extends working capital cycles for regional distributors serving this corridor. Local technical service coverage gaps disadvantage trading houses against direct converter relationships.
Kalimantan
Edible oil refineries in Balikpapan and Samarinda source heavy-duty shipping sacks for bulk commodity distribution across the archipelago. Ministry of Trade import licensing procedures for polyethylene grades create procurement bottlenecks during currency volatility periods. Industrial packaging demand outpaces local film extrusion infrastructure, sustaining cross-shipment dependencies.
Bali and Eastern Islands
Tourism-driven foodservice channels in Denpasar generate pull for portion-control pouches and disposable packaging formats. Limited mechanical recycling infrastructure constrains post-consumer film recovery rates outside Java's industrial corridor. E-commerce fulfillment expansion drives protective mailer demand as logistics networks penetrate secondary cities.
Indonesia Flexible Plastic Packaging Market Competitive Landscape
Global majors compete with regional champions across technical service intensity and sustainability certification depth. Market structure tilts toward consolidation at the premium tier, where multinational film producers leverage regional R&D networks, while mid-tier segments fragment across domestic converters with varying backward integration levels. Three archetypes dominate: multinational integrated producers with certified recyclable portfolios, domestic converters with captive blown film capacity, and trading houses losing share to direct technical relationships. Capacity expansion and supplier panel consolidation constitute the dominant competitive moves as brand owners reduce approved vendor lists.
Among the multinational integrated tier, Amcor PLC and Mondi Group exemplify archetypes built on regional technical service networks and sustainability credentials respectively. PT Berlina anchors the domestic converter segment through backward integration into blown film extrusion. These three occupy positions that reflect divergent strategic responses to Ministry of Environment and Forestry mandates—certification partnerships versus captive resin processing versus recyclable structure development.
| Leading Market Players |
|---|
| Amcor PLC |
| PT Toppan Indonesia Printing |
| Sonoco Products Company |
| PT ePac Flexibles Indonesia |
| Primajaya Eratama |
| PT Berlina |
| Mondi Group |
| Constantia Flexibles |
| SWC |
| Others |
Pricing and Supply Chain Analysis
Brand owner procurement teams in Java's food processing corridor concentrate purchasing power for technical film specifications, forcing a contract-based long-term offtake pricing model that locks in volume commitments against resin cost volatility. This buyer concentration privileges converters with certified recyclability credentials and integrated technical service networks.
Pricing Analysis
Technical service bundling separates premium converter relationships from commodity trading house arrangements, with after-sales support and color management included in direct contracts but unbundled in spot transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with Ministry of Environment and Forestry EPR-compliant films commanding margin premiums. Cost compression in mid-tier roll stock intensifies because resin import dependency exposes producers to central bank currency monitoring. Small regional processors outside Java exhibit highest price sensitivity, while multinational beverage co-packers prioritize barrier performance over unit cost.
Supply Chain Analysis
Freight costs from Singapore and Thailand polyethylene terminals to Java's northern coast converting clusters constitute a material share of delivered resin economics, privileging backward-integrated domestic producers. Supply concentrates in Saudi Arabia, South Korea, and Singapore for polyethylene feedstock, with Indonesia's domestic output lagging converter demand. Raw material dependencies rest on ethylene-vinyl alcohol copolymers, metallized BOPP substrates, and solvent-based adhesives. Single-source vulnerability runs through Singapore's polymer trading hub, where central bank foreign exchange procedures create working capital bottlenecks. Distribution feeds from import terminals through regional trading houses to direct converter relationships with technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indonesia flexible plastic packaging market operates as a cost-of-compliance arena where the Ministry of Environment and Forestry's extended producer responsibility framework erects a certification barrier-to-entry moat favoring prepared incumbents.
For Market Incumbents: Anticipate supplier panel consolidation by accelerating certification partnerships for industrial compostability under BIS-equivalent Indonesian National Standards ahead of mandatory biodegradability windows. Defend position by deepening backward integration into blown film extrusion to reduce resin cost volatility exposure from central bank import monitoring. Prioritize aqueous adhesive retrofit investments to meet volatile organic compound emission thresholds before enforcement timelines harden. For New Entrants and Emerging Players: Direct-to-brand technical service platforms offer a low-capital route to bypass entrenched trading house relationships in Sumatra and Sulawesi food processing clusters. Target Medan and Makassar converting capacity gaps with narrow-web flexography and inline spectrophotometric color management for shorter run lengths. Pursue compostable film certification as a first-mover positioning tool ahead of regulatory mandates. For Investors and Strategic Acquirers: The window for entry favors domestic converters with captive blown film capacity and established EPR certification partnerships. Long-term viability hinges on positioning for post-EPR enforcement consolidation when uncertified mid-tier players face tender exclusion. Monitor Ministry of Environment and Forestry waste collection target announcements as the inflection signal for compliance-driven market restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blown Film Extrusion | PT Berlina's captive resin processing reduces exposure to central bank import licensing volatility. |
| Industrial Compostability Certification | First-mover positioning under BIS-equivalent Indonesian National Standards secures tender access ahead of mandates. |
| Aqueous Adhesive Line Retrofit | Conversion from solvent-based lamination ensures volatile organic compound compliance for Bekasi and Tangerang operations. |
| Regional Technical Service Expansion | Direct converter relationships displace trading houses in Medan and Makassar food processing corridors. |
| Mono-Material Structure Development | Recyclable polyethylene-EVOH coextrusion meets retailer sustainability requirements for instant noodle and cooking oil brands. |
Research Methodology
Trade databases, Ministry of Environment and Forestry regulatory filings, and polymer import customs records formed the secondary backbone for resin flow and compliance timeline analysis. Primary interviews with blown film plant managers, brand owner packaging engineers, and trading house procurement leads validated capacity utilization assumptions and EPR implementation readiness. Bottom-up and top-down triangulation reconciled converter output estimates with end-use demand across Java's food processing corridor.
Bottom-up modeling of form-fill-seal line deployments and stand-up pouch conversion trials anchored volume projections across the analysis window. Segmentation dimensions included product geometry, substrate material, end-use sector, and customer type. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs incorporated Ministry of Trade import licensing procedures and BIS-equivalent Indonesian National Standards adoption trajectories.
Inputs from polymer trade associations and converter industry bodies were available through the study window; gaps in post-consumer collection infrastructure data introduce uncertainty bands around mechanical recyclability scaling assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market