
 Kenya Flexible Packaging Market | 2026-2036
Kenya Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Flexible Packaging Market Foresight
Food industry demand is rebalancing toward lightweight pouches for grains and dairy, pulling converter investment away from bulk sack formats. Huhtamaki Flexible Packaging Ltd leverages its multinational technical base to supply laminated barrier films for processed food brands. Statpack Ltd anchors domestic pouch production with localized printing and slitting capabilities. Silafrica Kenya Limited specializes in rigid-to-flexible conversion for pharmaceutical blister alternatives.
Flexible packaging comprises multi-layer films, foils, and papers engineered to 50-200 micron gauges, formed through extrusion, lamination, or coextrusion to provide moisture and oxygen barriers for perishable distribution. Plastic and polyethylene materials dominate current substrate volumes, though biodegradable grades are gaining trial placements under NEMA compliance pressure. Pouches represent the fastest-growing product type as brand owners downgauge from rigid containers. Food packaging applications command the deepest margin pools due to barrier specification complexity and volume scale.
Kenya Bureau of Standards enforces KS 1758 food contact safety rules, while NEMA operationalizes plastic waste regulations through producer compliance schemes. These frameworks raise technical barriers for informal converters and accelerate formal sector consolidation. Stakeholders must monitor enforcement consistency and substrate certification timelines to align capacity decisions with compliance-driven specification shifts.
Market Dynamics
NEMA's extended producer responsibility mandate is forcing converters to requalify substrate portfolios, accelerating formal sector consolidation while informal operators face technical exclusion from food contact supply chains.
Growth Catalysts
- Extended Producer Responsibility:NEMA's plastic waste compliance schemes create certified demand pools for biodegradable substrates among multinational food brands operating in Nairobi's industrial zone.
- Agricultural corridor expansion:Rift Valley grain processors are converting from bulk sacks to pre-formed pouches for export-ready packaging, pulling converter capacity toward high-barrier laminates.
- Barrier film innovation:Coextruded oxygen scavenger layers are replacing metalized structures in dairy applications, reducing material intensity while preserving shelf stability.
Market Restraints
- Resin import dependence:Polyethylene and polypropylene granule supply concentrates through Mombasa port infrastructure, exposing converters to currency-driven input cost volatility.
- Biodegradable certification backlog:Kenya Bureau of Standards' KS 1758 amendment timeline for compostable substrates creates specification uncertainty ahead of NEMA enforcement deadlines.
- Multilayer recycling incompatibility:Current mechanical recycling infrastructure cannot process laminated barrier films, limiting post-consumer recovery rates and circular economy claims.
Strategic Opportunities
- Pharmaceutical blister conversion:Rigid-to-flexible migration for tablet packaging opens margin pools above food-grade specifications, with CDSCO-equivalent compliance requirements creating technical moats.
- Coastal export hub development:Mombasa's emerging free trade zone positioning enables duty-advantaged supply to East African Community markets with harmonized packaging standards.
- Digital printing integration:Short-run variable data capability aligns with craft food brand proliferation, compressing minimum order quantities and enabling regionalized SKU strategies.
Industry Challenges
- Laminate technician scarcity:Solvent-based adhesive handling and tension control expertise concentrates among aging workforces at established converters, constraining new entrant scale-up.
- NEMA audit preparation burden:Producer compliance scheme documentation requirements demand dedicated regulatory staff that mid-cap converters struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Flexible Packaging Market |
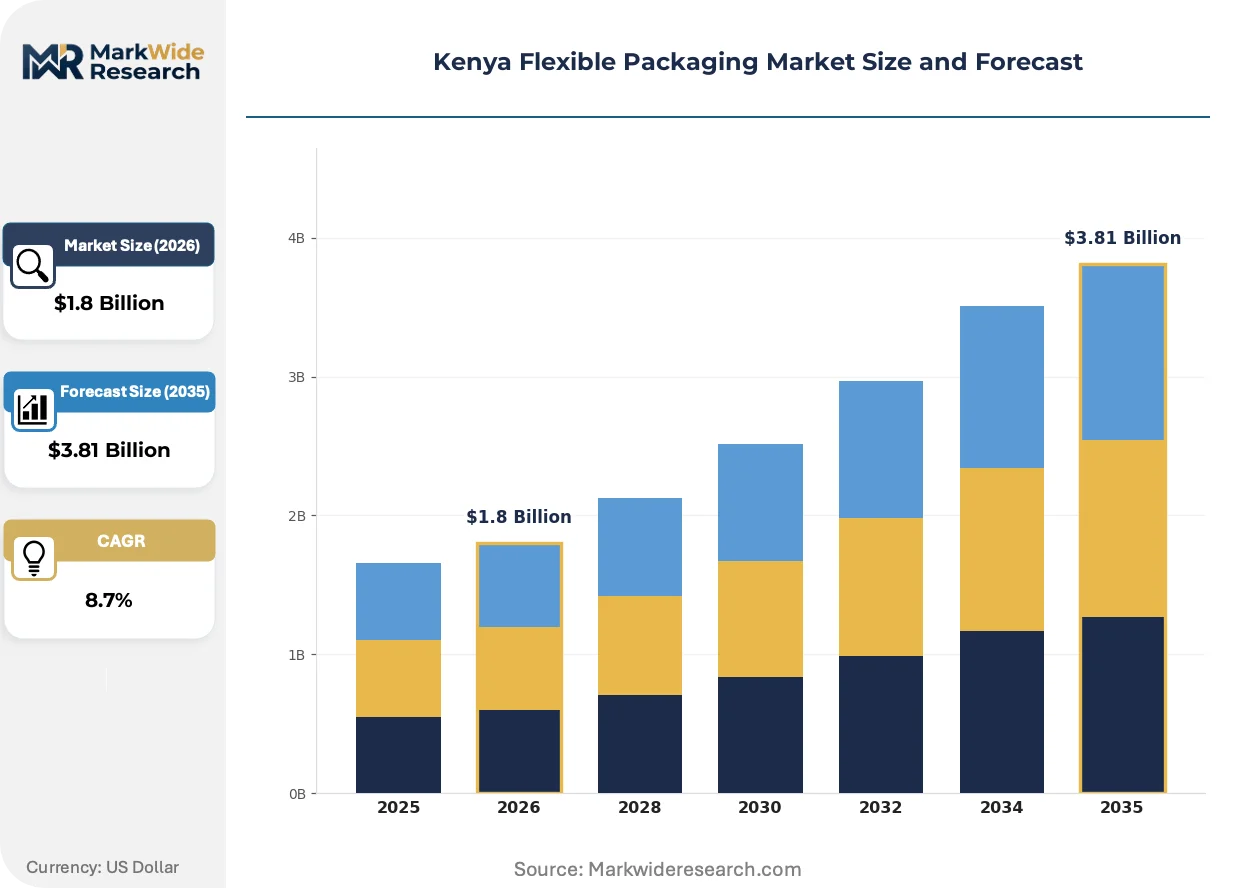
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Sacks, Pouches, Wraps Material: Plastic, Polyethylene, Biodegradable, Metalized Film Application: Food Packaging, Beverage Packaging, Healthcare Packaging, Personal Care Packaging End User: Food Industry, Pharmaceutical Industry, Cosmetics Industry, Consumer Goods |
| Companies Covered | Huhtamaki Flexible Packaging Ltd, Statpack Ltd, Platinum Packaging Ltd, Packaging Industries Ltd, Flexipac Limited, Polyflex Industries Limited, Dune Packaging Limited, Paperbags Ltd, Silafrica Kenya Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Flexible Packaging Market Shifts & Advancements
Digital workflow integration and substrate requalification are compressing product development cycles while regulatory pressure on plastic waste is redefining competitive advantage around certification depth rather than unit economics alone.
Water-based barrier coatings are integrating into food-grade film structures to replace solvent-laminated metalized layers, enabling heat-seal performance without volatile organic compound emissions. Nairobi-based converters serving dairy and snack brands are piloting these substrates at commercial scale. This integration is compressing the technical gap between regional suppliers and multinational film producers, allowing domestic converters to meet export-market barrier specifications.
NEMA's plastic waste regulations are operationalizing through mandatory producer registration and waste offset calculations, creating compliance infrastructure costs that favor converters with in-house regulatory teams. The enforcement mechanism prioritizes food contact packaging categories due to higher visibility and brand risk exposure. Formal sector operators are responding by consolidating substrate certification timelines and pre-qualifying biodegradable alternatives ahead of phased mandate expansion.
Brand owner specification teams are compressing supplier approval cycles from eighteen months to six months to match seasonal product launch windows, particularly in beverage and ready-to-eat segments. This acceleration favors converters with existing Kenya Bureau of Standards certifications and documented batch traceability systems. The shift is most visible among Nairobi-headquartered fast-moving consumer goods companies expanding pouch formats into traditional sachet-dominant categories.
Kenya Flexible Packaging Market Segmentation
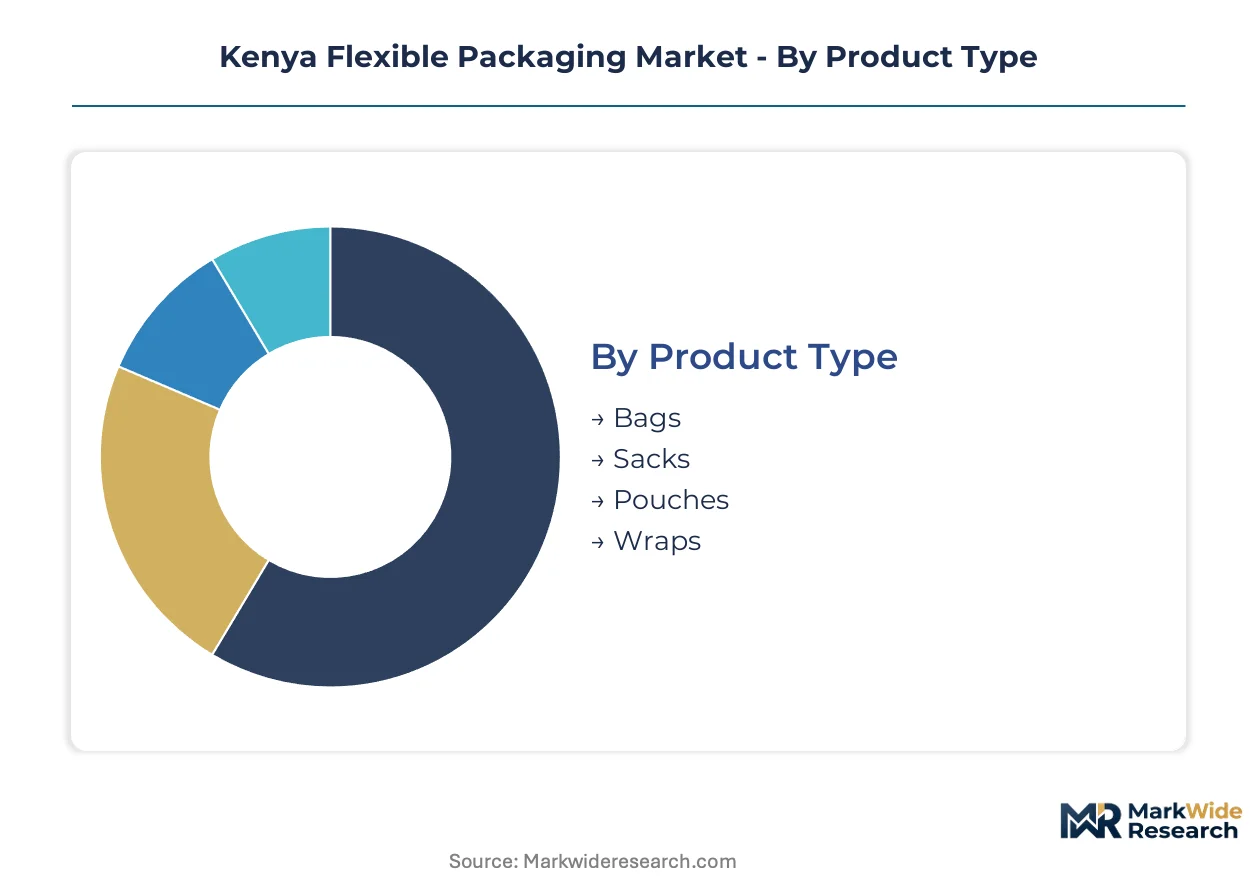
Flexible packaging in Kenya fragments across four intersecting dimensions that determine converter specialization and margin capture. Product type and material selection drive capital deployment, while application and end-user concentration shape regional capacity location.
Product Type:
Pouches demand the heaviest upfront investment in multilayer lamination lines and precision sealing equipment, while wraps require minimal specialized machinery.
- Pouches:Stand-up and flat pouches combine polyester, polyethylene, and aluminum layers through adhesive or extrusion lamination. Nairobi-based dairy processors and Rift Valley grain exporters are migrating bulk inventory into pre-formed pouches to reduce transport cube and shelf space. NEMA compliance timelines accelerate substrate requalification for this format.
- Bags:Side-seal and bottom-gusseted bags dominate polyethylene extrusion capacity, serving maize flour and sugar distribution through Kenya's informal retail network. Heat-seal strength specifications vary sharply between commodity grades and premium branded lines.
- Sacks:Woven polypropylene sacks retain volume in agricultural bulk transport, though flexible intermediate bulk containers are displacing share in export coffee and tea logistics.
- Wraps:Stretch and shrink wraps protect palletized goods through Mombasa port corridors; demand concentrates among consumer goods distributors with centralized warehousing.
Bags absorb the bulk of installed capacity; pouches are expanding most quickly.
Material:
Substrate selection determines barrier performance, regulatory compliance pathway, and end-market access.
- Plastic:Multilayer coextruded films combine nylon, EVOH, and polyethylene to achieve oxygen transmission rates below 1 cc/m²/day for processed meat and cheese applications. Kenya Bureau of Standards KS 1758 certification requirements concentrate converter expertise in Nairobi's industrial zone.
- Biodegradable:PLA and starch-based films are gaining trial placements under NEMA extended producer responsibility pressure, though composting infrastructure gaps limit commercial scale.
- Polyethylene:LDPE and LLDPE grades dominate cost-sensitive sachet and bag production, with resin imports through Mombasa exposing converters to currency volatility.
- Metalized Film:Vacuum-deposited aluminum layers provide moisture and light barriers for snack and pharmaceutical applications; oxygen scavenger coatings are displacing share in dairy segments.
Plastic retains the deepest converter specialization; biodegradable grades are climbing the fastest.
Application:
Barrier specification complexity and volume scale determine margin pools across end-use categories.
- Food Packaging:Retort pouches, modified atmosphere trays, and high-barrier lidding films serve Kenya's processed dairy, meat, and ready-to-eat segments. Oxygen scavenger and ethylene absorber integration differentiates premium specifications.
- Beverage Packaging:Aseptic carton alternatives and bag-in-box formats are displacing rigid containers in juice and wine exports; spout fitment welding demands precision equipment.
- Healthcare Packaging:Tyvek and medical-grade film sterilization pouches serve Nairobi's pharmaceutical manufacturing cluster; CDSCO-equivalent compliance creates technical barriers to entry.
- Personal Care Packaging:Sachet and pillow pack formats dominate shampoo and lotion distribution through Kenya's informal retail channel; fragrance barrier requirements drive multilayer specifications.
Food packaging commands the largest revenue pool; healthcare packaging offers the steepest expansion trajectory.
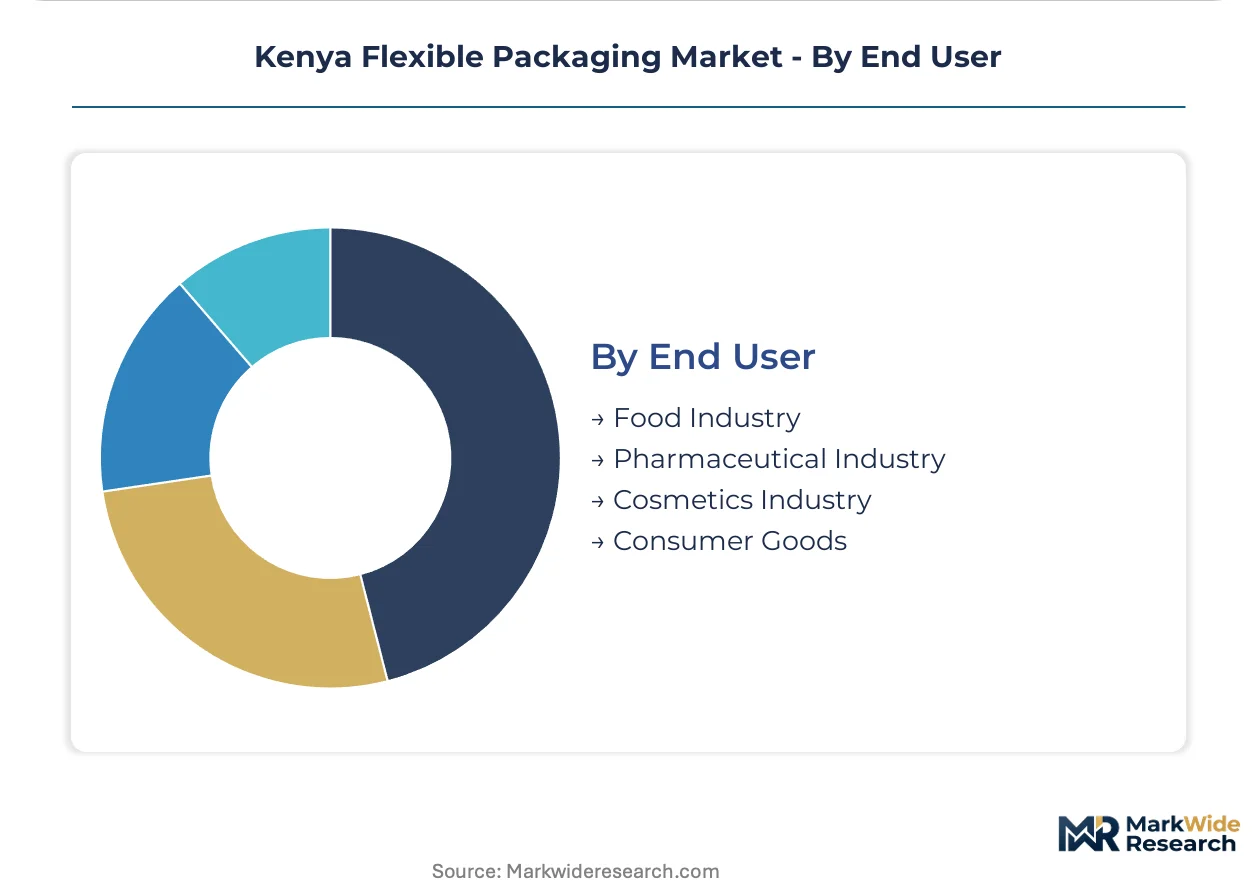
End User:
Procurement sophistication and specification authority vary sharply across buyer categories.
- Food Industry:Multinational fast-moving consumer goods companies headquartered in Nairobi compress supplier approval cycles and demand batch traceability systems. Seasonal product launch windows drive short-run digital printing adoption.
- Pharmaceutical Industry:Tablet blister alternatives and unit-dose pouches require cleanroom manufacturing environments; regulatory documentation burdens favor converters with dedicated compliance staff.
- Cosmetics Industry:Brand owners prioritize shelf differentiation through metallized finishes and tactile coatings; minimum order quantities constrain mid-tier domestic suppliers.
- Consumer Goods:Detergent and household chemical buyers balance unit cost against chemical resistance specifications; concentrated formulations intensify barrier requirements.
Food industry buyers absorb the dominant share of converter attention; pharmaceutical procurement is gaining specification sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nairobi's Export Processing Zone and Athi River industrial corridor concentrate flexible packaging capacity through tax-advantaged land leases and bonded warehouse infrastructure. Kenya's regional trade positioning under the East African Community customs protocol pulls converter investment toward Mombasa-Nairobi logistics spine.
Nairobi Metropolitan Area
Dairy processors and snack manufacturers drive pouch demand across the industrial zone. Kenya Bureau of Standards KS 1758 enforcement concentrates technical expertise in this corridor. Athi River and Mombasa Road clusters host multilayer lamination capacity serving multinational FMCG headquarters.
Rift Valley Agricultural Corridor
Grain exporters and tea processors convert from bulk sacks to pre-formed pouches for European market compliance. NEMA extended producer responsibility audits prioritize food contact packaging from this region. Nakuru and Eldoret host emerging converter capacity targeting export-ready barrier specifications.
Mombasa Coastal Hub
Resin import dependence shapes converter location around port infrastructure and bonded warehousing. Kenya Revenue Authority customs modernization accelerates polyethylene granule clearance times. Changamwe and Kipevu industrial zones concentrate extrusion capacity serving coastal beverage and detergent markets.
Central Highlands
Coffee and horticulture exporters demand high-barrier laminates for air-freight distribution to Middle Eastern markets. Phytosanitary certification requirements from Kenya Plant Health Inspectorate Service drive specification complexity. Thika and Kiambu host specialized printing and slitting operations.
Kenya Flexible Packaging Market Competitive Landscape
Top-tier vendors anchor multinational technical standards, while mid-cap domestic converters compete on localized printing speed and NEMA compliance documentation. The vendor base stratifies across three tiers: global film suppliers with Nairobi technical service offices, regional African converters with Kenyan subsidiary operations, and domestic specialists with single-site extrusion capacity. Strategic archetypes include barrier film innovators, regulatory compliance specialists, and agricultural corridor logistics optimizers. Competitive moves center on biodegradable substrate pre-qualification ahead of NEMA enforcement deadlines and digital printing integration for compressed SKU launch cycles.
Among Kenya-anchored converters, Huhtamaki Flexible Packaging Ltd and Statpack Ltd occupy positions representing multinational technical depth versus domestic operational agility. Silafrica Kenya Limited exemplifies the rigid-to-flexible conversion specialist archetype targeting pharmaceutical compliance requirements. These three entities collectively represent the competitive spectrum from global standards deployment to localized regulatory navigation.
| Leading Market Players |
|---|
| Huhtamaki Flexible Packaging Ltd |
| Statpack Ltd |
| Platinum Packaging Ltd |
| Packaging Industries Ltd |
| Flexipac Limited |
| Polyflex Industries Limited |
| Dune Packaging Limited |
| Paperbags Ltd |
| Silafrica Kenya Limited |
| Others |
Supply & Pricing Matrix
Backward integration into resin extrusion and lamination capacity anchors both supply security and margin protection for Nairobi-based converters facing NEMA compliance deadlines. This integration choice positions formal sector operators to absorb currency-driven input volatility while informal competitors face technical exclusion from food contact supply chains.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation between established converters and spot-market suppliers in Kenya's flexible packaging sector. Three-tier pricing structure across premium, standard, and economy levels separates Kenya Bureau of Standards-certified multilayer laminates from commodity polyethylene bags and informal sector wraps. Price differentiation stems from certification depth and volume scale, with multinational FMCG buyers least sensitive to unit cost and informal retail distributors most responsive to spot pricing. Cost compression in standard-tier pouches is intensifying because resin import exposure through Mombasa port feeds directly into converter margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from multinational food brands mandate polyethylene and polypropylene qualification across at least two resin distributors, driving converter inventory management complexity. Raw material supply draws from Saudi Arabia, South Korea, and India through Mombasa port infrastructure, with EVOH and nylon barrier film dependencies resting on European and Asian specialty chemical producers. Single-source vulnerability concentrates in metalized film substrates where vacuum deposition capacity remains limited regionally. Distribution runs through Nairobi's Athi River industrial corridor for domestic FMCG supply, with Rift Valley grain exporters pulling pre-formed pouch capacity toward Eldoret and Nakuru logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
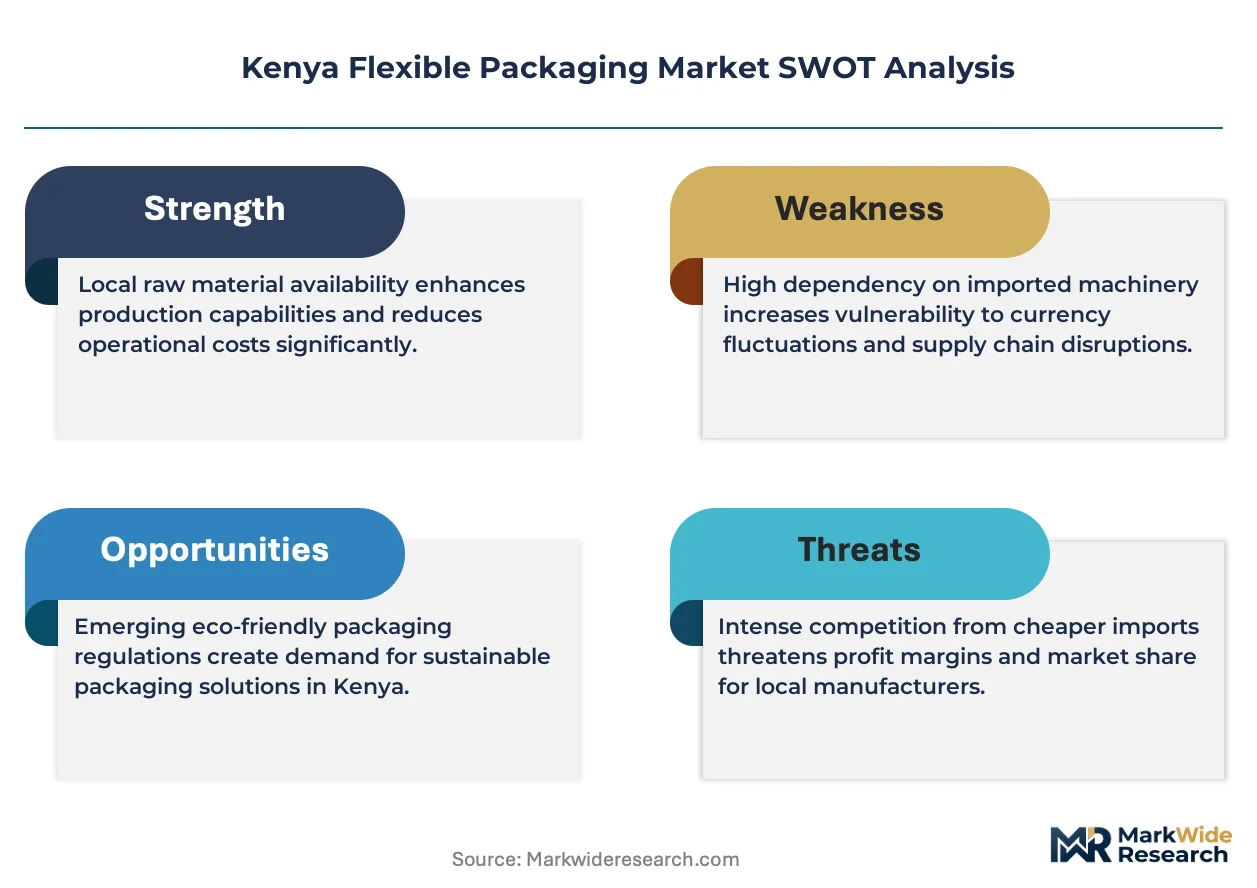
Kenya's flexible packaging sector operates as a cost-of-compliance story where NEMA's extended producer responsibility mandate erects barrier-to-entry moats favoring converters with dedicated regulatory staff and pre-qualified biodegradable substrate portfolios.
For Market Incumbents: Anchor defensive positioning through accelerated biodegradable substrate certification ahead of phased NEMA enforcement expansion, while consolidating solvent-based adhesive handling expertise that aging workforces constrain. Threat substitution from water-based barrier coatings demands coextrusion line investment to preserve barrier performance without volatile organic compound emissions. Capacity addition in Nakuru and Eldoret logistics nodes captures Rift Valley grain exporter migration from bulk sacks to pre-formed pouches. For New Entrants and Emerging Players: E-commerce platform supply contracts offer the most penetrable entry vector, bypassing multinational FMCG supplier approval cycles that compress from eighteen months to six months for established converters. White-space targets concentrate in pharmaceutical blister alternatives and craft food brand digital printing where short-run variable data capability enables regionalized SKU strategies. Go-to-market positioning through Kenya Bureau of Standards certification investment unlocks food contact packaging access that informal operators cannot replicate. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap regulatory compliance specialists with documented NEMA audit preparation infrastructure and in-house biodegradable substrate portfolios. Long-term viability frames around converters capable of bridging Kenya's composting infrastructure gaps while maintaining export-market barrier specifications. Acquisition target archetypes include rigid-to-flexible conversion specialists with CDSCO-equivalent pharmaceutical compliance and digital printing-integrated pouch converters serving compressed seasonal launch windows. Monitor NEMA enforcement consistency as the critical inflection signal for formal sector consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Pre-qualification | NEMA compliance deadlines create certified demand pools that exclude informal competitors from food contact supply chains. |
| Digital Printing Integration | Short-run variable data capability aligns with Nairobi-headquartered FMCG seasonal launch compression to six-month approval cycles. |
| Rift Valley Logistics Node Expansion | Nakuru and Eldoret capacity placement captures grain exporter migration from bulk sacks to high-barrier export-ready pouches. |
| Water-Based Barrier Coating Adoption | Heat-seal performance without solvent emissions bridges the technical gap between domestic converters and multinational film producers. |
| Pharmaceutical Compliance Investment | CDSCO-equivalent cleanroom manufacturing creates technical moats in tablet blister alternatives above food-grade margin pools. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining structured interviews with plant managers at Nairobi and Athi River converters, procurement leads at Rift Valley grain processors, Kenya Bureau of Standards certification officers, and NEMA compliance auditors. Secondary validation drew from Kenya Revenue Authority import records, Kenya Plant Health Inspectorate Service phytosanitary documentation, and East African Community harmonized standards filings. Bottom-up capacity modeling across extrusion, lamination, and printing assets triangulated against top-down demand estimates from food, beverage, and pharmaceutical end-use segments.
Granularity-level modeling deployed product type, material substrate, application barrier specification, and end-user procurement sophistication as intersecting segmentation dimensions across the analysis window. CAGRs derived from time-series capacity utilization rates, import substitution trajectories, and export corridor expansion patterns. Industry-specific forecast inputs included NEMA enforcement phase-in assumptions and Kenya Bureau of Standards KS 1758 amendment timelines for compostable substrate certification.
The model holds under sustained NEMA enforcement consistency and Kenya Revenue Authority customs modernization; deviation in resin import tariff structures or biodegradable certification backlogs would shift converter investment timing and substrate requalification priorities materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market