
 Latin America Flexible Packaging Market | 2026-2036
Latin America Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Flexible Packaging Market Outlook
Brazil's National Solid Waste Policy (PNRS) is recalibrating converter procurement priorities toward recyclable mono-material films. Amcor Plc leverages its regional extrusion network to supply polyethylene-rich structures compliant with extended producer responsibility frameworks. Huhtamaki Oyj anchors Latin American flexible packaging through its Brazil-based pouch manufacturing serving dairy and coffee brands. Mondi Plc differentiates via kraft-paper laminate portfolios targeting e-commerce and dry-food channels.
Latin America flexible packaging encompasses pliable substrates—polyethylene, polypropylene, polyester films, aluminum foils, and paper laminates—formed through extrusion coating, adhesive lamination, or coextrusion into bags, pouches, wraps, and films. These structures provide moisture barriers, oxygen resistance, and shelf-life extension for perishable goods across ambient and chilled supply chains. Plastic films dominate material tonnage due to cost efficiency and sealability, though paper and aluminum composites retain premium positions in coffee and pharmaceutical applications. Stand-up pouches capture the fastest volume expansion in beverage and personal care, while sachet formats sustain mass-market penetration across low-income consumer segments.
ANVISA in Brazil and COFEPRIS in Mexico enforce migration limits and food-contact substance approvals that dictate laminate composition choices. Argentina's national packaging law and Chile's extended producer responsibility regulations are tightening recyclability disclosure requirements, forcing reformulation investments. Stakeholders must monitor evolving state-level enforcement disparities and pre-qualify suppliers against diverging substrate approval timelines.
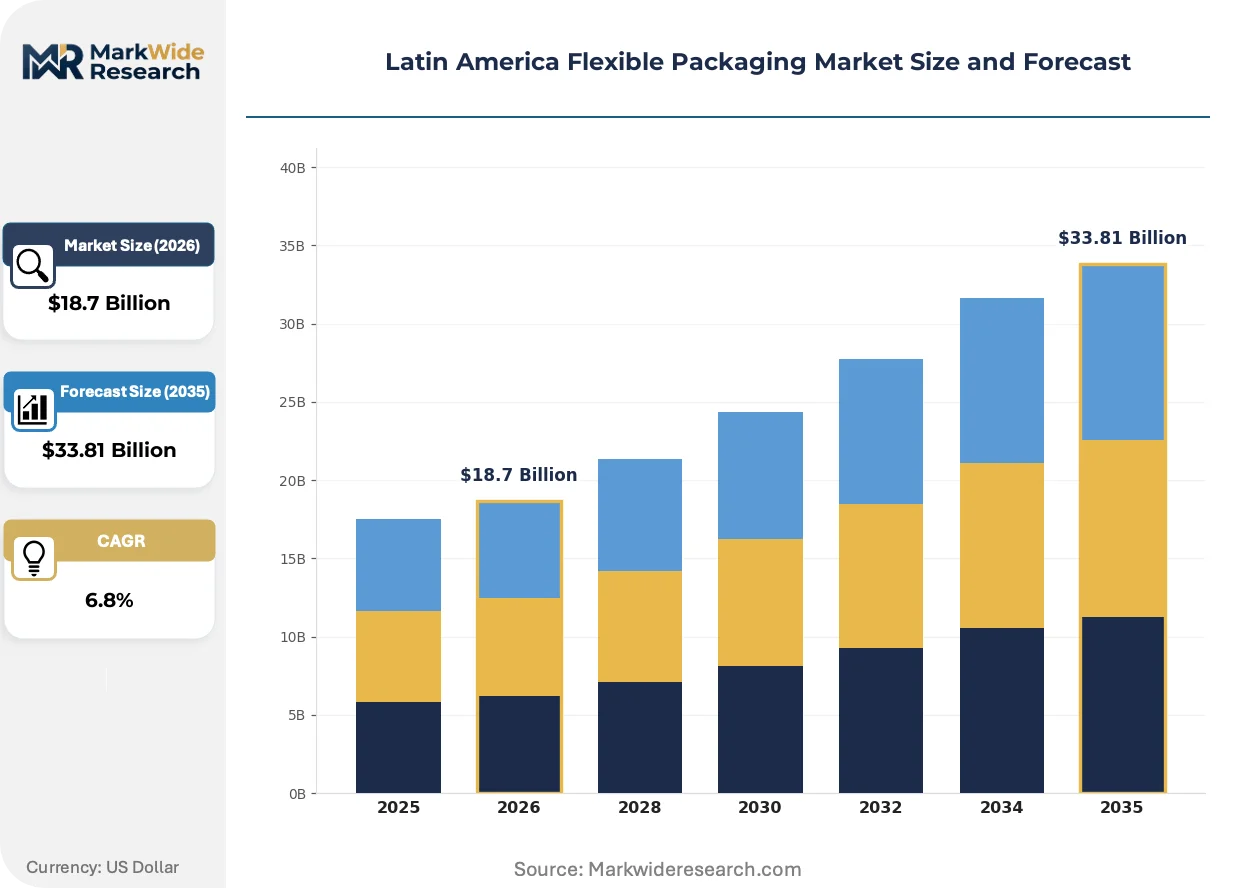
Market Dynamics
Converter procurement across Latin America is pivoting toward mono-material polyethylene structures as Brazil's National Solid Waste Policy (PNRS) imposes extended producer responsibility obligations on packaged goods manufacturers. This regulatory recalibration is compressing demand for multi-layer laminates while elevating investment in recyclable film extrusion capacity.
Growth Catalysts
- PNRS Compliance Deadlines:Brazil's updated solid waste framework mandates recyclability targets that redirect converter sourcing toward polyethylene-rich substrates approved for mechanical recycling streams.
- Processed Food Expansion:Mexico's central corridor of snack and ready-meal producers is converting from rigid containers to flexible pouches to reduce logistics costs and extend shelf stability.
- São Paulo Industrial Clustering:Brazil's southeastern manufacturing belt concentrates extrusion and converting capacity, creating density economies that lower film procurement costs for regional food brands.
Market Restraints
- Resin Import Dependency:Latin American converters rely on imported polyethylene and polypropylene, exposing margin structures to petrochemical price volatility and currency fluctuation against the US dollar.
- Multi-Layer Technical Lock-In:Oxygen-sensitive applications including coffee and dairy retain barrier requirements that mono-material films cannot yet satisfy, delaying format conversion timelines.
- Recycling Infrastructure Gaps:Mechanical recycling capacity for flexible films remains concentrated in southern Brazil, limiting closed-loop viability for converters in northern Mexico and Andean markets.
Strategic Opportunities
- Colombia's Underpenetrated Beverage Segment:Stand-up pouch adoption in juices and dairy alternatives lags regional peers, creating whitespace for format conversion among Bogotá-based bottlers.
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments in São Paulo and Monterrey promise to unlock circular feedstock for flexible packaging producers facing PCR content mandates.
- E-Commerce Protective Films:Kraft-paper laminates with moisture barriers are capturing demand from Brazilian and Mexican fulfillment networks seeking plastic reduction credentials for corrugated substitution.
Industry Challenges
- ANVISA Migration Testing Bottlenecks:Brazil's national health surveillance agency maintains extended approval timelines for new food-contact substances, delaying laminate reformulation cycles by 18-24 months.
- Coextrusion Technical Talent Scarcity:Regional universities produce insufficient polymer engineering graduates to staff expanding film extrusion lines across Mexico's Bajío and Brazil's ABC Paulista regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Flexible Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag, Pouch, Wrap, Film End Use Industry: Food, Beverage, Personal Care, Pharmaceuticals Material: Plastic, Paper, Aluminum, Composites Packaging Type: Stand-up Pouches, Zip-lock Bags, Shrink Films, Sachets |
| Companies Covered | Mondi Plc, ProAmpac Holdings Inc., Amcor Plc, Tetra Pak International SA, Huhtamaki Oyj, Berry Global Inc., Sealed Air Corp., Novolex, Sonoco Products Co., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Flexible Packaging Market Strategic Shifts
Digital printing and mono-material barrier development are compressing minimum order quantities while elevating recyclability performance. These shifts are enabling shorter production runs and faster brand refresh cycles across Latin America's fragmented consumer packaged goods landscape.
Digital flexographic and inkjet systems are decentralizing pre-press and plate-making workflows that historically concentrated in São Paulo and Mexico City. Mid-sized converters in Guadalajara and Campinas are adopting these platforms to serve regional snack brands with run lengths below 10,000 meters. This capability is compressing the traditional advantage of high-volume gravure houses while enabling faster graphic turnaround for seasonal promotions.
ANVISA's updated food-contact substance positive list is accelerating laminate reformulation investments among Brazilian dairy and meat processors. The regulator's tightened migration limits for certain adhesive chemistries are forcing converters to qualify alternative lamination technologies before legacy stocks deplete. Coffee exporters in Minas Gerais and São Paulo are most affected, accelerating trials of water-based and solvent-free adhesive systems to maintain export certification.
Brand owners in Mexico and Brazil are consolidating supplier relationships to secure volume commitments and technical co-development access. This concentration is displacing fragmented spot-buying patterns that characterized the 2015-2020 period. Procurement teams at multinational food manufacturers are now requiring recyclability roadmaps and carbon disclosure as qualification criteria, with enforcement most visible among packaged meat and dairy processors in the Mexico City metropolitan zone.
Latin America Flexible Packaging Market Segmentation
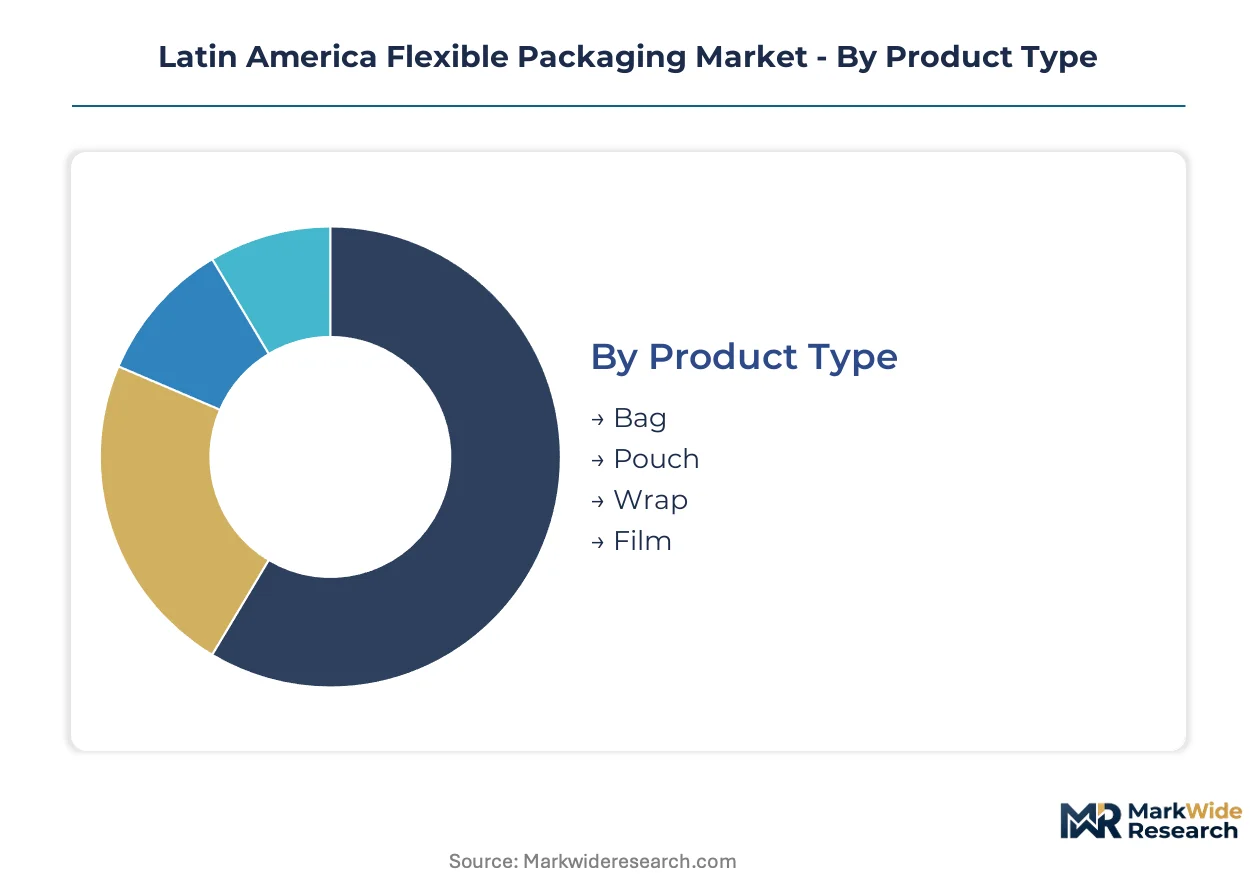
Latin American converters align product specifications with regulatory mandates and end-use performance requirements. Material selection and format geometry determine recyclability compliance, barrier functionality, and total applied cost across Mexico's processed food corridor and Brazil's industrial belt.
Product Type:
Structural geometry dictates machinery compatibility, filling speed, and shelf presence across ambient and chilled supply chains.
- Bag:Three-side-seal and gusseted configurations dominate dried goods and frozen vegetable applications. Brazilian meat processors in São Paulo's ABC region are converting from rigid trays to vacuum bags to reduce freight cube and extend refrigerated shelf life.
- Pouch:Flat and stand-up formats capture volume in coffee, dairy, and pet food segments. Mexico's snack brands in Querétaro and Guadalajara are expanding retort pouch capacity for ready-meal formats targeting convenience retail.
- Wrap:Cling and stretch films sustain bakery, fresh produce, and pallet unitization demand. Argentine wheat exporters rely on moisture-barrier wraps for grain protection during extended port storage.
- Film:Rollstock for form-fill-seal and flow-wrap equipment serves high-speed automated lines. Chilean salmon exporters specify coextruded films with oxygen scavenging layers for trans-Pacific shipment.
Bag formats lead on scale; pouch formats lead on momentum.
End Use Industry:
Application-specific barrier requirements and regulatory exposure shape procurement priorities across consumer segments.
- Food:Processed meats, dairy, and baked goods generate the largest material tonnage. ANVISA migration limits for adhesive chemistries are forcing Brazilian dairy processors to qualify solvent-free lamination systems ahead of legacy stock depletion.
- Beverage:Stand-up pouches for juices and dairy alternatives are gaining share against rigid bottles. Colombian bottlers in Bogotá represent underpenetrated whitespace for format conversion.
- Personal Care:Sachet and pillow-pack formats sustain mass-market penetration across low-income consumer segments. Brazilian beauty brands are consolidating supplier relationships to secure volume commitments and recyclability roadmaps.
- Pharmaceuticals:Blister foils and strip packs demand aluminum-polymer composites with precise moisture and light barriers. Mexico's COFEPRIS enforces food-contact substance approvals that extend qualification timelines for laminate reformulation.
Food commands installed capacity; beverage is climbing the fastest.
Material:
Substrate selection balances cost efficiency, barrier performance, and mechanical recyclability under evolving extended producer responsibility frameworks.
- Plastic:Polyethylene and polypropylene films dominate tonnage due to sealability and cost position. Brazil's PNRS compliance deadlines are redirecting procurement toward mono-material polyethylene structures approved for mechanical recycling streams.
- Paper:Kraft laminates with moisture barriers are capturing demand from e-commerce fulfillment networks seeking plastic reduction credentials. Mondi Plc differentiates via paper-based portfolios targeting corrugated substitution in Brazilian and Mexican logistics.
- Aluminum:Foil layers provide absolute moisture and oxygen barriers for coffee, pharmaceuticals, and premium confectionery. Multi-layer technical lock-in delays format conversion for oxygen-sensitive applications.
- Composites:Coextruded and adhesive-laminated structures combine substrate properties for demanding specifications. ANVISA's tightened migration limits are accelerating reformulation investments among converters serving coffee exporters in Minas Gerais.
Plastic leads on volume; paper is gaining share fastest.
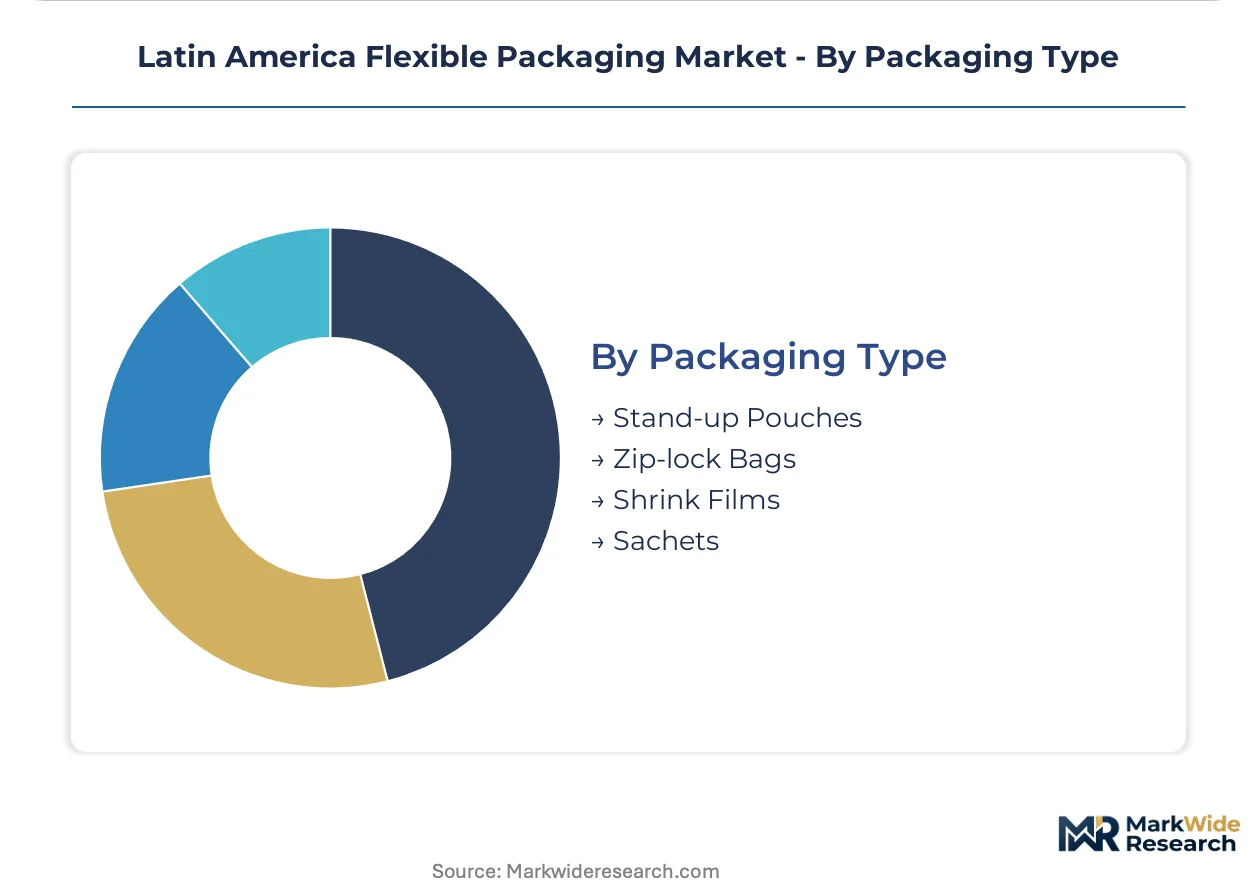
Packaging Type:
Closure and display features differentiate consumer convenience and retail merchandising performance.
- Stand-up Pouches:Doyen and K-seal geometries with spouts or fitments enable shelf-stable liquid and semi-liquid products. Amcor Plc leverages regional extrusion networks to supply polyethylene-rich structures compliant with Brazilian EPR frameworks.
- Zip-lock Bags:Reclosable polyethylene formats sustain snack, frozen food, and household chemical applications. Huhtamaki Oyj anchors regional supply through Brazil-based pouch manufacturing serving dairy and coffee brands.
- Shrink Films:Polyolefin and PVC formulations provide unitization and tamper evidence for beverage and personal care multipacks. São Paulo's industrial clustering creates density economies that lower film procurement costs for regional brands.
- Sachets:Single-serve pillow packs dominate price-sensitive segments across Latin America's fragmented retail landscape. Digital printing platforms are compressing minimum order quantities for mid-sized converters serving seasonal promotions.
Stand-up pouches lead on growth trajectory; sachets lead on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer engineers and extrusion technicians concentrate in São Paulo's ABC industrial belt and Mexico's Bajío region, anchoring flexible packaging manufacturing capacity across the hemisphere's two largest economies.
Brazil
Converter procurement pivots toward mono-material polyethylene structures as ANVISA tightens migration limits for adhesive chemistries. The National Solid Waste Policy imposes extended producer responsibility deadlines that redirect sourcing toward mechanically recyclable substrates. São Paulo's southeastern manufacturing cluster concentrates extrusion capacity, enabling regional food brands to reduce film procurement costs through density economies.
Mexico
Processed food producers in Querétaro and Guadalajara convert rigid containers to flexible pouches for logistics efficiency and shelf stability extension. COFEPRIS enforces food-contact substance approvals that extend laminate reformulation timelines for dairy and meat processors. The Bajío region's expanding extrusion lines face technical talent scarcity as regional universities produce insufficient polymer engineering graduates.
Argentina
Wheat exporters specify moisture-barrier wraps for grain protection during extended port storage at Rosario and Buenos Aires terminals. The national packaging law tightens recyclability disclosure requirements, forcing reformulation investments among converters serving agricultural commodity markets. Córdoba's industrial corridor hosts mid-sized converters adopting digital printing platforms for seasonal promotional runs.
Chile
Salmon exporters demand coextruded films with oxygen scavenging layers for trans-Pacific shipment durability. Extended producer responsibility regulations mandate recyclability roadmaps as qualification criteria for packaging suppliers. Santiago's metropolitan zone concentrates pharmaceutical blister foil demand, where aluminum-polymer composites retain premium positioning.
Colombia
Beverage bottlers in Bogotá represent underpenetrated whitespace for stand-up pouch adoption in juices and dairy alternatives. Chemical recycling investments in pyrolysis capacity promise circular feedstock for converters facing PCR content mandates. Medellín's manufacturing base sustains sachet production for mass-market personal care penetration across low-income consumer segments.
Latin America Flexible Packaging Market Competitive Environment
Capital-heavy producers with integrated extrusion networks compete with asset-light converters outsourcing film supply, creating a tiered structure where scale advantages concentrate among multinational substrate manufacturers. The vendor base spans three strategic archetypes: integrated resin-to-package conglomerates, regional pouch specialists, and niche paper-laminate innovators. Dominant competitive moves include backward integration into resin compounding and geographic expansion through distribution partnerships in underpenetrated Andean markets.
Within the integrated conglomerate tier, Amcor Plc and Berry Global Inc. exemplify asset-heavy positioning through captive extrusion networks supplying polyethylene-rich structures. Among Nordic-origin specialists, Huhtamaki Oyj occupies a position exemplifying regional manufacturing anchoring through Brazil-based operations. Mondi Plc represents the paper-laminate innovation archetype, with kraft-based portfolios targeting e-commerce fulfillment substitution demand.
| Leading Market Players |
|---|
| Mondi Plc |
| ProAmpac Holdings Inc. |
| Amcor Plc |
| Tetra Pak International SA |
| Huhtamaki Oyj |
| Berry Global Inc. |
| Sealed Air Corp. |
| Novolex |
| Sonoco Products Co. |
| Others |
Value Chain & Pricing Dynamics
Polyethylene resin indices on the US Gulf Coast cascade through Latin American converter pricing tiers, amplifying margin compression for spot buyers while contract offtake agreements insulate integrated producers. Brazilian meat processors in São Paulo's ABC region negotiate annual volume commitments to lock in film supply costs, whereas Mexican snack brands absorb sharper volatility through shorter procurement cycles.
Pricing Analysis
Film supply splits between bundled toll-converting services and unbundled resin-plus-film transactions. Three-tier pricing structure across premium certified, standard industrial, and economy spot grades reflects ANVISA food-contact certification status and volume scale. Price differentiation hinges on migration-test documentation depth and extrusion line dedication. Cost compression in economy tiers is intensifying because resin import exposure amplifies currency fluctuation against the US dollar. Small-format sachet converters in Colombia exhibit highest price sensitivity; multinational dairy processors in Brazil's industrial belt demonstrate lowest.
Supply Chain Analysis
Brazil's updated solid waste policy recalibrates local-content thresholds for mechanical recycling feedstock, reshaping converter sourcing toward domestic polyethylene reprocessors. Raw material supply concentrates in Brazil, Mexico, and the US Gulf Coast petrochemical corridor. Converter operations rest on imported polyethylene granules, solvent-based adhesive chemistries, and aluminum foil rolls from South American smelters. Single-source vulnerability runs through resin import channels exposed to port congestion at Santos and Veracruz. Distribution runs through São Paulo-based master distributors serving regional converting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American flexible packaging offers margin-expansion pathways through premium mono-material certification tiers that command price premiums over commodity multi-layer alternatives. Converter consolidation toward recyclability-compliant capacity is compressing supply-side fragmentation.
For Market Incumbents: Hedge resin price exposure through backward integration into compounding operations or long-term offtake agreements with Braskem and Pemex petrochemical divisions. Defend market position by accelerating solvent-free lamination qualification ahead of ANVISA migration limit enforcement. Prioritize certification investment in mechanical recycling stream approval to capture extended producer responsibility compliance premiums from multinational food brands. For New Entrants and Emerging Players: Begin with stand-up pouch supply to Colombia's Bogotá beverage bottlers, where format conversion lags regional peers and incumbent capacity remains thin. Target chemical recycling feedstock partnerships in Monterrey and São Paulo pyrolysis ventures as a differentiated circular-content value proposition. Deploy digital printing platforms to serve mid-sized snack brands with sub-10,000 meter run lengths that gravure houses reject. For Investors and Strategic Acquirers: Asymmetric upside sits with paper-laminate specialists possessing kraft-barrier technical capabilities and e-commerce fulfillment network relationships. Long-term viability favors converters with demonstrated regulatory navigation across ANVISA and COFEPRIS approval timelines. Monitor chemical recycling capacity announcements in São Paulo as an inflection signal for circular feedstock cost competitiveness against virgin resin.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Capacity Expansion | Captures PNRS compliance premiums from Brazilian meat and dairy processors. |
| Solvent-Free Lamination Technology Adoption | Accelerates qualification timelines under ANVISA tightened migration limits. |
| Chemical Recycling Feedstock Partnership | Unlocks circular content supply for converters facing PCR mandate enforcement. |
| Digital Printing Platform Deployment | Compresses minimum order quantities for mid-sized regional snack brands. |
| Kraft-Paper Barrier Portfolio Development | Targets e-commerce plastic-reduction credentials in Brazilian fulfillment networks. |
Study Parameters
Multiple input streams — converter procurement director interviews, resin distributor volume disclosures, and regulatory filing analysis — were reconciled to construct demand estimates. Primary fieldwork encompassed extrusion plant managers, food-brand packaging engineers, ANVISA regulatory consultants, and São Paulo-based master distributors. Secondary validation drew from Brazilian customs polyethylene import records, COFEPRIS food-contact substance registries, and SEC filings of multinational packaging producers. Bottom-up capacity counts and top-down consumption estimates were triangulated to anchor volume figures.
Historical capacity utilization patterns were cross-referenced against panel-based demand projections across the analysis window. Segmentation modeling incorporated product type, end-use industry, material substrate, and packaging format dimensions. CAGRs were derived from slope-consistency checks against resin demand elasticity and converter capital expenditure pipelines. Forecast inputs included ANVISA regulatory timeline scenarios and extended producer responsibility enforcement trajectories.
Several conditions sit outside the modeled scope, including abrupt currency devaluation events, trade policy disruptions affecting resin tariff structures, and breakthrough barrier technologies displacing multi-layer laminates. Forecasts reflect documented assumptions regarding regulatory implementation pacing and mechanical recycling infrastructure buildout. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market