
 Asia-Pacific Shotcrete Market | 2026-2036
Asia-Pacific Shotcrete Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Shotcrete Market Insights
Skilled nozzle operator availability is reorganizing project timelines across the Asia-Pacific shotcrete sector, with labor shortages in remote tunneling sites pushing contractors toward robotic installation systems. Sika AG leverages its admixture technology leadership to sustain premium positioning in wet-mix formulations across Southeast Asian megaprojects. HeidelbergCement anchors its regional supply through integrated cement-shotcrete distribution networks in China and India. Normet Group specializes in robotic spraying equipment, competing on automation intensity where labor constraints bite hardest.
Shotcrete denotes concrete or mortar pneumatically projected at high velocity onto a surface, typically containing Portland cement, aggregates, and accelerators that enable rapid layer buildup with compressive strengths exceeding 30 MPa within 24 hours; its primary purpose is to provide structural support, waterproofing, and ground stabilization in excavated or irregular substrates. Wet-mix shotcrete dominates volume across tunneling applications where continuous flow and lower rebound rates reduce material waste, while fiber-reinforced formulations command margin premiums in slope stabilization projects requiring crack resistance. Robotic installation is displacing manual methods in deep-mining operations across Australia and Indonesia, though combined systems retain share where access geometry fluctuates.
China's SAMR enforces GB standards that mandate minimum bond strength and durability testing for sprayed concrete in infrastructure, while India's BIS certification requirements for shotcrete admixtures filter substandard imports from neighboring markets. Australia's adoption of ISO 22966 for sprayed concrete execution aligns quality thresholds with European practice, creating compliance complexity for multinational suppliers. Stakeholders must monitor how Japan's METI decarbonization roadmap for construction materials reshapes accelerator chemistry and cement substitution protocols across the region.
Market Dynamics
Robotic spraying equipment is compressing project timelines across the Asia-Pacific shotcrete sector as skilled nozzle operator scarcity in remote Himalayan and Indonesian tunneling sites forces contractors toward capital-intensive automation.
Growth Catalysts
- Underground rail corridor expansion:Southeast Asian governments are accelerating metro and high-speed rail tunneling, generating sustained wet-mix shotcrete procurement from state-owned infrastructure developers.
- GB standards tightening:China's SAMR mandates elevated performance benchmarks for fiber-reinforced sprayed concrete, filtering substandard formulations and rewarding admixture technology investments.
- Hydropower tunneling surge:India's Himalayan hydropower sector is concentrating demand for high-strength shotcrete in headrace and tailrace excavations, with state utilities specifying 30 MPa compressive strength within 24 hours.
Market Restraints
- Portland cement price volatility:Input cost swings in clinker and cement concentrate margins for wet-mix contractors, particularly in Indonesia and Vietnam where import dependency remains acute.
- Accelerated supply concentration:Admixture formulation expertise clusters with European and Japanese chemical suppliers, creating procurement bottlenecks for remote Australian and Indonesian mining projects.
- Technical rebound limitations:Dry-mix methods retain share in confined access geometries where robotic wet-mix equipment cannot maneuver, constraining automation penetration in legacy mine shafts.
Strategic Opportunities
- Vietnam underpenetration:Central Highlands hydropower and coal mining expansion offers white space for wet-mix system deployment where manual methods still dominate slope stabilization.
- METI decarbonization roadmap:Japan's construction materials decarbonization protocols are reshaping accelerator chemistry and cement substitution, creating first-mover advantage for low-carbon formulation suppliers.
- Equipment-as-service models:Normet-style robotic spraying fleets offered through lease-to-operate structures reduce capex barriers for mid-tier Indonesian and Philippine tunneling contractors.
Industry Challenges
- Nozzle operator certification gaps:Australia's adoption of ISO 22966 execution standards has compressed training pipelines, extending project mobilization timelines for contractors without in-house robotic capabilities.
- BIS admixture compliance timelines:India's certification requirements for shotcrete additives filter neighboring market imports, forcing reformulation cycles that delay product registration by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Shotcrete Market |
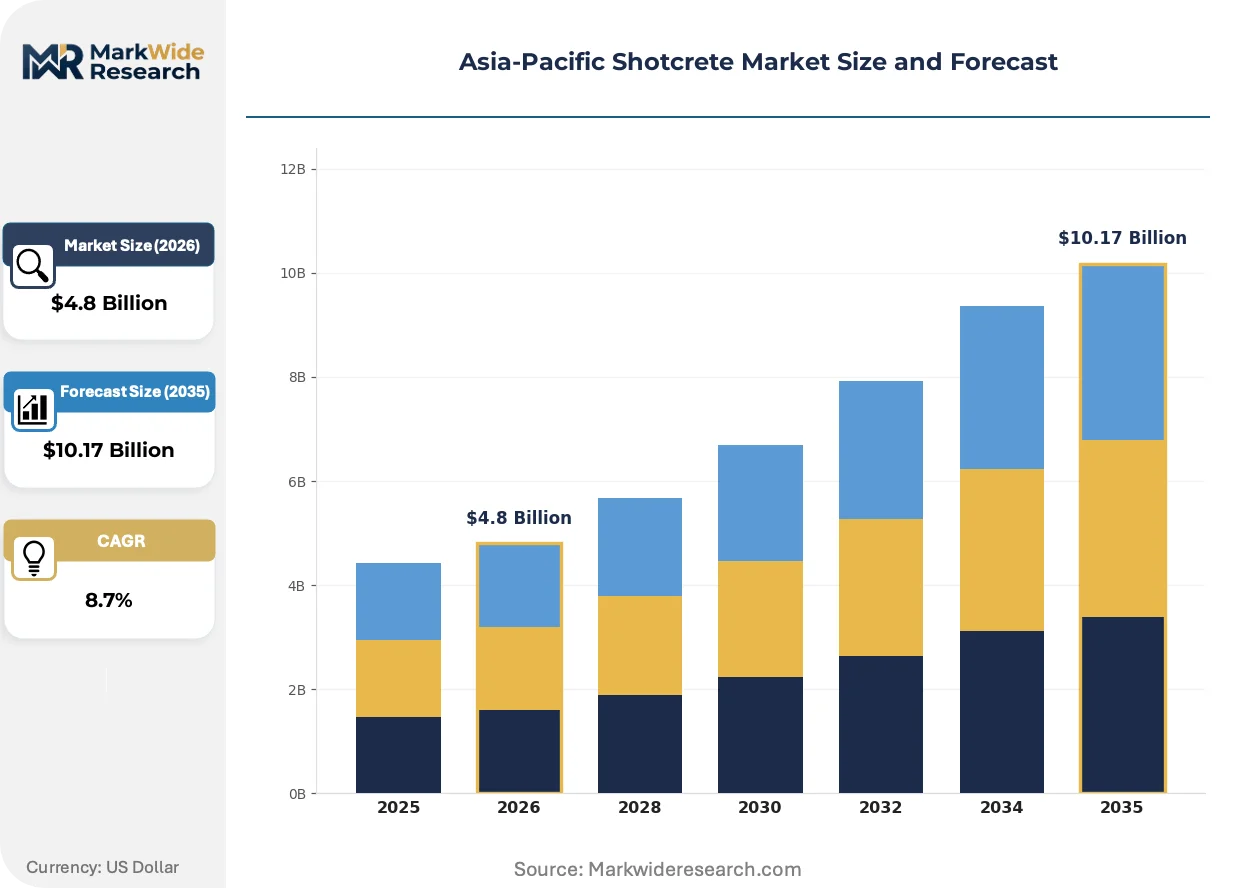
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Mix, Dry Mix, Specialty, Fiber-Reinforced Application: Tunneling, Underground Construction, Slope Stabilization, Water Retaining Structures Installation Method: Robotic, Manual, Automated, Combined End User: Construction Companies, Mining Firms, Infrastructure Developers, Government Agencies |
| Companies Covered | Sika AG, BASF SE, HeidelbergCement, Cemex, Normet Group, Mapei, GCP Applied Technologies, Grupo ACS, Lafargeholcim, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Shotcrete Market Trends and Innovations
Automation intensity and formulation chemistry are the twin vectors reshaping competitive positioning in Asia-Pacific shotcrete, with regulatory pressure on embodied carbon adding a third accelerant to technology investment cycles.
Robotic wet-mix spraying platforms is supplanting manual nozzle operations in Australian and Indonesian deep-mining applications. Major tier-one contractors are mandating automated installation for shafts exceeding 500 meters depth. This shift is compressing labor cost structures while elevating capital intensity requirements for equipment procurement.
China's SAMR enforcement of revised GB standards for sprayed concrete bond strength and durability testing is elevating quality thresholds across infrastructure applications. Domestic contractors are reformulating mixes to meet accelerated curing specifications. Imported admixture suppliers face compliance complexity as local certification timelines extend.
Service unbundling is fragmenting traditional equipment-admixture bundles in Southeast Asian megaprojects. EPC contractors are separating spraying equipment procurement from chemical supply contracts, forcing Sika and HeidelbergCement to compete independently on admixture performance and cement logistics respectively. This pattern is most visible in Vietnam's metro expansion and Thailand's high-speed rail tunneling segments.
Asia-Pacific Shotcrete Market Segmentation
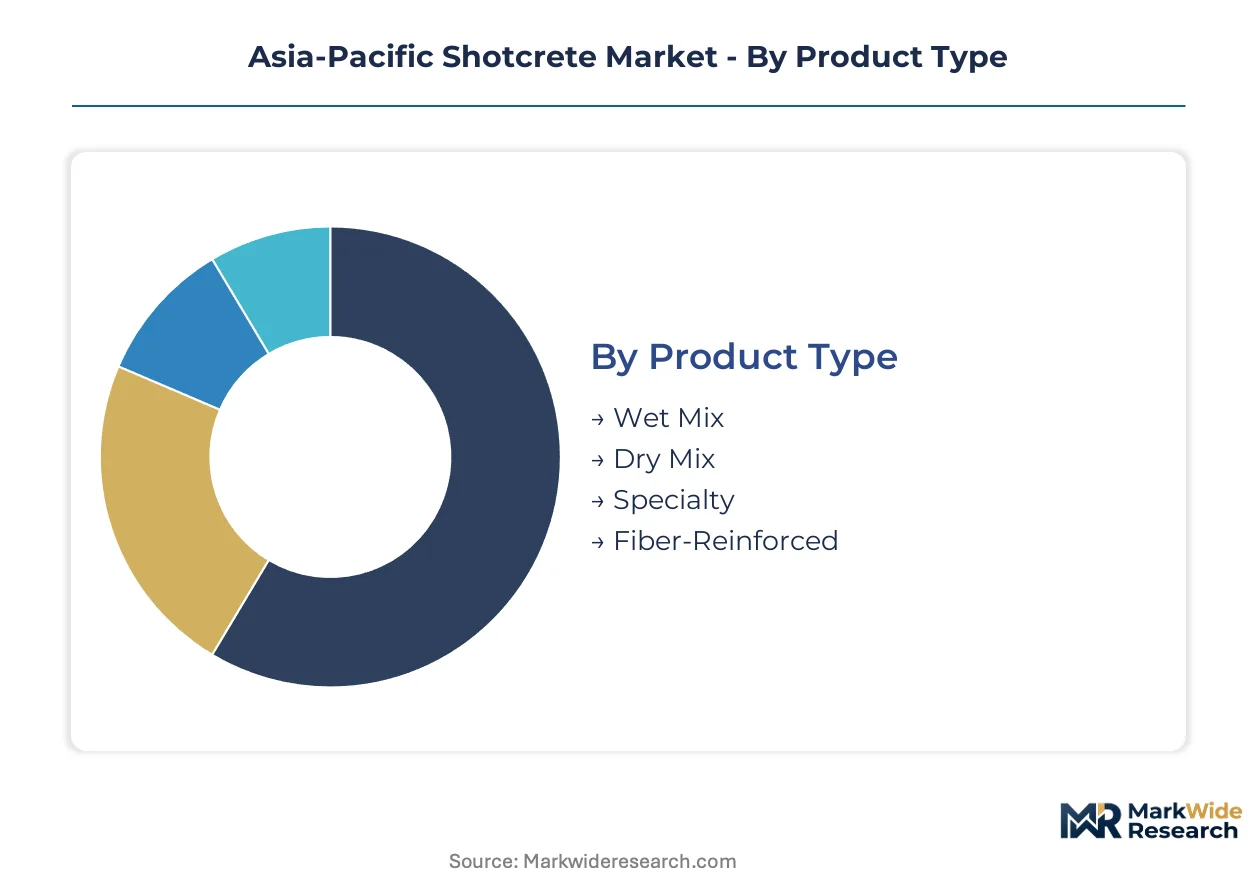
Shotcrete procurement patterns diverge sharply across product formulations and installation methods, with wet-mix systems commanding tunneling contracts while dry-mix retains footholds in confined geometries. Understanding segment-level substitution dynamics reveals where robotic automation can displace manual methods and where fiber-reinforced formulations justify margin premiums.
Product Type:
Dry-mix shotcrete faces the most acute substitution pressure as wet-mix systems demonstrate superior rebound control and continuous flow in high-volume tunneling applications across Southeast Asian megaprojects.
- Wet Mix:Pre-blended concrete delivered through pressurized hoses enables continuous application with rebound rates below 15 percent. State-owned infrastructure developers in Vietnam and Thailand specify wet-mix systems for metro tunneling contracts exceeding five kilometers in length.
- Fiber-Reinforced:Polypropylene or steel fiber dosing enhances crack resistance and flexural strength for slope stabilization and seismic zones. India's Himalayan hydropower sector concentrates procurement of macro-synthetic fiber formulations for headrace tunnel linings subject to rock burst conditions.
- Dry Mix:Bagged cement-aggregate blends mixed at the nozzle suit remote sites with intermittent water supply. Legacy mining operations in Indonesia's Central Highlands retain dry-mix methods where equipment mobilization costs exceed automation savings.
- Specialty:Accelerated curing and corrosion-resistant formulations target marine structures and chemical containment. Japan's coastal defense projects specify sulphate-resistant shotcrete for tidal zone applications.
Wet-mix formulations anchor the volume base while fiber-reinforced shotcrete gains share at the steepest rate as seismic design standards tighten across the region.
Application:
Cost tier differentiation separates commodity ground support from engineered structural applications, with tunneling contractors optimizing material throughput and slope stabilization projects accepting formulation premiums for durability.
- Tunneling:Primary ground support in rail, road, and hydropower excavations demands 30 MPa compressive strength within 24 hours. China's high-speed rail corridor expansion generates sustained procurement from state-owned construction consortia.
- Slope Stabilization:Rockfall protection and embankment reinforcement require fiber dosing and mesh integration for crack control. Australia's alpine highway projects specify engineered shotcrete with alkali-resistant glass fiber for freeze-thaw cycling.
- Underground Construction:Shaft sinking and cavern excavation for storage and industrial facilities. South Korean urban development agencies deploy shotcrete for underground parking and utility tunnels beneath Seoul's dense districts.
- Water Retaining Structures:Reservoir linings, canal walls, and dam face repairs demand low-permeability formulations. Philippine irrigation authorities specify waterproofing admixtures for Mindanao reservoir rehabilitation contracts.
Tunneling commands the dominant procurement volume while slope stabilization applications expand most quickly as climate-induced landslide risks intensify infrastructure protection spending.
Installation Method:
Customer type stratification separates capital-intensive robotic fleets from manual operations, with tier-one contractors amortizing automation across multi-year projects and mid-tier firms retaining labor-dependent methods.
- Robotic:Articulated booms with programmable nozzle positioning achieve consistent layer thickness and reduce operator exposure. Australian deep-mining contractors mandate robotic installation for shafts exceeding 500 meters depth.
- Manual:Hand-held nozzles operated by certified personnel suit variable geometry and confined access. Indonesia's remote coal mining sites rely on manual methods where equipment transport costs exceed labor availability constraints.
- Automated:Sensor-guided systems with real-time thickness monitoring and rebound recovery. Japan's metropolitan rail extensions deploy automated platforms for consistent quality in high-visibility infrastructure.
- Combined:Hybrid configurations pairing robotic booms with manual finishing for complex geometries. Philippine tunneling contractors use combined systems where access conditions fluctuate along excavation profiles.
Manual installation retains the broadest deployment base while robotic systems capture share most rapidly as skilled nozzle operator scarcity intensifies across Himalayan and Indonesian project sites.
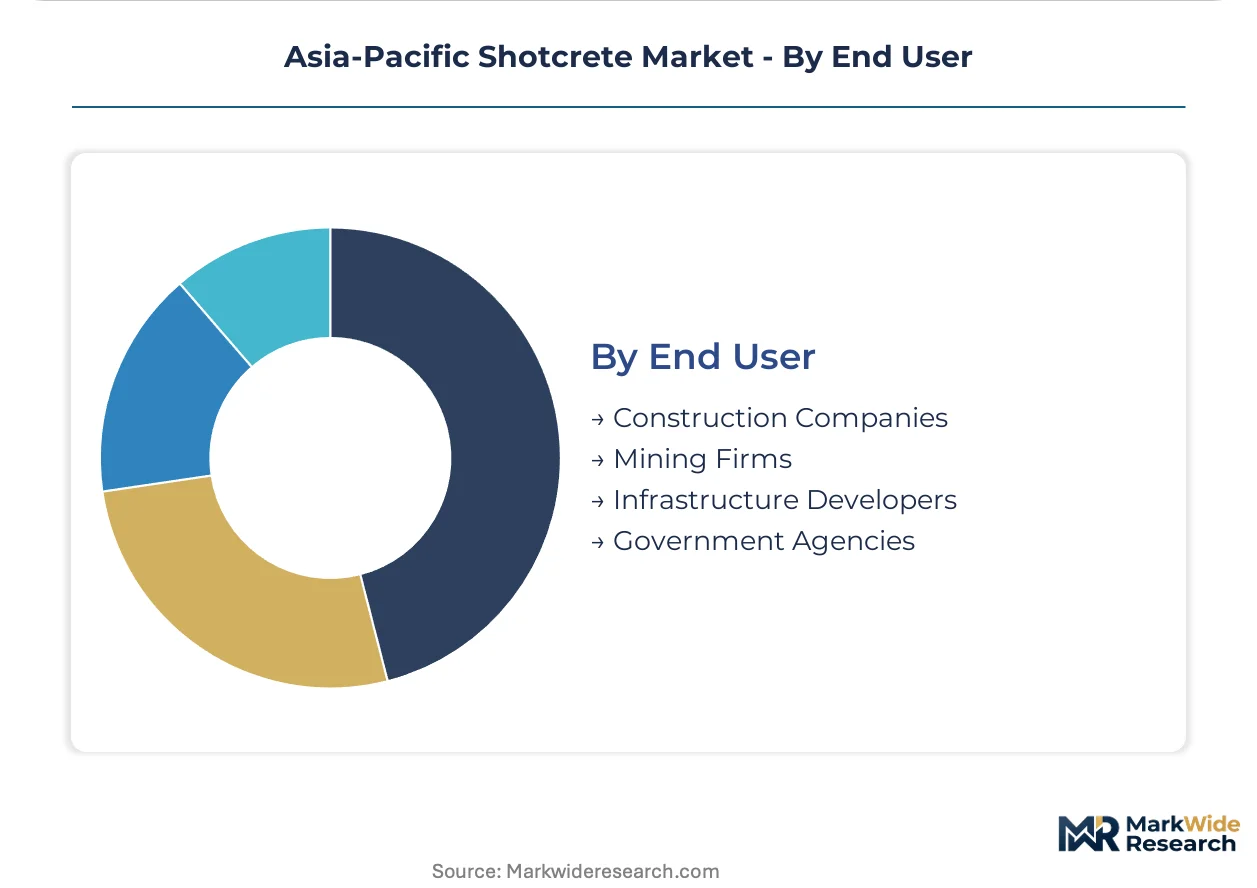
End User:
Supply concentration patterns cluster admixture expertise with mining sector procurement, while infrastructure developers prioritize cement logistics and government agencies enforce quality certification thresholds.
- Infrastructure Developers:State-owned rail, highway, and hydropower agencies specify performance-based contracts with durability warranties. India's National High Speed Rail Corporation mandates wet-mix robotic application for all tunneling segments.
- Mining Firms:Underground and open-pit operations prioritize rapid ground support for cycle time optimization. Indonesia's coal mining sector concentrates demand for accelerated curing formulations in high-humidity conditions.
- Construction Companies:General contractors and specialist subcontractors balance equipment ownership against lease arrangements. Vietnam's emerging metro builders source equipment-as-service models to reduce capital deployment.
- Government Agencies:Public works departments and defense authorities enforce compliance with national standards. China's SAMR certification requirements filter admixture suppliers for state-funded infrastructure.
Infrastructure developers anchor procurement volume while mining firms drive automation adoption fastest as labor constraints bite deepest in remote extraction sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards that tighten performance benchmarks for fiber-reinforced sprayed concrete, filtering substandard formulations and elevating quality thresholds across infrastructure applications.
China
High-speed rail corridor expansion generates sustained wet-mix procurement from state-owned construction consortia. SAMR mandates elevated bond strength and durability testing for sprayed concrete. Domestic contractors in the Yangtze River Delta are reformulating mixes to meet accelerated curing specifications.
India
Himalayan hydropower tunneling concentrates demand for high-strength shotcrete in headrace and tailrace excavations. BIS certification requirements for shotcrete admixtures filter substandard imports from neighboring markets. State utilities in Himachal Pradesh and Uttarakhand specify 30 MPa compressive strength within 24 hours.
Australia
Deep-mining operations mandate robotic installation for shafts exceeding 500 meters depth. Adoption of ISO 22966 for sprayed concrete execution aligns quality thresholds with European practice. Western Australian iron ore and gold extraction sites compress labor cost structures through automation intensity.
Indonesia
Remote coal mining sites in Central Highlands retain dry-mix methods where equipment transport costs exceed automation savings. The country's national infrastructure regulator enforces construction material standards for state-funded projects. Kalimantan mining contractors face skilled nozzle operator scarcity that forces capital-intensive equipment procurement.
Vietnam
Metro expansion and Central Highlands hydropower offer white space for wet-mix system deployment where manual methods still dominate. State-owned infrastructure developers specify wet-mix systems for tunneling contracts exceeding five kilometers. Ho Chi Minh City and Hanoi urban rail projects separate spraying equipment procurement from chemical supply contracts.
Asia-Pacific Shotcrete Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific shotcrete sector. Admixture formulation expertise clusters with European and Japanese chemical specialists while cement logistics concentrate with integrated building materials groups. Equipment automation represents a third competitive vector where robotic spraying systems command premium positioning. Strategic moves center on geographic expansion into underpenetrated Southeast Asian markets and backward integration into cement sourcing.
Among Switzerland-based chemical specialists, Sika AG exemplifies the admixture technology archetype through its wet-mix formulation leadership. Finnish equipment manufacturer Normet Group occupies a position within the robotic automation tier where labor constraints drive replacement demand. Germany's HeidelbergCement represents the integrated materials model through cement-shotcrete distribution network control across China and India.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| HeidelbergCement |
| Cemex |
| Normet Group |
| Mapei |
| GCP Applied Technologies |
| Grupo ACS |
| Lafargeholcim |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day accelerator inventory cycles at Indonesian mining sites concentrate procurement leverage with European chemical suppliers while compressing margins for wet-mix contractors facing clinker price volatility. This lead-time band shapes pricing power across the Asia-Pacific shotcrete sector by tethering formulation costs to cement logistics and admixture certification timelines.
Pricing Analysis
Price spreads between Australian robotic installation contracts and Vietnamese manual-method projects exceed factor-of-two differentials, reflecting labor cost arbitrage and equipment amortization burdens. Project-based long-term offtake dominates procurement, with price differentiation driven by GB standard certification tier and fiber-dosing customization level. Cost compression in economy-tier wet-mix formulations is intensifying because Indonesian import dependency concentrates cement supply risk. State-owned infrastructure developers exhibit lowest price sensitivity, while mid-tier Philippine tunneling contractors face acute margin pressure from equipment lease obligations.
Supply Chain Analysis
Strategic stockpiling of accelerators and fibers prevails among Himalayan hydropower contractors facing monsoon-season logistics disruptions, contrasting with just-in-time cement sourcing practiced by Australian deep-mining operators with established port access. Supply concentrates in China for clinker and cement, Germany and Switzerland for admixture formulations, and Finland for robotic spraying equipment. Raw material dependencies rest on Portland cement, alkali-free accelerators, and polypropylene macro-fibers. Single-source vulnerability in accelerator chemistry creates procurement bottlenecks for remote Indonesian projects. Distribution runs through integrated cement-shotcrete networks in China and India, with equipment leasing platforms penetrating Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across installation-method tiers creates niche opportunities as robotic automation displaces manual operations at divergent speeds across geographies and project scales. This demand-side shift rewards specialized positioning over broad-based market coverage.
For Market Incumbents: Secure backward integration into clinker sourcing across Vietnam and Indonesia to buffer margin compression from import dependency. Anchor certification investment in China's evolving GB standards to filter substandard competitors from state-funded infrastructure procurement. For New Entrants and Emerging Players: Differentiate on equipment-as-service bundling for mid-tier Philippine and Indonesian contractors capitalizing on robotic penetration gaps. Target Vietnam's Central Highlands hydropower expansion where manual methods still dominate slope stabilization. Deploy lease-to-operate structures reducing capex barriers for first-time automation adopters. For Investors and Strategic Acquirers: Carve-out targets emerge from European construction chemicals parents seeking portfolio rationalization away from commodity shotcrete toward specialty admixtures. Long-term viability hinges on automation intensity and low-carbon formulation readiness across a five-to-ten-year window. Monitor Japan's METI decarbonization protocol implementation as inflection signal for accelerator chemistry substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Sourcing | HeidelbergCement's captive supply networks in China and India demonstrate margin protection against import volatility. |
| Equipment-as-Service Model Expansion | Normet-style lease structures reduce capex barriers for Indonesian mid-tier contractors facing skilled labor scarcity. |
| GB Standard Certification Investment | Sika AG's admixture technology leadership aligns with China's SAMR enforcement filtering substandard formulations. |
| Low-Carbon Accelerator Development | Japan's METI decarbonization roadmap reshapes chemistry protocols, rewarding first-mover formulation suppliers. |
| Robotic Spraying Fleet Deployment | Australian deep-mining mandates for shafts exceeding 500 meters depth compress labor cost structures through automation. |
Research Methodology
Desk research of customs trade data, national standards filings, and cement industry association reports preceded structured interviews with tunneling contractors, admixture procurement leads at state-owned infrastructure developers, robotic equipment fleet managers, and BIS certification specialists. Primary fieldwork across Himalayan hydropower sites and Indonesian mining operations validated secondary estimates through bottom-up project pipeline analysis and top-down materials consumption modeling.
Variance decomposition across product type, installation method, application segment, and end-user category anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration, with industry-specific inputs including tunneling contract award timelines and GB standard implementation schedules. Modeled outputs reflect triangulation between equipment shipment records, cement consumption patterns, and admixture formulation registration databases.
Material uncertainties — regulatory acceleration in China's SAMR enforcement, monsoon disruption severity in Southeast Asian logistics corridors, and skilled nozzle operator availability in remote Himalayan sites — sit outside the modeled envelope. Forecasts reflect assumptions regarding infrastructure budget continuity and mining sector automation adoption curves. Revision becomes warranted when robotic equipment penetration rates in Indonesian coal mining cross thresholds that compress manual-method market viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global White Cement Market
Building Materials
India Concrete Admixtures Market
Building Materials
Building Asphalt Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Italy Cement Market
Building Materials
Concrete and Cement Market
Building Materials
Drywall Joint Tape Market
Building Materials
East Africa Wall Putty Market
Building Materials
Sprayed Concrete Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Asia-Pacific Cement Market
Building Materials
North America Architectural Coatings Market
Building Materials
Cement Market
Building Materials
Africa Green Cement Market
Building Materials
Cellular Concrete Market