
 Natural Stone Market | 2026-2036
Natural Stone Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Stone Market Intelligence
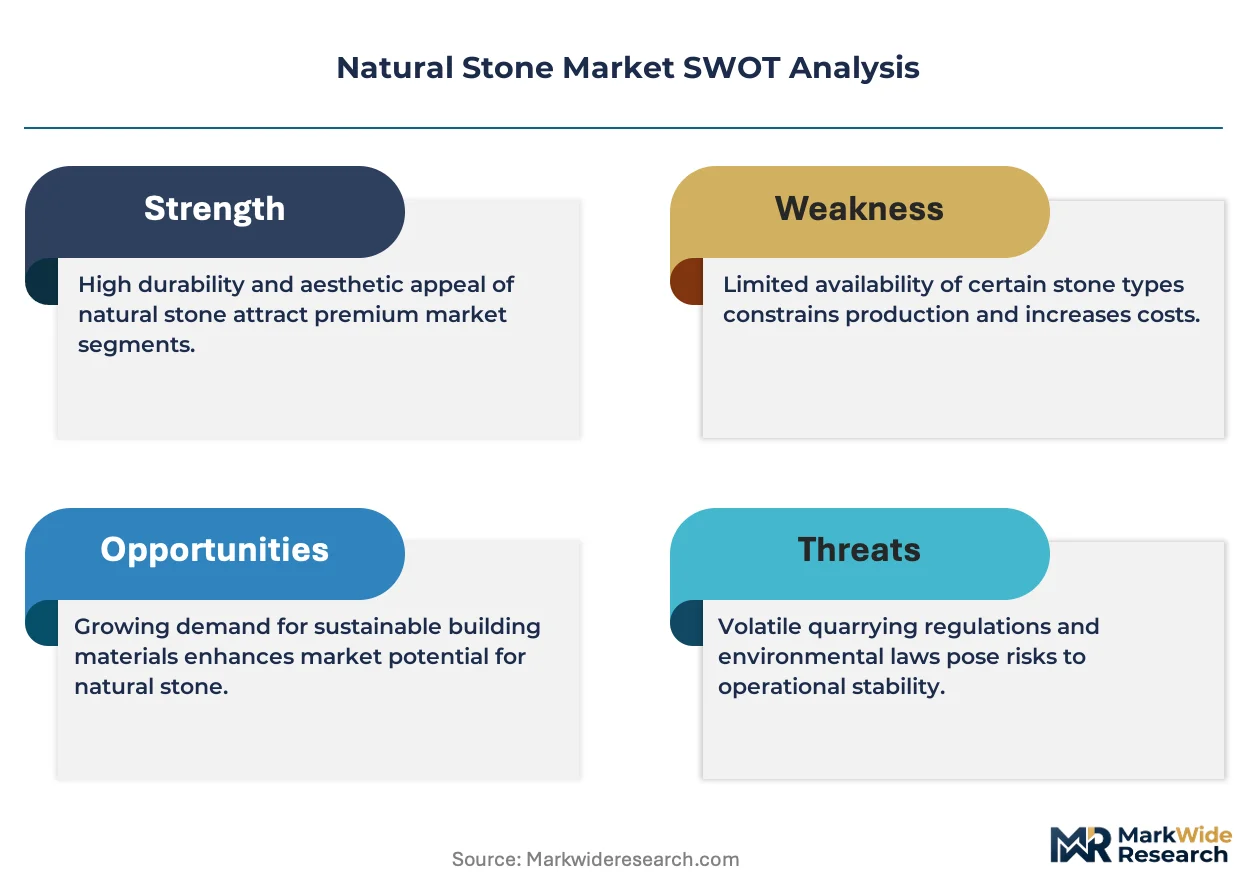
The EU Green Deal's embodied carbon thresholds for construction materials is broadening the addressable market for domestically quarried stone with Environmental Product Declarations. Levantina leverages vertical integration from Spanish quarries to global distribution hubs to guarantee chain-of-custody documentation. Polycor Inc. anchors North American supply through deep reserves of Appalachian marble and Quebec granite, while XISHI Group dominates fabrication scale in China's stone processing corridors.
Natural stone encompasses rock formations quarried and finished for architectural and decorative applications, with granite exhibiting Mohs hardness ratings of 6-7 and marble composed primarily of recrystallized calcite or dolomite. Its primary commercial purpose centers on delivering durable, aesthetically distinctive surfaces for high-traffic interior and exterior environments. Granite commands the largest product type volume due to superior abrasion resistance in flooring and countertop applications, while marble captures premium margin pools in luxury residential and hospitality facades. The commercial end-use segment generates the fastest specification growth, driven by biophilic design mandates in corporate headquarters and wellness-oriented retail concepts.
REACH compliance in Europe governs chemical treatment agents used in stone sealing and finishing, while the EU AI Act's building-material traceability provisions will tighten documentation requirements for imported slabs. China's GB standards for radioactive emission limits in decorative stone constrain quarry output qualification for interior applications. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their differential impact on quarried versus synthetic alternatives.
Market Dynamics
EU Green Deal embodied carbon thresholds are redirecting specification toward domestically quarried stone with verified Environmental Product Declarations, compressing import-dependent supply chains and rewarding quarry-to-fabrication integration.
Growth Catalysts
- EU Green Deal carbon thresholds:Construction procurement mandates in France, Germany, and Italy now require lifecycle documentation for structural materials, elevating locally quarried limestone and marble over imported alternatives lacking chain-of-custody credentials.
- Biophilic design mandates:Corporate headquarters and wellness retail concepts in Dubai, Riyadh, and Singapore are specifying full-slab natural stone for lobby installations, driven by WELL Building Standard certification requirements.
- Fujian-Shandong fabrication clusters:Integrated quarry-to-processing corridors in China's coastal provinces achieve 40% faster turnaround on custom dimension stone, capturing specification for mega-project facades across Southeast Asia and the Middle East.
Market Restraints
- Diesel and electricity input volatility:Quarry extraction and gang saw operations remain energy-intensive; Italian Carrara basin operators face margin compression from natural gas price fluctuations affecting diamond wire cutting and polishing stages.
- Radioactive emission constraints:China's GB standards for radon emission limits in decorative stone disqualify approximately 15% of domestic granite reserves from interior specification, forcing reliance on imported Brazilian and Indian material.
- Engineered quartz substitution:Silestone and Caesarstone products capture mid-market countertop specification through consistent color matching and lower installed cost, pressuring granite slab demand in residential renovation.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM, Red Sea Global, and Qiddiya developments specify premium marble and travertine for hospitality and cultural assets, creating demand for suppliers with verified EPD documentation and regional fabrication partnerships.
- EU AI Act traceability provisions:Automated slab tracking and digital twin documentation will become mandatory for imported stone, rewarding early adopters of blockchain-based chain-of-custody systems with preferred supplier status.
- Carbon border adjustment mechanisms:The EU CBAM's phased implementation on construction materials creates competitive advantage for Turkish, Portuguese, and Spanish quarries with lower transport emissions versus distant competitors.
Industry Challenges
- Certified stonemason scarcity:Heritage restoration and precision facade installation require skilled craft labor; Italian and Portuguese training programs graduate insufficient numbers to meet conservation and luxury project demand.
- REACH compliance timeline compression:Chemical sealant and resin formulation changes required by ECHA substance restrictions force reformulation cycles that delay product certification and market re-entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Stone Market |
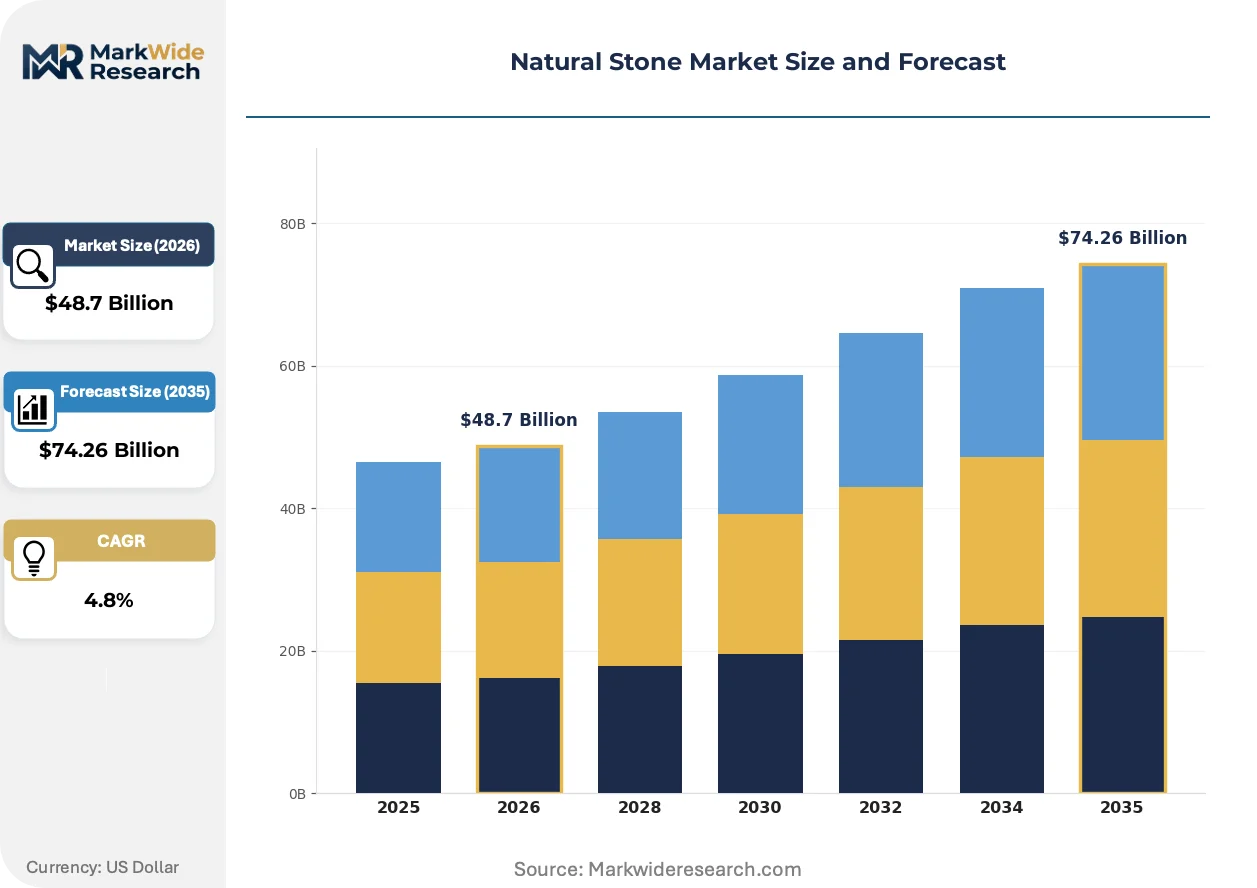
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granite, Marble, Limestone, Slate Application: Flooring, Countertops, Facades, Landscaping End Use: Residential, Commercial, Institutional, Industrial Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Levantina, Universal Marble & Granite Group Ltd., Mohawk Industries, Inc., Stone Source LLC, XISHI Group, Shaw Industries Group, Inc., HeidelbergCement, Emser Tile, Polycor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Stone Market Strategic Shifts & Innovations
Digital fabrication and carbon-accounting technologies are compressing traditional quarry-to-site timelines while embedding documentation directly into material specification workflows.
Waterjet cutting combined with 3D surface scanning is expanding into complex architectural envelope applications. Façade contractors in London, New York, and Melbourne are adopting these systems for double-curved stone cladding that previously required hand-carving. The technology is expanding into mass-customization territory where standardized slab inventory once dominated, enabling project-specific dimension optimization that reduces waste and transport cost.
REACH substance restrictions on siloxane-based sealants are forcing reformulation across European finishing operations. ECHA's candidate list expansion for persistent organic pollutants now covers several hydrophobic treatment chemistries previously standard for exterior limestone protection. Portuguese and Spanish processors are accelerating mineral-based penetrating sealant adoption, with Italian laboratories filing novel nano-silica formulations to maintain performance without regulatory liability.
Direct quarry-to-developer contracting is displacing traditional distributor intermediation in Middle East hospitality procurement. Dubai and Riyadh project managers now negotiate slab selection at Spanish and Italian quarry sites, bypassing regional stockyards. This pattern concentrates most visibly in marble specification for luxury hotel lobbies, where developers prioritize exclusive block reservation and single-origin documentation over inventory convenience.
Natural Stone Market Segmentation
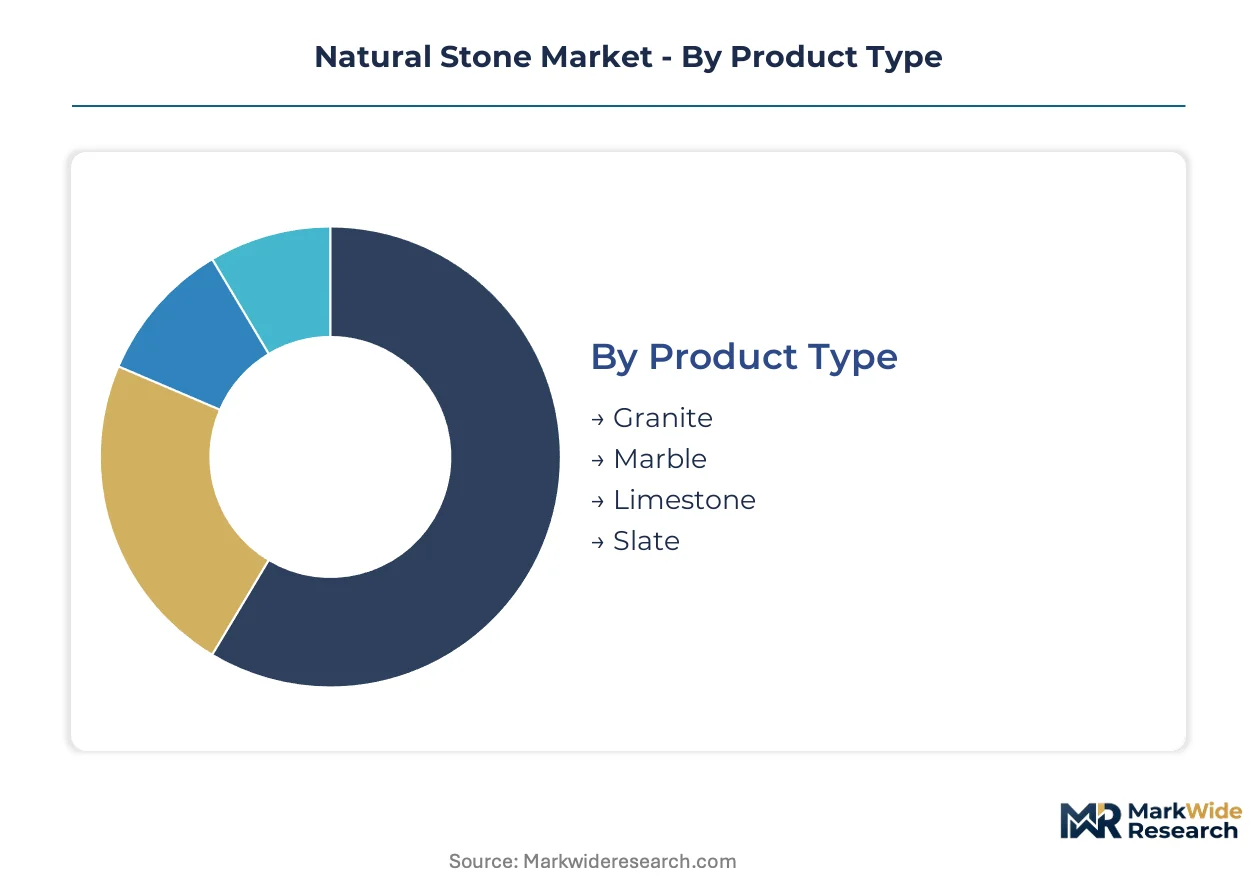
Natural stone specification varies sharply by hardness, porosity, and finish compatibility, driving divergent procurement patterns across architectural applications. Understanding these segment boundaries enables suppliers to align quarry output with the technical and aesthetic requirements of distinct end-use environments.
Product Type:
Granite dominates volume throughput due to its Mohs hardness of 6-7, while marble commands premium positioning in luxury facades.
- Granite:Igneous rock with superior abrasion resistance and low porosity. Demand concentrates in Dubai and Riyadh hospitality flooring, driven by WELL Building Standard durability requirements for high-traffic lobbies.
- Marble:Metamorphic limestone composed of recrystallized calcite or dolomite, prized for veining and polishability. Fujian and Shandong fabrication clusters process Carrara and Calacatta varieties for Middle East giga-project facades, where exclusive block reservation outweighs inventory convenience.
- Limestone:Sedimentary carbonate stone with softer composition suited to interior cladding and restoration work.
- Slate:Fine-grained metamorphic rock with natural cleavage planes, specified for roofing and landscape applications.
Mature deployment sits with granite in commercial flooring. Newer deployment is concentrated in marble for biophilic hospitality interiors.
Application:
Surface performance requirements split procurement between structural load-bearing and decorative finish specifications.
- Flooring:Hard-wearing surfaces requiring slip resistance and point-load tolerance. Saudi giga-projects specify granite and travertine for hotel lobbies and conference centers, with procurement teams conducting slab selection directly at Spanish and Italian quarry sites.
- Countertops:Kitchen and vanity surfaces demanding stain resistance and hygiene certification. Engineered quartz substitution pressures natural granite in residential renovation, though premium residential and commercial segments maintain marble and soapstone specification.
- Facades:Exterior envelope cladding requiring freeze-thaw durability and anchoring system compatibility.
- Landscaping:Paving, retaining walls, and decorative hardscape elements with lower finish tolerance.
Volume concentration tracks flooring in Middle East commercial builds. Margin expansion is climbing the fastest in facades, where digital fabrication enables complex architectural geometries.
End Use:
Procurement authority and specification standards diverge sharply between owner-occupied and developer-driven projects.
- Residential:Single-family and multi-family housing with renovation-driven demand cycles. Countertop replacement dominates, though luxury new construction in Dubai and Singapore specifies full-slab marble for primary bathrooms.
- Commercial:Corporate headquarters, retail, and hospitality assets with design-mandated natural materials. Biophilic design requirements in wellness-oriented retail concepts and WELL-certified offices drive fastest specification growth here.
- Institutional:Government, educational, and healthcare facilities with extended procurement timelines and public tender requirements.
- Industrial:Manufacturing and logistics facilities with utilitarian surface requirements and cost-minimization procurement.
Certified stonemason scarcity constrains institutional heritage restoration. Commercial segment procurement is accelerating most quickly through direct quarry contracting.
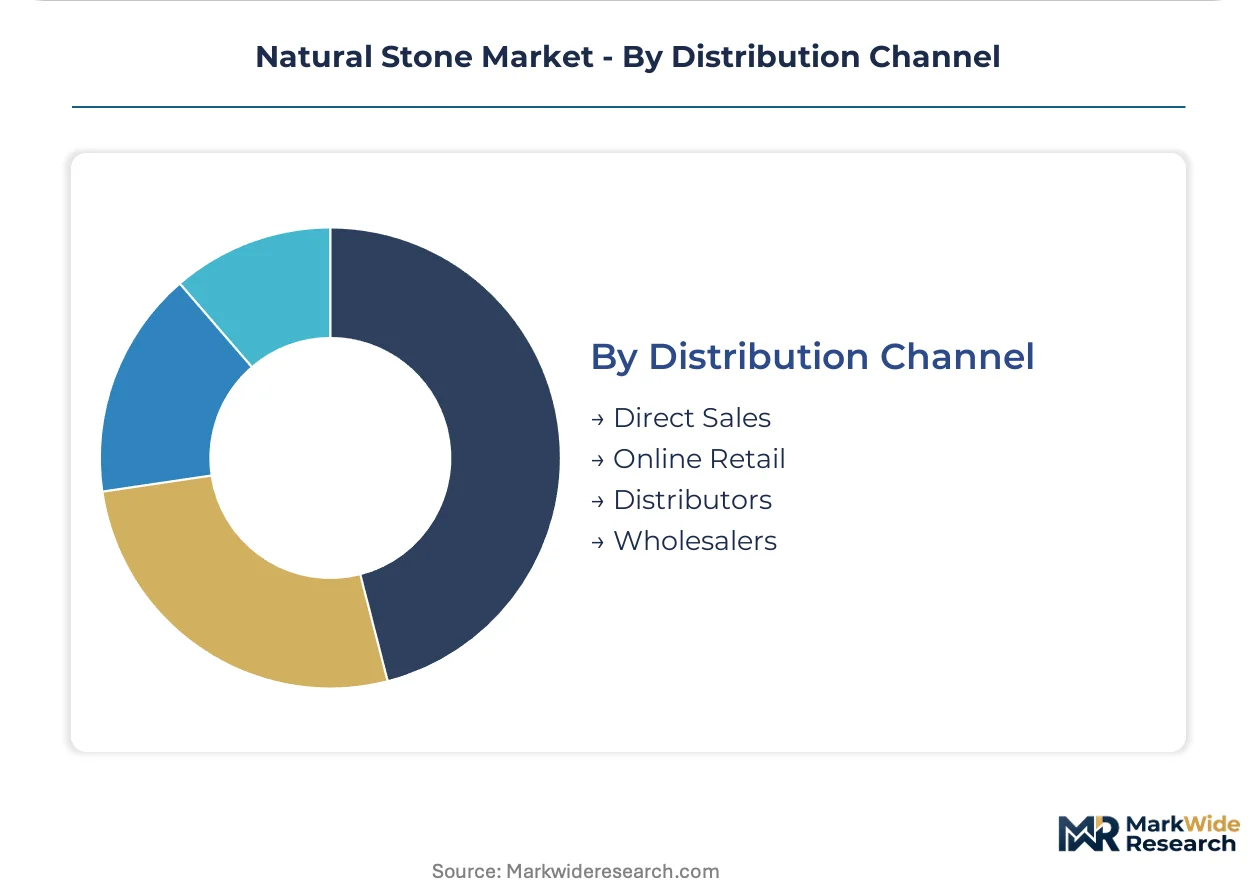
Distribution Channel:
Channel selection reflects project scale, documentation requirements, and the need for physical slab inspection.
- Direct Sales:Quarry-to-developer contracting bypassing intermediaries. Dubai and Riyadh project managers negotiate block reservation at Spanish and Italian extraction sites, prioritizing chain-of-custody documentation for EU Green Deal compliance.
- Distributors:Regional stockyards holding inventoried slab inventory for rapid fulfillment of standard specifications.
- Wholesalers:Volume aggregators serving fabrication shops and smaller contractors with consolidated purchasing.
- Online Retail:Digital platforms for standardized tile and paver products with lower inspection requirements.
Traditional distributor intermediation retains residential and small-contractor volume. Direct sales channels are gaining share fastest in Middle East hospitality procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian and Shandong provinces anchor fabrication capacity through integrated quarry-to-processing corridors serving Middle East giga-projects. Procurement teams from Dubai and Riyadh conduct direct block selection at Chinese coastal facilities, bypassing traditional distribution layers.
China
Domestic mega-projects in Beijing and Shanghai sustain granite demand for commercial flooring, while Fujian and Shandong clusters export finished slabs to Saudi Arabia's NEOM and Red Sea Global developments. GB standards for radioactive emission limits disqualify approximately 15% of domestic granite reserves from interior applications. XISHI Group dominates fabrication scale in these coastal processing corridors.
Italy
Carrara basin operators supply Calacatta and Statuario marble for luxury hospitality facades in Dubai and Singapore, with direct quarry contracting displacing regional distributors. REACH compliance timelines compress chemical sealant reformulation cycles for ECHA substance restrictions. Tuscan finishing laboratories file nano-silica formulations to maintain exterior limestone protection.
Spain
Levantina leverages vertical integration from domestic quarries to global distribution hubs, guaranteeing chain-of-custody documentation for EU Green Deal compliance. Portuguese and Spanish processors accelerate mineral-based penetrating sealant adoption following ECHA candidate list expansion. Andalusian extraction sites serve Middle East procurement teams seeking exclusive block reservation.
Saudi Arabia
NEOM, Qiddiya, and Red Sea Global developments specify premium marble and travertine for hospitality and cultural assets, creating demand for suppliers with verified EPD documentation. SFDA and MOHAP procurement guidelines influence material specification for healthcare and institutional facilities. Riyadh project managers negotiate directly at Italian and Spanish quarry sites.
United States
Corporate headquarters in New York and Chicago specify full-slab natural stone for WELL Building Standard certification, driving biophilic design procurement. EPA and OSHA guidelines govern quarry extraction and fabrication workplace standards. Polycor Inc. anchors North American supply through Appalachian marble and Quebec granite reserves.
Natural Stone Market Key Industry Players
The competitive structure tilts toward quarry-to-fabrication integration over distributor intermediation. Tiered positioning separates premium heritage suppliers from scale-driven processors and regional fabricators. Two strategic archetypes dominate: vertically integrated operators controlling extraction through finishing, and specialized fabricators leveraging proximity to end-markets. M&A activity concentrates on quarry reserve acquisition and digital fabrication capability buildout.
Among European heritage suppliers, Levantina and Polycor Inc. exemplify the integrated archetype through captive quarry reserves and global distribution infrastructure. XISHI Group occupies a position within the scale-driven Asia-Pacific fabrication tier, leveraging coastal corridor concentration for mega-project turnaround. Universal Marble & Granite Group Ltd. represents the regional specialist model, anchoring supply relationships through proximity to Middle East procurement channels.
| Leading Market Players |
|---|
| Levantina |
| Universal Marble & Granite Group Ltd. |
| Mohawk Industries, Inc. |
| Stone Source LLC |
| XISHI Group |
| Shaw Industries Group, Inc. |
| HeidelbergCement |
| Emser Tile |
| Polycor Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned quarry operators in Carrara and the Fujian-Shandong corridor anchor supply discipline through generational reserve stewardship and selective block release. Their ownership structure enables long-term pricing power against cyclical demand swings from Middle East hospitality procurement and EU Green Deal compliance mandates.
Pricing Analysis
Outcome-based pricing anchors slab valuation through WELL Building Standard certification and exclusive block provenance rather than commodity tonnage. Three-tier pricing structure across premium heritage marble, standard fabrication-grade granite, and economy construction limestone separates procurement budgets. Cost compression in mid-market countertop segments intensifies because engineered quartz substitutes capture renovation specification. Residential renovation buyers exhibit highest price sensitivity; luxury hospitality developers in Dubai and Riyadh demonstrate lowest.
Supply Chain Analysis
EPD certification and REACH-compliant finishing qualifications gate supply participation for EU-bound material. Extraction concentrates in Italy, Spain, and China; fabrication clusters in Fujian and Shandong provinces process raw block for export. Diamond wire, gang saw blades, and resin-based sealants constitute critical input dependencies. Single-source vulnerability runs through Brazilian and Indian granite imports blocked by Chinese radon emission standards. Distribution runs through direct quarry-to-developer contracting for premium hospitality specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU AI Act traceability mandates and certified stonemason scarcity will force out undercapitalized regional fabricators lacking documentation infrastructure.
For Market Incumbents: Extend chain-of-custody documentation through blockchain-based slab tracking to capture preferred supplier status under EU AI Act provisions. Anchor backward integration into captive quarry reserves in Turkey, Portugal, and Spain to exploit carbon border adjustment advantages against distant competitors. Counter engineered quartz substitution by embedding WELL Building Standard certification into specification workflows for corporate headquarters procurement.
For New Entrants and Emerging Players: Digital fabrication technology-first wedges open white-space in complex architectural envelope applications requiring waterjet-cut double-curved cladding. Target heritage restoration and precision facade installation segments where certified stonemason scarcity constrains incumbent capacity. Pursue go-to-market partnerships with London, New York, and Melbourne facade contractors adopting 3D surface scanning systems.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Portuguese and Spanish processors with mineral-based sealant reformulation capabilities and existing ECHA compliance infrastructure. Long-term viability centers on quarry-to-fabrication integration with verified EPD documentation serving EU and Middle East procurement channels. Watch carbon border adjustment mechanism expansion as inflection signal for competitive repositioning of Turkish and Mediterranean supply bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Chain-of-Custody Implementation | EU AI Act traceability provisions reward early adopters with preferred supplier status in hospitality procurement. |
| Mineral-Based Sealant Reformulation | ECHA substance restrictions on siloxane chemistries force adoption of compliant finishing technologies. |
| Direct Quarry Contracting Expansion | Dubai and Riyadh developers now negotiate block selection at Italian and Spanish extraction sites. |
| Digital Fabrication Capability Buildout | Waterjet cutting with 3D scanning enables mass-customization for complex architectural envelopes. |
| Heritage Stonemason Training Investment | Italian and Portuguese programs graduate insufficient certified craftspeople to meet conservation demand. |
Research Approach
Trade association filings, customs export records, and quarry operator production disclosures formed the secondary backbone for volume and trade flow calibration. Primary interviews with quarry operations managers, facade contractor procurement leads, hospitality project developers, and EPD certification auditors combined with secondary validation through bottom-up and top-down triangulation.
Historical extraction and fabrication capacity trendlines established baseline supply-side constraints across the analysis window. Segmentation modeling incorporated product type hardness ratings, application surface performance requirements, end-use procurement authority structures, and distribution channel documentation intensity. CAGRs derived from fitted trend extrapolation adjusted for regulatory phase-in schedules and giga-project pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon border adjustment acceleration or engineered quartz technological improvement. Forecasts reflect documented assumptions about EU Green Deal enforcement timing and Saudi giga-project completion schedules. A model refresh is warranted upon material change in ECHA substance restriction scope or Chinese GB standard radon emission threshold revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Aluminum Door and Window Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Drywall Joint Tape Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Long Steel Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Composite Rebar Market
Building Materials
China Cement Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Cladding Market
Building Materials
HDG Steel Pipe Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Facade Gasket Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Global Corrugated Steel Sheets Market