
 Ultraviolet Germicidal Irradiation Market | 2026-2036
Ultraviolet Germicidal Irradiation Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraviolet Germicidal Irradiation Market Outlook
The EU Green Deal's indoor air quality mandates is consolidating procurement standards across European healthcare systems. American Ultraviolet leverages its domestic manufacturing footprint to serve hospital retrofit programs. Atlantic Ultraviolet Corporation anchors the municipal water treatment segment with legacy mercury vapor installations. Trojan Technologies specializes in advanced reactor designs for industrial wastewater applications.
Ultraviolet germicidal irradiation employs short-wavelength ultraviolet light, primarily at 254 nanometers, to disrupt nucleic acid structures and inactivate microorganisms in air, water, and on surfaces. Low pressure mercury vapor technology dominates installed base economics due to decades of operational validation and lamp replacement infrastructure. UVC LEDs represent the fastest-growing technology segment as solid-state sources achieve germicidal efficacy thresholds with reduced mercury compliance burdens. Water treatment applications command the deepest margin pools owing to regulatory discharge standards and continuous-flow operational intensity.
The EPA regulates UV pesticidal devices under FIFRA while the FDA oversees medical device claims, creating dual compliance pathways that shape product positioning and labeling strategy. OSHA ventilation guidelines and ASHRAE standards increasingly reference UVGI as an engineered infection control measure, expanding specification authority for building engineers. Stakeholders must monitor wavelength-specific efficacy data against emerging pathogen variants to validate technology selection and defend capital deployment decisions.
Market Dynamics
The transition from mercury vapor lamps to solid-state UVC LEDs constitutes the central structural force reshaping competitive economics and supply chain configuration across ultraviolet germicidal irradiation markets.
Growth Catalysts
- ASHRAE Standard 241:The American Society of Heating, Refrigerating and Air-Conditioning Engineers now explicitly incorporates UVGI as an engineered infection control measure, compelling building engineers to specify upper-room and in-duct systems for new commercial construction.
- Hospital infrastructure modernization:German hospital infrastructure programs prioritize UV-based air disinfection systems as core components of HVAC retrofit initiatives, creating concentrated procurement demand from public health authorities.
- Mercury compliance burdens:The Minamata Convention on Mercury and EU RoHS directives are accelerating phase-out timelines for legacy mercury vapor technology, forcing installed base replacements and opening specification windows for LED alternatives.
Market Restraints
- Aluminum nitride substrate costs:UVC LED manufacturing depends on specialized aluminum nitride substrates where supply concentrates among Japanese and German specialty ceramic producers, creating input cost volatility that compresses module margins.
- Wavelength efficacy validation gaps:Germicidal efficacy data at 265-280 nanometer LED peak wavelengths remains thinner than the decades of 254 nanometer mercury lamp validation, creating specification friction with conservative infection control officers.
- Dual regulatory pathways:EPA FIFRA pesticidal device registration and FDA medical device oversight create overlapping compliance obligations that extend time-to-market and inflate regulatory affairs staffing requirements for multi-claim products.
Strategic Opportunities
- Residential air purification:Underpenetrated consumer markets in India present white space for compact UV-C air purifiers as household awareness of indoor air quality rises following pandemic-era education campaigns.
- EU Green Deal indoor air mandates:The European Commission's forthcoming binding indoor air quality standards will mandate engineered disinfection in schools, transit hubs, and eldercare facilities, creating regulatory tailwind for specification-grade UVGI.
- UVC LED plus IoT convergence:Solid-state sources enable precise dose monitoring and predictive maintenance algorithms, allowing equipment providers to unbundle hardware sales from subscription-based performance assurance contracts.
Industry Challenges
- Photobiological safety certification:IEC 62471 photobiological safety testing and UL 8802 germicidal system certification require specialized laboratory partnerships that extend product development timelines by six to twelve months.
- Legacy HVAC integration complexity:Retrofit installations demand coordination with existing ductwork geometries and airflow patterns, requiring field engineering capabilities that strain mid-tier equipment providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraviolet Germicidal Irradiation Market |
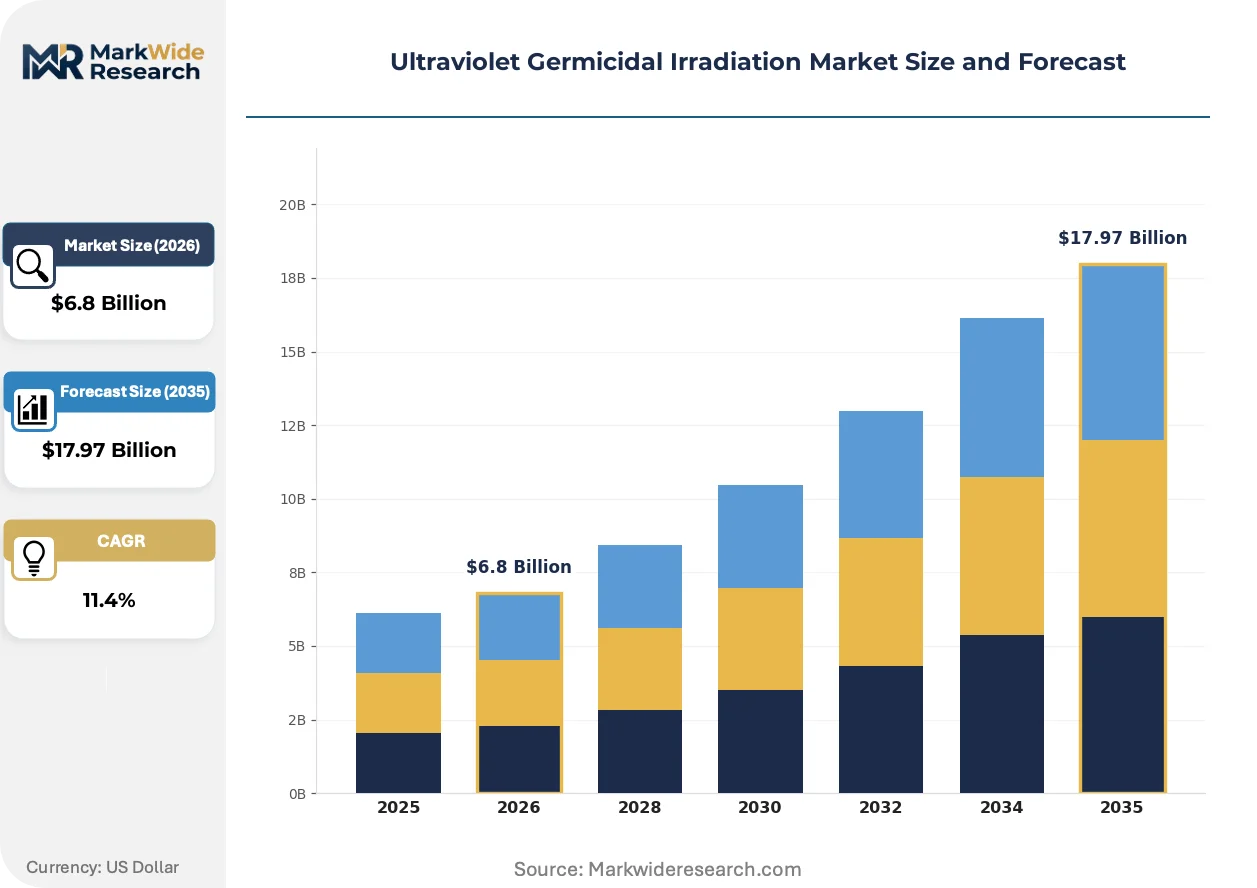
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UVC Lamps, UVC LEDs, Ballast, Reactors Application: Water Treatment, Air Disinfection, Surface Sterilization, HVAC Systems End User: Healthcare Facilities, Food & Beverage Industry, Residential, Commercial Technology: Low Pressure, Medium Pressure, Pulsed Xenon, Mercury Vapor |
| Companies Covered | American Ultraviolet, Atlantic Ultraviolet Corporation, UltraViolet Devices, Koninklijke Philips, Halma plc, Ensavior, Trojan Technologies, UV Resources, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraviolet Germicidal Irradiation Market Strategic Shifts
Technological substitution, regulatory harmonization pressures, and procurement model evolution are converging to restructure how UVGI equipment is specified, validated, and monetized across end-use verticals.
UVC LED technology emits germicidal radiation through semiconductor junctions rather than gas discharge, enabling instant on-off cycling and dimming control impossible with mercury vapor sources. Hospital engineering departments in Germany and the Netherlands are piloting LED-based upper-room fixtures for occupied-space disinfection. This capability is expanding into continuous environmental monitoring applications where dynamic dosing responds to real-time occupancy sensors.
The EPA's emerging framework for UV pesticidal devices under FIFRA Section 3 registration is consolidating labeling requirements and efficacy claim substantiation protocols. Manufacturers must now generate organism-specific kill-rate data under standardized test conditions, raising barriers for commodity importers. Industrial wastewater treatment operators face the steepest compliance burden as they seek to maintain discharge permits while defending UV system performance claims.
Buyers are consolidating vendor relationships around full-service disinfection assurance rather than capital equipment transactions. German hospital procurement cooperatives now contract for guaranteed air changes per hour with pathogen reduction targets, transferring operational risk to OEM service organizations. This restructuring is most visible in Nordic healthcare systems where county-level purchasing authorities bundle HVAC, filtration, and UVGI into fifteen-year performance contracts.
Ultraviolet Germicidal Irradiation Market Segmentation
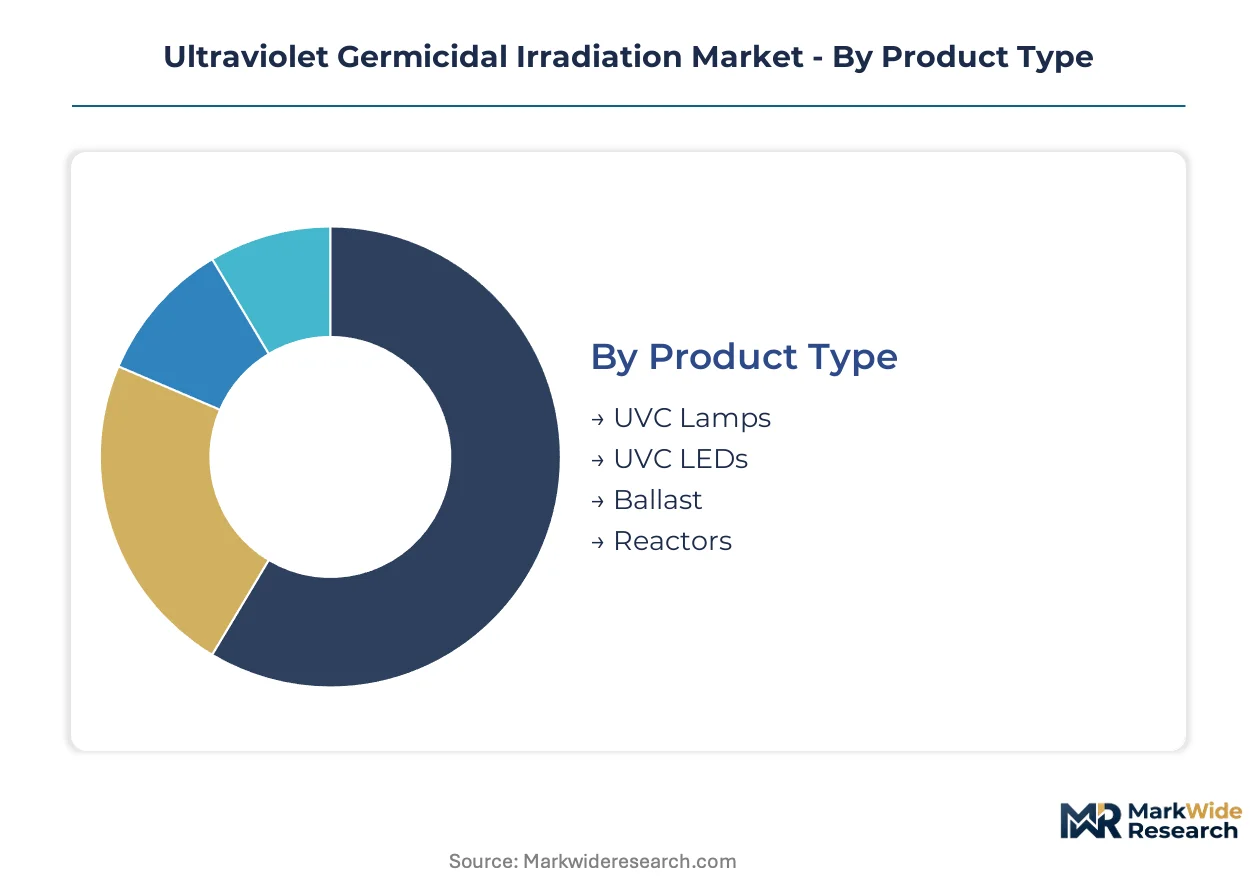
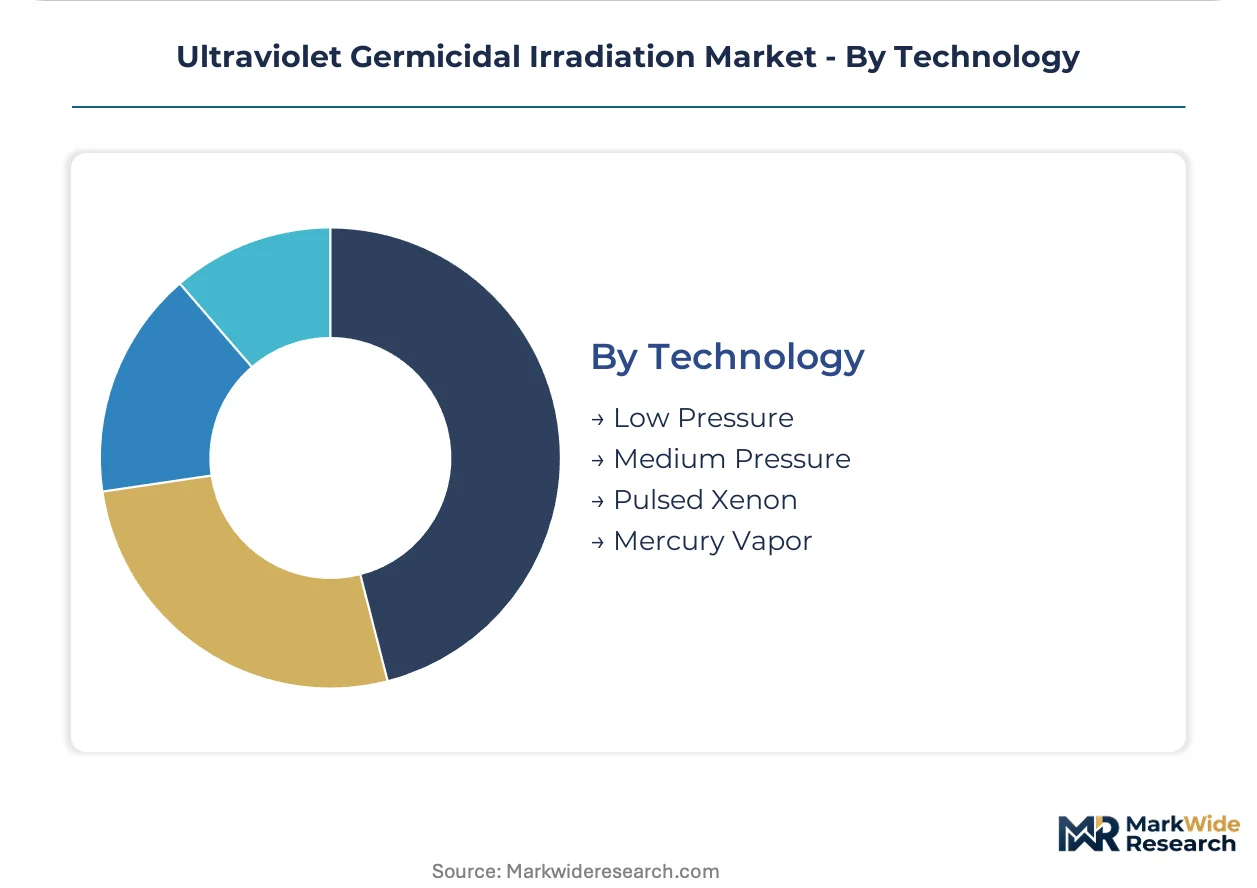
UVGI procurement patterns diverge sharply across end-use contexts, with healthcare engineers prioritizing validated mercury systems while industrial operators pilot solid-state alternatives. Technology selection maps directly to regulatory exposure and operational intensity rather than unit economics alone.
Product Type:
Buyers differentiate by compliance burden and lifecycle cost structure rather than upfront capital outlay.
- UVC Lamps:Low-pressure mercury vapor tubes dominate installed base economics through decades of EPA FIFRA validation and standardized lamp replacement protocols. German hospital engineering departments specify these for HVAC retrofit programs demanding immediate regulatory defensibility.
- UVC LEDs:Solid-state semiconductor junctions enable instant cycling and dimming control impossible with gas discharge sources. The Minamata Convention's mercury phase-out timelines are accelerating specification windows for LED alternatives in EU Green Deal procurement.
- Ballast:Electronic drivers condition power delivery to mercury vapor lamps, with replacement demand tracking installed base aging across North American municipal water facilities.
- Reactors:Engineered vessel geometries optimize hydraulic retention time and UV dose distribution for industrial wastewater discharge compliance.
Volume sits with UVC Lamps; growth tilts toward UVC LEDs.
Application:
Margin pools concentrate where continuous-flow operations meet enforceable discharge or occupancy standards.
- Water Treatment:Municipal and industrial facilities deploy UV reactors for pathogen inactivation without chemical residual formation. Regulatory discharge permits in Germany and the Netherlands mandate validated dose monitoring, deepening service contract attachment rates.
- Air Disinfection:Upper-room and in-duct systems target airborne pathogen reduction in occupied spaces. ASHRAE Standard 241's explicit UVGI incorporation is compelling specification for new commercial construction across the United States.
- Surface Sterilization:Mobile and fixed arrays address terminal cleaning gaps in operating suites and food processing lines.
- HVAC Systems:Coil irradiation and duct-mounted installations prevent biofilm accumulation on heat exchange surfaces.
Water Treatment commands the deepest margins; Air Disinfection is expanding most quickly.
End User:
Risk tolerance and procurement sophistication separate institutional buyers from consumer markets.
- Healthcare Facilities:Infection control officers demand organism-specific kill-rate data under standardized EPA test conditions. German county-level purchasing authorities bundle HVAC, filtration, and UVGI into fifteen-year performance contracts with guaranteed pathogen reduction targets.
- Food & Beverage Industry:Process engineers specify UV pasteurization for liquid sugar, brine, and rinse water applications where thermal methods degrade product quality.
- Residential:Compact air purifiers target post-pandemic household awareness in underpenetrated Indian consumer markets.
- Commercial:Building owners evaluate UVGI for LEED certification credits and tenant retention in premium office segments.
Healthcare Facilities anchor procurement volume; Residential shows the steepest expansion trajectory.
Technology:
Operational validation depth determines specification authority across conservative engineering constituencies.
- Low Pressure:Monochromatic 254 nanometer emission aligns with decades of microbial inactivation research and standardized dosimetry protocols. EPA FIFRA registration pathways favor this wavelength for pesticidal device claims.
- Medium Pressure:Polychromatic output across 200-300 nanometers enables single-pass cryptosporidium inactivation in high-flow drinking water facilities.
- Pulsed Xenon:High-intensity flashlamps target rapid surface decontamination in pharmaceutical cleanrooms and biosafety laboratories.
- Mercury Vapor:Amalgam lamp variants extend operating temperature ranges for industrial process water applications.
Low Pressure holds installed base dominance; Medium Pressure gains share in high-throughput municipal contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European UVGI manufacturing density, with Dortmund and Essen hosting specialized lamp fabrication facilities serving hospital retrofit programs across North Rhine-Westphalia.
United States
Healthcare facilities in Texas and Florida are accelerating HVAC upgrade timelines following ASHRAE Standard 241 adoption. The EPA's FIFRA Section 3 registration pathway is consolidating efficacy claim requirements for pesticidal UV devices. Boston's hospital engineering consortium pilots upper-room LED installations for occupied-space pathogen reduction.
Germany
County-level purchasing authorities in Bavaria and Baden-Württemberg bundle fifteen-year performance contracts for guaranteed air disinfection outcomes. The EU Green Deal's binding indoor air quality mandates are reshaping procurement standards for schools and eldercare facilities. Stuttgart's engineering clusters specialize in reactor design for industrial process water applications.
Netherlands
Municipal water authorities in Rotterdam and Amsterdam mandate validated UV dose monitoring for discharge permit compliance. The country's national environmental agency enforces strict mercury phase-out timelines under EU RoHS directives. Eindhoven's semiconductor ecosystem supplies aluminum nitride substrates for LED module fabrication.
India
Household awareness campaigns in Maharashtra and Karnataka are opening consumer markets for compact air purifiers. The Bureau of Indian Standards is developing certification protocols for residential UV-C devices. Mumbai's hospital infrastructure programs prioritize UV-based HVAC integration in public health facility upgrades.
Japan
Specialty ceramic producers in Osaka and Nagoya dominate aluminum nitride substrate supply for UVC LED manufacturing. METI efficiency standards are accelerating solid-source adoption in commercial building retrofits. Kyoto's infection control research institutes generate wavelength-specific efficacy data for conservative engineering specifications.
Ultraviolet Germicidal Irradiation Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology validation depth and regulatory compliance infrastructure. The vendor base organizes into three tiers: legacy mercury system specialists with decades of EPA FIFRA registration history, solid-state LED entrants with semiconductor supply chain partnerships, and full-service disinfection assurance providers with fifteen-year performance contracting capabilities. Dominant competitive moves include backward integration into aluminum nitride substrate sourcing and strategic partnerships with HVAC OEMs for bundled retrofit specifications.
Within the legacy-system tier, American Ultraviolet and Atlantic Ultraviolet Corporation occupy positions anchored by domestic manufacturing footprints and municipal water treatment installed bases. Trojan Technologies exemplifies the industrial-specialist archetype with advanced reactor design capabilities for wastewater discharge compliance. Koninklijke Philips represents the diversified electronics conglomerate model, leveraging semiconductor manufacturing scale for LED module cost positioning. These three company structures illustrate how competitive positioning maps to capital intensity and regulatory defensibility requirements across end-use verticals.
| Leading Market Players |
|---|
| American Ultraviolet |
| Atlantic Ultraviolet Corporation |
| UltraViolet Devices |
| Koninklijke Philips |
| Halma plc |
| Ensavior |
| Trojan Technologies |
| UV Resources |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's binding indoor air quality mandates gate qualified supply access and premium-tier pricing power for UVGI equipment manufacturers. Buyers seeking specification-grade systems for healthcare and educational facilities must source from vendors with validated EPA FIFRA registration or EU-equivalent certification, creating a bifurcated market where compliant suppliers command price premiums.
Pricing Analysis
Value-based pricing anchors on guaranteed pathogen reduction outcomes rather than hardware unit costs. Three-tier pricing structure across premium, standard, and economy levels separates performance-contracted healthcare installations from commodity municipal retrofits and residential consumer units. Cost compression in the LED module tier is intensifying because aluminum nitride substrate supply concentrates among Japanese specialty ceramic producers. Municipal water treatment authorities demonstrate the lowest price sensitivity due to regulatory discharge compliance requirements, while residential air purifier buyers in emerging markets exhibit the highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German hospital procurement cooperatives mandate qualified suppliers for both mercury vapor lamps and solid-state LED modules to ensure retrofit continuity. Manufacturing draws from Japan for aluminum nitride substrates, Germany for specialized lamp fabrication, and the Netherlands for semiconductor packaging capabilities. Single-source vulnerability in aluminum nitride supply creates exposure to input cost volatility that compresses module margins. Distribution runs through HVAC OEM channel partnerships for commercial specifications and direct contracting for municipal water treatment installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UVGI market sits in a technology-transition phase as solid-state UVC LEDs displace legacy mercury vapor systems. This substitution is reshaping competitive economics and procurement patterns across healthcare, industrial, and municipal end-use verticals.
For Market Incumbents: To counter specification erosion from LED entrants with semiconductor cost advantages, deepen backward integration into aluminum nitride substrate sourcing through partnerships with Osaka-based ceramic producers. Accelerate EPA FIFRA registration for 265-280 nanometer wavelength efficacy data to defend regulatory defensibility against solid-state competitors.
For New Entrants and Emerging Players: Begin with underpenetrated residential air purification markets in Maharashtra and Karnataka where household awareness campaigns have primed consumer demand. Target compact UV-C air purifier segments with direct-to-consumer distribution models that bypass established HVAC channel gatekeepers.
For Investors and Strategic Acquirers: German county-level purchasing authorities bundling fifteen-year performance contracts is the leading indicator that service-based monetization models are displacing capital equipment transactions. Target full-service disinfection assurance providers with IoT-enabled predictive maintenance capabilities and established hospital system relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Nitride Sourcing | Captive supply of Japanese ceramic substrates insulates LED module margins from input volatility. |
| EPA FIFRA Section 3 Registration Completion | Validated pesticidal device claims unlock specification authority with conservative infection control officers. |
| IoT-Enabled Performance Contract Launch | Real-time dose monitoring supports subscription-based guaranteed outcome monetization for healthcare buyers. |
| HVAC OEM Strategic Partnership | Bundled retrofit specifications with Carrier or Trane accelerate commercial building penetration. |
| Residential Distribution Channel Expansion | Direct-to-consumer platforms in India bypass traditional clinical specification gatekeepers. |
Study Parameters
Independent corroboration across infection control officers at German hospital engineering departments, EPA regulatory affairs specialists, and aluminum nitride substrate procurement managers underwrites the qualitative findings. Primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from EPA FIFRA registration databases, ASHRAE standard documentation, and EU Green Deal implementation directives. Bottom-up equipment shipment data triangulates against top-down healthcare capital expenditure surveys.
Comparable-period anchoring to historical mercury vapor lamp deployment cycles and LED adoption curves in adjacent solid-state lighting markets structured the forecast window. Segmentation dimensions modeled include technology type, application vertical, end-user risk tolerance, and regional regulatory framework across the projection horizon. CAGRs were derived from installed base replacement timelines and emerging specification windows. Forecast inputs incorporate ASHRAE Standard 241 adoption velocity and Minamata Convention mercury phase-out compliance schedules.
Mercury vapor supply disruption, aluminum nitride substrate cost spikes, and wavelength efficacy validation delays are the dominant revision risks to the outlook. Forecasts reflect assumptions regarding regulatory harmonization timelines and semiconductor manufacturing scale-up curves. A model refresh is warranted upon material change in EPA FIFRA registration pathway consolidation or EU indoor air quality mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Antiseptic Bathing Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Ear Infection Treatment Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Preventable Vaccines Market
Infection Control
Hygiene Stations Market
Infection Control
Surgical Site Infections Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Sterilization Monitoring Market
Infection Control
Yeast Infection Market