
 Ipilimumab Market | 2026-2036
Ipilimumab Market Size, Share, and Industry Trends Forecast 2026-2036
Ipilimumab Market Outlook
Immuno-oncology fellowship training capacity is unwinding faster than hospital expansion of cellular therapy units, creating a bottleneck in combination protocol administration. Bristol-Myers Squibb leverages its first-mover manufacturing scale to anchor supply contracts with major infusion centers. Merck & Co., Inc. competes through sustained investment in PD-1 combination studies that broaden addressable patient populations. Roche Holding AG differentiates via integrated diagnostic platforms that pair biomarker testing with therapy selection.
Ipilimumab is a fully human monoclonal antibody targeting cytotoxic T-lymphocyte-associated protein 4 (CTLA-4), manufactured through recombinant DNA technology in Chinese hamster ovary cells, with a molecular weight of approximately 148 kDa and administered via intravenous infusion to block inhibitory immune signals and activate T-cell antitumor responses. The indication segment shows melanoma retaining the largest patient volume while lung cancer applications expand fastest through combination trials. Distribution channel dynamics reveal specialty pharmacy controlling the majority of outpatient volumes, though hospital pharmacy captures higher-margin inpatient loading doses.
FDA accelerated approval requirements and EMA conditional marketing authorization frameworks shape trial design and label expansion timelines for CTLA-4 inhibitors across North America and Europe. The country's national pharmaceutical regulator in Japan, PMDA, imposes distinct immunogenicity testing standards that filter market entry for foreign-manufactured biologics. Stakeholders must monitor evolving CMS reimbursement rates for outpatient infusion services and the trajectory of biosimilar development programs targeting key patent cliffs.
Market Dynamics
FDA accelerated approval pathways for combination immunotherapy regimens are compressing clinical trial timelines while simultaneously expanding the addressable patient population for CTLA-4 inhibitors beyond melanoma into lung and renal cancer indications.
Growth Catalysts
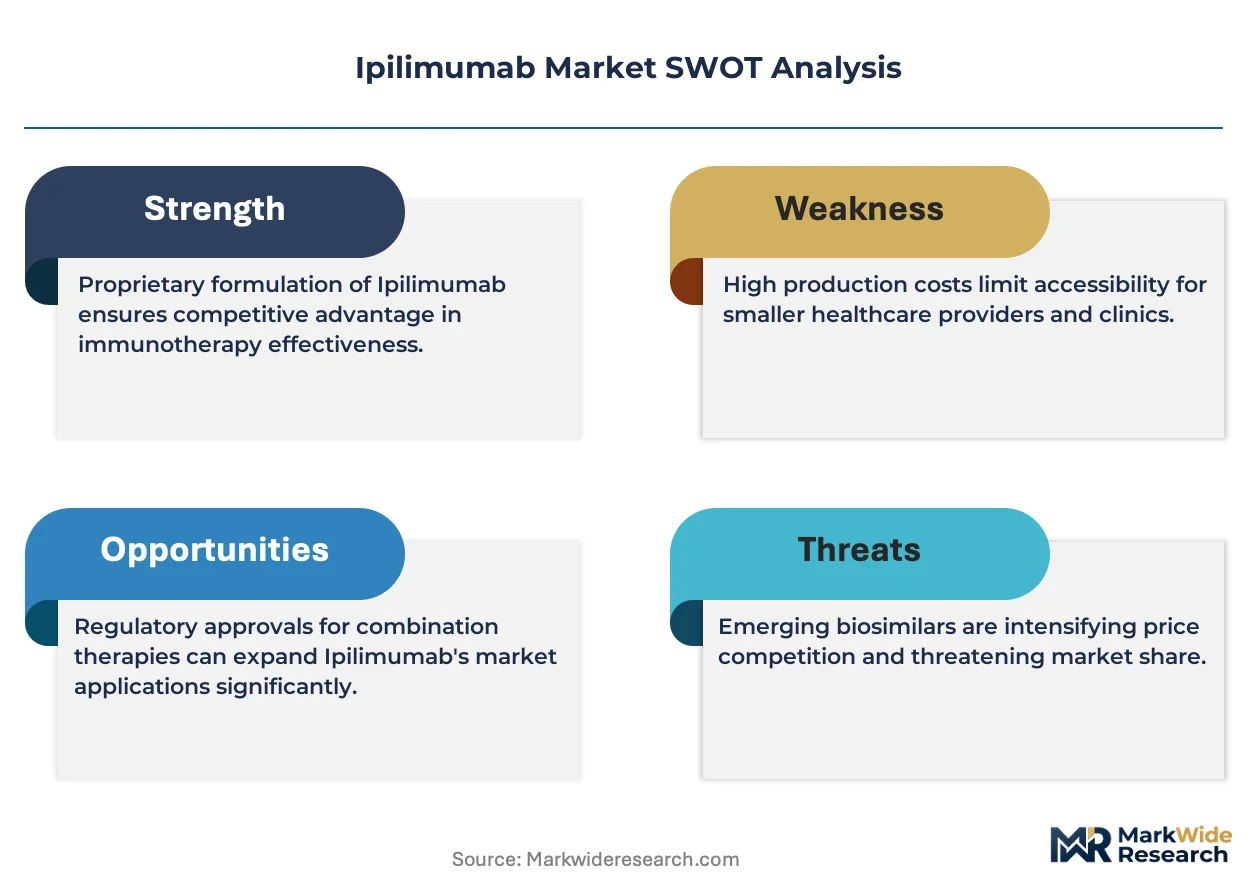
- CMS reimbursement expansion:Medicare Part B coverage for outpatient infusion services in the United States removes cost barriers for elderly melanoma patients.
- EMA conditional marketing authorization:The European framework permits earlier patient access while confirmatory trials continue, accelerating European commercialization timelines.
- Biomarker testing integration:PD-L1 and tumor mutational burden assays now standardly precede ipilimumab combination decisions, sharpening patient selection and response rates.
Market Restraints
- Chinese hamster ovary cell supply concentration:Recombinant manufacturing depends on a limited pool of qualified bioreactor facilities, creating single-source vulnerability.
- Immune-related adverse event management costs:Colitis and endocrinopathy monitoring requirements inflate total cost of care beyond drug acquisition alone.
- PD-1 monotherapy substitution:Pembrolizumab and nivolumab single-agent protocols capture lower-risk patients who might otherwise receive combination therapy.
Strategic Opportunities
- Neoadjuvant melanoma protocols:Pre-surgical administration in Stage III patients represents an entirely new treatment window with no established standard of care.
- Japan PMDA immunogenicity harmonization:Streamlined testing requirements for foreign-manufactured biologics reduce regulatory friction for market entry.
- Subcutaneous formulation development:Self-administration potential would shift distribution from infusion centers to specialty pharmacy channels.
Industry Challenges
- Immuno-oncology fellowship scarcity:Academic training programs produce fewer certified specialists than hospital expansion of cellular therapy units requires.
- Combination trial complexity:Dose-finding studies with multiple checkpoint inhibitors demand larger patient cohorts and extended safety follow-up periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ipilimumab Market |
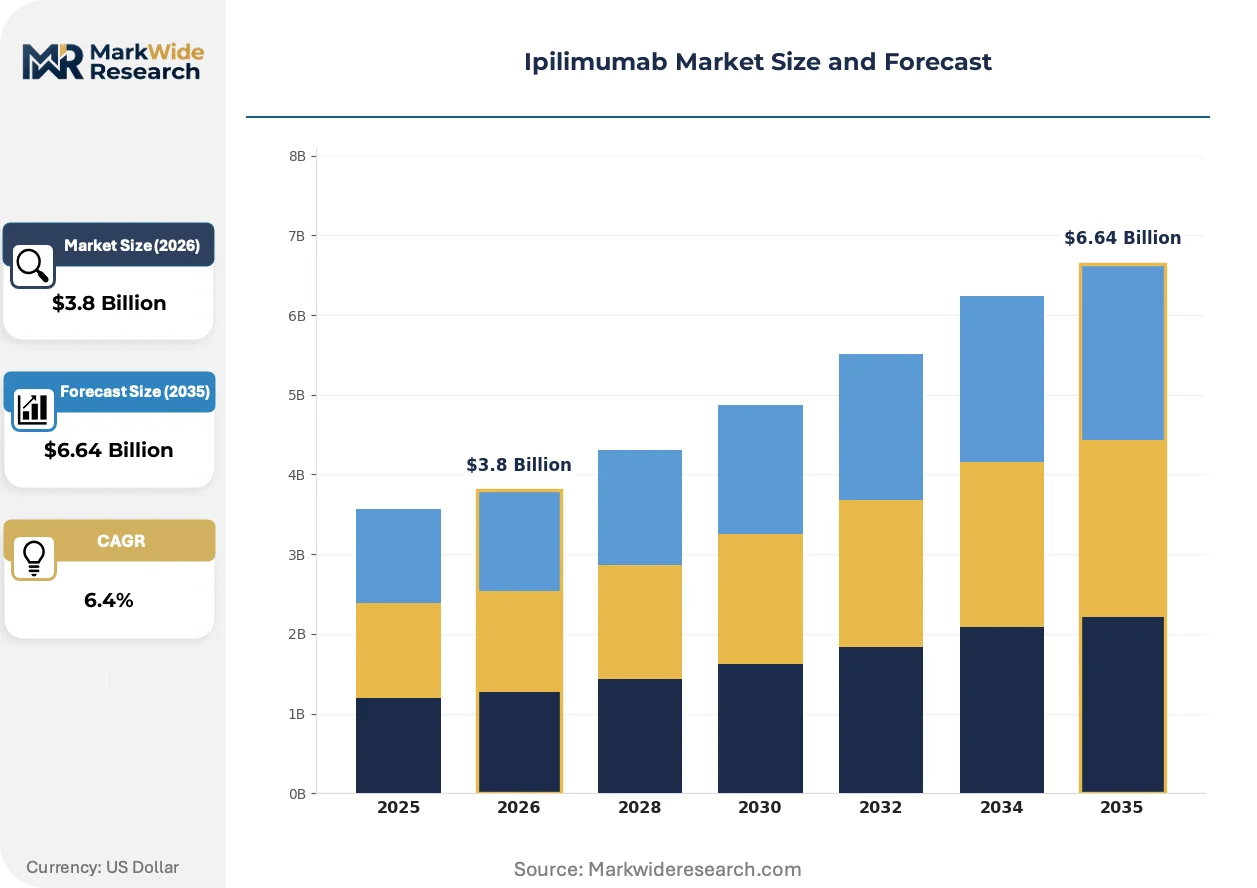
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Subcutaneous, Combination Therapy, Monotherapy Indication: Melanoma, Colorectal Cancer, Lung Cancer, Head and Neck Cancer Patient Type: Adults, Pediatric, Elderly, Immunocompromised Distribution Channel: Specialty Pharmacy, Hospital Pharmacy, Online Pharmacy, Direct Sales |
| Companies Covered | Bristol-Myers Squibb, Merck & Co., Inc., Roche Holding AG, AstraZeneca, Pfizer Inc., Novartis AG, Amgen Inc., Sanofi, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ipilimumab Market Strategic Shifts
Next-generation sequencing and real-world evidence platforms are collapsing the gap between biomarker discovery and clinical deployment, fundamentally altering how CTLA-4 inhibitors are positioned against competing immunotherapy modalities.
Fixed-duration combination protocols are displacing indefinite maintenance regimens in melanoma treatment guidelines. Memorial Sloan Kettering and MD Anderson adopted four-cycle limits for ipilimumab-nivolumab induction in 2024. This compression is reducing cumulative toxicity exposure while preserving survival endpoints, forcing manufacturers to defend value through response durability rather than treatment duration.
The FDA's Project Optimus dose-optimization mandate now requires randomized dose-comparison arms in oncology trials. Sponsors must demonstrate that selected doses maximize efficacy-toxicity ratios rather than defaulting to maximum tolerated doses. This policy shift most impacts Phase II combination studies where ipilimumab dosing previously followed melanoma-established schemas regardless of tumor type.
Academic medical centers now demand integrated diagnostic-therapeutic contracts that bundle biomarker testing with drug procurement. University of Texas Southwestern and Stanford Health Care consolidated vendor relationships to capture volume discounts on sequencing panels paired with checkpoint inhibitor purchases. This bundling concentrates purchasing power among large integrated delivery networks in the United States, marginalizing smaller community oncology practices.
Ipilimumab Market Segmentation
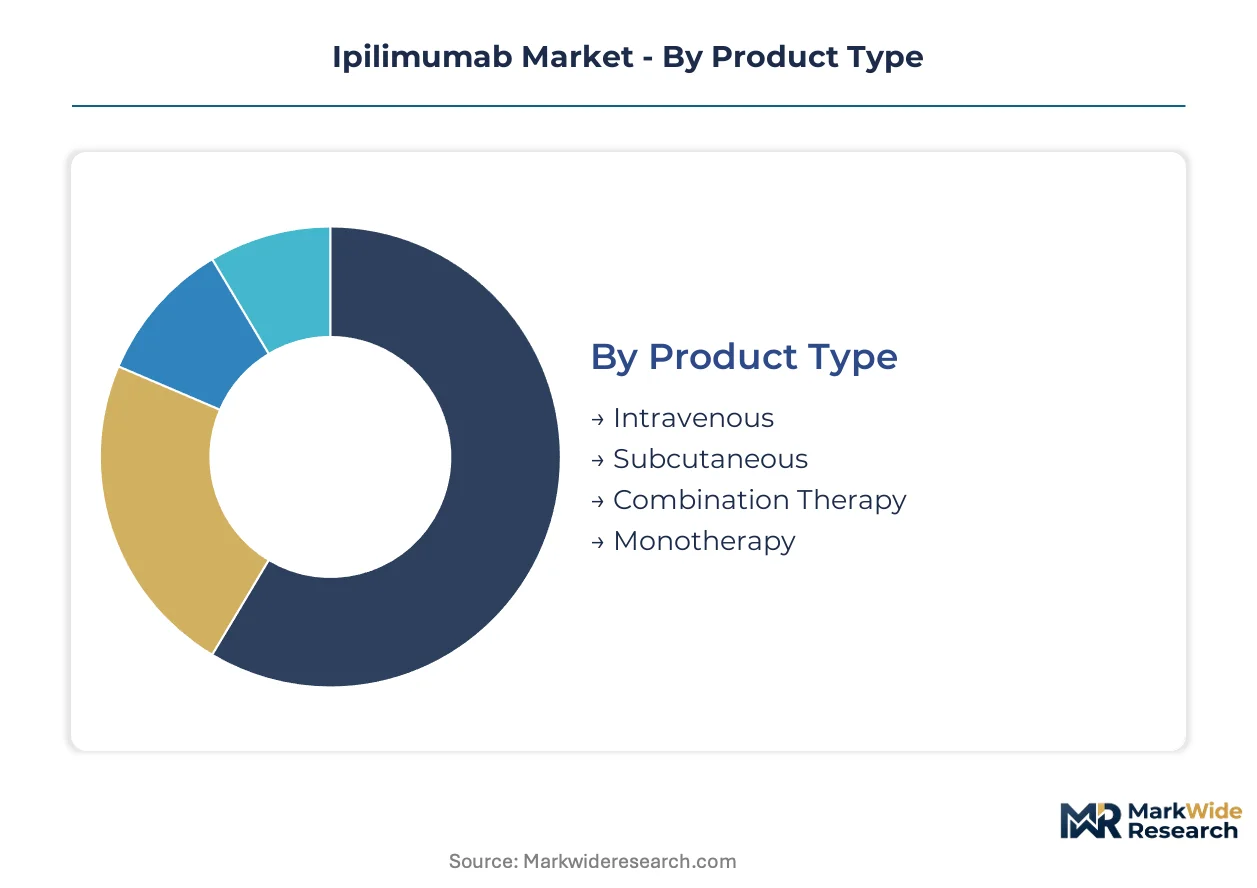
Ipilimumab's commercial architecture fragments across four distinct dimensions, each governing how the CTLA-4 inhibitor reaches patients and captures value. Understanding these segment boundaries clarifies why specialty pharmacy dominates outpatient volumes while hospital pharmacy secures inpatient loading doses.
Product Type:
Intravenous formulations flow through hospital infusion centers and specialty pharmacy networks, while subcutaneous development promises to reroute volumes toward self-administration channels.
- Intravenous:The established administration route delivers 3 mg/kg over 90 minutes through recombinant protein infusion. Academic medical centers in the United States concentrate demand here, driven by Medicare Part B reimbursement structures that favor supervised administration.
- Combination Therapy:Ipilimumab paired with nivolumab anchors melanoma and lung cancer protocols, requiring coordinated biologic procurement and complex adverse event management. Memorial Sloan Kettering and MD Anderson adopted fixed four-cycle induction limits, compressing treatment duration while preserving survival endpoints.
- Subcutaneous:Investigational formulations aim to shift distribution from infusion centers to home-based administration, though immunogenicity concerns and PMDA testing standards complicate regulatory pathways.
- Monotherapy:Single-agent use persists in select melanoma maintenance settings and clinical trial contexts where combination toxicity proves prohibitive.
By volume, intravenous leads. By growth pace, combination therapy is ahead.
Indication:
Cost tier stratification separates melanoma's established reimbursement from lung cancer's expanding but contested coverage landscape.
- Melanoma:The foundational indication commands premium pricing through established adjuvant and metastatic protocols. United States Medicare coverage removes cost barriers for elderly patients, sustaining the largest patient volume segment.
- Lung Cancer:Non-small cell applications expand through checkpoint inhibitor combinations, though PD-1 monotherapy substitution captures lower-risk patients who might otherwise receive dual therapy.
- Colorectal Cancer:MSI-high subpopulations represent a narrow but defensible addressable market with distinct biomarker requirements.
- Head and Neck Cancer:Squamous cell carcinoma investigations proceed through EMA conditional authorization frameworks, accelerating European access while confirmatory trials continue.
Melanoma retains the deepest penetration. Lung cancer shows the steepest expansion trajectory.
Patient Type:
Application intensity varies sharply across immunocompetency strata, with elderly patients requiring enhanced monitoring protocols.
- Elderly:Patients over 65 constitute the dominant volume segment in Western markets, where Medicare reimbursement and melanoma incidence curves intersect. Immune-related adverse event management costs inflate total care expenditure beyond drug acquisition alone.
- Adults:The core commercial demographic spans working-age populations eligible for employer-sponsored coverage and commercial payer contracts.
- Immunocompromised:Transplant recipients and autoimmune patients require specialized protocol modifications, limiting addressable volume but commanding premium coordination services.
- Pediatric:Rare pediatric indications face restricted labeling and limited trial enrollment, constraining commercial relevance despite orphan drug designations.
Elderly patients anchor volume. Immunocompromised populations are gaining share fastest.
Distribution Channel:
Margin concentration distinguishes inpatient loading doses from outpatient maintenance volumes, with online channels capturing emerging self-administration formats.
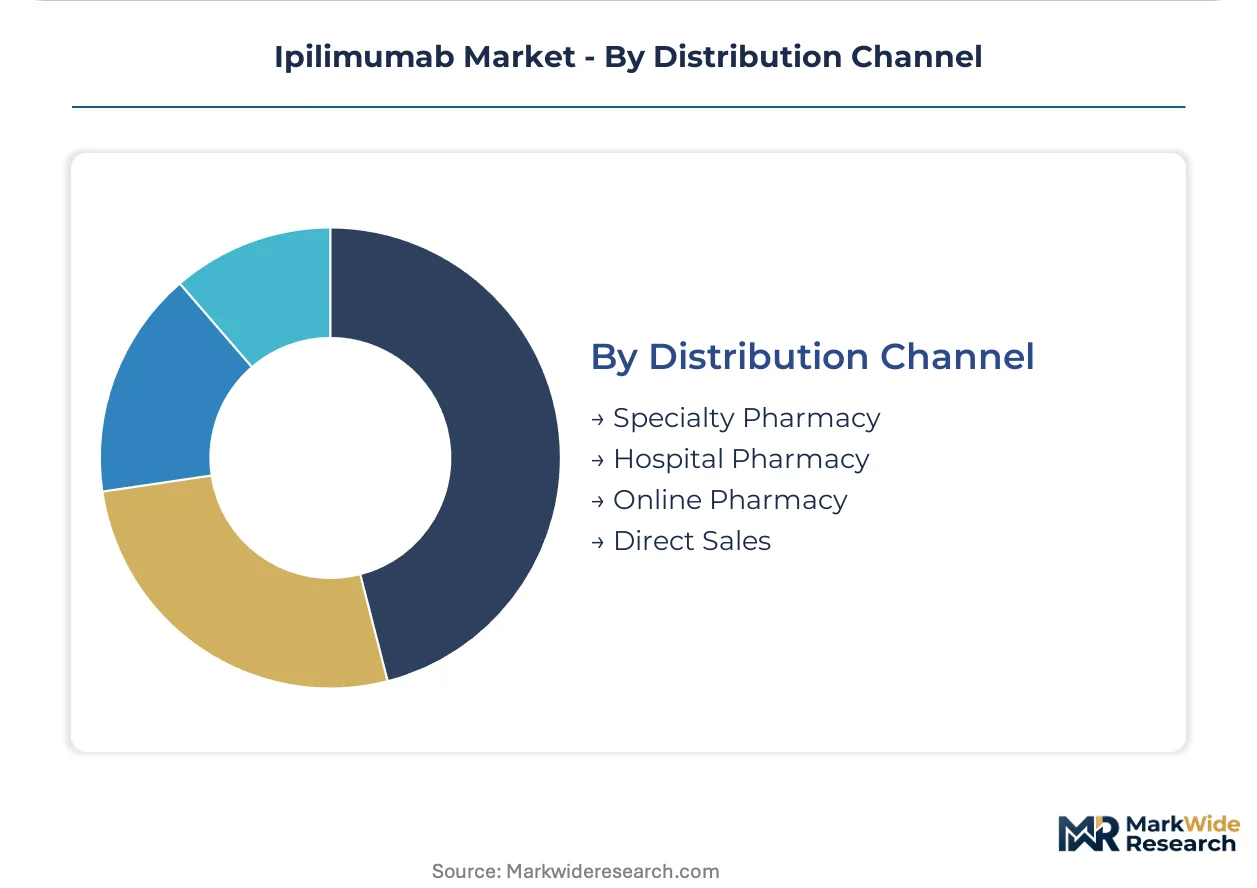
- Specialty Pharmacy:Outpatient infusion and home delivery services control the majority of maintenance dose volumes. CVS Specialty and Accredo anchor United States distribution through integrated payer contracts.
- Hospital Pharmacy:Inpatient loading doses and academic medical center procurement capture higher per-unit margins through bundled diagnostic-therapeutic contracts. University of Texas Southwestern and Stanford Health Care consolidated vendor relationships to extract volume discounts.
- Direct Sales:Manufacturer-to-provider arrangements serve select integrated delivery networks with captive infusion capacity.
- Online Pharmacy:Emerging channels target patient assistance program fulfillment and oral oncology adjacents, though biologic cold chain requirements limit current penetration.
Specialty pharmacy leads by volume. Hospital pharmacy leads by margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, with Medicare reimbursement structures and academic medical center concentration shaping utilization patterns across North America, Europe, and Asia-Pacific.
United States
Medicare Part B coverage removes cost barriers for elderly melanoma patients while Memorial Sloan Kettering and MD Anderson anchor demand through fixed four-cycle induction protocols. CMS reimbursement rates for outpatient infusion services directly influence prescribing patterns. The Northeast Corridor and Texas Medical Center concentrate the highest-volume infusion centers.
Germany
EMA conditional marketing authorization accelerates commercialization timelines while statutory health insurance funds negotiate combination therapy coverage. The country's national pharmaceutical regulator, BfArM, maintains stringent pharmacovigilance requirements for immune-related adverse event reporting. Bavaria and Baden-Württemberg host the densest networks of university hospital oncology departments.
Japan
PMDA immunogenicity testing standards filter market entry for foreign-manufactured biologics, creating distinct regulatory friction for CTLA-4 inhibitors. The Ministry of Health, Labour and Welfare sets reimbursement prices through biennial price revisions that compress margins. Kanto and Kansai regions concentrate demand through designated cancer care hospitals in Tokyo and Osaka.
United Kingdom
NICE technology appraisals determine National Health Service access for combination immunotherapy regimens, creating coverage uncertainty during evaluation periods. The MHRA operates under retained EU legislation while developing independent accelerated assessment pathways. London and the Greater Manchester cancer network anchor regional prescribing concentration.
France
ANSM marketing authorization procedures align with EMA centralized approvals while HAS transparency committee ratings influence hospital formulary placement. Complementary universal health coverage reduces patient cost-sharing for infused cancer therapies. Île-de-France and Auvergne-Rhône-Alpes concentrate academic medical center capacity and clinical trial enrollment.
Ipilimumab Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding manufacturing scale and the latter occupying biomarker-diagnostic niches. The structure consolidates around first-mover manufacturing assets and checkpoint inhibitor combination portfolios. Three archetypes dominate: integrated biopharmaceutical conglomerates with captive biologics capacity, diagnostic-therapeutic integrators bundling testing with drug procurement, and emerging biosimilar developers targeting patent cliffs. Capacity expansion and strategic diagnostic partnerships constitute the primary competitive vectors.
Within the integrated biopharmaceutical tier, Bristol-Myers Squibb and Merck & Co., Inc. occupy positions defined by manufacturing scale and combination study investment, while Roche Holding AG exemplifies the diagnostic-therapeutic integration archetype through biomarker platform control. These three anchors represent distinct strategic postures: manufacturing-led supply contracting, PD-1 combination pipeline breadth, and testing-therapy bundling respectively.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Merck & Co., Inc. |
| Roche Holding AG |
| AstraZeneca |
| Pfizer Inc. |
| Novartis AG |
| Amgen Inc. |
| Sanofi |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
FDA accelerated approval pathways gate both supply qualification and price differentiation simultaneously, requiring manufacturers to demonstrate efficacy-toxicity optimization before securing premium positioning in Medicare Part B reimbursement tiers. This regulatory filter concentrates pricing power among first-mover biologics manufacturers while compressing margins for late entrants facing biosimilar development timelines.
Pricing Analysis
Long-term offtake contracts with integrated delivery networks anchor pricing stability for Bristol-Myers Squibb, while spot procurement through group purchasing organizations introduces variability for smaller infusion centers. Price differentiation hinges on biomarker testing bundling and volume scale, with academic medical centers extracting steeper discounts than community oncology practices. Cost compression in the maintenance dose segment intensifies as fixed-duration protocols reduce per-patient revenue. Employer-sponsored coverage populations show lowest price sensitivity; Medicare-dependent elderly patients face highest out-of-pocket exposure despite Part B reimbursement.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled biologics from Chinese hamster ovary cell facilities concentrate vulnerability on trans-Pacific trade lanes, where container availability constraints and port congestion at Los Angeles-Long Beach disrupt cold chain integrity. Manufacturing draws from qualified bioreactor facilities in the United States, Ireland, and Puerto Rico, with recombinant protein production resting on fetal bovine serum and single-use bioreactor bag dependencies. Single-source vulnerability at the cell line development stage creates regulatory restriction risk if contamination events trigger batch recalls. Distribution runs through specialty pharmacy networks for outpatient maintenance, with hospital pharmacy capturing inpatient loading doses through direct manufacturer arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ipilimumab Market operates through a bottleneck in certified immuno-oncology specialists, where fellowship training capacity lags hospital expansion of cellular therapy units by a widening margin. This capability scarcity rewards stakeholders who secure clinical talent pipelines ahead of protocol expansion.
For Market Incumbents: Fortify manufacturing scale advantages through captive bioreactor capacity additions in Singapore and Ireland, insulating against Chinese hamster ovary cell supply concentration. Deepen diagnostic-therapeutic bundling with Memorial Sloan Kettering and MD Anderson to lock in fixed-cycle protocol adoption before biosimilar entry erodes margin position. For New Entrants and Emerging Players: FDA Project Optimus dose-optimization studies offer a certification fast-track for sponsors willing to run randomized dose-comparison arms in combination trials. Target neoadjuvant melanoma protocols as the most penetrable white space, where no established standard of care exists and academic medical centers seek novel induction regimens. Pursue subcutaneous formulation partnerships to bypass infusion center capacity constraints entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across combination therapy manufacturing, as multi-product bioreactor facilities require larger upfront investment than single-agent legacy plants. Five-to-ten year viability favors diagnostic platform integrators with biomarker testing captive to therapy selection. Watch PMDA immunogenicity harmonization negotiations as the signal indicating when Japanese market entry friction will ease for foreign-manufactured biologics.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Project Optimus dose-optimization arms satisfy FDA requirements while refining efficacy-toxicity ratios. |
| Regulatory Approval Pathway | EMA conditional marketing authorization accelerates European commercialization before confirmatory trial completion. |
| Manufacturing Scale-Up | Captive bioreactor capacity in Singapore reduces trans-Pacific logistics vulnerability for Asian markets. |
| Pipeline Diversification | Neoadjuvant melanoma indications expand addressable patients into pre-surgical treatment windows. |
| Strategic Partnership | Diagnostic-therapeutic bundling with Stanford Health Care concentrates purchasing power against biosimilar entrants. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling triangulates with top-down market sizing across indication and distribution channel segments.
Sensitivity analysis on pricing assumptions and biosimilar entry timing shapes the analytical framework across the projection horizon. Segmentation dimensions include indication type, administration route, patient population immunocompetency status, and regional regulatory cluster. CAGRs derive from patient volume trajectories, protocol duration compression effects, and reimbursement rate evolution. Forecast inputs incorporate biomarker testing penetration curves and fixed-cycle adoption rates at major academic medical centers.
The analysis sits within stated boundaries; outcomes outside current FDA accelerated approval frameworks, EMA conditional authorization timelines, or stable CMS reimbursement rates would require recalibration. Forecasts reflect assumptions regarding immune-related adverse event management cost trajectories and combination therapy substitution patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market