
 Allulose Powder Market | 2026-2036
Allulose Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Allulose Powder Market Insights
North American enzymatic conversion capacity is rebalancing as domestic producers scale D-psicose output to serve beverage and bakery formulators. Tate & Lyle leverages its ingredient science heritage to anchor clean-label sweetener portfolios for multinational food manufacturers. CJ Cheil Jedang competes through integrated fermentation infrastructure that sustains cost discipline across Asian and North American supply corridors. Matsutani Chemical Industry Co. Ltd. specializes in rare sugar research originating from Kagawa Prefecture, positioning its output for premium nutraceutical applications where purity specifications tighten.
Allulose powder is a low-calorie monosaccharide, specifically D-psicose, produced through enzymatic epimerization of fructose and yielding approximately 0.4 calories per gram while delivering 70% of sucrose sweetness. Its primary commercial purpose centers on sugar reduction in processed foods without the cooling aftertaste or laxative thresholds associated with polyol alternatives. Conventional allulose dominates volume production due to established enzymatic conversion economics, though organic-certified supply lines command margin premiums as clean-label procurement intensifies among North American food manufacturers. The beverages application leads current offtake as carbonated and ready-to-drink brands reformulate around reduced-sugar claims, while confectionery represents the fastest-growing segment as chocolate and gummy producers solve crystallization and browning challenges inherent to allulose chemistry.
The FDA's Nutrition Facts labeling exemption for allulose directly shapes demand by permitting zero added-sugar declarations, fundamentally altering formulation economics for US food manufacturers. USDA organic certification requirements and GRAS self-affirmation pathways create layered compliance thresholds that filter market access for new entrants. The FSSC 22000 and ISO 22000 frameworks govern food safety management across production facilities, with audit intensity rising as ingredient traceability expectations harden among downstream buyers. Stakeholders must monitor pending GRAS affirmation petitions and evolving calorie disclosure rules that could recalibrate competitive positioning between allulose and emerging rare sugar alternatives.
Market Dynamics
The FDA's 2019 Nutrition Facts labeling exemption for allulose has fundamentally restructured formulation economics for US food manufacturers, converting a niche rare sugar into a mainstream sugar-reduction tool. This regulatory inflection point now drives enzymatic conversion capacity expansion and downstream procurement patterns.
Growth Catalysts
- US FDA Labeling Exemption:The zero added-sugar declaration permitted for allulose-containing products accelerates reformulation across carbonated beverages and ready-to-drink portfolios.
- Keto-Aligned Product Development:Functional food manufacturers targeting low-carbohydrate consumer segments drive procurement volumes for clean-label sweetener alternatives.
- Enzymatic Epimerization Advances:Improved D-psicose 3-epimerase efficiency reduces production costs and expands commercial viability for bakery applications.
Market Restraints
- Fructose Feedstock Volatility:Corn-derived fructose price swings directly compress margins for enzymatic conversion operations dependent on agricultural commodity inputs.
- Asian Supply Concentration:CJ CheilJedang and Matsutani Chemical anchor rare sugar output in South Korea and Japan, creating geographic vulnerability for North American formulators.
- Browning and Crystallization Chemistry:Allulose's Maillard reaction behavior and humectancy limits direct substitution ratios in chocolate and hard candy production.
Strategic Opportunities
- Organic-Certified Supply Lines:USDA organic certification commands margin premiums as clean-label procurement intensifies among natural product retailers.
- Confectionery Application Expansion:Chocolate and gummy producers solving texture challenges unlock the fastest-growing segment beyond beverages.
- EU Novel Food Authorization Pathway:EFSA safety assessments progressing toward regulatory acceptance open formulation opportunities across European food manufacturers.
Industry Challenges
- GRAS Self-Affirmation Complexity:New entrants face layered compliance thresholds requiring toxicology dossiers and FDA notification pathways that extend market access timelines.
- Enzyme Engineering Talent Scarcity:Specialist biochemists capable of optimizing D-psicose 3-epimerase specificity remain concentrated in rare sugar research clusters.
- ISO 22000 Audit Intensification:Downstream buyers harden traceability expectations, forcing facility-level food safety management system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allulose Powder Market |
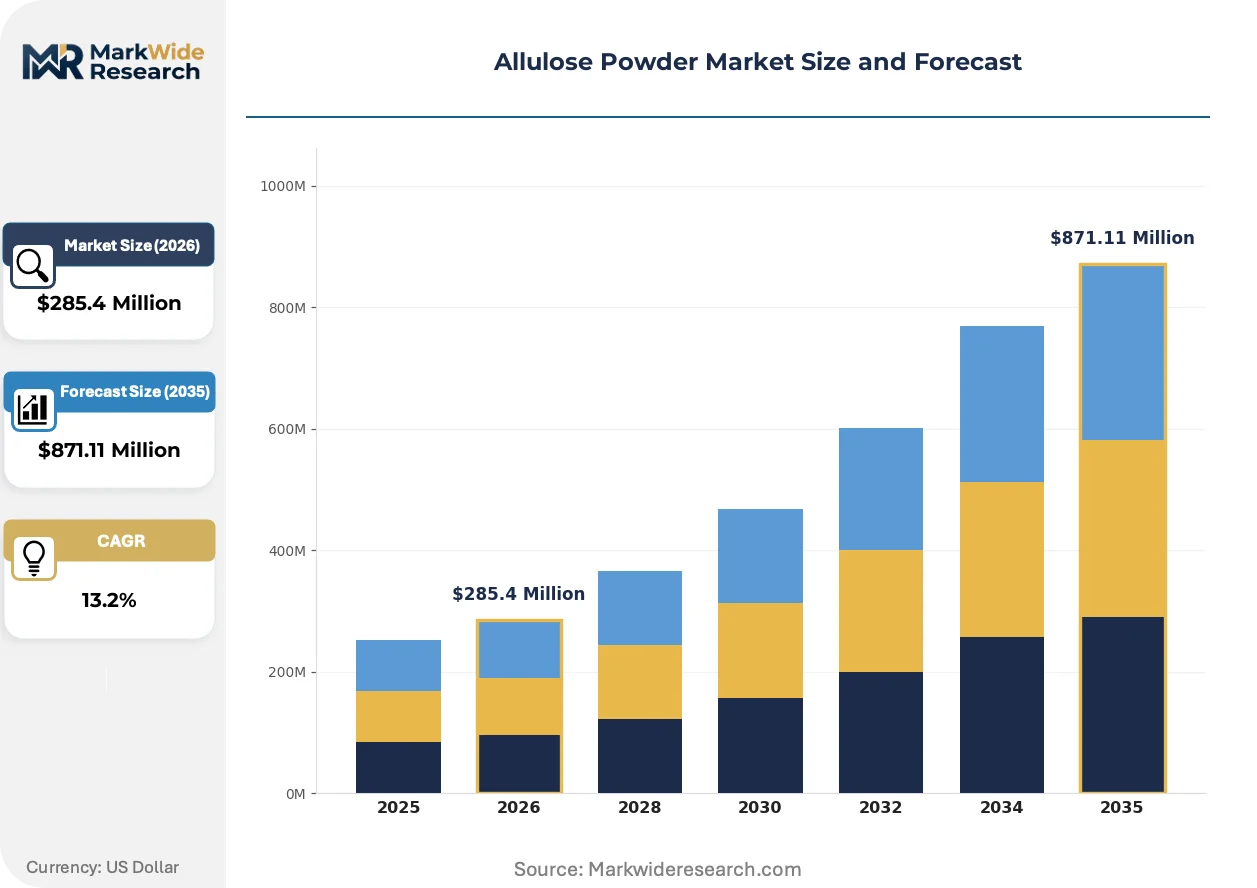
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $871.11 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Blended, Granulated Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Nutraceuticals, Personal Care, Restaurants Distribution Channel: Online, Supermarkets, Health Stores, Specialty Retailers |
| Companies Covered | Anderson Advanced Ingredients, Apura Ingredients, Bonumose LLC, CJ Cheil Jedang, Ingredion Incorporated, Matsutani Chemical Industry Co. Ltd., Samyang Corporation, Tate & Lyle, Heartland Food Products Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allulose Powder Market Trends and Innovations
Formulation science is converging with regulatory arbitrage as manufacturers exploit labeling advantages while solving allulose's functional limitations in heat-processed applications.
Continuous enzymatic conversion systems are unifying upstream fermentation with downstream crystallization, collapsing batch-to-batch variation that historically plagued rare sugar production. Beverage formulators adopting these integrated platforms secure supply consistency for high-volume carbonated lines. The technology is unifying quality specifications across North American and Asian supply corridors, reducing qualification burdens for multinational procurement teams.
EFSA's ongoing novel food assessments for D-psicose are reshaping European formulation roadmaps. Manufacturers awaiting positive opinions are pre-qualifying supply chains and reformulating prototypes to capture first-mover positioning. Confectionery applications face the steepest technical barriers under this regulatory uncertainty, as browning chemistry requires validation beyond safety dossiers.
Direct supplier relationships are displacing ingredient distributor intermediation as large food manufacturers secure dedicated allulose volumes. Tate & Lyle and domestic enzymatic conversion specialists field technical service teams embedded in customer R&D facilities. This channel compression is most visible in United States keto-aligned brands, where formulation speed determines shelf positioning cycles.
Allulose Powder Market Segmentation
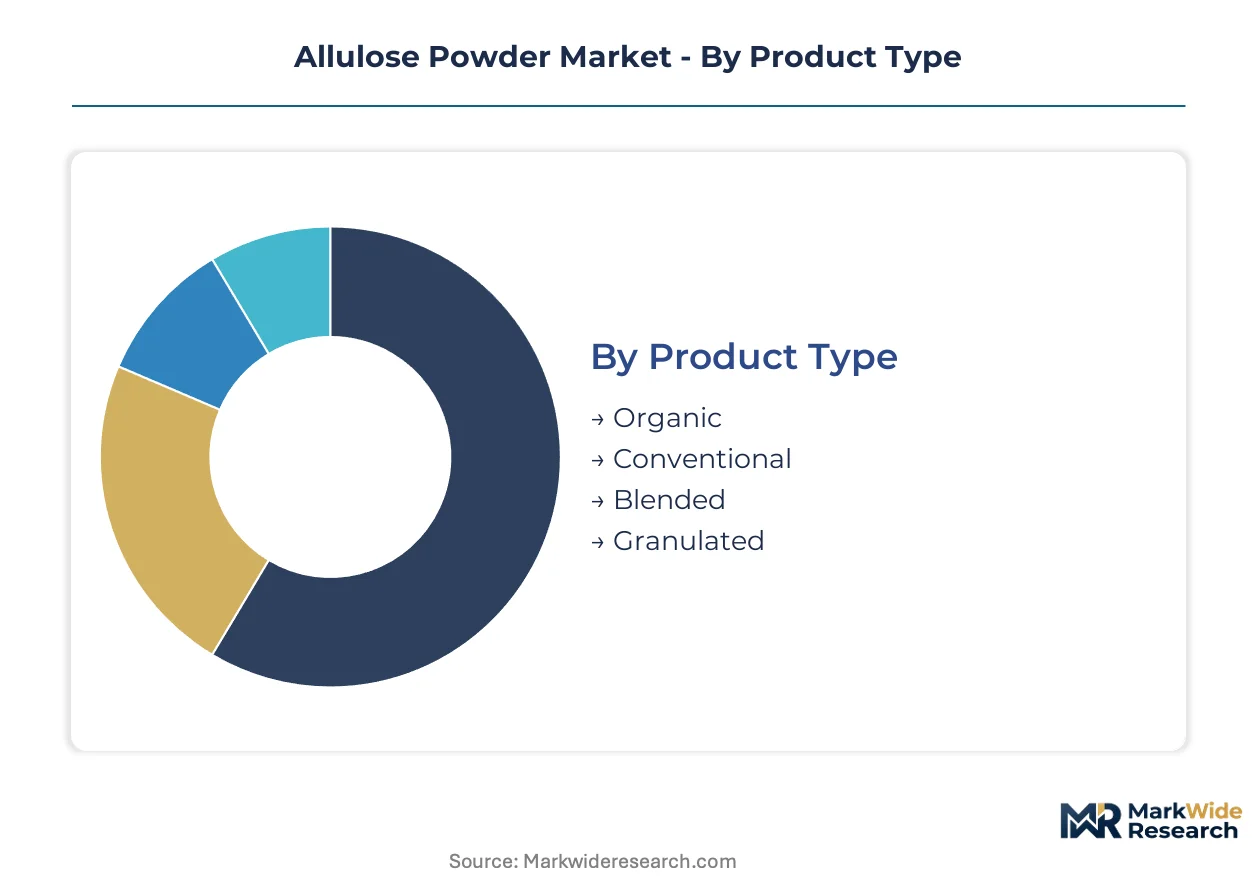
Allulose powder procurement patterns diverge sharply across product certifications, application heat-stability requirements, and channel traceability demands. Buyers prioritize functional performance in beverages, label claims in nutraceuticals, and cost efficiency in food service.
Product Type:
Cost tier separates buyers seeking USDA premiums from those optimizing enzymatic conversion economics at scale.
- Conventional:Standard enzymatic epimerization of corn-derived fructose yields D-psicose with established purity specifications. Beverage formulators in the United States anchor procurement volumes here, leveraging FDA labeling exemptions for zero added-sugar claims while managing Maillard reaction limitations in heat-processed applications.
- Organic:Non-GMO fructose feedstocks and certified enzymatic processing command margin premiums of 15-25% over conventional supply. Natural product retailers and clean-label food manufacturers concentrate demand, particularly for keto-aligned brands targeting ingredient transparency as a competitive differentiator.
- Blended:Allulose-monk fruit or allulose-stevia combinations balance sweetness intensity with cost per serving in reduced-sugar formulations.
- Granulated:Crystalline particle size distributions optimize for tabletop sweetener and home baking applications where dissolution behavior matches sucrose expectations.
Conventional supply leads volumes today; organic-certified lines are gaining share fastest.
Application:
Heat exposure tolerance determines substitution ratios and formulation complexity across processing environments.
- Beverages:Ready-to-drink and carbonated applications exploit allulose's clean sweetness without cooling aftertaste or polyol laxative thresholds. United States brands reformulating around reduced-sugar claims drive the steepest procurement expansion, supported by FDA labeling advantages.
- Confectionery:Chocolate and gummy manufacturers face crystallization control and browning chemistry constraints that limit direct sucrose replacement. Technical service investments from enzymatic conversion suppliers are unlocking texture solutions in premium sugar-free segments.
- Bakery:Yeast-raised and chemically leavened goods require modified allulose ratios to manage moisture retention and crust color development.
- Dairy:Fermented and frozen applications leverage humectancy properties for texture stabilization in reduced-sugar ice creams and yogurts.
Beverage applications anchor current demand; confectionery is expanding most quickly as texture barriers resolve.
End User:
Volume scale and technical service intensity separate multinational formulators from specialty ingredient buyers.
- Food Manufacturers:Large-scale reformulation of legacy brands around reduced-sugar claims requires dedicated supply contracts and embedded R&D collaboration. Direct supplier relationships are displacing distributor intermediation for high-volume carbonated and ready-to-drink portfolios.
- Nutraceuticals:Supplement and functional food producers prioritize GRAS documentation and batch-to-batch consistency for keto-aligned protein powders and meal replacements.
- Personal Care:Oral care and cosmetic applications exploit non-cariogenic and humectant properties in limited specialty volumes.
- Restaurants:Food service procurement concentrates on cost-per-serving optimization for beverage syrup reformulations.
Food manufacturers dominate procurement scale today; nutraceuticals are climbing the fastest as functional food segments mature.
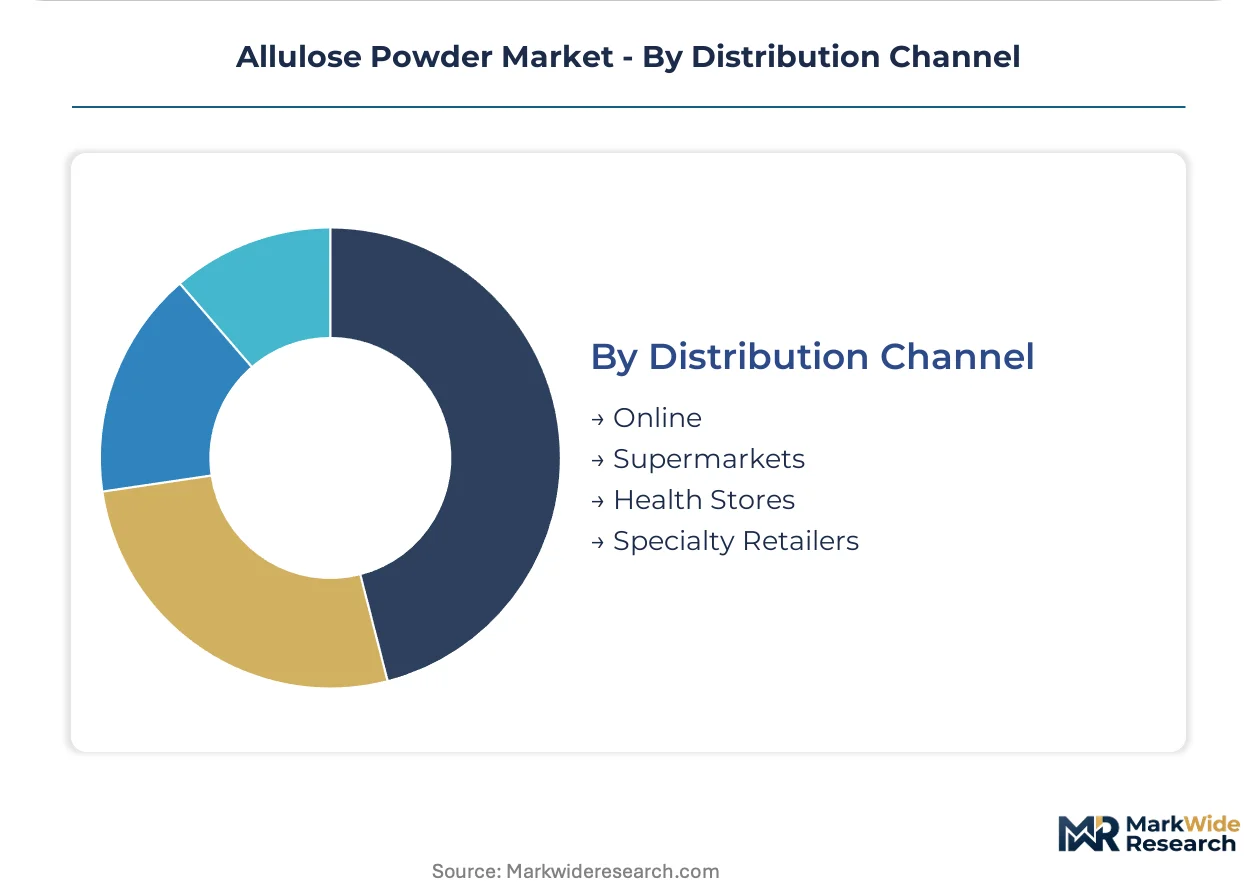
Distribution Channel:
Traceability documentation and technical support depth vary across channel structures.
- Specialty Retailers:Natural product and keto-focused stores command premium pricing for organic-certified and small-batch allulose offerings. Clean-label procurement intensity concentrates here, with buyers validating non-GMO and allergen-free documentation.
- Online:Direct-to-consumer and B2B platforms enable rapid formulation ingredient sourcing for emerging brands and R&D procurement. United States keto-aligned startups leverage these channels for speed-to-market advantages.
- Health Stores:Regional chains and independent operators serve clean-label consumers with curated sweetener assortments.
- Supermarkets:Mass retail penetration remains limited as allulose awaits broader consumer recognition beyond specialty segments.
Specialty retailers anchor premium positioning today; online channels are gaining share fastest as direct B2B procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as enzymatic conversion capacity migrates toward jurisdictions with favorable rare-sugar classification and lower compliance burdens. Manufacturers exploit cost-of-compliance gaps between FDA-exempt North American markets and pending EFSA authorization zones.
United States
Beverage formulators in Atlanta, Chicago, and Austin drive procurement volumes for carbonated and ready-to-drink reformulations. The FDA's 2019 Nutrition Facts labeling exemption permits zero added-sugar declarations, accelerating enzymatic conversion capacity expansion in Iowa and Illinois corn-belt corridors. Domestic D-psicose output is scaling to reduce dependence on Asian import lanes.
South Korea
CJ CheilJedang anchors integrated fermentation infrastructure serving North American and Asian supply corridors. The MFDS maintains GRAS-equivalent safety frameworks for rare sugar production while subsidizing biotech R&D clusters in Incheon and Daejeon. Export-oriented enzymatic conversion facilities concentrate in the Seoul Capital Area.
Japan
Matsutani Chemical Industry Co. Ltd. leverages Kagawa Prefecture rare sugar research heritage for premium nutraceutical applications. METI funding supports D-psicose 3-epimerase optimization programs in Takamatsu. Purity specifications tighten for pharmaceutical-grade output destined for domestic functional food manufacturers.
China
Enzymatic conversion specialists in Shandong and Jiangsu provinces scale conventional allulose output for food service and industrial ingredient channels. SAMR novel food regulations create compliance thresholds that filter market access for new entrants. NMPA-aligned toxicology dossiers extend approval timelines versus FDA self-affirmation pathways.
Germany
EFSA novel food assessments for D-psicose are progressing through safety validation stages in Parma-coordinated reviews. German bakery and confectionery manufacturers in Bavaria and North Rhine-Westphalia pre-qualify supply chains for post-authorization formulation launches. REACH-aligned substance registrations create layered documentation requirements for enzymatic conversion imports.
Allulose Powder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic-certified and blended-sweetener niches. Market structure consolidates around integrated fermentation specialists with captive enzyme engineering capabilities and ingredient-science heritage players with multinational technical service networks. Three archetypes dominate: Asian integrated biotech conglomerates, North American clean-label ingredient platforms, and rare-sugar research specialists. Capacity expansion and direct supplier relationship compression represent the dominant competitive vectors as large food manufacturers displace distributor intermediation.
Among Asian integrated producers, CJ CheilJedang and Matsutani Chemical Industry Co. Ltd. exemplify the fermentation-infrastructure archetype, occupying positions that leverage domestic rare-sugar research clusters for premium output. Tate & Lyle represents the ingredient-science heritage tier, anchoring multinational formulation support capabilities for beverage and bakery manufacturers. These three companies illustrate the geographic bifurcation between Asian supply concentration and North American technical service depth.
| Leading Market Players |
|---|
| Anderson Advanced Ingredients |
| Apura Ingredients |
| Bonumose LLC |
| CJ Cheil Jedang |
| Ingredion Incorporated |
| Matsutani Chemical Industry Co. Ltd. |
| Samyang Corporation |
| Tate & Lyle |
| Heartland Food Products Group |
| Others |
Pricing and Supply Chain Analysis
Corn futures volatility on the Chicago Board of Trade cascades through enzymatic conversion economics into three distinct pricing tiers for allulose powder buyers. Fructose feedstock swings compress margins for conventional supply while amplifying premiums for organic-certified lines that hedge through non-GMO corn contracting.
Pricing Analysis
Direct-to-OEM discounts of 12-18% displace distributor margins as multinational beverage manufacturers secure dedicated allulose volumes through Tate & Lyle and domestic enzymatic conversion specialists. Pricing stratifies across USDA organic certification, conventional enzymatic grade, and blended sweetener formulations with monk fruit or stevia. Cost compression in conventional supply intensifies as Iowa and Illinois capacity expansion feeds spot-market liquidity. Food service procurement teams exhibit highest price sensitivity, while nutraceutical formulators absorbing GRAS documentation costs show lowest elasticity.
Supply Chain Analysis
Pacific container rates and inland rail tariffs from West Coast ports to Chicago distribution hubs add 8-14% to landed costs for Asian-sourced allulose. Production gravity centers on South Korea, Japan, and China where CJ CheilJedang, Matsutani Chemical, and Shandong enzymatic conversion specialists anchor output. Corn-derived fructose, D-psicose 3-epimerase enzymes, and crystallization energy feedstocks anchor input dependencies. Single-source vulnerability concentrates in Kagawa Prefecture rare sugar research clusters. Distribution runs through direct supplier relationships displacing ingredient distributor intermediation for high-volume carbonated and ready-to-drink portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Allulose powder procurement has entered a late-cycle quality phase where USDA organic certification and batch-to-batch enzymatic consistency command decisive premiums. Clean-label food manufacturers are shifting specifications toward non-GMO fructose feedstocks and FSSC 22000 audit documentation.
For Market Incumbents: Anticipate margin compression from domestic enzymatic conversion capacity scaling in Iowa and Illinois corn-belt corridors. Defensive consolidation moves center on backward integration into captive D-psicose 3-epimerase production and embedded technical service teams inside customer R&D facilities. Tate & Lyle's ingredient science heritage and CJ CheilJedang's fermentation infrastructure represent the consolidation archetypes to emulate. Certification investment in USDA organic and GRAS affirmation pathways anchors channel control against emerging clean-label entrants. For New Entrants and Emerging Players: Launch via specialty retailer and direct-to-consumer online channels before attempting multinational food manufacturer qualification. White-space targets concentrate in organic-certified supply lines commanding 15-25% margin premiums and blended allulose-stevia formulations for keto-aligned protein powders. The most penetrable segment sits in natural product retailers validating non-GMO documentation. Go-to-market acceleration exploits speed-to-market advantages through B2B platform procurement serving United States keto-aligned startups. For Investors and Strategic Acquirers: Consolidation pressure builds where enzymatic conversion capacity fragments across single-site fermentation specialists lacking integrated enzyme engineering capabilities. Long-term viability favors integrated biotech conglomerates with captive rare sugar research clusters and multinational technical service networks. Acquisition target archetypes include domestic enzymatic conversion specialists scaling D-psicose output and organic-certified processors with established non-GMO fructose supply contracts. The signal to watch is EFSA novel food authorization timing for European formulation market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Production | In-house D-psicose 3-epimerase capacity collapses batch-to-batch variation and secures cost discipline. |
| USDA Organic Certification Investment | Non-GMO fructose feedstock sourcing unlocks 15-25% margin premiums from clean-label procurement. |
| Embedded Technical Service Deployment | R&D facility integration accelerates formulation speed for carbonated beverage reformulation cycles. |
| Direct Supplier Relationship Compression | Eliminating distributor intermediation secures dedicated volumes for high-volume ready-to-drink portfolios. |
| EFSA Pre-Qualification Supply Chain Build | Early European supply chain validation captures first-mover positioning pending novel food authorization. |
Research Methodology
Bottom-up beverage and confectionery modeling reconciled against top-down enzymatic conversion capacity tracking forms the analytical core of this study. Primary interviews with plant managers at enzymatic conversion facilities, procurement leads at multinational food manufacturers, technical R&D directors at sweetener formulators, and regulatory affairs specialists at GRAS affirmation consultancies combined with secondary validation. Secondary sources include FDA GRAS notification databases, USDA organic certification registries, FSSC 22000 audit documentation, and customs trade data tracking D-psicose import flows. Triangulation across these sources reconciles supply-side capacity announcements with downstream procurement patterns.
Input-output matrices mapping fructose feedstock availability, enzyme conversion yields, and crystallization throughput to end-use demand segments across product type, application, and distribution channel dimensions generate volume and value trajectories. CAGRs derive from segment-level growth rate reconciliation against macro sweetener substitution trends. Industry-specific forecast inputs include FDA labeling exemption persistence assumptions and EFSA novel food authorization probability weightings.
Several conditions sit outside the modeled scope, including pending GRAS affirmation petition outcomes, fructose feedstock price shocks beyond historical volatility bands, and regulatory reclassification of allulose added-sugar status. Forecasts reflect documented assumptions about enzymatic conversion efficiency gains and clean-label procurement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Specialty Sweeteners Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Sugar Polyols Market
Sweeteners
Sorbitol Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Maltodextrin Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Trehalose Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Digestion Resistant Maltodextrin Market