
 Molasses Market | 2026-2036
Molasses Market Size, Share, and Industry Trends Forecast 2026-2036
Molasses Market Outlook
Brazil is fragmenting as new cane crushing capacity comes online across São Paulo and Minas Gerais. Cosan S.A. leverages its vertically integrated sugar-energy platform to dominate South American supply. Tereos SCA anchors European beet molasses output through cooperative processing networks in France and Belgium. Archer Daniels Midland Company competes across North American distribution with extensive grain and sweetener logistics infrastructure.
Molasses is a viscous byproduct of sugar refining containing 30-50% sucrose, invert sugars, and mineral ash, recovered during the crystallization stage of cane or beet juice extraction. Its primary commercial purpose centers on fermentation substrates, animal nutrition, and browning agents in processed foods. Cane molasses leads volume globally due to tropical belt processing scale, while blackstrap molasses commands premium positioning in health-conscious food and pharmaceutical channels where mineral density differentiates pricing. Biofuels application is expanding fastest as ethanol producers favor molasses over grain feedstocks in water-stressed regions where crop competition intensifies.
EPA biofuel mandates in the United States, EU Green Deal sustainability criteria, and India's CEA ethanol blending directives collectively shape product specifications and market access pathways for molasses traders. REACH compliance in Europe and FDA feed ingredient standards in North America impose traceability and contaminant thresholds that favor large processors with analytical capabilities. Stakeholders must monitor how carbon border adjustments and evolving renewable fuel standards redirect molasses trade flows between established suppliers and emerging biofuel markets.
Market Dynamics
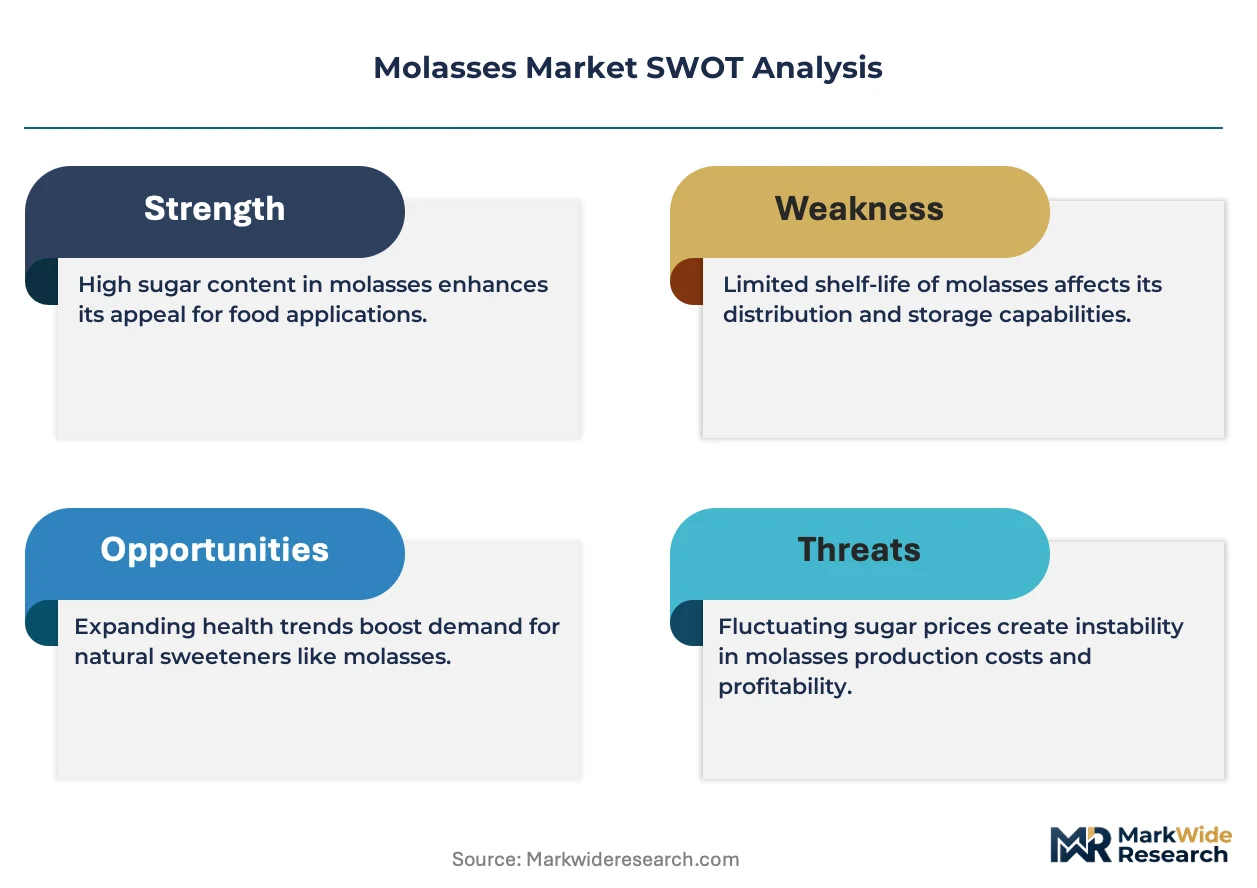
Ethanol blend mandates in water-stressed regions are forcing cane molasses into direct competition with grain feedstocks, compressing traditional ruminant feed allocations and redirecting supply toward biofuel fermentation.
Growth Catalysts
- Biofuel Mandates:India's CEA ethanol blending directives and Southeast Asian blend requirements are pulling cane molasses into fuel-grade fermentation, displacing corn and sorghum in regions where irrigation constraints limit grain expansion.
- Animal Nutrition Science:Brazilian and Indian feed producers are expanding molasses inclusion in ruminant diets as a palatability enhancer and rumen energy source, supported by veterinary research on digestibility coefficients.
- Sustainability Benchmarking:The EU Green Deal and F-Gas Regulation are tightening carbon accounting for agricultural inputs, positioning beet molasses as a lower-emission alternative to synthetic additives in European feed formulations.
Market Restraints
- Input Cost Volatility:Raw sugar price swings and energy costs for juice concentration create margin pressure for independent processors lacking captive cane supply.
- Supply Concentration Risk:Brazilian cane belt dominance concentrates global cane molasses output in São Paulo and Minas Gerais, exposing buyers to weather-driven harvest variability and port logistics bottlenecks.
- Substitution Threat:Corn steep liquor and wheat-based fermentation substrates are gaining traction in North American ethanol plants, eroding molasses share where grain logistics infrastructure is mature.
Strategic Opportunities
- Pharmaceutical-Grade Extraction:Blackstrap molasses mineral density is opening pharmaceutical and nutraceutical channels in Japan and South Korea, where METI and MFDS standards favor natural mineral sources over synthetic supplements.
- Carbon Border Positioning:EU carbon border adjustment mechanisms are creating premium pricing tiers for certified low-carbon molasses, rewarding processors with verified supply chain emissions data.
- Precision Fermentation:Convergence of synthetic biology and molasses substrate engineering is enabling tailored sugar profiles for specialty yeast and enzyme production, commanding technical-grade premiums.
Industry Challenges
- Analytical Capability Gaps:REACH compliance and FDA feed ingredient standards require contaminant testing and traceability systems that strain mid-scale processors without in-house laboratory infrastructure.
- Certification Timeline Compression:Organic and non-GMO certification cycles for export markets are extending lead times, freezing working capital in inventory while auditors verify field-to-tank documentation.
- Legacy Equipment Retrofit Costs:Beet processing plants in France and Belgium face capital demands to upgrade crystallization efficiency and reduce energy intensity per ton of molasses extracted.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molasses Market |
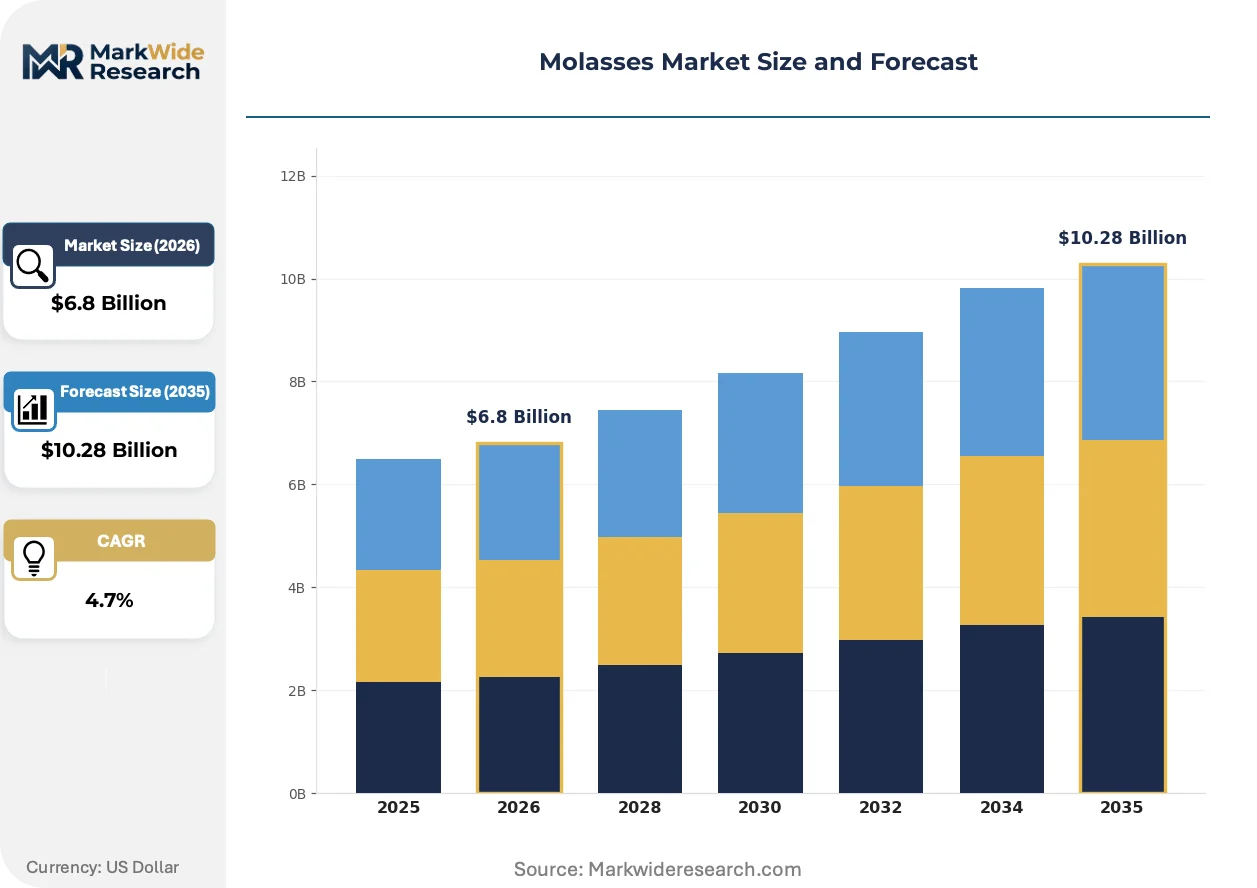
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cane Molasses, Beet Molasses, Blackstrap Molasses, Light Molasses Application: Food & Beverage, Animal Feed, Biofuels, Pharmaceuticals Distribution Channel: Wholesale, Retail, Online, Direct Sales Form: Liquid, Powder, Granulated, Paste |
| Companies Covered | Cosan S.A., Tereos SCA, Archer Daniels Midland Company, B&G Foods Inc., Wilmar International Limited, Louis Dreyfus Company, ED&F Man Holdings Ltd, Crosby Molasses Co Ltd., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molasses Market Strategic Shifts
Fermentation substrate engineering and carbon-accounting traceability systems are reconfiguring how molasses is graded, priced, and allocated between food, feed, and fuel applications.
Membrane filtration technology for molasses desugarization is hybridizing traditional cane processing with biorefinery logic, enabling simultaneous production of fermentation-grade substrates and high-purity sucrose streams. Brazilian processors are retrofitting existing mills with nanofiltration skids at pilot scale. This dual-output configuration is compressing the historical trade-off between sugar crystallization yields and molasses volume recovery.
REACH authorization requirements for chemical intermediates are tightening impurity thresholds for molasses entering European pharmaceutical and cosmetic supply chains, forcing exporters to implement HACCP-based contaminant monitoring. The regulation is elevating analytical costs for blackstrap molasses destined for health-conscious channels. French and Belgian beet processors are responding by certifying trace mineral content through third-party laboratories to secure premium positioning.
Long-term offtake contracting is displacing spot-market purchasing among North American ethanol producers seeking supply security amid cane harvest volatility. Large fuel blenders are negotiating multi-year agreements directly with Brazilian mill groups, bypassing traditional commodity traders. This channel consolidation is most visible in California and Texas, where Low Carbon Fuel Standard compliance costs amplify the value of predictable feedstock sourcing.
Molasses Market Segmentation
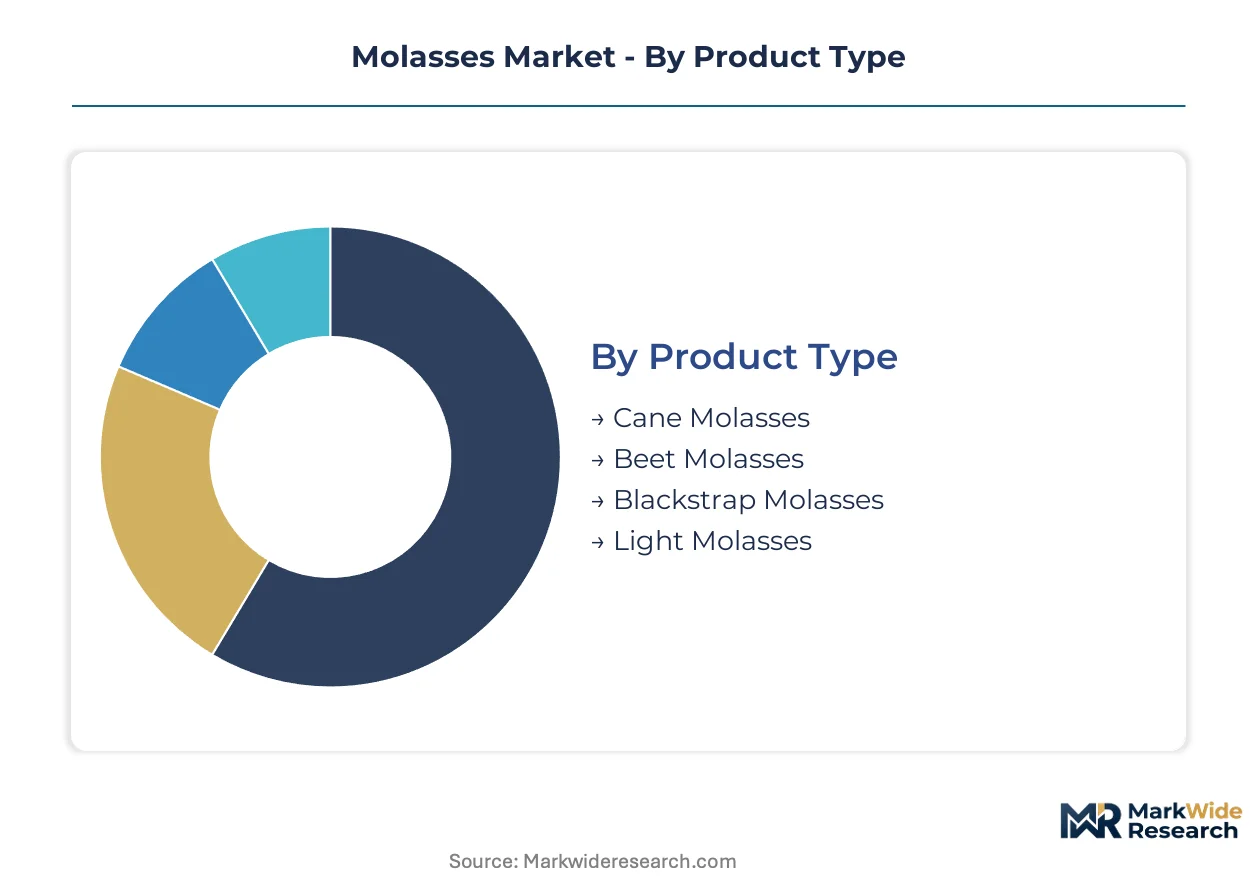
Molasses grades diverge sharply in mineral content and fermentable sugars, directing each variant toward distinct commercial channels. Application requirements and distribution economics further partition the market into specialized supply chains with incompatible specifications.
Product Type:
End-use requirements span fermentation substrates, feed energy density, and pharmaceutical mineral sourcing, creating four distinct product tiers with non-overlapping customer bases.
- Cane Molasses:Recovered from tropical sugarcane processing with 30-40% sucrose and elevated invert sugar content. Brazilian ethanol producers in São Paulo and Minas Gerais are absorbing rising volumes under CEA-influenced blending mandates, displacing ruminant feed allocations.
- Blackstrap Molasses:The final extraction stage retains concentrated iron, calcium, and magnesium ash at 40-50% by weight. Japanese nutraceutical manufacturers under METI standards favor this grade for natural mineral supplements over synthetic alternatives.
- Beet Molasses:European cooperative processors in France and Belgium extract this variant with lower sodium and higher betaine content. EU Green Deal carbon accounting positions beet molasses favorably against synthetic feed additives.
- Light Molasses:Early-stage syrup with higher residual sucrose and milder flavor profile. North American food manufacturers deploy this grade as browning agents and sweetener extenders in processed baked goods.
Cane molasses commands the dominant share by volume, while blackstrap molasses is climbing the fastest on pharmaceutical-grade pricing premiums.
Application:
Customer procurement patterns separate bulk fermentation buyers from specification-sensitive food and pharmaceutical channels.
- Biofuels:Fuel-grade fermentation in India and Southeast Asia favors molasses over grain where irrigation constraints limit corn expansion. Long-term offtake contracting is displacing spot purchasing among California and Texas blenders seeking Low Carbon Fuel Standard compliance.
- Animal Feed:Brazilian and Indian feed compounders are expanding inclusion rates as palatability enhancers and rumen energy sources, supported by veterinary digestibility research on high-moisture rations.
- Food & Beverage:Processed food manufacturers value molasses for moisture retention, browning reactions, and flavor masking in reduced-sugar formulations. REACH compliance costs are elevating impurity testing burdens for European-bound shipments.
- Pharmaceuticals:Blackstrap mineral density meets MFDS standards in South Korea and METI requirements in Japan for natural-source supplements. Third-party laboratory certification of trace mineral content secures premium positioning.
The largest demand concentration sits with biofuels, though animal feed is expanding most quickly on Brazilian and Indian ruminant nutrition science.
Distribution Channel:
Channel selection tracks shipment scale, certification requirements, and customer analytical capabilities.
- Wholesale:Commodity-grade cane molasses moves through established sugar traders with port logistics and harvest timing expertise. Brazilian mill groups are increasingly bypassing these intermediaries for direct ethanol producer contracts.
- Direct Sales:Pharmaceutical-grade blackstrap and certified organic beet molasses require documented field-to-tank traceability. French and Belgian processors negotiate directly with Japanese and South Korean nutraceutical manufacturers.
- Retail:Consumer-packaged blackstrap for health-conscious households distributes through specialty grocers and natural product stores. SKU proliferation strains inventory turns for mid-scale processors.
- Online:E-commerce penetration remains limited to specialty health products and small-batch food ingredients. Cold-chain requirements constrain liquid molasses shipping economics.
Wholesale channels handle the greatest volume, yet direct sales are gaining share fastest on pharmaceutical and certified organic demand.
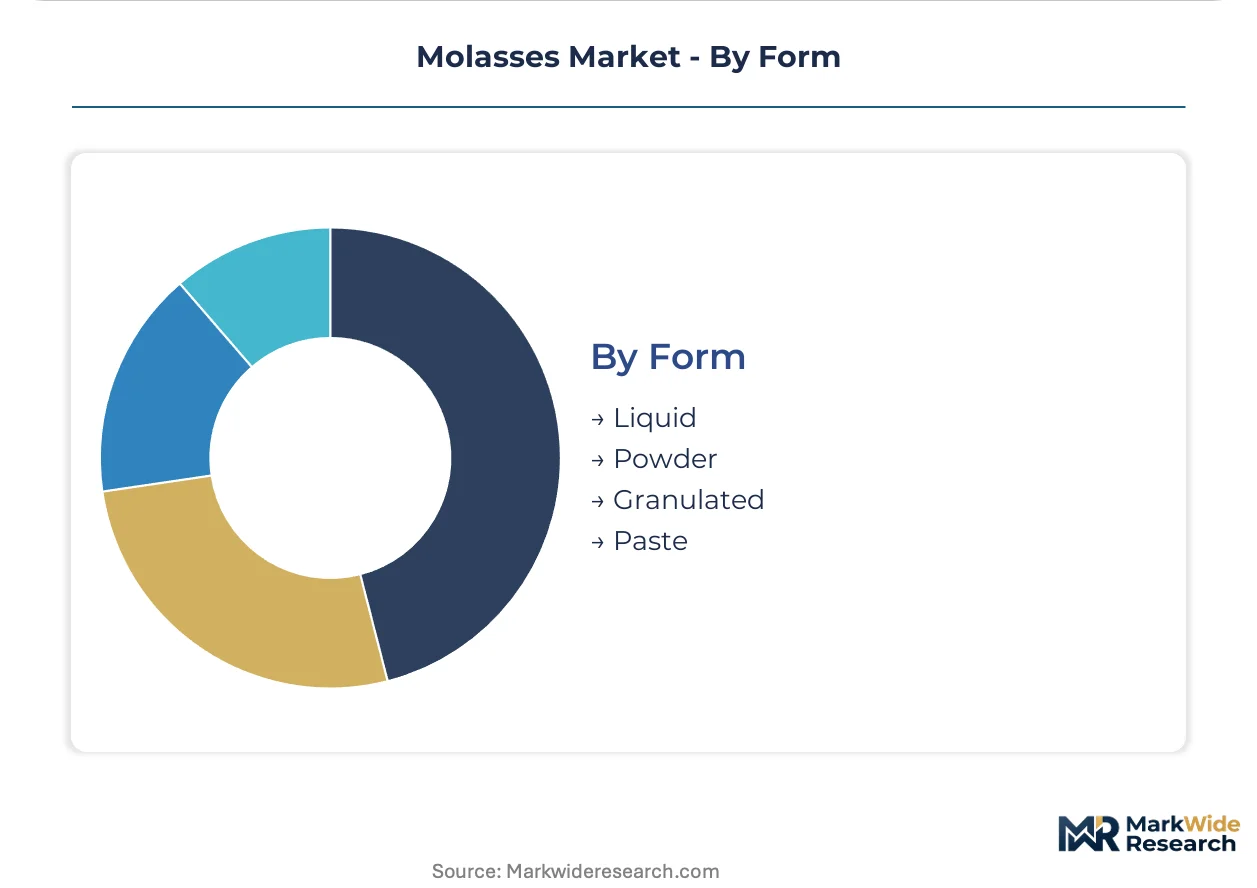
Form:
Physical state determines storage economics, handling equipment, and end-use compatibility.
- Liquid:The standard extraction state requiring heated storage tanks and agitated transport. Brazilian ethanol plants and Indian feed mills maintain captive heated tankage for bulk receipt.
- Powder:Spray-dried molasses solids enable inclusion in dry feed premixes and powdered beverage formulations. Energy costs for dehydration compress margins for independent processors.
- Granulated:Intermediate moisture content reduces caking while preserving solubility. European feed compounders favor this form for automated batching systems.
- Paste:High-viscosity concentrated product for industrial food manufacturing. Specialized pumping and heating equipment limits customer flexibility.
Liquid form retains the dominant position, with powder experiencing the steepest expansion trajectory on dry premix and beverage application growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA ethanol blending directives in India are redirecting cane molasses from feed rations toward fuel-grade fermentation, establishing regulatory gravity in South Asia. Brazil's cane belt expansion and EU Green Deal carbon accounting are reshaping trade flows across three continents.
Brazil
Animal nutrition science and biofuel fermentation are competing for cane molasses output in São Paulo and Minas Gerais. ANVISA feed ingredient standards and CEA-influenced export protocols govern cross-border shipments. São Paulo's vertically integrated sugar-energy complexes are absorbing rising volumes under long-term ethanol offtake contracts.
India
CEA ethanol blending mandates are pulling cane molasses into fuel-grade channels, displacing traditional ruminant feed allocations. FSSAI traceability requirements and DGFT export licensing impose documentation burdens on processors. Maharashtra and Uttar Pradesh crushing capacity is expanding to meet distillery demand.
United States
EPA biofuel mandates and California Low Carbon Fuel Standard compliance costs are elevating molasses procurement priority among ethanol blenders. FDA feed ingredient standards require contaminant testing for imported blackstrap grades. Texas and California fuel terminals are negotiating multi-year supply agreements directly with Brazilian mill groups.
France
EU Green Deal carbon accounting positions beet molasses favorably against synthetic feed additives. REACH authorization requirements tighten impurity thresholds for pharmaceutical-bound shipments. Cooperative processing networks in northern France and Belgium are certifying trace mineral content through third-party laboratories.
Japan
METI standards favor blackstrap molasses mineral density over synthetic supplements in nutraceutical formulations. MFDS-aligned import protocols govern South Korean transshipments. Osaka and Tokyo pharmaceutical manufacturers are contracting directly with French and Belgian processors for certified organic grades.
Molasses Market Competitive Environment
Capability concentration sits with beet processors possessing REACH-compliant laboratory infrastructure; scale advantage sits with cane belt operators commanding port logistics and harvest timing expertise. The market structures around three tiers: vertically integrated sugar-energy platforms, cooperative processing networks, and commodity traders with analytical capabilities. Dominant competitive moves include backward integration into captive cane supply and direct offtake contracting that bypasses traditional trading intermediaries.
Among South American operators, Cosan S.A. exemplifies the vertically integrated platform archetype. Tereos SCA anchors European cooperative processing through S.C.A. structure. Archer Daniels Midland Company occupies the North American distribution tier with extensive grain and sweetener logistics infrastructure.
| Leading Market Players |
|---|
| Cosan S.A. |
| Tereos SCA |
| Archer Daniels Midland Company |
| B&G Foods Inc. |
| Wilmar International Limited |
| Louis Dreyfus Company |
| ED&F Man Holdings Ltd |
| Crosby Molasses Co Ltd. |
| Cargill, Incorporated |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European beet processing facilities is tightening supply discipline and elevating price premiums for REACH-compliant grades, while Brazilian cane belt overcapacity compresses export margins and forces mill groups toward direct offtake contracting to defend position.
Pricing Analysis
São Paulo-to-Rotterdam freight spreads now exceed processing cost differentials, compressing arbitrage margins for commodity traders. Pricing stratifies across pharmaceutical-grade blackstrap, certified organic beet, and bulk fermentation cane tiers. Cost compression in standard cane molasses is intensifying because Indian ethanol blenders are absorbing regional supply at contract premiums. Animal feed compounders show highest price sensitivity; pharmaceutical manufacturers in Japan and South Korea accept technical-grade premiums.
Supply Chain Analysis
EU F-Gas Regulation and REACH authorization requirements restrict pharmaceutical-grade molasses flows into European channels without third-party contaminant certification. Supply concentrates in Brazil, India, and France, with raw sugar juice and energy for concentration as critical inputs. Single-source vulnerability runs through São Paulo port logistics bottlenecks during harvest peaks. Distribution runs through vertically integrated sugar-energy platforms and cooperative processing networks with captive laboratory infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as biofuel blend mandates in water-stressed regions restore demand absorption capacity after years of feed-ration dominance.
For Market Incumbents: Entrench analytical capability advantages by certifying trace mineral content through third-party laboratories for pharmaceutical channels. Expand backward integration into captive cane supply in Minas Gerais to offset harvest volatility. Lock in multi-year offtake agreements with California and Texas fuel terminals before carbon border adjustments reshape trade flows.
For New Entrants and Emerging Players: Precision fermentation substrate engineering for specialty yeast production represents the most penetrable entry point, commanding technical-grade premiums unavailable to commodity processors. Japanese nutraceutical channels under METI standards favor certified organic blackstrap with documented field-to-tank traceability. Direct sales relationships with Osaka pharmaceutical manufacturers bypass entrenched trading intermediaries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane filtration retrofit programs as Brazilian processors hybridize traditional mills with biorefinery logic. Five-to-ten year viability favors processors with verified supply chain emissions data for EU carbon border positioning. Watch for CEA ethanol blending directive revisions as the inflection signal for demand reallocation between feed and fuel channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Enables simultaneous sucrose and fermentation-grade substrate recovery, compressing historical yield trade-offs. |
| Third-Party Laboratory Certification | Secures REACH-compliant access to European pharmaceutical channels with elevated impurity thresholds. |
| Direct Offtake Contracting | Bypasses commodity traders for California Low Carbon Fuel Standard compliance among ethanol blenders. |
| Carbon Border Adjustment Positioning | Rewards processors with verified emissions data under EU Green Deal sustainability criteria. |
| Precision Fermentation Substrate Engineering | Tailors sugar profiles for specialty yeast production under METI and MFDS technical standards. |
Study Parameters
Desk research of trade customs records, cooperative processor financial disclosures, and biofuel regulatory filings preceded structured interviews with sugar mill operations directors, ethanol plant procurement managers, veterinary feed formulation scientists, and European pharmaceutical raw material buyers. Primary fieldwork with Brazilian mill groups and French beet cooperatives combined with secondary validation against ANVISA, FSSAI, and DGFT documentation. Bottom-up volume estimates from crushing capacity utilization triangulated against top-down demand absorption models.
Assumptions held fixed include current EPA biofuel mandate levels, EU Green Deal carbon accounting frameworks, and CEA ethanol blending directive trajectories; sensitivity analysis varied cane harvest yields and membrane filtration adoption rates. Segmentation modeling spanned product grade tiers, application channels, and regional regulatory clusters. CAGRs derived from logarithmic trend fitting across the projection horizon, with inputs including distillery capacity expansion in Maharashtra and Uttar Pradesh, and veterinary digestibility research publication rates.
Macroeconomic conditions sit as an overlay; deviation in raw sugar price volatility, energy costs for juice concentration, or freight rate spikes would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and harvest timing patterns. Material shifts in EU carbon border adjustment implementation timelines or F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Dextrose Syrup Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Icing Sugar Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Tagatose Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Xylitol Injection Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Granulated Sugar Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Sour Sugar Market