
 Polyphenol Sweetener Market | 2026-2036
Polyphenol Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenol Sweetener Market Analytics
EU F-Gas Regulation is pivoting refrigeration-dependent extraction facilities toward enzymatic and ambient-temperature processing, raising capital requirements for new entrants. Cargill leverages its integrated agricultural supply chain to secure raw stevia leaf volumes across multiple growing regions. DSM-Firmenich AG anchors its position through biotechnology platforms that enhance polyphenol yield from fermentation-derived precursors. Givaudan SA competes on flavor modulation expertise, masking bitter off-notes that limit high-concentration polyphenol applications.
Polyphenol sweeteners comprise glycoside compounds—primarily steviol glycosides, mogrosides, and related phenolic structures—extracted from plant matrices or produced via bioconversion, with sweetness intensities ranging from 150 to 400 times that of sucrose at functional concentrations. These compounds serve industrial formulators seeking to replicate sucrose's temporal sweetness profile while eliminating caloric load and glycemic response. The stevia category dominates current volume flows due to established GRAS status and broad beverage penetration, though allulose claims the fastest structural expansion as FDA exclusion from added sugars labeling drives bakery and confectionery uptake. Application segmentation shows beverages commanding the largest absolute margin pool, while dairy products present concentrated growth as cultured and flavored milk processors reformulate to meet front-of-package warning requirements.
FDA GRAS notification pathways, EFSA novel food authorizations, and USDA organic certification standards collectively determine which polyphenol extracts achieve commercial scale in regulated food systems. EFSA's evolving stance on steviol glycoside purity thresholds and FDA scrutiny of allulose manufacturing residuals shape reformulation timelines and supplier qualification protocols. Stakeholders must monitor pending determinations on monk fruit mogroside specifications and prepare supply chain redundancies before regulatory windows narrow for preferred extraction methods.
Market Dynamics
Enzymatic bioconversion platforms are compressing extraction costs for high-purity steviol glycosides and mogrosides, enabling volume scale previously blocked by solvent-dependent processing economics. This technological inflection is redrawing supplier qualification thresholds across beverage and dairy formulators.
Growth Catalysts
- Sugar-Reduction Mandates:Front-of-package warning requirements in processed foods are forcing dairy and bakery manufacturers toward polyphenol reformulation. Germany's processed food labeling rules exemplify this regulatory pull.
- GRAS Notification Pathways:FDA's streamlined novel food ingredient review is accelerating stevia extract commercialization timelines. Beverage manufacturers leverage this to compress product development cycles.
- Clean-Label Procurement:Retailer private-label programs in the United States are specifying non-nutritive sweeteners with organic certification. This procurement shift concentrates volume with certified extract suppliers.
Market Restraints
- Raw Material Concentration:Stevia leaf supply clusters in Paraguay and China, exposing processors to climate-driven yield volatility and geopolitical friction.
- Purity Threshold Friction:EFSA's evolving steviol glycoside specifications create reformulation risk for legacy extract inventories that marginally miss emerging standards.
- Allulose Substitution Threat:FDA's added-sugar labeling exclusion for allulose is diverting bakery and confectionery R&D budgets away from polyphenol pathways.
Strategic Opportunities
- Fermentation-Derived Expansion:Biotechnology platforms producing mogroside precursors via microbial fermentation unlock supply independence from monk fruit cultivation cycles. DSM-Firmenich AG anchors this capability.
- Ambient-Temperature Processing:EU F-Gas Regulation is pivoting extraction facilities toward enzymatic methods, creating first-mover advantage for capitalized equipment suppliers.
- Flavor Modulation Integration:Bitter-masking expertise from fragrance houses enables higher-concentration polyphenol applications in functional beverages previously limited by sensory rejection.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Fermentation scale-up expertise for glycoside production concentrates with a narrow pool of specialists, inflating compensation and extending hiring timelines.
- Organic Certification Complexity:USDA organic standards for extraction solvents and enzymatic carriers create multi-year compliance pathways that delay premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenol Sweetener Market |
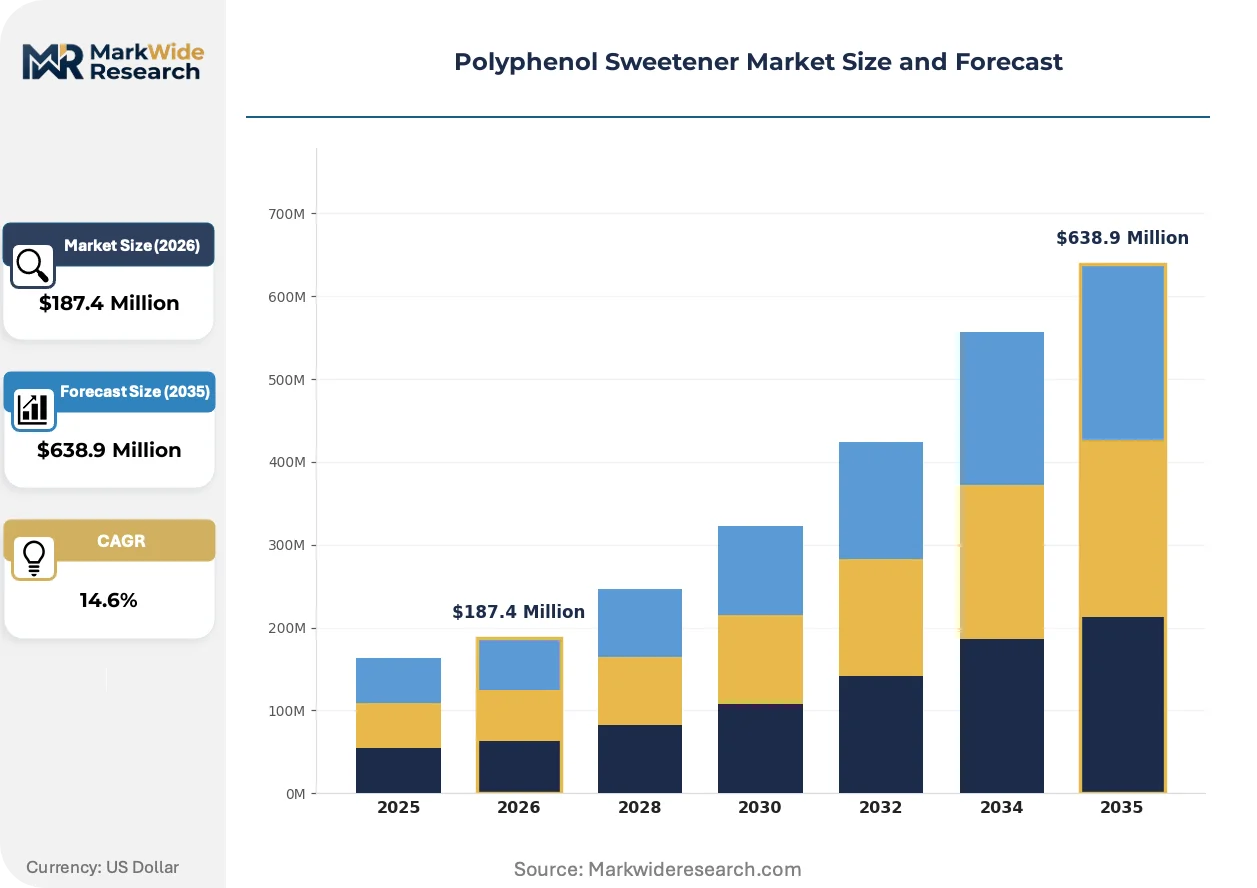
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Monk Fruit, Erythritol, Allulose Application: Beverages, Bakery Products, Confectionery, Dairy Products End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Nutraceutical Users Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Aurea, DolCas Biotech, Iprona, Optipure, Botanic Healthcare, Givaudan SA, International Flavors & Fragrances, DSM-Firmenich AG, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenol Sweetener Market Evolving Landscape
Bioconversion technologies are displacing traditional solvent extraction as the dominant production paradigm, compressing capital intensity while expanding geographic sourcing flexibility. This shift is enabling new entrant participation and fragmenting incumbent supply control.
Enzymatic glycoside modification is consolidating production economics for high-purity rebaudioside M and mogroside V. Dairy processors in Germany and the United States are adopting these ingredients at accelerated qualification paces. The technology is consolidating supplier tiers by compressing margin capture toward integrated biotech platforms and away from commodity extractors.
EFSA's F-Gas Regulation is forcing refrigeration-dependent extraction facilities toward ambient-temperature enzymatic processing or carbon-intensive compliance investments. Industrial consequence includes raised capital barriers for new market entrants and accelerated obsolescence of legacy solvent infrastructure. Spanish and Italian extraction hubs are responding with joint venture structures to share biorefinery capex.
Buyer concentration among beverage multinationals is shortening supplier qualification cycles and demanding dedicated fermentation capacity commitments. Direct procurement contracts are displacing spot-market extract purchases across North American and European formulators. This pattern is most visible in stevia supply chains serving Coca-Cola and PepsiCo reformulation programs.
Polyphenol Sweetener Market Segmentation
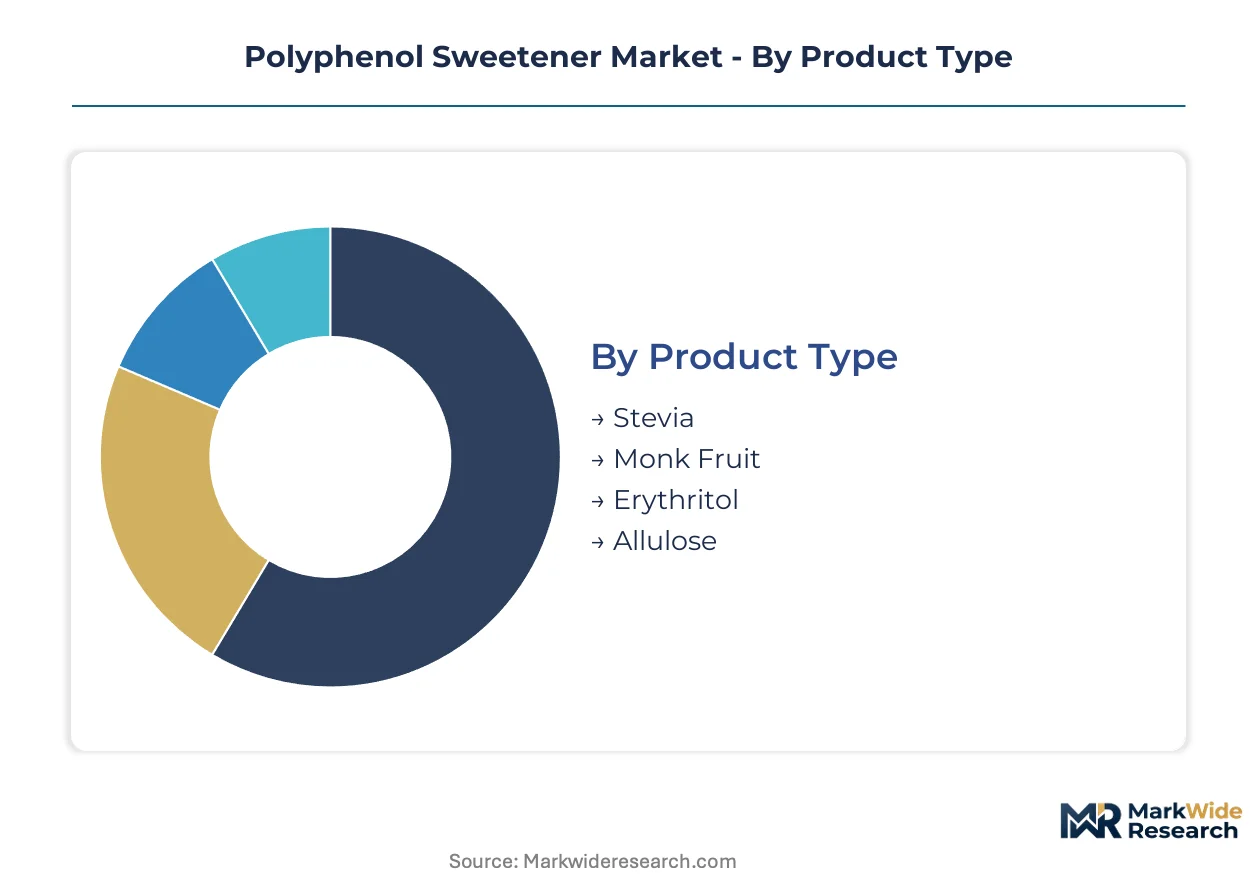
Polyphenol sweetener procurement patterns diverge sharply across buyer categories, with regulatory pressure and formulation complexity driving segment-specific sourcing strategies. Manufacturers prioritize glycoside purity thresholds and supply security over unit economics, reshaping how suppliers structure their commercial offerings.
Product Type:
Buyers differentiate primarily by regulatory clearance status and sensory performance requirements, with GRAS notification pathways determining commercial viability in regulated food systems.
- Stevia:Steviol glycosides extracted from Stevia rebaudiana leaves deliver sweetness intensities 150-300 times sucrose. Beverage manufacturers in the United States dominate procurement volumes, leveraging established FDA GRAS status to accelerate reformulation timelines for sugar-reduction mandates.
- Monk Fruit:Mogrosides from Siraitia grosvenorii offer a cleaner sweetness profile with reduced bitter aftertaste compared to stevia. German dairy processors are expanding qualification programs for monk fruit extracts as EFSA novel food specifications stabilize, though supply remains constrained by cultivation cycles in southern China.
- Erythritol:A sugar alcohol produced via fermentation of glucose, erythritol provides bulk and mouthfeel in bakery applications where high-intensity sweeteners alone fail.
- Allulose:A rare sugar with 70% sucrose sweetness but negligible caloric impact, allulose benefits from FDA exclusion from added sugars labeling, diverting R&D investment from polyphenol pathways in confectionery segments.
Stevia leads volumes today; allulose is gaining share fastest.
Application:
Margin capture varies dramatically by end-use, with beverage formulators commanding dedicated fermentation capacity and dairy buyers accepting premium pricing for certified organic extracts.
- Beverages:Carbonated soft drinks, flavored waters, and ready-to-drink teas represent the largest absolute volume channel. Coca-Cola and PepsiCo reformulation programs in the United States are compressing supplier qualification cycles and demanding multi-year supply commitments from stevia extractors.
- Dairy Products:Cultured yogurts and flavored milk processors face front-of-package warning requirements in Germany and are accelerating polyphenol adoption at premium price points. EFSA's evolving steviol glycoside purity thresholds create reformulation risk for legacy extract inventories.
- Bakery Products:Cookies, cakes, and bread formulations require bulking agents alongside high-intensity sweeteners, limiting pure polyphenol penetration.
- Confectionery:Hard candies and chocolate applications prioritize temporal sweetness profiles matching sucrose, where allulose substitution threatens polyphenol growth.
Beverages command the deepest supplier relationships; dairy shows the steepest expansion trajectory.
End User:
Procurement sophistication separates multinational formulators with dedicated technical teams from smaller nutraceutical buyers reliant on distributor technical support.
- Food Manufacturers:Processed food conglomerates with internal R&D capabilities qualify suppliers directly, negotiating long-term contracts for high-purity rebaudioside M and mogroside V.
- Beverage Companies:Soft drink and juice processors concentrate buying power, demanding flavor modulation expertise to mask bitter off-notes at high polyphenol concentrations.
- Pharmaceutical Firms:Excipient-grade sweeteners for pediatric and geriatric formulations require USP certification, creating a premium tier with distinct supplier qualifications.
- Nutraceutical Users:Dietary supplement manufacturers source smaller volumes through distributors, prioritizing organic certification over unit cost optimization.
Food manufacturers anchor procurement volumes; nutraceutical users expand most quickly.
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with bulk industrial buyers bypassing retail infrastructure entirely.
- Online Retail:E-commerce platforms serve small-scale nutraceutical and artisan food producers with minimum order quantities below distributor thresholds.
- Supermarkets:Mass retail channels move consumer-packaged sweetener blends, not industrial-grade extracts, with private-label programs specifying organic certification.
- Health Food Stores:Specialty retailers cater to clean-label consumers willing to pay premiums for certified organic stevia and monk fruit products.
- Specialty Stores:Professional ingredient distributors serve mid-scale food manufacturers with technical support and formulation guidance unavailable through commodity channels.
Supermarkets dominate consumer-facing volumes; specialty stores capture the highest industrial margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocess engineering talent concentrates in Germany's industrial biotechnology corridor and California's fermentation clusters, anchoring extraction technology advancement. Supply chain managers in these hubs coordinate procurement from cultivation regions while navigating divergent regulatory frameworks.
United States
Beverage manufacturers in Atlanta and Purchase drive stevia procurement volumes through direct supplier contracts. FDA GRAS notification pathways compress qualification timelines for high-purity rebaudioside M. California's Sacramento Valley hosts extraction facilities pivoting toward enzymatic processing to meet sustainability procurement standards from multinational formulators.
Germany
Dairy processors in Bavaria accelerate monk fruit extract adoption ahead of front-of-package warning mandates. EFSA novel food specifications for mogrosides stabilize, reducing reformulation risk for cultured yogurt manufacturers. North Rhine-Westphalia's industrial biotech cluster supplies fermentation-derived precursors to sweetener compounders across the Benelux region.
China
Monk fruit cultivation concentrates in Guangxi Zhuang Autonomous Region, supplying global mogroside demand. The national food safety regulator maintains purity thresholds for plant extracts entering processed food channels. Yangtze River Delta biorefineries integrate enzymatic conversion capacity to serve European and North American importer specifications.
Paraguay
Stevia leaf production anchors rural agricultural employment in the Alto Paraná and Caaguazú departments. Climate-driven yield volatility exposes processors to supply interruption risk during El Niño cycles. Asunción-based exporters coordinate with multinational agrifood traders to secure forward contracts for high-rebaudioside leaf varieties.
India
Nutraceutical formulators in Mumbai and Hyderabad source certified organic stevia extracts for dietary supplement applications. FSSAI standards for non-nutritive sweeteners in processed foods tighten labeling requirements. Karnataka's agricultural biotechnology institutes develop domestic stevia cultivars with enhanced glycoside content for regional processing scale-up.
Polyphenol Sweetener Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three identifiable tiers. Integrated agrifood traders leverage backward control over cultivation regions to secure raw material flows. Biotechnology platforms anchor the premium tier through fermentation-derived production economics. Fragrance and flavor houses occupy a specialized position masking sensory limitations that constrain high-concentration applications. Dominant competitive moves include capacity commitments to beverage multinational direct procurement programs and joint venture structures to share biorefinery capital requirements.
Among Swiss-anchored diversified specialists, DSM-Firmenich AG and Givaudan SA exemplify contrasting archetypes. DSM-Firmenich AG represents the biotechnology-integrated platform model, while Givaudan SA occupies the flavor modulation expertise position. Cargill, as a privately held U.S. agrifood conglomerate, anchors the agricultural supply chain control archetype through its integrated leaf procurement networks. These three entities collectively illustrate the strategic segmentation between upstream agricultural control, bioprocess platform scale, and downstream sensory formulation capability.
| Leading Market Players |
|---|
| Aurea |
| DolCas Biotech |
| Iprona |
| Optipure |
| Botanic Healthcare |
| Givaudan SA |
| International Flavors & Fragrances |
| DSM-Firmenich AG |
| Cargill |
| Others |
Value Network & Pricing Analysis
Premium-commodity bifurcation between fermentation-derived mogrosides and solvent-extracted steviol glycosides manifests in divergent margin structures and procurement security premiums across North American and European formulators. Certification ladders for USDA organic and EFSA novel food status create pricing rungs that suppliers exploit to capture value from risk-averse dairy and beverage manufacturers.
Pricing Analysis
Contract-based long-term offtake dominates procurement between beverage multinationals and integrated biotech platforms, while spot-market transactions persist for commodity-grade stevia extracts. Price differentiation rests on glycoside purity thresholds and organic certification status, with rebaudioside M commanding substantial premiums over legacy stevioside grades. Cost compression in standard-tier extracts is intensifying because enzymatic conversion capacity is expanding faster than differentiated fermentation output. Nutraceutical distributors show highest price sensitivity, while Coca-Cola and PepsiCo procurement teams prioritize supply security over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with monk fruit cultivation concentrated in China's Guangxi Zhuang Autonomous Region, where climate-driven yield volatility exposes global mogroside supply to interruption. Raw material dependencies draw from stevia leaf clusters in Paraguay and China, fermentation feedstocks including glucose and yeast strains, and enzymatic catalysts for glycoside modification. Tariff exposure runs through U.S.-China trade friction affecting extract imports and European carbon border adjustments on solvent-intensive processing. Distribution runs through direct procurement contracts with beverage and dairy formulators, displacing traditional commodity broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in polyphenol sweeteners rests on enzymatic conversion economics compressing production costs while premium-tier fermentation-derived ingredients capture pricing power from supply-constrained applications.
For Market Incumbents: Cement backward integration into stevia leaf procurement across multiple growing regions to buffer climate-driven yield volatility in Paraguay. Lock dedicated fermentation capacity commitments from Coca-Cola and PepsiCo reformulation programs before biotechnology platforms achieve scale. Allulose substitution in bakery and confectionery segments threatens volume retention in standard-tier extracts. For New Entrants and Emerging Players: Enter via certified organic monk fruit extraction targeting German dairy processors ahead of front-of-package warning mandate deadlines. White-space concentrates in flavor-modulation services masking bitter off-notes for functional beverage applications, and in ambient-temperature enzymatic processing equipment serving EU F-Gas Regulation compliance needs. A technical-service-heavy go-to-market model bypasses incumbent commodity broker relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up expertise concentrates with a narrow specialist pool, inflating compensation and extending hiring timelines for bioprocess engineering talent. Long-term viability favors biotechnology platforms with demonstrated mogroside precursor production and integrated flavor modulation capabilities. The signal to watch is FDA determination timelines on monk fruit mogroside specifications, which will reshape supplier qualification protocols and stranded-asset risk for legacy extraction infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Cargill's multi-region stevia leaf networks reduce climate-driven supply interruption exposure for beverage formulators. |
| Fermentation Capacity Expansion | DSM-Firmenich AG's biotechnology platforms unlock supply independence from monk fruit cultivation cycles in southern China. |
| Flavor Modulation Service Development | Givaudan SA's bitter-masking expertise enables higher-concentration polyphenol applications in functional beverages. |
| Joint Venture Biorefinery Structures | Spanish and Italian extraction hubs share enzymatic processing capex to meet EU F-Gas Regulation compliance requirements. |
| Organic Certification Investment | USDA organic standards for extraction solvents create multi-year compliance pathways that delay premium positioning for uncertified suppliers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with beverage formulation directors, dairy procurement leads, extraction facility engineers, and biotechnology R&D heads with secondary validation. Secondary sources include FDA GRAS notification filings, EFSA novel food authorization databases, USDA organic certification records, and trade flow data from customs authorities. Bottom-up volume estimates from cultivation regions and top-down demand aggregation from end-use sectors were triangulated to reconcile supply-demand balances.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects to isolate real demand expansion from premium-tier shift. Segmentation dimensions modeled include glycoside type, application category, end-user sophistication tier, and distribution channel structure. CAGRs were derived from fitted growth curves anchored to regulatory milestone dates and procurement contract tenors. Forecast inputs incorporate enzymatic conversion yield improvements and EFSA purity threshold evolution scenarios.
Inputs from regulatory filing databases and procurement contract registries were available through the study window; gaps in real-time cultivation yield data from Paraguay and China introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions about technology adoption curves and regulatory determination timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sugar Polyols Market
Sweeteners
Xylitol Injection Market
Sweeteners
Allulose Market
Sweeteners
South Korea Allulose Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Liquid Sugar Market
Sweeteners
D-Mannose Market
Sweeteners
Tagatose Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Dextrose Syrup Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
North America Sugar Substitutes Market