
 Sucralose Market | 2026-2036
Sucralose Market Size, Share, and Industry Trends Forecast 2026-2036
Sucralose Market Intelligence
The rise of asset-light manufacturing models, where companies outsource capital-intensive production steps, is fragmenting the competitive landscape for sucralose. Tate & Lyle PLC leverages its extensive R&D capabilities and brand recognition to command a premium. In contrast, JK Sucralose Inc. specializes in high-purity grades for pharmaceutical applications. Niutang Chemical Ltd. competes on production scale and cost leadership, primarily serving high-volume food and beverage manufacturers.
Sucralose is a zero-calorie artificial sweetener derived from sucrose through a multi-step chemical process that selectively replaces three hydroxyl groups with chlorine atoms. This modification makes it approximately 600 times sweeter than sugar and exceptionally stable under heat, ensuring its suitability for cooking and baking. Powder form dominates the market due to its versatility and ease of integration into dry mixes and industrial food processing. The beverage segment represents the largest application, driven by consumer preference for sugar-free sodas, juices, and flavored waters.
Market access is contingent on approvals from national food safety authorities, including the US FDA and the European Food Safety Authority (EFSA). In China, compliance with GB standards and NMPA regulations is mandatory for both domestic production and imports, governing purity levels and acceptable daily intake. Future competitive dynamics will hinge on producers' ability to navigate evolving consumer perceptions of artificial sweeteners and secure supply chains for key chemical precursors.
Market Dynamics
The central force shaping the sucralose market is the implementation of sugar taxes by national governments. These fiscal policies, designed to curb sugar consumption and address public health issues, directly incentivize food and beverage manufacturers to reformulate products using low-calorie alternatives.
Growth Catalysts
- Government Sugar Levies:Policies such as the United Kingdom's Soft Drinks Industry Levy and Mexico's tax on sugary drinks are compelling major beverage companies to accelerate their transition to non-caloric sweeteners like sucralose to maintain price competitiveness.
- Beverage Industry Reformulation:The global beverage sector remains the largest consumer, driven by the expansion of sugar-free sodas, flavored waters, and ready-to-drink teas where sucralose provides high-intensity sweetness without impacting calorie counts or requiring major process changes.
- Manufacturing Scale in China:China's vast and cost-efficient food processing and chemical manufacturing infrastructure provides a robust supply base for sucralose, supporting its use in high-volume applications and enabling exports to global markets.
Market Restraints
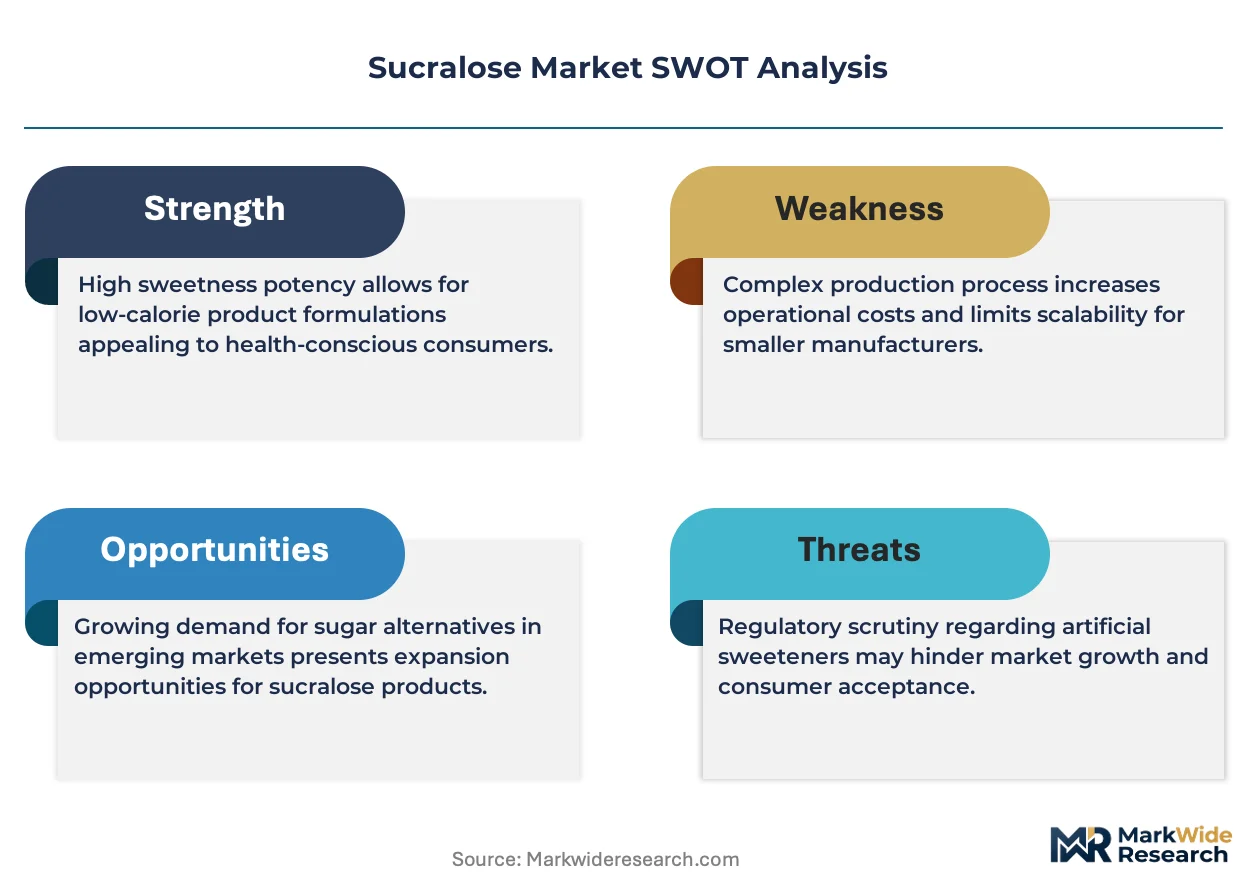
- Competition from Natural Sweeteners:The rising consumer preference for "clean label" and natural ingredients poses a significant substitution threat from sweeteners like stevia and monk fruit, which are perceived as healthier alternatives to artificial sweeteners.
- Precursor Chemical Price Volatility:The sucralose synthesis process depends on specific chlorinated sucrose precursors and other chemical reagents. Fluctuations in the price and availability of these inputs can directly impact production costs and final product pricing.
- Negative Consumer Perceptions:Persistent consumer skepticism and media reports questioning the long-term health effects of artificial sweeteners create market headwinds, influencing purchasing decisions and prompting some brands to seek non-artificial options.
Strategic Opportunities
- Expansion into Nutraceuticals:The exceptional heat and pH stability of sucralose creates opportunities in functional foods, sports nutrition powders, and vitamin supplements, where it can sweeten products without degrading during processing or shelf life.
- Penetration in Southeast Asian Markets:Growing economies in Southeast Asia with rising disposable incomes and increasing health awareness present an untapped market for low-calorie food and beverage products, offering new growth avenues for sucralose suppliers.
- Development of Sweetener Blends:Formulating sucralose in combination with other sweeteners, such as erythritol or allulose, allows for the creation of customized sweetness profiles that can mask off-notes and more closely mimic the taste and texture of sugar.
Industry Challenges
- Navigating Global Regulatory Patchworks:Manufacturers face the operational challenge of adhering to a complex and divergent set of international food safety standards, including purity specifications from the US FDA, EFSA in Europe, and China's NMPA.
- Securing Chemical Supply Chains:Ensuring a stable and reliable supply of critical chemical intermediates for sucralose production is a constant logistical challenge, vulnerable to geopolitical tensions, trade policy shifts, and plant-specific disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sucralose Market |
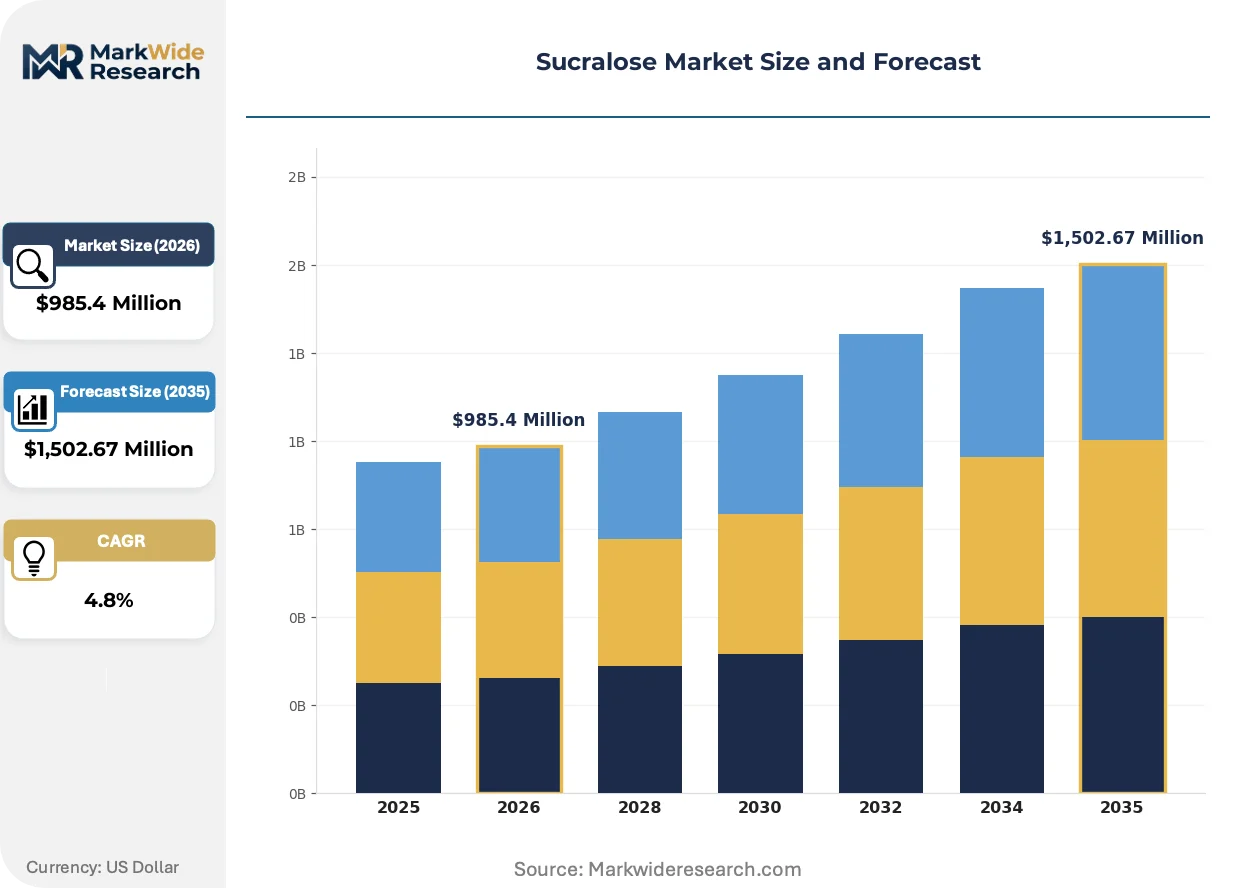
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,502.67 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid Concentrate, Tablets Application: Beverages, Baked Goods, Dairy Alternatives, Pharmaceuticals, Personal Care End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Cosmetic Producers, Nutraceutical Firms Packaging Type: Plastic Bottles, Sachets, Glass Jars, Cardboard Containers |
| Companies Covered | Newtrend Group, Niutang Chemical Ltd., Tate & Lyle PLC, Changzhou Hanbang Food Co Ltd., Techno Food Ingredients Co Ltd, JK Sucralose Inc., BioPlus Life Sciences, Xiamen Boao Technology Co Ltd., Nantong Changhai Food Additive Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sucralose Market Strategic Shifts & Innovations
The market is advancing through a dual focus on process optimization and ingredient synergy. Manufacturers are investing in technologies to enhance purity and efficiency, while food formulators are exploring sophisticated sweetener blends to meet evolving consumer taste preferences.
Advanced process control systems are being integrated into sucralose manufacturing facilities to monitor the multi-step chlorination process. Pharmaceutical and high-purity grade producers are leading this adoption to meet stringent quality requirements. This automation is digitizing the factory floor, allowing for real-time adjustments that improve yield, reduce solvent use, and ensure consistent product quality batch after batch.
Regulatory bodies are intensifying their review of food additives, exemplified by the European Food Safety Authority's (EFSA) ongoing re-evaluation of all approved sweeteners. This process mandates that producers submit updated toxicological and exposure data, increasing the compliance burden and R&D expenditure. The beverage and confectionery segments are most directly impacted, as they must ensure their supply chains and product formulations can withstand heightened regulatory scrutiny across the EU.
A notable behavioral shift is the move by food formulators toward purchasing customized sweetener systems instead of single ingredients. This disrupts the commodity-style sale of sucralose, creating an advantage for suppliers that can provide technical support and co-develop blends with other sweeteners like stevia or monk fruit. This trend is particularly prominent in the North American sports nutrition and functional foods sectors, where optimizing taste is paramount for brand differentiation.
Sucralose Market Segmentation
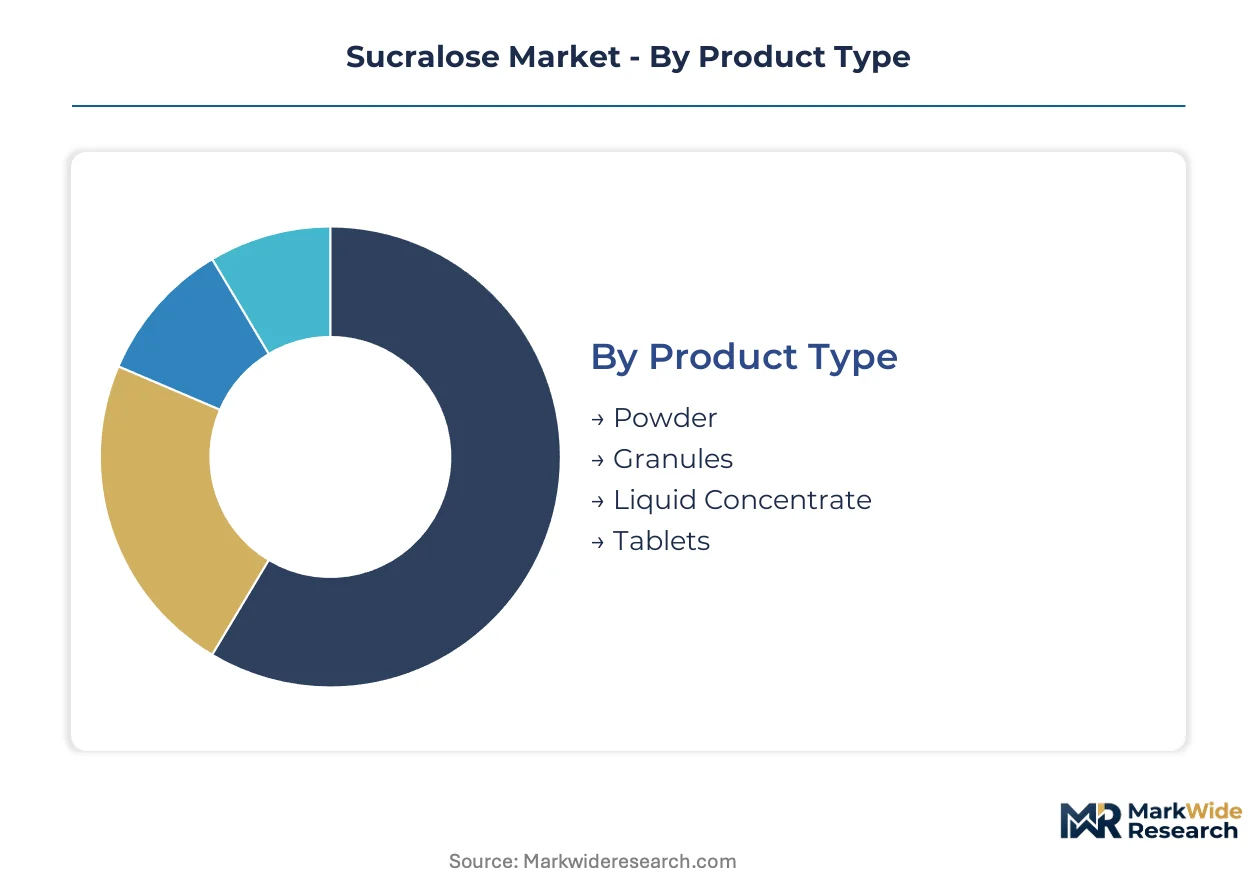
Sucralose market segmentation reveals distinct demand patterns across various forms and applications. Understanding these segments helps producers tailor product offerings and refine distribution strategies. This granular view highlights where specific formulations gain traction and which end-user groups drive volume.
Product Type:
The varying product types of sucralose dictate the level of technical support and formulation guidance required by industrial clients, influencing supplier engagement models.
- Powder:Sucralose in powder form represents the most widely utilized format, characterized by its high purity and excellent stability for diverse applications. Demand for powder concentrates heavily within China's vast food and beverage manufacturing sector, supporting its integration into high-volume consumer goods.
- Liquid Concentrate:Liquid concentrate sucralose provides superior solubility and consistent sweetness dispersion, making it ideal for large-scale beverage production. European beverage manufacturers frequently specify liquid forms for their efficiency in automated dosing systems, ensuring precise formulation control.
- Granules:Granular sucralose provides controlled dissolution properties, often preferred in specific confectionery and baking applications.
- Tablets:Tablet forms offer convenient, pre-portioned sweetness for direct consumer use or specialized dietary supplements.
Powder holds the largest share; momentum sits with Liquid Concentrate.
Application:
Each application for sucralose demands specific purity profiles and functional characteristics, influencing formulation strategies across diverse industries.
- Beverages:This segment represents the largest application for sucralose, driven by consumer preference for sugar-free sodas, flavored waters, and ready-to-drink teas. Government sugar tax policies in the United Kingdom and Mexico compel manufacturers to reformulate products using low-calorie alternatives.
- Pharmaceuticals:Sucralose in pharmaceutical applications requires exceptional purity and stability for use in drug formulations, where it masks bitter tastes without interacting with active ingredients. JK Sucralose Inc. specializes in high-purity grades for this demanding sector.
- Baked Goods:Sucralose provides heat-stable sweetness in baked goods, supporting low-calorie product development for health-conscious consumers.
- Dairy Alternatives:This application utilizes sucralose to sweeten plant-based milks and yogurts, catering to dietary preferences and lactose intolerance.
- Personal Care:Sucralose finds use in personal care products like toothpaste and mouthwash, improving palatability without contributing to dental caries.
Beverages dominate the volume, while Pharmaceuticals demonstrate consistent, high-value growth.
End User:
Different end-user categories for sucralose present distinct purchasing behaviors and regulatory compliance requirements.
- Food & Beverage Manufacturers:These industrial clients represent the primary consumers of sucralose, integrating it into a vast array of products from soft drinks to confectionery. Their demand is directly influenced by consumer trends towards sugar reduction and national health policies.
- Pharmaceutical Companies:These firms procure high-purity sucralose for use as an excipient and sweetener in oral medications, requiring strict adherence to pharmacopoeial standards. Compliance with NMPA regulations in China and US FDA guidelines is paramount for these buyers.
- Cosmetic Producers:Cosmetic producers use sucralose in oral hygiene products to enhance taste and consumer acceptance.
- Nutraceutical Firms:Nutraceutical companies incorporate sucralose into dietary supplements and functional foods for palatable, sugar-free formulations.
Food & Beverage Manufacturers exert the most significant market influence, with Nutraceutical Firms expanding most quickly.
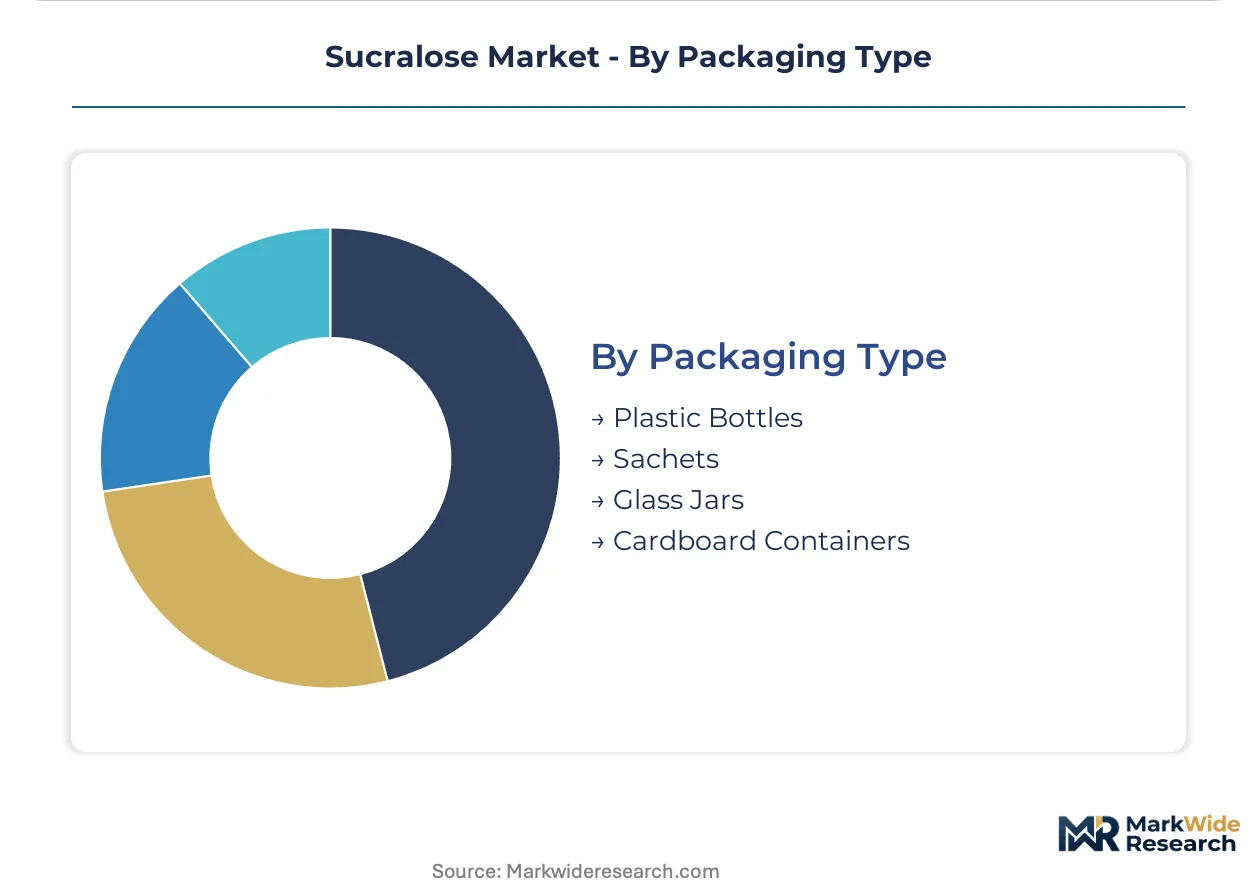
Packaging Type:
The choice of packaging for sucralose often reflects cost considerations and the intended scale of distribution, from bulk industrial supply to retail consumer formats.
- Plastic Bottles:Plastic bottles serve as a common packaging solution for both industrial and consumer-grade sucralose, offering durability and cost-effectiveness. This format is prevalent in North America for liquid concentrate and granular sucralose.
- Sachets:Sachets provide convenient, single-serving portions of sucralose, primarily targeting direct consumer sales and the hospitality sector. This packaging type sees strong demand in Asian markets for individual beverage sweetening.
- Glass Jars:Glass jars are used for premium or specialized sucralose products, often emphasizing product integrity and perceived quality.
- Cardboard Containers:Cardboard containers facilitate bulk transport of powdered sucralose, particularly for large industrial orders to food processing plants.
Plastic Bottles see widespread adoption, while Sachets carve out a significant niche in retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry positions China as a cost-efficient supply hub, while Western markets command higher value for specialized sucralose grades. Diverse regulatory environments and consumer preferences shape demand across continents. This dynamic influences market access and product formulation strategies for sucralose manufacturers globally.
China
China's vast food and beverage manufacturing sector drives significant sucralose demand, leveraging the country's cost-efficient production base. Compliance with GB standards and NMPA regulations governs purity levels for both domestic use and exports. The Yangtze River Delta region, a major industrial cluster, houses numerous food processing plants that integrate sucralose into high-volume consumer goods.
United States
Consumer demand for low-calorie products, particularly in the beverage and nutraceutical sectors, fuels sucralose consumption in the United States. The US FDA mandates rigorous safety assessments for food additives, ensuring product integrity. California's burgeoning food tech industry, centered around Los Angeles and San Francisco, actively develops new sugar-free formulations using sucralose.
United Kingdom
Government sugar tax policies, such as the Soft Drinks Industry Levy, strongly incentivize beverage manufacturers in the United Kingdom to reformulate with sucralose. This fiscal measure aims to reduce public sugar intake and improve health outcomes. London, a hub for beverage innovation, sees significant R&D efforts focused on palatable, sugar-reduced drinks using alternative sweeteners.
Mexico
Mexico's tax on sugary drinks has significantly accelerated the adoption of sucralose as a calorie-free sweetener across its beverage industry. This policy shift directly impacts consumer choices and product availability in the market. Major beverage production facilities around Mexico City are actively integrating sucralose into their product lines to remain competitive.
Vietnam
Rising disposable incomes and increasing health awareness in Vietnam are creating an expanding market for low-calorie food and beverage products. The country's food safety regulations are evolving to accommodate new ingredients and consumer trends. Ho Chi Minh City's dynamic food and beverage sector presents an untapped growth avenue for sucralose suppliers targeting emerging Asian markets.
Sucralose Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical sucralose ingredients. The sucralose market exhibits a tiered structure, with a few large players dominating commodity production alongside niche specialists. Companies engage in strategic partnerships to expand geographic reach and invest in R&D to develop high-purity grades.
Specialists in high-purity sucralose for pharmaceutical applications, such as JK Sucralose Inc., exemplify precision manufacturing within this market. Tate & Lyle PLC leverages its extensive R&D capabilities and established brand recognition to command a premium across diverse applications. Niutang Chemical Ltd. anchors the cost-leadership segment, primarily serving high-volume food and beverage manufacturers with large-scale production capacities.
| Leading Market Players |
|---|
| Newtrend Group |
| Niutang Chemical Ltd. |
| Tate & Lyle PLC |
| Changzhou Hanbang Food Co Ltd. |
| Techno Food Ingredients Co Ltd |
| JK Sucralose Inc. |
| BioPlus Life Sciences |
| Xiamen Boao Technology Co Ltd. |
| Nantong Changhai Food Additive Co Ltd |
| Others |
Cost & Logistics Intelligence
China's vast chemical manufacturing infrastructure, a key upstream concentration, significantly influences sucralose pricing and downstream margin pools for high-volume food and beverage applications. Precursor chemical availability and cost from this region directly impact final product pricing for global buyers.
Pricing Analysis
Configured-to-order pricing for specialized sucralose grades, particularly for pharmaceutical applications, commands a premium over standard, high-volume commodity pricing. The dominant pricing model is contract-based long-term offtake for large food and beverage manufacturers, shifting to transactional per-unit sales for smaller buyers. Price differentiation stems from purity levels, with pharmaceutical-grade sucralose commanding higher values, and geographic delivery costs. Pricing pressure stems from the availability of low-cost producers like Niutang Chemical Ltd. Buyers in the high-volume food and beverage sector are most price-sensitive, while pharmaceutical companies prioritize purity and stability.
Supply Chain Analysis
Precursor chemical price volatility, particularly for chlorinated sucrose intermediates, represents a significant structural supply chain risk for sucralose producers. Geographic supply concentration for these inputs primarily sits in China and India, influencing global production costs. The sucralose synthesis process heavily relies on specific chemical reagents and solvents. Distribution runs through a mix of direct sales to large industrial clients and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sucralose market is currently experiencing a buyer-power shift, driven by the increasing consolidation of major food and beverage manufacturers seeking integrated sweetener solutions. This trend places greater demand on suppliers for comprehensive technical support and customized blends.
For Market Incumbents:Insulate core market share by investing in advanced process control systems to enhance sucralose purity and production efficiency. This move helps counter margin pressure from cost-leadership competitors like Niutang Chemical Ltd. Tate & Lyle PLC can leverage its R&D capabilities to develop novel sweetener blends, securing long-term supply agreements with major beverage manufacturers. Expanding capacity in regions with evolving regulatory frameworks, such as Southeast Asia, also provides a strategic lever for growth.
For New Entrants and Emerging Players:Build out specialized production capabilities for high-purity sucralose, targeting the pharmaceutical and nutraceutical sectors that prioritize quality over volume. The most penetrable segment lies within functional food and sports nutrition, where demand for sugar-free options is expanding. A compelling go-to-market angle involves offering customized sweetener systems that address specific off-note masking challenges, differentiating from commodity suppliers.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized, specialty chemical producers possessing proprietary synthesis technologies or established regulatory approvals in key markets. The long-term viability of sucralose remains strong due to ongoing global sugar reduction initiatives. Acquisition targets should include firms with strong R&D pipelines for next-generation sweeteners or established market access in emerging economies. The signal to watch is the pace of regulatory re-evaluations by bodies like EFSA, which could reshape market dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Secures market access and leverages growing demand for low-calorie products in Vietnam and other emerging economies. |
| R&D in Sweetener Blends | Develops customized sweetness profiles to mask off-notes and mimic sugar, enhancing product differentiation for food formulators. |
| Investment in Process Optimization | Enhances sucralose purity and production efficiency, meeting stringent quality requirements for pharmaceutical applications. |
| Long-term Supply Agreements | Ensures stable supply of sucralose for major food and beverage manufacturers, mitigating precursor chemical price volatility. |
| Geographic Market Penetration | Establishes a stronger presence in untapped markets like Vietnam, capitalizing on rising disposable incomes and health awareness. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, procurement managers, and regulatory affairs specialists across the sucralose value chain and refined through an iterative process. This involved structured interviews with chemical manufacturers, food and beverage formulators, and nutraceutical firms. Secondary validation drew from customs and trade data, national food safety authority publications like US FDA and EFSA reports, and company 10-K filings. A bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Demand-supply balance modeling formed the core of the quantitative analytical framework across the projection horizon. This framework integrated market segmentation across product type, application, end user, and packaging type, along with regional production capacities. Compound Annual Growth Rates were derived from historical data analysis and projected market drivers, including sugar tax policies and consumer health trends. Key forecast inputs included projected beverage industry reformulation rates and precursor chemical availability.
Sensitivities concentrate around unforeseen shifts in global regulatory policies regarding artificial sweeteners and significant disruptions to chemical supply chains. Forecasts reflect assumptions documented through extensive primary and secondary research. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Citrus Molasses Market
Sweeteners
Liquid Sugar Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
China Saccharin Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Europe Stevia Market
Sweeteners
France Food Sweetener Market
Sweeteners
Rice Syrup Market
Sweeteners
Sorbitol Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Fructose Market