
 Dry Sweeteners Market | 2026-2036
Dry Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Sweeteners Market Foresight
Food service buyer concentration is pivoting toward large-scale contract manufacturers and quick-service chains, reshaping volume commitments and pricing leverage across the supply base. Cargill, Incorporated leverages its integrated corn and stevia supply chains to secure cost positions in bulk erythritol. Archer Daniels Midland Company anchors North American distribution through its sweetener ingredient terminals and tolling partnerships. Südzucker AG competes on beet sugar specialization while extending refining capacity into crystalline fructose for industrial bakery clients.
Dry sweeteners encompass powdered, granulated, or crystallized carbohydrate and non-carbohydrate compounds used to impart sweetness in processed foods and beverages, typically standardized by particle size distribution, moisture content below five percent, and flowability indices for automated production lines. Sucrose retains volume leadership across bakery and confectionery applications where bulking and browning functionality remain irreplaceable. Stevia extracts are gaining fastest in beverages as reformulation pipelines prioritize zero-calorie natural positioning. Erythritol commands premium placement in health-conscious consumer channels where digestive tolerance and cooling sensory profiles differentiate finished products.
The FDA governs high-intensity sweetener approvals and GRAS notifications, while the EFSA sets acceptable daily intake thresholds that constrain aspartame formulation ceilings in European formulations. The FSSAI in India enforces additive labeling mandates that push domestic manufacturers toward stevia and monk fruit blends for export compliance. Stakeholders must monitor evolving sweetener additive codes across FDA, EFSA, and FSSAI jurisdictions to anticipate reformulation timelines and secure early-mover positions in next-generation clean-label portfolios.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are compressing formulation cycles and forcing ingredient suppliers to revalidate entire sweetener portfolios under accelerated timelines.
Growth Catalysts
- EFSA Acceptable Daily Intake Revisions:Tightened aspartame thresholds in European formulations are redirecting beverage manufacturers toward stevia-erythritol blends with validated safety dossiers.
- Beverage Sector Expansion:China's sugar reduction campaigns and functional drink proliferation are concentrating procurement volumes among domestic bottlers seeking bulk natural alternatives.
- Crystallization Process Advances:Continuous cooling crystallization systems are reducing erythritol production energy intensity and enabling smaller-batch flexibility for contract manufacturers.
Market Restraints
- Corn Feedstock Volatility:Erythritol production costs track Midwest grain futures, exposing margin structures to weather-driven supply shocks and biofuel policy arbitrage.
- Beet Sugar Supply Concentration:EU processing capacity clusters in northern France and eastern Germany, creating single-source dependency risks for industrial bakery procurement desks.
- Digestive Tolerance Ceilings:Polyol consumption thresholds limit high-dose applications in meal-replacement bars, constraining formulation latitude against allulose competitors.
Strategic Opportunities
- India Export Compliance:FSSAI additive labeling mandates are pushing domestic manufacturers toward monk fruit-stevia blends that satisfy both domestic and Middle Eastern import standards.
- Precision Fermentation:Microbial production of rare sugars is converging with enzymatic conversion platforms to unlock cost parity for tagatose and allulose at commercial scale.
- Direct-to-Manufacturer Platforms:Digital ingredient marketplaces are bypassing traditional distributor markups for mid-sized confectionery producers in Southeast Asia.
Industry Challenges
- GRAS Timeline Compression:Novel sweetener submissions face extended FDA review queues, delaying revenue recognition for developers by 18-24 months beyond historical benchmarks.
- Legacy Equipment Retrofit Costs:Powder handling systems designed for sucrose require humidity-controlled modifications to prevent erythritol caking, straining capex budgets at regional bakeries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Sweeteners Market |
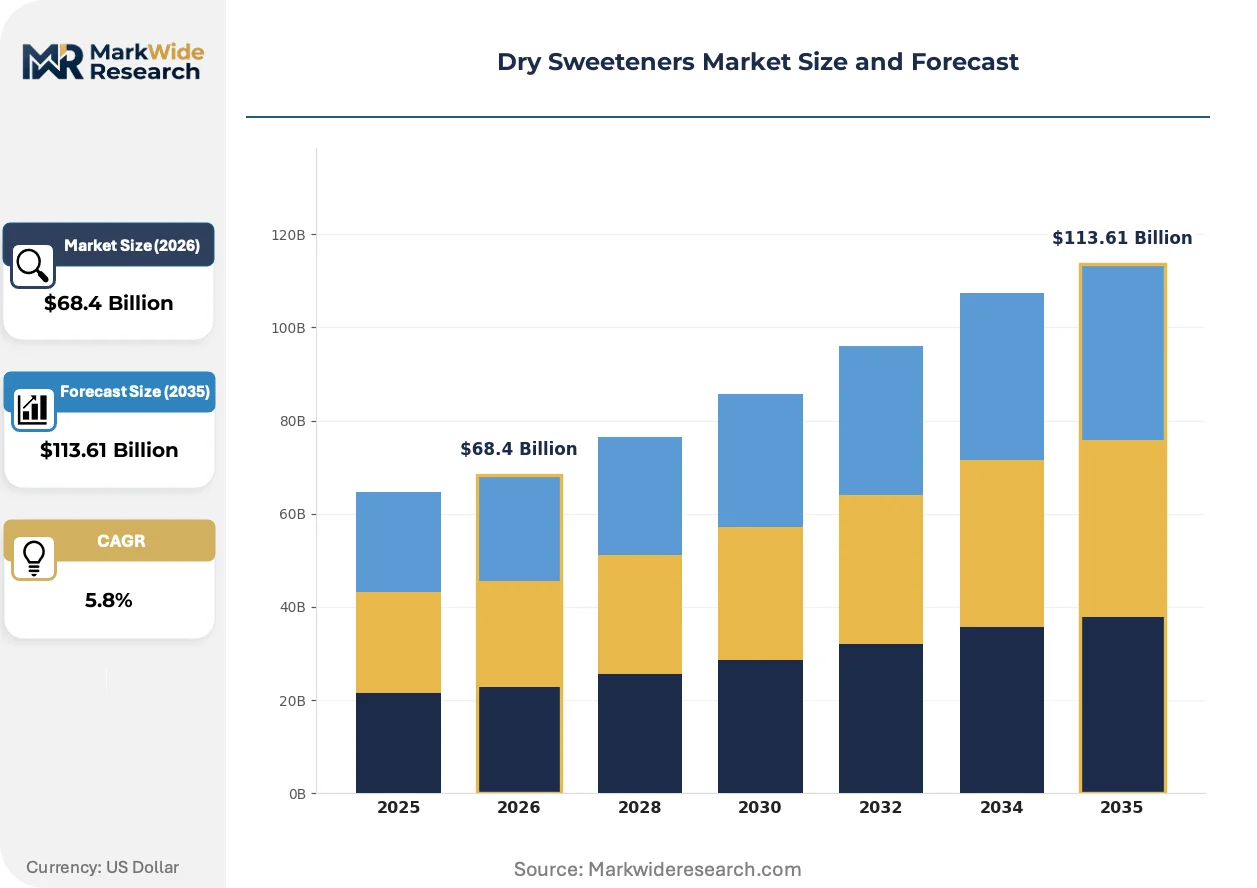
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Stevia, Aspartame, Erythritol Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Retailers, Food Service, Health-conscious Consumers Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle, Roquette Frères, Südzucker AG, Ajinomoto Co., Inc., International Flavors & Fragrances Inc., PureCircle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Sweeteners Market Shifts & Advancements
Formulation science is pivoting from single-ingredient replacement toward synergistic blends that replicate sucrose's full sensory signature while satisfying clean-label procurement criteria.
Enzymatic glycosylation platforms are modularizing stevia extract production, enabling food technologists to tailor rebaudioside ratios for specific bitterness masking in carbonated applications. Mid-sized beverage co-packers in Mexico and Indonesia are adopting these systems to bypass concentrated extract imports. The technology is modularizing supply chain configurations by permitting distributed production nodes closer to formulation facilities.
REACH authorization requirements for synthetic high-intensity sweeteners are elevating documentation burdens for European importers. Manufacturers must now submit extended safety profiles and exposure assessments to ECHA for continued market access. The confectionery segment is responding by accelerating natural sweetener validation programs and dual-sourcing strategies.
Buyer concentration among quick-service chains and private-label retailers is compressing supplier negotiation cycles and unbundling technical service from ingredient pricing. Large-scale contract manufacturers now demand dedicated R&D support and rapid prototype turnaround as table stakes. This pattern is most pronounced in China's beverage corridor, where domestic brand owners consolidate volume among three to four approved sweetener houses.
Dry Sweeteners Market Segmentation
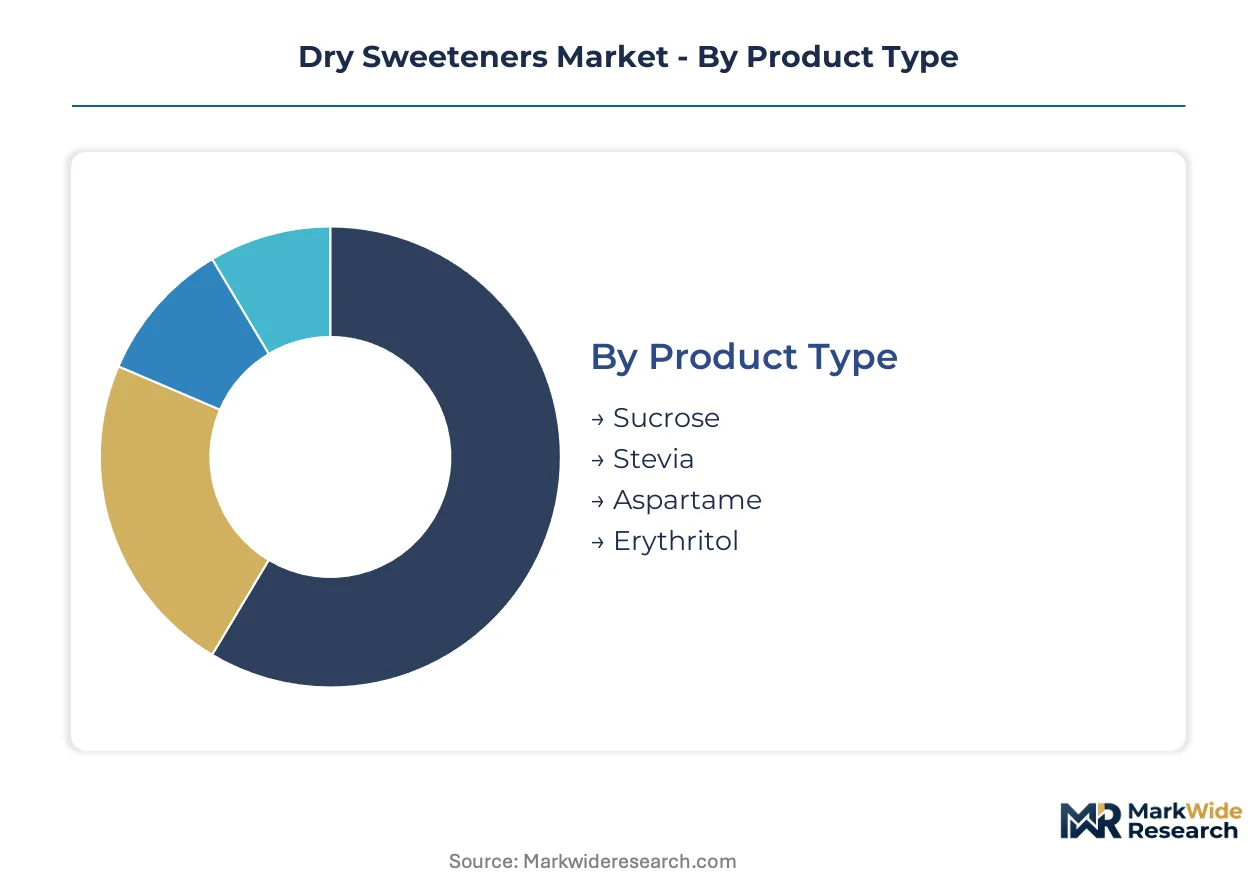
Sweetener selection cascades through formulation chemistry, regulatory compliance, and finished-product positioning. Procurement desks segment their portfolios across functional performance, end-use thermal processing requirements, and clean-label certification thresholds.
Product Type:
Crystallization technology and extraction chemistry differentiate cost structures and formulation latitude across the four product classes.
- Sucrose:Granulated and powdered forms derived from sugarcane or sugar beet provide Maillard browning, bulk density, and hygroscopic control that remains unmatched in laminated dough applications. Industrial bakeries in Germany and France anchor procurement volumes for crystalline sucrose where caramelization kinetics determine finished product appearance.
- Stevia:Glycoside extracts—primarily rebaudioside A and M—deliver zero-calorie sweetness with heat stability up to 200°C, enabling pasteurization-resistant beverage formulations. Chinese extraction facilities supply 70% of global steviol glycoside output, with FSSAI-compliant labeling driving Indian import demand for Reb-M enriched variants.
- Aspartame:Methyl ester dipeptide compound restricted by EFSA daily intake ceilings in European formulations, forcing reformulation toward phenylalanine-free alternatives in pediatric and diabetic product lines.
- Erythritol:Fermentation-derived four-carbon sugar alcohol with 70% sucrose sweetness and negligible glycemic impact, produced via corn glucose fermentation in Iowa and Thailand facilities.
Mature deployment sits with sucrose. Newer deployment is concentrated in stevia.
Application:
Thermal processing intensity and water activity requirements determine sweetener compatibility across finished product categories.
- Beverages:Cold-fill and hot-fill liquid applications prioritize solubility rates, osmotic stability, and aftertaste masking. Stevia-erythritol blends dominate carbonated and still water reformulations in China's sugar-reduction corridor, where SAMR labeling mandates accelerate natural sweetener validation.
- Bakery:Oven temperatures exceeding 180°C demand thermal stability and moisture retention control. Sucrose retains dominance in croissant and puff pastry lamination where crystalline structure creates steam expansion layers.
- Confectionery:Hard candy and chocolate applications require precise control of glass transition temperatures and fat bloom inhibition. Polyol blends face digestive tolerance constraints in portion-controlled formats.
- Dairy:Yogurt and ice cream formulations balance freezing point depression with fermentable carbohydrate exclusion for diabetic-positioned lines.
Volume concentration favors beverages. Margin expansion is steepest in confectionery.
End User:
Scale economies and technical service requirements stratify procurement behavior across buyer categories.
- Food Manufacturers:Multinational CPG houses with integrated R&D facilities demand batch-to-batch consistency certificates and rapid prototype support. These buyers negotiate multi-year supply agreements locking in erythritol volumes from Thai fermentation facilities.
- Retailers:Private-label program managers source co-packed formulations with specified sweetener declarations, prioritizing EFSA and FDA dual-compliance for cross-border distribution.
- Food Service:Quick-service chains and contract caterers specify pourable and packet formats with portion-controlled dosing for fountain beverage systems.
- Health-conscious Consumers:Direct purchasers of tabletop sweeteners prioritize monk fruit and stevia extracts with organic certification and non-GMO verification.
Contract volume aggregates with food manufacturers. Direct-to-consumer channels are expanding most quickly.
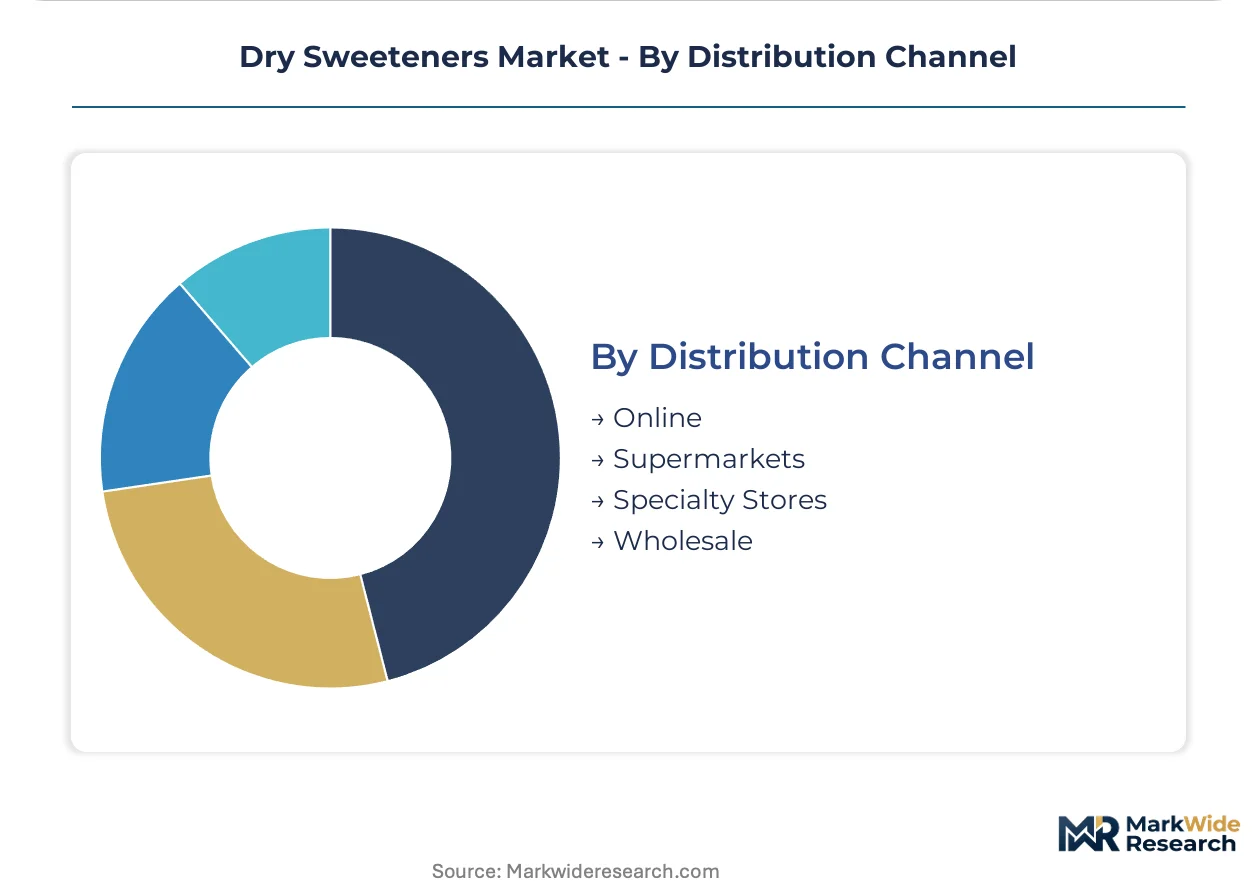
Distribution Channel:
Logistics infrastructure and buyer technical sophistication determine channel selection for bulk and packaged sweetener flows.
- Online:Direct-to-manufacturer platforms and B2B marketplaces bypass traditional distributor markups for mid-tier confectionery producers in Indonesia and Vietnam, with digital procurement penetration accelerating post-pandemic.
- Supermarkets:Mass-market tabletop sweetener placement depends on shelf-space negotiations and promotional slotting fees for stevia and sucralose private-label lines.
- Specialty Stores:Health food retailers and organic co-ops command premium positioning for rare sugar alternatives including allulose and tagatose with validated low-glycemic claims.
- Wholesale:Industrial ingredient terminals operated by Archer Daniels Midland and Cargill handle bulk sucrose and crystalline fructose flows to regional bakery and beverage co-packers.
Traditional wholesale anchors industrial procurement. Digital platforms are gaining share fastest in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volumes for plant-derived alternatives as beverage manufacturers accelerate reformulation timelines. Germany and the United States anchor industrial bakery demand for crystalline sucrose and specialty polyols. India emerges as a compliance-driven export hub where FSSAI labeling mandates reshape domestic production patterns.
China
SAMR sugar-reduction campaigns and functional beverage proliferation drive stevia-erythritol procurement volumes among domestic bottlers. The national regulator enforces additive labeling mandates that accelerate natural sweetener validation programs. Shanghai and Guangdong province concentrate fermentation capacity for corn-derived erythritol serving Asia-Pacific formulation facilities.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia anchor crystalline sucrose demand for laminated dough applications where Maillard browning remains irreplaceable. EFSA tightened aspartame acceptable daily intake thresholds, redirecting beverage manufacturers toward validated stevia dossiers. The country's beet sugar processing clusters in northern regions create supply concentration for EU-wide procurement desks.
United States
Midwest corn belt proximity determines erythritol production economics as Cargill and ADM operate integrated fermentation facilities. FDA GRAS notification requirements for novel sweeteners extend review timelines, compressing revenue recognition windows for developers. Iowa and Illinois host bulk sweetener terminals handling crystalline fructose flows to regional beverage co-packers.
India
FSSAI additive labeling mandates push domestic manufacturers toward monk fruit-stevia blends satisfying Middle Eastern export standards. The regulator enforces dual-compliance protocols that accelerate clean-label portfolio development. Maharashtra and Gujarat concentrate extraction and blending operations for Reb-M enriched variants targeting Gulf Cooperation Council markets.
Thailand
Cassava-derived glucose feedstock supports erythritol fermentation capacity expansion serving Japanese and Australian beverage importers. The Board of Investment promotes bioprocessing infrastructure through tax incentive schemes. Eastern Economic Corridor provinces host contract manufacturing facilities supplying ASEAN-wide natural sweetener demand.
Dry Sweeteners Market Competitive Landscape
North American agribusiness conglomerates anchor one tier; European beet sugar specialists and Asian extraction houses hold differentiated positions in natural alternatives. The vendor base stratifies across integrated commodity processors, fermentation technology operators, and botanical extract refiners. Three archetypes dominate: corn-to-polyol integrators, steviol glycoside extraction specialists, and beet sugar refiners extending into crystalline fructose. Capacity expansion and backward integration into captive glucose supply represent the primary competitive vectors.
Within the integrated processing tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain control through Midwest corn origination and coastal distribution terminal networks. Südzucker AG occupies a position as the European beet sugar specialist extending refining capacity into industrial bakery sweetener segments. These three entities represent distinct geographic and feedstock archetypes rather than direct product competitors.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle |
| Roquette Frères |
| Südzucker AG |
| Ajinomoto Co., Inc. |
| International Flavors & Fragrances Inc. |
| PureCircle |
| Others |
Supply & Pricing Matrix
Fermentation technologist clusters in Iowa and Thailand generate labor-cost differentials that widen pricing-tier spreads between commodity erythritol and premium steviol glycoside extracts. Corn belt proximity to Midwest processing plants compresses logistics overhead for bulk polyol output, while Chinese extraction facilities command quality premiums through Reb-M specialization.
Pricing Analysis
Volume concentrates in contract-manufactured erythritol for beverage reformulation, while margin accretion flows to stevia extract houses with validated GRAS dossiers. Three-tier pricing structure separates pharmaceutical-grade monk fruit from standard stevia blends and economy sucrose for industrial bakery. Pricing pressure stems from Midwest grain futures volatility feeding into corn-derived polyol cost structures. Quick-service chains exhibit highest price sensitivity through centralized procurement desks, whereas multinational CPG houses absorb premiums for regulatory compliance certainty.
Supply Chain Analysis
Freight cost arbitrage between Thai cassava corridors and Iowa corn belt facilities shapes regional sourcing decisions for Asia-Pacific beverage bottlers. Supply concentrates in Chinese steviol glycoside extraction, Thai erythritol fermentation, and EU beet sugar refining clusters. Raw material dependencies center on corn glucose, sugar beet pulp, and stevia leaf biomass. Single-source vulnerability runs through Shanghai stevia concentration for Reb-M supply. Distribution runs through ADM and Cargill coastal terminals serving North American co-packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EFSA's tightened aspartame thresholds erect regulatory moats favoring dossier-validated natural sweetener houses over commodity processors lacking safety investment capacity.
For Market Incumbents: Acquire fermentation capacity in Thai Eastern Economic Corridor to secure cassava-feedstock cost positions against Midwest corn volatility. Backward integration into captive stevia leaf cultivation in Guangdong province defends margin structure against Chinese extraction concentration. Lock multi-year supply agreements with domestic beverage bottlers before SAMR labeling mandates accelerate procurement consolidation. For New Entrants and Emerging Players: Capture FSSAI-compliant monk fruit-stevia blend demand among Maharashtra-based exporters serving Gulf Cooperation Council markets. White-space sits with precision-fermentation rare sugars where enzymatic conversion platforms achieve cost parity. Digital direct-to-manufacturer marketplaces in Indonesia and Vietnam bypass entrenched distributor markups for mid-tier confectionery procurement. For Investors and Strategic Acquirers: Re-rating potential sits with integrated corn-to-polyol processors given FDA GRAS timeline compression extending review queues for novel entrants. Long-term viability favors fermentation technology operators with backward feedstock control. Watch EFSA additive code revisions as inflection signal for portfolio reallocation toward natural extract houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | Corn belt origination secures cost positions against biofuel policy arbitrage and weather-driven supply shocks. |
| GRAS Dossier Investment for Novel Extracts | FDA review queue compression rewards early-mover safety validation with 18-24 month competitive lead. |
| Regional Fermentation Capacity Expansion | Thai cassava corridor proximity reduces freight exposure for Japanese and Australian beverage importers. |
| Digital Platform Launch for B2B Procurement | Direct-to-manufacturer marketplaces bypass traditional distributor markups in Southeast Asian confectionery. |
| Dual-Compliance Formulation Development | EFSA-FDA aligned portfolios capture cross-border private-label demand from retailer procurement desks. |
Research Methodology
Independent corroboration across FDA GRAS notification filings, EFSA safety dossier databases, and SAMR additive labeling directives underwrites the qualitative findings. Primary interviews with fermentation plant managers, beverage formulation technologists, and FSSAI regulatory consultants combined with secondary validation from customs trade data, SEC 10-K filings of agribusiness conglomerates, and FAO sweetener production statistics. Bottom-up volume modeling triangulates against top-down expenditure analysis across food manufacturer procurement desks.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span sweetener chemistry class, thermal processing application, and regulatory compliance tier. CAGRs derive from installed fermentation capacity trajectories, extraction yield improvements, and reformulation pipeline visibility at multinational CPG houses. Forecast inputs incorporate corn futures curve dynamics and stevia leaf harvest variability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA additive code revisions and SAMR enforcement intensity. Forecasts reflect assumptions about regulatory timeline adherence and feedstock cost stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Rare Sugar Market
Sweeteners
South America Stevia Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Coconut Sugar Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Methyl Glucose Market
Sweeteners
Glucose Syrup Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Maltitol Market
Sweeteners
Dextrates Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Erythritol Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Global Brown Sugar Market