
 Mexico Food Sweetener Market | 2026-2036
Mexico Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Food Sweetener Market Foresight
Health-conscious consumers is rotating demand away from traditional sugar-laden products toward reduced-calorie and clean-label alternatives across Mexican retail channels. Cargill leverages its extensive agricultural supply chain to dominate bulk high-intensity sweetener distribution to industrial food processors. Tate & Lyle anchors the premium formulation segment with specialized texturizing systems that mask off-notes in stevia-sweetened beverages. Ajinomoto Co., Inc. specializes in aspartame and amino acid-based sweetener applications for the Mexican dairy and confectionery sectors.
Food sweeteners encompass caloric and non-caloric substances that impart sweetness to food and beverage matrices, typically measured by sucrose equivalence factors ranging from 30 to 600 times standard sugar intensity. These compounds function as sugar replacers, texture modifiers, and shelf-life extenders in processed foods where thermal stability and pH tolerance determine application suitability. Stevia extracts lead the natural sweetener category due to expanding clean-label preferences among Mexican urban consumers, though sucralose retains the largest volume share in carbonated soft drink reformulations. The liquid form segment captures disproportionate value in beverage manufacturing, while granulated formats sustain dominance in bakery applications where crystalline structure affects dough rheology.
COFEPRIS enforces food additive safety standards under NOM-051 front-of-package labeling rules that directly restrict high-sugar product marketing and incentivize reformulation with approved non-nutritive sweeteners. The Secretariat of Economy coordinates with BIS-equivalent technical committees to align Mexican sweetener specifications with evolving Codex Alimentarius international standards for trade compatibility. Stakeholders must monitor pending modifications to NOM-051 implementation thresholds and assess captive blending capabilities before committing to single-source sweetener supply agreements.
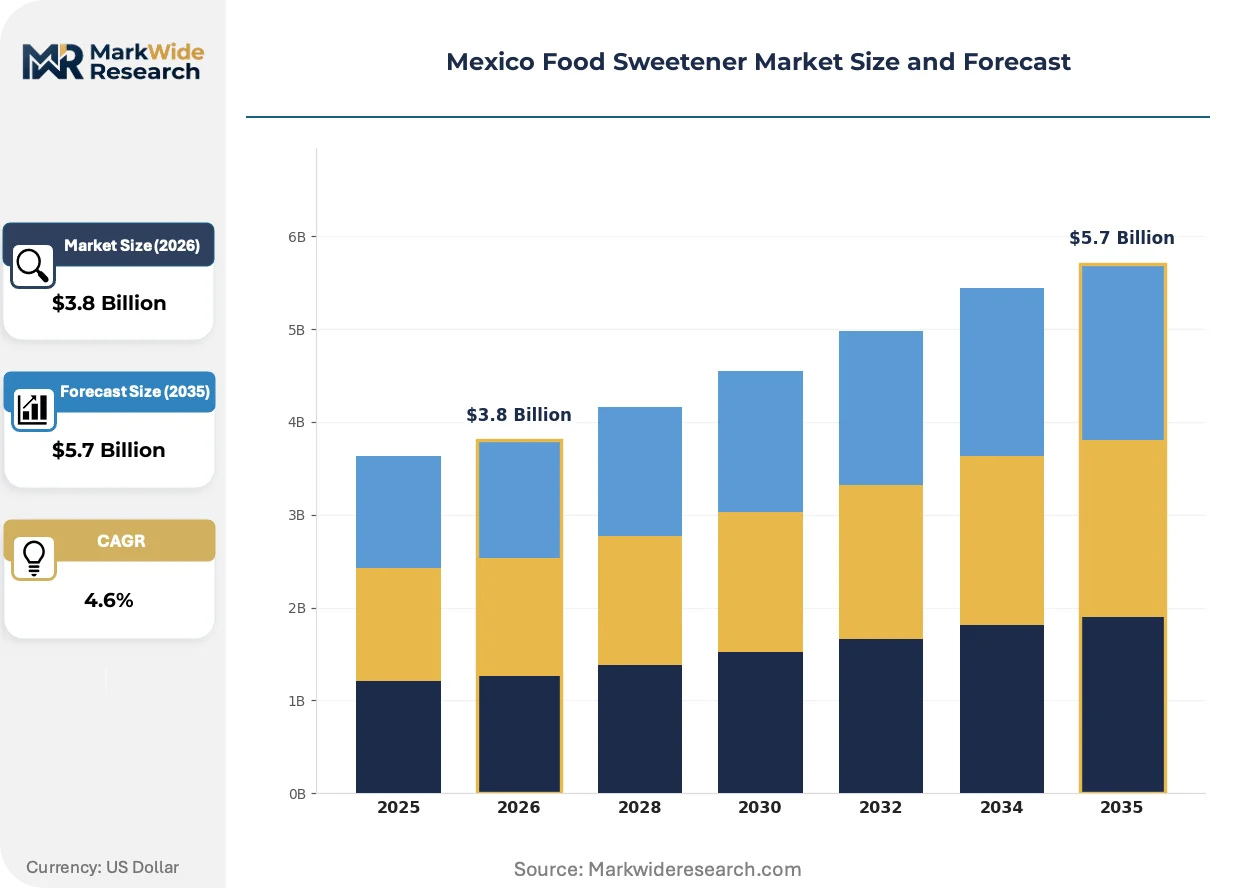
Market Dynamics
NOM-051 front-of-package warning labels are forcing beverage and packaged food manufacturers to accelerate reformulation timelines, converting sucrose-heavy portfolios toward non-nutritive alternatives across Mexican production facilities.
Growth Catalysts
- COFEPRIS NOM-051 enforcement:Mandatory octagonal warning labels on high-sugar products compel manufacturers to reduce caloric density through approved sweetener substitutions.
- Stevia extraction biotechnology:Enzymatic bioconversion methods are lowering production costs for Reb M and Reb D glycosides, expanding accessibility for mid-tier beverage formulators.
- Monterrey industrial corridor concentration:Dense clustering of dairy and confectionery processors creates localized demand pull for specialized amino acid-based sweetener blends.
Market Restraints
- Stevia leaf supply volatility:Weather-dependent harvests in Guizhou and Paraguay cultivation zones generate raw material price instability for natural extract processors.
- Sucralose manufacturing concentration:Three integrated chemical producers control bulk sucralose supply to Latin America, creating single-source vulnerability for carbonated soft drink bottlers.
- Thermal degradation thresholds:Aspartame instability above 85°C restricts application in UHT dairy and high-temperature bakery processes, limiting substitution flexibility.
Strategic Opportunities
- Querétaro-Bajío beverage cluster expansion:Greenfield bottling investments by multinational CPG groups create captive demand for localized liquid sweetener blending facilities.
- Allulose regulatory approval pathway:Pending COFEPRIS novel food designation would unlock rare sugar applications in Mexican diabetic-friendly confectionery segments.
- E-commerce ingredient sourcing platforms:Direct-to-manufacturer digital procurement channels are disintermediating traditional distributor networks for mid-scale bakery operations.
Industry Challenges
- Reformulation technical staffing scarcity:Shortage of food technologists trained in sweetness modulation and off-note masking complicates NOM-051 compliance timelines for regional brands.
- Dual-labeling inventory complexity:Parallel SKU maintenance for pre- and post-reformulation products strains working capital and warehouse management systems during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Food Sweetener Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sweetener Type: Stevia, Sucralose, Aspartame, Saccharin End Use: Beverages, Bakery Products, Dairy Products, Sauces Form: Liquid, Granulated, Powder, Bulk Distribution Channel: Supermarkets, Convenience Stores, Online, Health Stores |
| Companies Covered | Tate & Lyle, Ajinomoto Co., Inc., Cargill, AGRANA Beteiligungs AG, Kerry Group plc, Archer Daniels Midland Company, International Flavors & Fragrances, Koninklijke DSM N.V., Ingredion, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Food Sweetener Market Shifts & Advancements
Clean-label imperatives are intersecting with regulatory pressure to reshape ingredient selection protocols, pushing manufacturers beyond single-drop-in replacements toward integrated sweetness-texture systems.
Enzymatically produced steviol glycosides are fragmenting the natural sweetener cost structure. Mid-market beverage formulators in Jalisco and Puebla are adopting these next-generation extracts at accelerating rates. The technology is fragmenting historical premium-mass tier boundaries that separated Cargill-supplied multinational processors from regional compounders.
COFEPRIS harmonization with Codex Alimentarius additive specifications is tightening purity thresholds for imported high-intensity sweeteners. Mexican customs laboratories are rejecting shipments with elevated residual solvent levels, forcing suppliers to upgrade refining protocols. Carbonated soft drink concentrate importers bear the highest compliance burden, redirecting sourcing toward ISO-certified European and North American producers.
Urban retail buyers are consolidating procurement authority at headquarters level, displacing autonomous plant-level purchasing decisions. Large-format retailers in Mexico City metropolitan area are imposing approved-supplier lists that privilege vertically integrated sweetener-blend providers. This concentration is most visible in the private-label beverage segment, where Walmart México and Chedraui centralize formulation specifications.
Mexico Food Sweetener Market Segmentation
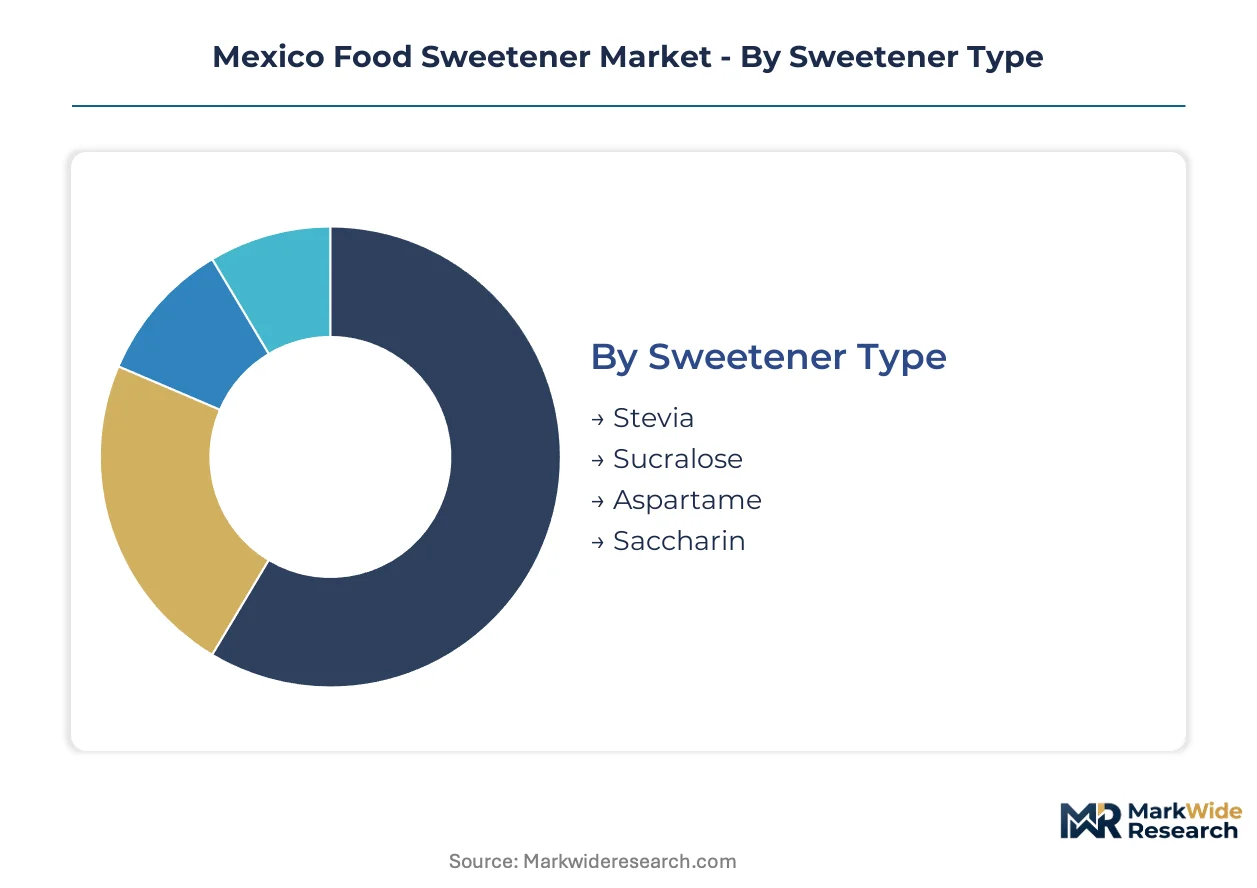
Segmentation reveals how NOM-051 compliance pressures reshape procurement patterns across Mexican manufacturing tiers. Sweetener selection now hinges on thermal stability requirements, distribution reach, and reformulation service capabilities rather than commodity pricing alone.
Sweetener Type:
Domestic beverage bottlers drive demand for heat-stable synthetics, while export-oriented processors favor natural extracts to meet international clean-label standards.
- Stevia:Reb M and Reb D glycosides extracted through enzymatic bioconversion deliver superior taste profiles without the licorice aftertaste of conventional steviosides. Jalisco and Puebla beverage formulators are adopting these premium extracts at accelerating rates as enzymatic production lowers unit costs. The segment pulls demand from both NOM-051 compliance mandates and Walmart México's clean-label supplier requirements.
- Sucralose:A chlorinated sucrose derivative maintaining sweetness stability across pH ranges from 3.0 to 8.0 and temperatures exceeding 120°C. Carbonated soft drink concentrate importers in Mexico City metropolitan area rely on this segment despite supply concentration among three global chemical producers. Thermal resilience makes it indispensable for UHT processing lines.
- Aspartame:A dipeptide methyl ester restricted to ambient and refrigerated applications due to thermal degradation above 85°C. Mexican dairy processors in Monterrey industrial corridor utilize this segment for flavored milk and yogurt applications where heating requirements remain moderate.
- Saccharin:The oldest high-intensity synthetic, produced through toluene sulfonation with characteristic metallic aftertaste. Legacy tabletop applications and industrial compounders in State of Mexico industrial corridors sustain residual demand.
Sucralose commands the established base. The steepest expansion runs through stevia enzymatic glycosides.
End Use:
Application requirements vary sharply by thermal processing intensity and sweetness modulation complexity.
- Beverages:Carbonated soft drinks, flavored waters, and juice concentrates requiring precise sweetness-acid balance. Mexico City metropolitan bottlers dominate procurement volume, with NOM-051 warning labels forcing rapid portfolio reformulation toward non-nutritive blends.
- Bakery Products:Cookies, cakes, and pastries where Maillard browning reactions and moisture retention complicate sugar substitution. Crystalline structure requirements favor granulated formats, though sucralose heat stability enables partial replacement in industrial tunnel ovens.
- Dairy Products:Flavored milks, yogurts, and dairy-based desserts where protein-sweetener interactions affect mouthfeel. Monterrey's dense dairy processor clustering creates localized demand for amino acid-based sweetener systems.
- Sauces:Ketchup, dressings, and condiments with high acidity and pasteurization requirements. Mid-scale manufacturers in Querétaro-Bajío corridor are expanding reformulation programs to reduce added sugars.
Beverages anchor procurement volumes. Dairy applications are climbing the fastest as processors navigate NOM-051 thresholds.
Form:
Physical format selection tracks manufacturing scale and dosing precision requirements.
- Liquid:Pre-dissolved concentrates enabling automated dosing in high-speed bottling lines. Multinational CPG greenfield investments in Querétaro-Bajío are creating captive demand for localized liquid blending facilities.
- Granulated:Free-flowing crystalline particles matching sugar's handling properties in bakery dough systems. State of Mexico industrial corridors sustain dominance through legacy equipment compatibility.
- Powder:Fine-milled particles for instant beverage mixes and dry seasoning blends. E-commerce ingredient platforms are disintermediating traditional distribution for mid-scale users.
- Bulk:Tanker or tote-container delivery for high-volume processors with captive blending capabilities. Cargill's agricultural supply chain integration secures preferential access to this tier.
Granulated formats command the established base. Liquid concentrates are gaining share fastest through automated manufacturing investments.
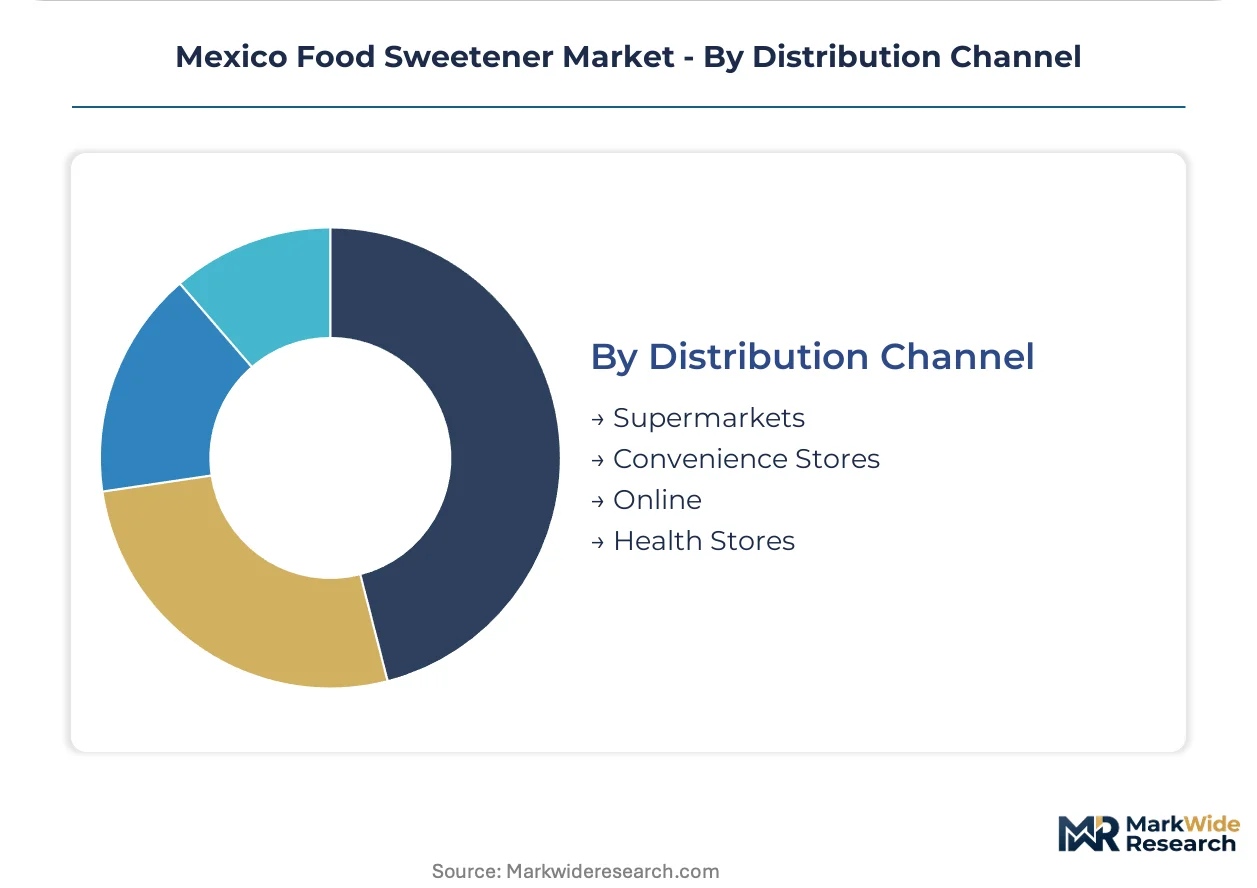
Distribution Channel:
Channel selection reflects buyer scale and formulation support requirements.
- Supermarkets:Retail tabletop sweetener sales concentrated in Mexico City metropolitan area and Monterrey. Private-label expansion by Walmart México and Chedraui is consolidating procurement authority at headquarters level.
- Convenience Stores:Impulse-oriented single-serve packets and small-format products. OXXO's national network provides reach into secondary cities and rural corridors.
- Online:Direct-to-manufacturer ingredient sourcing and specialty natural sweetener retail. Digital procurement channels are disintermediating traditional distributor networks for mid-scale bakery operations.
- Health Stores:Premium organic and non-GMO certified stevia products. Urban consumer clean-label preferences concentrate demand in Polanco, Condesa, and San Pedro Garza García retail zones.
Supermarkets command the established base. Online B2B procurement is climbing the fastest as manufacturers seek direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ferrocarril Suburbano rail network and the Lerma River basin water infrastructure anchor the Mexico City metropolitan area's dominance in food sweetener processing and distribution corridors.
Mexico City Metropolitan Area
The Valley of Mexico concentrates beverage bottling headquarters and reformulation R&D facilities serving national brands. COFEPRIS regulatory filings flow through this administrative hub, creating compliance service clusters. Industrial corridors in Toluca and Cuautitlán Izcalli host liquid sweetener blending operations for carbonated soft drink concentrate importers.
Nuevo León
Monterrey's dense dairy processor clustering generates localized demand for amino acid-based sweetener systems in flavored milk and yogurt applications. The state's technical university network supplies food technologists trained in sweetness modulation. García and Apodaca municipalities concentrate industrial compounders serving regional confectionery manufacturers.
Jalisco
Guadalajara anchors Mexico's second-largest beverage production zone, with mid-market formulators adopting enzymatically produced steviol glycosides at accelerating rates. The ZMG industrial belt connects to Pacific port infrastructure for raw material import. El Salto and Tlajomulco host expanding natural extract processing facilities.
Bajío Region
Querétaro's greenfield bottling investments by multinational CPG groups create captive demand for localized liquid sweetener blending facilities. The Qro-Mex industrial corridor links to central Mexico distribution networks. San Juan del Río and El Marqués municipalities concentrate mid-scale sauce manufacturers navigating NOM-051 sugar reduction thresholds.
Northern Border States
Baja California and Chihuahua maquiladora operations process sweetener-intensive products for cross-border retail channels. Tijuana and Ciudad Juárez facilities maintain dual-labeling inventory for US and Mexican market specifications. COFEPRIS-FDA regulatory alignment pressures drive adoption of Codex-harmonized additive specifications in these export zones.
Mexico Food Sweetener Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and agricultural supply chain integration dimensions. The market structure tilts toward consolidated bulk distribution at the base and fragmented specialty blending at the premium tier. Three strategic archetypes dominate: multinational agricultural conglomerates with captive extraction capabilities, European and Japanese specialty ingredient formulators with proprietary masking technologies, and regional compounders serving mid-scale manufacturers. Capacity expansion and enzymatic bioconversion licensing represent the dominant competitive moves reshaping procurement relationships.
Within the multinational agricultural tier, Cargill anchors bulk high-intensity sweetener distribution through extensive supply chain integration. Tate & Lyle occupies a position exemplifying European specialty formulators with advanced texturizing systems. Ajinomoto Co., Inc. represents Japanese amino acid-based specialists serving dairy and confectionery applications. These three entities collectively illustrate how geographic origin and corporate structure map to distinct service archetypes in Mexican procurement channels.
| Leading Market Players |
|---|
| Tate & Lyle |
| Ajinomoto Co., Inc. |
| Cargill |
| AGRANA Beteiligungs AG |
| Kerry Group plc |
| Archer Daniels Midland Company |
| International Flavors & Fragrances |
| Koninklijke DSM N.V. |
| Ingredion |
| Others |
Supply & Pricing Matrix
Enzymatic stevia bioconversion replacing conventional leaf extraction is redrawing procurement geography toward biotechnology hubs while collapsing historical premium-mass price boundaries across Mexican formulation tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Mexican sweetener procurement. Price differentiation hinges on Reb M/Reb D glycoside purity grades and COFEPRIS certification tier for imported concentrates. Cost compression in mid-market enzymatic extracts is intensifying because Jalisco and Puebla beverage formulators are bypassing traditional distributor markups. Multinational CPG buyers exhibit lowest price sensitivity due to captive blending capabilities, while regional bakery compounders face acute margin pressure from inventory carrying costs.
Supply Chain Analysis
Inbound logistics costs from Guizhou and Paraguay stevia cultivation zones through Lázaro Cárdenas and Manzanillo ports create working capital intensity for natural extract processors. Bulk sucralose supply draws from China, India, and the United States, with chlorinated sucrose derivatives subject to residual solvent testing at COFEPRIS customs laboratories. Single-source vulnerability concentrates among three integrated chemical producers serving Latin American carbonated soft drink bottlers. Distribution runs through Cargill's agricultural supply chain integration for bulk high-intensity sweeteners, while specialty amino acid-based systems rely on regional compounder networks in Monterrey and State of Mexico industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food technologists trained in sweetness modulation and off-note masking represent the critical capability gap constraining NOM-051 compliance timelines for regional Mexican brands.
For Market Incumbents: Shield market position by deepening backward integration into enzymatic bioconversion licensing for Reb M and Reb D glycosides, countering emerging biotechnology entrants from Asian fermentation specialists. Expand captive liquid blending capacity in Querétaro-Bajío corridor to capture multinational CPG greenfield investments. Prioritize ISO-certified refining protocol upgrades to preempt COFEPRIS customs rejection risk on residual solvent thresholds. For New Entrants and Emerging Players: Technical staffing services for reformulation projects represent an under-served layer where incumbents lack dedicated deployment resources. Target mid-scale sauce manufacturers in San Juan del Río and El Marqués navigating NOM-051 sugar reduction thresholds without in-house food technology capabilities. Build go-to-market through direct e-commerce ingredient platforms disintermediating traditional distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional compounders in Monterrey industrial corridor holding specialized amino acid-based sweetener blending capabilities. Five-to-ten year viability hinges on COFEPRIS novel food approval pathways for rare sugars like allulose unlocking diabetic-friendly confectionery applications. Monitor pending NOM-051 threshold modifications as the inflection signal determining reformulation service demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Licensing | Reb M and Reb D glycoside production cost reduction fragments premium-mass tier boundaries for mid-market beverage formulators. |
| COFEPRIS Novel Food Approval | Allulose regulatory pathway unlocks rare sugar applications in Mexican diabetic-friendly confectionery segments. |
| Querétaro-Bajío Liquid Blending Capacity | Localized facilities capture multinational CPG greenfield bottling investments with captive demand. |
| E-commerce B2B Platform Development | Direct-to-manufacturer procurement channels disintermediate traditional distributor networks for mid-scale bakery operations. |
| ISO-Certified Refining Protocol Upgrade | Residual solvent compliance prevents COFEPRIS customs laboratory rejection of imported high-intensity sweetener shipments. |
Research Methodology
The analysis maps stevia extract, sucralose, aspartame, and saccharin sub-sectors, each validated through food technology directors, procurement leads at beverage bottlers, regulatory affairs specialists, and distribution channel managers. Primary interviews with COFEPRIS compliance consultants and secondary validation through customs import records, SEC filings of listed ingredient suppliers, and Codex Alimentarius additive specifications inform the foundation. Bottom-up demand modeling from individual manufacturing facilities triangulates against top-down trade flow analysis.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models sweetener type, end-use application, physical form, and distribution channel segmentation dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating NOM-051 compliance timeline assumptions and enzymatic production cost decline trajectories. Forecast inputs include beverage reformulation program announcements and greenfield bottling investment disclosures.
Forecasts assume regulatory continuity in COFEPRIS NOM-051 implementation and Codex Alimentarius harmonization; material policy shifts would require re-modeling. Stevia leaf supply volatility from weather-dependent harvests and pending allulose novel food designation represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Methyl Glucose Market
Sweeteners
Sucralose Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Sorbitol Market
Sweeteners
Xylitol Market
Sweeteners
Smoked Sugar Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Liquid Sugar Market
Sweeteners
Tagatose Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Mannitol Market
Sweeteners
D-Mannose Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Palm Sugar Market