
 Inverted Squeeze Bottle Market | 2026-2036
Inverted Squeeze Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Inverted Squeeze Bottle Market Foresight
Capital-intensity divergence between blow-molding specialists and brand-owning consumer goods groups is redrawing competitive boundaries in inverted squeeze bottle supply. Amcor Limited leverages integrated resin-to-film capabilities across multiple continents. Berry Global Inc. anchors North American production scale through extensive thermoforming and extrusion networks. Silgan Holdings Inc. competes via rigid packaging specialization serving food and personal care multinationals.
An inverted squeeze bottle is a flexible container engineered with a valve or dispensing closure at its base, typically fabricated from high-density polyethylene or polypropylene via extrusion blow molding, designed to deliver viscous fluids—ketchup, sauces, lotions, or cleaning agents—through gravity-assisted flow without inversion by the user. Plastic variants dominate unit economics due to resin cost efficiency and cycle-time advantages in high-cavitation molding, while silicone segments command premium positioning in reusable household and infant-care applications. Leak-proof feature engineering now represents the fastest-growing specification branch as e-commerce shipment damage rates drive closure-investment intensity.
FDA food-contact notification requirements govern resin additives and migration thresholds for U.S.-destined inverted squeeze bottles, while EU REACH and the Packaging and Packaging Waste Regulation mandate recycled-content minimums and extended producer responsibility schemes across European supply chains. China's SAMR enforces GB standards for plastic food-contact materials that restrict specific plasticizers and mandate labeling transparency. Stakeholders must monitor evolving state-level recycled-content mandates in California and New York, assess dual-sourcing strategies for compliant resin grades, and calibrate R&D allocation between virgin-performance optimization and post-consumer recycled integration pathways.
Market Dynamics
EU single-use plastic directives and FDA food-contact notifications are jointly forcing resin requalification cycles that compress formulation lead times while expanding testing budgets across blow-molding supply chains.
Growth Catalysts
- Condiment dispensing efficiency:Food service operators in the United States prioritize gravity-fed valve systems that reduce portion waste and accelerate service throughput during peak hours.
- REACH recycled-content mandates:European Union Packaging and Packaging Waste Regulation minimums pull post-consumer polyethylene into compliant food-contact grades faster than virgin-resin expansion.
- E-commerce shipment integrity:Leak-proof closure engineering investment intensity rises as direct-to-consumer sauce and personal care brands absorb damage-rate penalties from logistics providers.
Market Restraints
- Resin price volatility:High-density polyethylene feedstock costs track naphtha and natural gas liquid swings that destabilize converter margin structures quarter-to-quarter.
- Closure-component supply concentration:Silicone valve diaphragm and precision-molded polypropylene dispensing tip production clusters in southeastern China, exposing brands to port congestion and tariff exposure.
- Migration threshold compliance:FDA food-contact notification requirements for recycled-content resins extend approval timelines beyond virgin-material substitution schedules.
Strategic Opportunities
- India food-processing expansion:FSSAI packaging compliance requirements for domestic sauce and condiment brands create specification windows for imported blow-molding equipment and technical closure partnerships.
- Refill station channel emergence:Bulk dispensing retail formats in Germany and the Netherlands bypass single-use mandates while demanding durable silicone-body inverted bottles with standardized neck finishes.
- California recycled-content mandates:State-level minimums accelerate ahead of federal timelines, rewarding early movers with compliant resin inventories and preferred supplier status with in-state CPG brands.
Industry Challenges
- Multi-cavity mold commissioning timelines:Lead times for high-cavitation blow-molds stretch 18-24 months, constraining capacity response to demand surges in specific neck-finish specifications.
- Post-consumer recycled integration:Food-contact approval pathways for mechanically recycled polyethylene require extensive extraction testing that delays product launches versus virgin-resin benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inverted Squeeze Bottle Market |
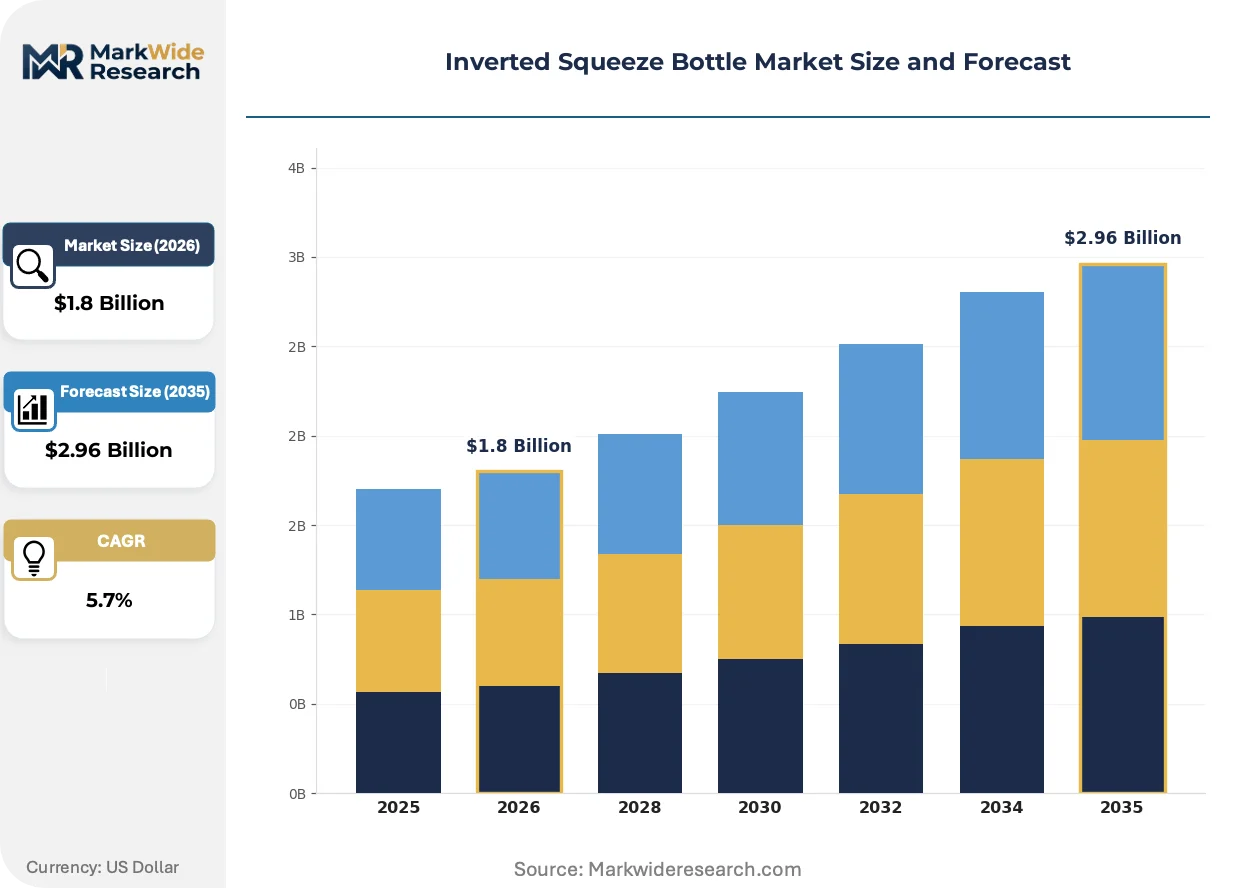
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Silicone End User: Household, Industrial, Food Service, Personal Care Feature: Leak-Proof, Reusable, Easy-Clean, Ergonomic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Procter & Gamble, Unilever, Henkel, Amcor Limited, Berry Global Inc., Silgan Holdings Inc., Graham Packaging Company, Alpla Werke Alwin Lehner GmbH & Co KG, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inverted Squeeze Bottle Market Shifts & Advancements
Valve miniaturization, regulatory chemistry disclosure, and procurement model compression are restructuring how converters specify closures and how brands negotiate supply agreements.
Silicone valve diaphragm technology is miniaturizing. Precision-molded elastomer components now integrate sub-millimeter slit geometries that control viscosity-specific flow rates without mechanical springs. Infant care and premium skincare brands in South Korea and Japan adopt these specifications fastest. The technology is miniaturizing closure assemblies to sub-gram weights that reduce resin content per unit and enable thinner-wall bottle bodies without sacrificing seal integrity.
EU REACH substance-of-very-high-concern candidate list expansions now capture specific antioxidant stabilizers common in polyethylene regrind streams. Converter qualification protocols must document absence of these chemistries through supply-chain attestation rather than testing alone. European private-label sauce brands face the steepest reformulation costs, with several accelerating partnerships with resin compounders holding pre-approved additive packages.
Direct material pass-through contracting is displacing fixed-price annual agreements in North American food service supply. Large restaurant chains now index resin and freight components monthly, transferring volatility risk to blow-mold converters. This shift concentrates procurement leverage with buyers possessing commodity-hedging capabilities while squeezing margin visibility for mid-cap molders without resin trading desks. The practice is most advanced in United States quick-service restaurant condiment supply, with similar structures emerging in German retail private-label negotiations.
Inverted Squeeze Bottle Market Segmentation
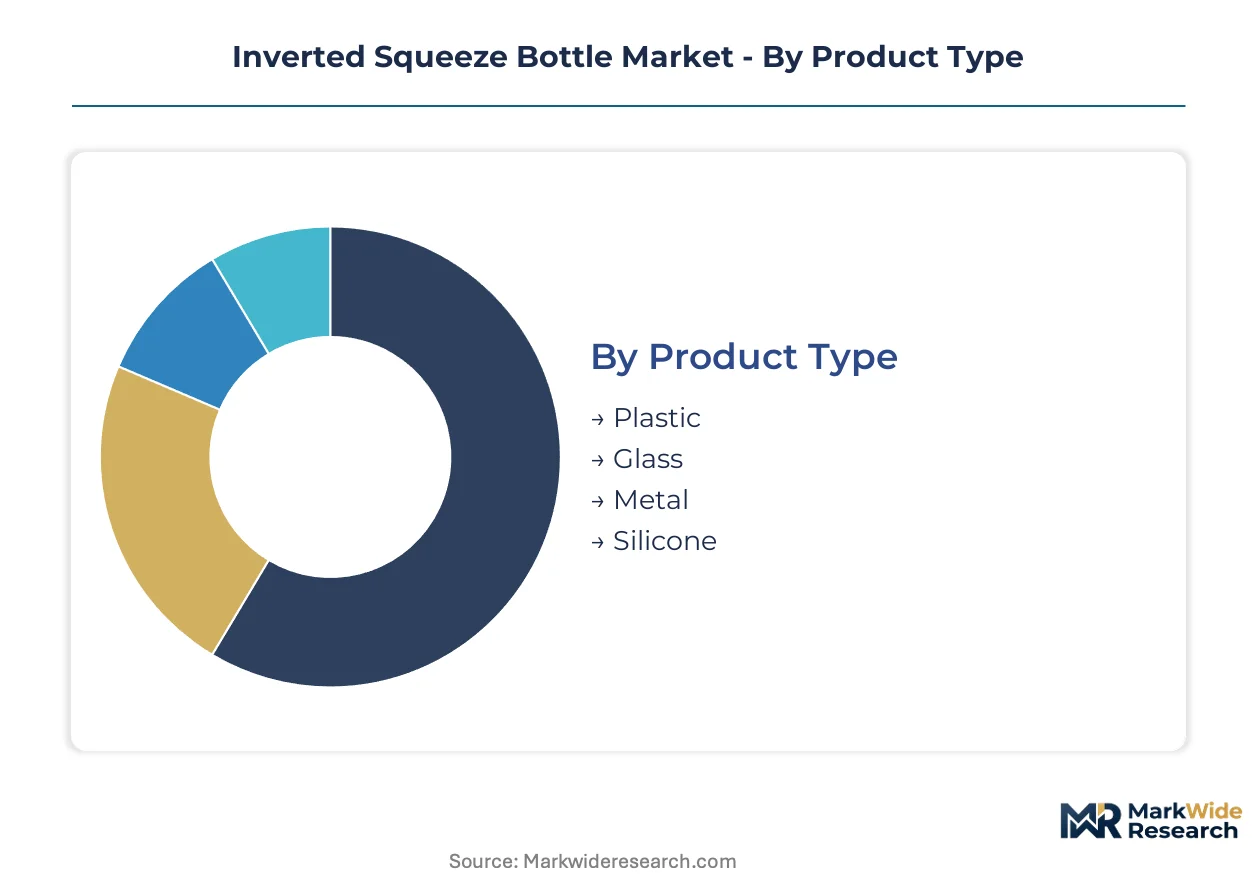
Segmentation in the inverted squeeze bottle market reveals how resin chemistry, end-use specifications, and channel economics partition value capture. Each dimension carries distinct regulatory exposure and margin architecture that shapes supplier positioning.
Product Type:
Plastic variants dominate domestic production across the United States, Germany, and China due to established blow-molding infrastructure and resin compounding proximity. Silicone and glass segments rely more heavily on export-led demand from premium skincare and infant-care brands in Japan and South Korea.
- Plastic:High-density polyethylene and polypropylene formulations fabricated through extrusion blow molding deliver cost efficiency at high cavitation. Demand concentrates in United States quick-service restaurant chains where portion control and shipment durability outweigh premium positioning. FDA food-contact notification requirements govern resin additive packages, extending qualification cycles for recycled-content grades.
- Silicone:Platinum-cured elastomer bodies withstand repeated sterilization cycles while maintaining valve seal integrity. Japanese and South Korean infant-care brands specify these for reusable feeding systems, absorbing premium pricing in exchange for durability and chemical inertness under GB standards and FDA migration thresholds.
- Glass:Borosilicate and soda-lime variants serve premium sauce and cosmetic applications requiring oxygen barrier performance and aesthetic clarity. European refill station networks in Germany and the Netherlands favor standardized neck finishes for bulk dispensing compatibility.
- Metal:Aluminum and stainless steel bodies target industrial cleaning agents and high-viscosity adhesives requiring puncture resistance. Applications cluster in German automotive aftermarket and United States manufacturing maintenance supply.
Plastic commands the established base. The steepest expansion runs through silicone.
End User:
Cost-tier differentiation separates commodity condiment supply from specification-intensive personal care and infant-care segments, with food service operators occupying the volume midpoint.
- Food Service:Gravity-fed valve systems reduce portion waste and accelerate throughput during peak hours. United States quick-service restaurant chains index resin and freight costs monthly, transferring volatility risk to converters without commodity-hedging capabilities.
- Personal Care:Precision-molded elastomer valves with sub-millimeter slit geometries control viscosity-specific flow rates for lotions and serums. South Korean and Japanese brands lead adoption of miniaturized closure assemblies that reduce resin content per unit.
- Household:Standard polyethylene bottles with flip-top or twist closures serve mass-market cleaning agents and condiments. Private-label retail concentration in Germany and the United States drives specification standardization around neck-finish interoperability.
- Industrial:High-density formulations withstand chemical compatibility requirements for solvents, adhesives, and lubricants. German automotive and United States manufacturing sectors specify UN-rated packaging for hazardous material transport compliance.
Food service anchors volume throughput. Personal care generates the highest margin per unit.
Feature:
Application-specific requirements determine which features command premium pricing versus baseline inclusion, with e-commerce shipment integrity reshaping investment priorities.
- Leak-Proof:Silicone valve diaphragms and precision-molded polypropylene dispensing tips prevent shipment damage in direct-to-consumer channels. Closure-component production clusters in southeastern China, exposing brands to port congestion and tariff exposure.
- Reusable:Durable silicone bodies with standardized neck finishes enable refill station compatibility in German and Dutch retail formats. EU single-use plastic directives accelerate specification windows for compliant designs.
- Easy-Clean:Wide-mouth geometries and dishwasher-safe materials reduce bacterial harboring in household and infant-care applications. FSSAI packaging compliance requirements in India create specification opportunities for imported technical designs.
- Ergonomic:Contoured body profiles and non-slip surface treatments target aging demographics and accessibility requirements in Japanese and European markets. Premium skincare brands absorb higher per-unit costs for differentiated tactile experience.
Leak-proof engineering captures the steepest investment trajectory. Reusable designs gain regulatory tailwinds.
Distribution Channel:
Volume concentration varies by customer scale and specification complexity, with direct procurement consolidating leverage among large operators.
- Distributors:Industrial and food service supply flows through specialized packaging distributors holding regional inventory positions. German and United States networks maintain technical specification expertise for valve and closure matching.
- Online Retail:Direct-to-consumer sauce and personal care brands absorb damage-rate penalties from logistics providers, driving leak-proof closure investment intensity. Amazon and specialized platform fulfillment requirements shape packaging specifications.
- Supermarkets:Private-label condiment and cleaning product specifications standardize around high-cavitation blow-molded polyethylene with flip-top closures. California and New York recycled-content mandates influence supplier qualification.
- Specialty Stores:Premium skincare and infant-care boutiques specify silicone and glass variants with miniaturized valve assemblies. South Korean and Japanese retail formats lead premium positioning and technical specification density.
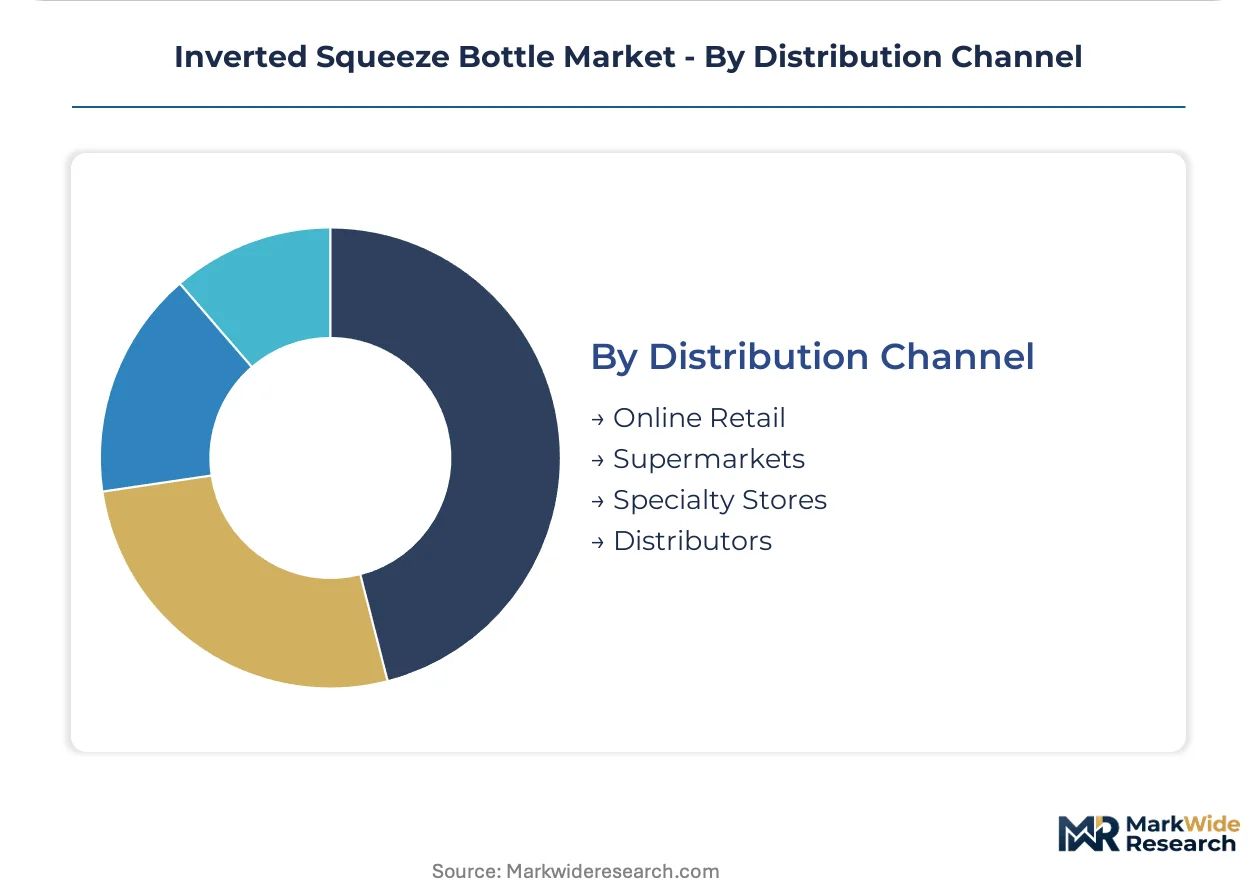
Distributors maintain the broadest geographic coverage. Online retail channels expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply by geography. United States quick-service restaurant chains absorb resin-price volatility through indexed contracts, while Japanese infant-care brands prioritize silicone durability over cost minimization.
United States
Quick-service restaurant condiment dispensing drives volume throughput. FDA food-contact notification requirements govern resin additive packages for domestic blow-molding supply. Southeastern converter clusters around Atlanta and Charlotte expand high-cavitation capacity for national chain specifications.
Germany
Refill station retail formats in Berlin and Hamburg pull durable silicone-body designs with standardized neck finishes. EU Packaging and Packaging Waste Regulation mandates accelerate post-consumer recycled polyethylene qualification. Bavarian resin compounders hold pre-approved additive packages for private-label sauce brands.
China
Closure-component manufacturing concentrates around Shenzhen and Dongguan for silicone valve diaphragms. SAMR enforces GB standards restricting specific plasticizers in food-contact materials. Yangtze River Delta blow-molding equipment suppliers scale technical partnerships for Indian market entry.
Japan
Premium skincare and infant-care brands in Tokyo and Osaka specify miniaturized elastomer valves with sub-millimeter slit geometries. METI guidelines shape chemical disclosure requirements for imported packaging materials. Kansai region specialty retailers drive premium positioning for reusable silicone systems.
India
FSSAI packaging compliance requirements for domestic sauce brands create specification windows for imported technical designs. Maharashtra and Gujarat food-processing corridors expand molded-plastic packaging capacity for condiment manufacturers. Mumbai-based distributors hold regional inventory positions for valve and closure matching expertise.
Inverted Squeeze Bottle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the inverted squeeze bottle supply base. The market structures around three tiers: integrated multinational packaging groups with resin-to-film capabilities, regional blow-molding specialists serving branded consumer goods accounts, and niche silicone fabricators targeting premium reusable applications. Consolidation pressure runs highest among mid-cap converters lacking commodity-hedging infrastructure or captive resin supply. Dominant competitive moves include backward integration into resin compounding and geographic expansion through technical closure partnerships in emerging food-processing corridors.
Among integrated packaging groups, Amcor Limited and Berry Global Inc. exemplify scale-driven archetypes with multi-continent production networks. Silgan Holdings Inc. occupies a position within the rigid packaging specialization tier, serving food and personal care multinationals through dedicated manufacturing relationships. These three entities collectively represent the competitive core against which regional specialists and niche silicone fabricators calibrate positioning.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel |
| Amcor Limited |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Graham Packaging Company |
| Alpla Werke Alwin Lehner GmbH & Co KG |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
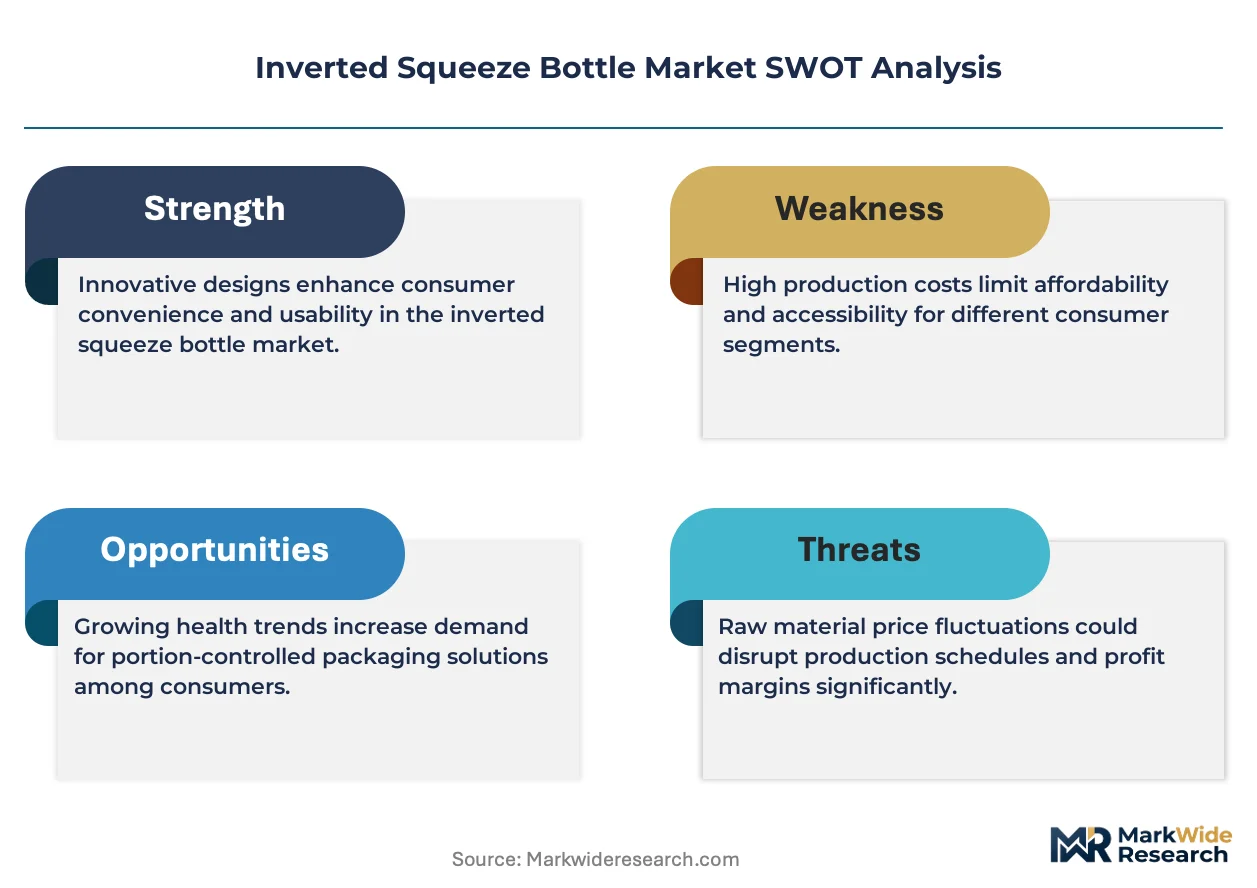
Monthly resin-indexed contracting for United States quick-service restaurant chains locks in supply access while transferring polyethylene and freight volatility risk to blow-mold converters lacking commodity-hedging infrastructure. This structure compresses margin visibility for mid-cap molders while rewarding integrated packaging groups with captive resin compounding and trading desks.
Pricing Analysis
After-sales closure replacement revenue drives lifetime value in food-contact applications where valve diaphragm wear necessitates periodic refresh cycles. Three-tier pricing structure across premium silicone, standard polyethylene, and economy polypropylene tiers separates infant-care brands from quick-service operators from private-label household segments. Cost compression in standard polyethylene runs through direct material pass-through clauses that strip converters of buffer margin. Quick-service restaurant procurement teams exhibit highest price sensitivity, while Japanese skincare brands absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Shenzhen-Dongguan closure-component manufacturing clusters concentrate silicone valve diaphragm and precision-molded polypropylene dispensing tip production, exposing brands to port congestion and tariff exposure. Blow-molding equipment draws from German and Chinese suppliers, while resin compounders anchor in United States Gulf Coast and Bavarian chemical corridors. Single-source vulnerability concentrates in southeastern Chinese precision molding for sub-millimeter slit geometries. Distribution runs through specialized packaging distributors holding regional inventory positions in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as EU single-use plastic directives and California recycled-content mandates accelerate specification windows for compliant designs ahead of mainstream converter requalification cycles.
For Market Incumbents: Compound defensive positioning through backward integration into resin compounding with pre-approved additive packages and capacity expansion in high-cavitation blow-molding around Atlanta and Charlotte to serve national quick-service chain specifications. Silicone valve miniaturization R&D and FDA food-contact notification expertise represent critical levers against emerging regional specialists. For New Entrants and Emerging Players: FDA food-contact notification fast-track partnerships with established resin compounders enable specification entry ahead of full qualification timelines. White-space targets concentrate in Indian FSSAI-compliant technical designs for domestic sauce brands and German refill station durable silicone systems with standardized neck finishes. Direct technical closure partnerships with Maharashtra food-processing corridors offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Regional blow-molding specialists with captive high-cavitation mold capacity and established quick-service restaurant relationships present acquisition target archetypes with embedded customer lock-in. Long-term viability hinges on converter positioning within resin-to-closure integration pathways. The signal to watch is state-level recycled-content mandate acceleration ahead of federal timelines, which would revalue compliant resin inventories and preferred supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of FDA pre-approved additive packages accelerates food-contact qualification cycles for recycled-content grades. |
| High-Cavitation Mold Capacity Expansion | Atlanta and Charlotte regional clusters position converters for national quick-service restaurant chain specifications. |
| Silicone Valve Miniaturization R&D | Sub-millimeter slit geometries enable thinner-wall bottle bodies while maintaining seal integrity for premium skincare brands. |
| Technical Closure Partnerships in India | FSSAI compliance expertise creates specification windows for imported blow-molding equipment in Maharashtra food-processing corridors. |
| Refill Station Format Compatibility | Standardized neck finishes for durable silicone bodies align with EU single-use plastic directive compliance requirements in German retail. |
Research Methodology
The analysis maps plastic, silicone, glass, and metal sub-sectors, each validated through blow-molding plant managers, resin procurement leads at consumer goods manufacturers, technical closure engineers, and food service supply chain directors. Primary interview findings triangulate against customs trade data, FDA food-contact notification filings, EU Packaging and Packaging Waste Regulation implementation reports, and SEC 10-K disclosures from integrated packaging groups. Bottom-up capacity modeling and top-down demand estimation cross-validate volume outputs across the analysis window.
Consistency checks against external benchmarks validate projection outputs against historical resin price elasticity patterns and regulatory implementation timelines. The analytical framework segments by material chemistry, end-use application, closure feature specification, and distribution channel across the modeling period. CAGRs derive from installed capacity expansion schedules, recycled-content mandate compliance trajectories, and e-commerce shipment damage rate trends that reshape closure investment intensity.
Decision-makers should treat outputs as directional under stable regulatory implementation timelines and resin feedstock cost assumptions; material deviation in EU directive enforcement or polyethylene price volatility would warrant model refresh. Practitioners should keep alternative scenarios live as California and New York state-level mandate acceleration and Indian FSSAI technical specification evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Dosage Cups Market
Packaging Containers
VCI Bags Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Airless Bottles Market