
 Liquid Pouch Packaging Market | 2026-2036
Liquid Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Pouch Packaging Market Analysis
Asian flexible packaging capacity is shifting toward aseptic and high-barrier liquid pouch lines. Amcor Plc leverages its integrated film-to-pouch manufacturing network across Southeast Asia. Huhtamaki Oyj anchors European dairy pouch supply through specialized extrusion and printing assets. Tetra Laval International SA competes by extending its aseptic carton expertise into spouted pouch formats for ambient beverages.
Liquid pouch packaging comprises flexible laminated structures, typically 80-200 microns thick, engineered to contain liquids under pressure, thermal processing, or extended shelf-life conditions. These pouches employ multi-layer coextrusion or adhesive lamination to achieve oxygen transmission rates below 0.1 cc/m²/day for sensitive products like retort soups and infant formula. Stand-up pouches with spouted closures command premium positioning in food and beverage applications due to convenience and dispensing functionality. Flat pouches and sachets dominate single-serve personal care and household product segments where cost minimization shapes procurement decisions. Aluminum foil composites retain share in pharmaceutical and high-acid food applications despite recyclability pressures driving polyethylene and polypropylene mono-material development.
FDA food contact substance notifications govern barrier layer approvals in the United States, while EU REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant pouch coatings. EFSA migration limits for mineral oils from recycled paperboard secondary packaging indirectly shape laminate specifications for sensitive liquid contents. China's GB standards for food packaging materials, administered by SAMR, mandate specific heavy metal and evaporation residue thresholds that influence export-oriented supplier qualification. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
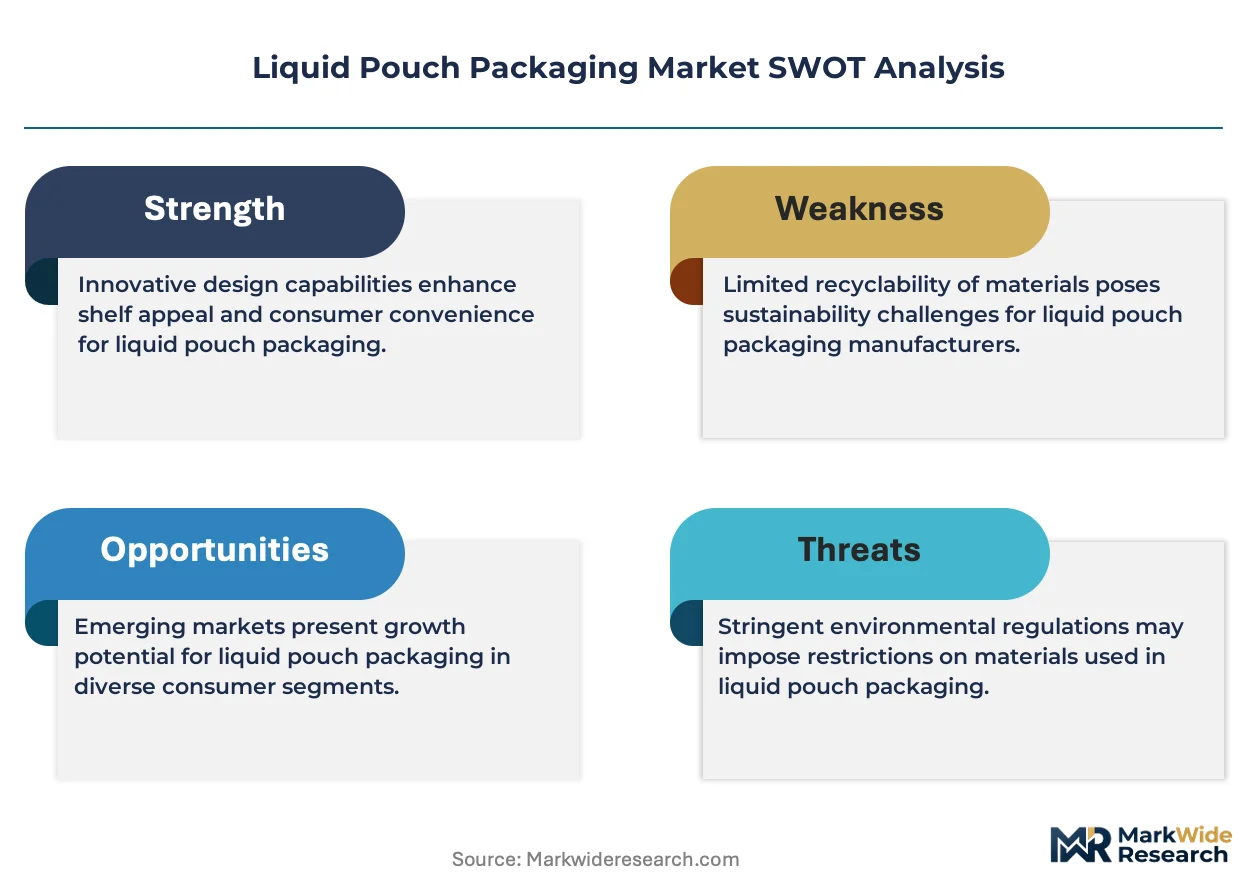
Mono-material polyethylene pouch structures are displacing multi-layer aluminum laminates as Extended Producer Responsibility schemes in Germany and France impose recyclability quotas on flexible packaging.
Growth Catalysts
- EU Green Deal packaging mandates:France's AGEC law requires 100% recyclable packaging by 2025, forcing dairy processors to adopt polyethylene mono-material pouches for yogurt and cream products.
- Aseptic spouted pouch technology:Beverage manufacturers in Thailand and Vietnam are retrofitting carton lines to produce ambient-stable fruit juice pouches with screw-cap dispensing.
- Retort pouch conversion:Japanese ready-meal producers are shifting from metal cans to laminated pouches for curry and soup products to reduce logistics costs and microwave preparation time.
Market Restraints
- Ethylene-vinyl alcohol supply concentration:Kuraray and Nippon Gohsei control over 70% of global high-barrier EVOH resin capacity, creating input cost volatility for oxygen-sensitive liquid pouches.
- Mechanical recycling contamination limits:Multi-layer structures containing aluminum foil or adhesive tie-layers fail European RecyClass certification, blocking circular economy claims.
- Glass bottle substitution resilience:Premium olive oil and wine vinegar segments in Italy and Spain retain glass packaging for perceived quality differentiation, limiting pouch penetration.
Strategic Opportunities
- Indonesia's dairy expansion:Domestic UHT milk consumption is rising 12% annually, yet pouch packaging penetration remains below 15% compared to 60% in Thailand.
- Pharmaceutical unit-dose liquids:Oral vaccine and diagnostic reagent manufacturers seek sterile, tamper-evident pouch formats for tropical disease programs in sub-Saharan Africa.
- Digital printing integration:HP Indigo and Xeikon systems enable run-length flexibility for seasonal beverage promotions, compressing minimum order quantities from 500,000 to 10,000 units.
Industry Challenges
- Barrier engineer scarcity:Formulation chemists capable of matching 0.1 cc/m²/day oxygen transmission rates in mono-material structures command salary premiums exceeding 40% in the European flexible packaging sector.
- Retort validation timelines:Achieving FDA food contact notification approval for new adhesive systems requires 18-24 month migration studies, delaying product launches.
- Legacy filling equipment incompatibility:Converting rigid bottling lines to pouch handling requires robotic pick-place systems and modified sterilization tunnels, complicating brownfield investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Pouch Packaging Market |
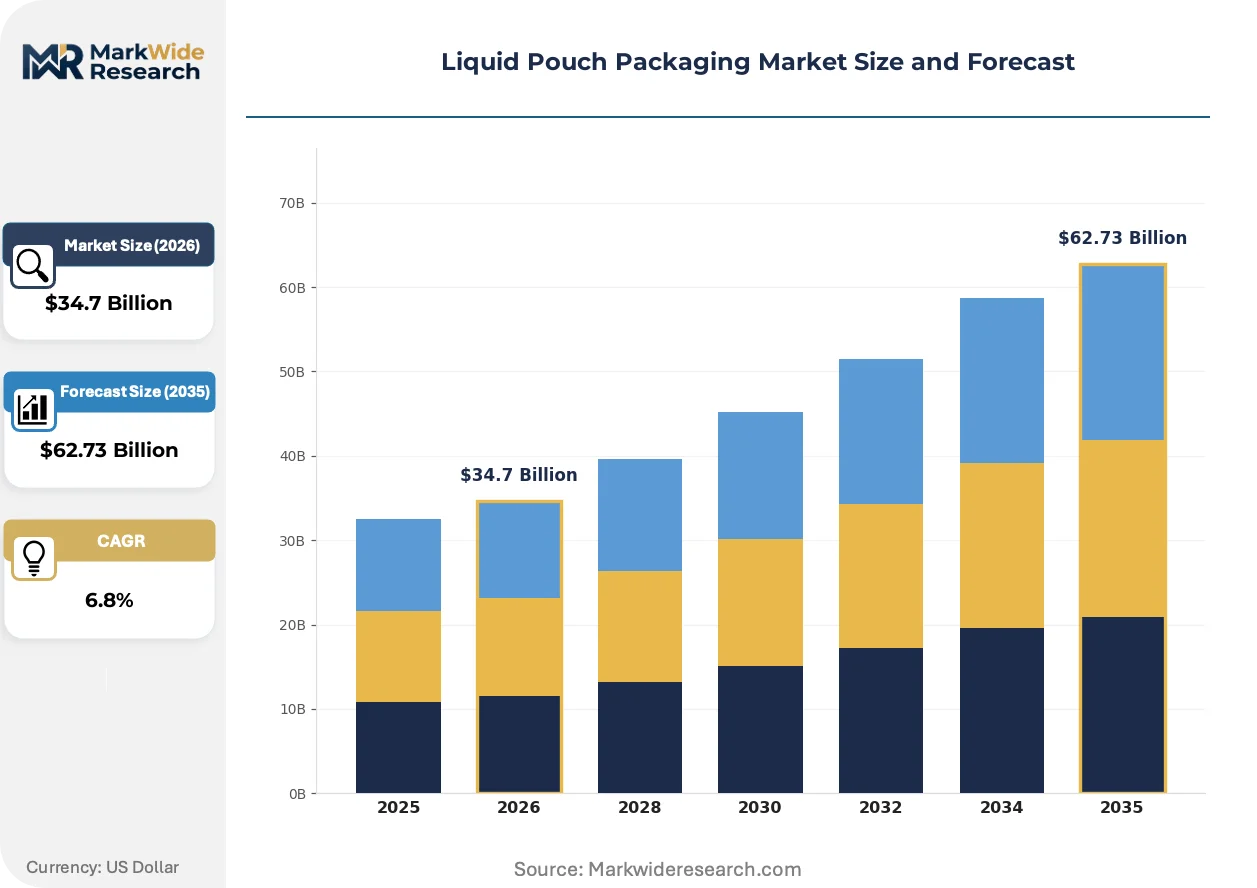
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Spouted Pouches, Sachets Material: Polyethylene, Polypropylene, Aluminum Foil, Composites End User: Food & Beverage, Personal Care, Healthcare, Household Products Closure Type: Zip Lock, Screw Cap, Spout, Heat Seal |
| Companies Covered | Amcor Plc, Huhtamaki Oyj, Tetra Laval International SA, Evergreen Packaging LLC, Sealed Air Corporation, SIG Global Pte. Ltd, Mondi PLC, Greatview Aseptic Packaging Co. Ltd, Elopak AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Pouch Packaging Market Emerging Trajectories
Digital manufacturing and regulatory chemistry are converging to restructure how liquid pouch specifications are developed, validated, and deployed across food, beverage, and pharmaceutical supply chains.
High-speed digital printing with water-based inks is modularizing short-run production economics for seasonal beverage promotions and private-label launches. Brand owners in the United Kingdom and Netherlands are adopting 10,000-unit minimum orders for limited-edition smoothie and kombucha formats. This capability is compressing inventory carrying costs and enabling regional flavor localization previously uneconomical with rotogravure cylinders.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant pouch coatings for cooking sauces and edible oils. ECHA's 2023 proposal to classify all PFAS as substances of very high concern triggers substitution mandates across European converter operations. Laminate suppliers are responding with silicon dioxide and clay-based barrier coatings, though these require slower line speeds and modified heat-seal parameters.
Direct-store-delivery networks for fresh chilled soups and probiotic drinks are consolidating procurement decisions at regional dairy cooperative level. German and Polish retailers are mandating shelf-ready secondary packaging with pre-applied barcode labeling, displacing traditional corrugated shippers. This concentration is forcing pouch converters to integrate case-packing automation and ERP data interchange capabilities previously handled by third-party logistics providers.
Liquid Pouch Packaging Market Segmentation
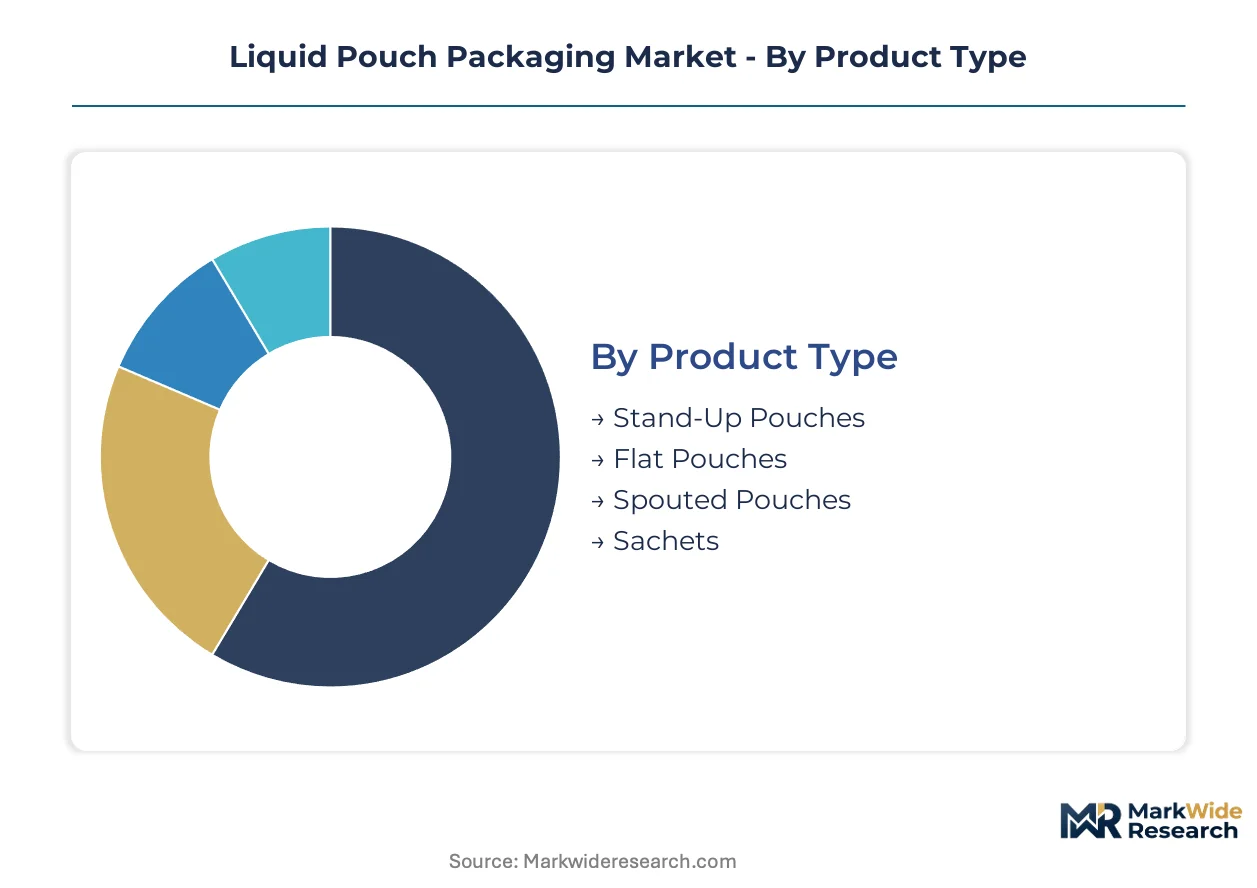
Liquid pouch packaging specifications diverge sharply across application requirements, with barrier performance and dispensing functionality driving format selection. Material composition and closure engineering determine compatibility with thermal processing, shelf-life extension, and consumer convenience expectations.
Product Type:
Equipment upgrade cycles and line conversion investments are pushing manufacturers toward formats that minimize retrofit costs while expanding product range flexibility.
- Stand-Up Pouches:These structures incorporate gusseted bottoms enabling vertical shelf display and enhanced brand visibility. Dairy processors in Germany and France are converting yogurt and cream lines to stand-up formats to meet AGEC law recyclability mandates. The format reduces secondary packaging requirements and optimizes retail shelf density.
- Spouted Pouches:Screw-cap or flip-top dispensing closures transform these pouches into replacements for rigid bottles in beverages and condiments. Thai and Vietnamese fruit juice producers are retrofitting aseptic carton lines to produce ambient-stable spouted pouches with controlled flow characteristics. Child-resistant and tamper-evident closure options expand pharmaceutical applications.
- Flat Pouches:Two-dimensional sealed-edge structures dominate single-serve condiments and sample sachets where minimizing unit cost outweighs dispensing convenience. Heat-seal or tear-notch openings predominate.
- Sachets:Ultra-thin laminates, typically 60-100 microns, serve personal care samples and instant beverage powders. High-speed form-fill-seal compatibility drives specification standardization.
Volume placements concentrate in stand-up pouches; the faster expansion belongs to spouted pouches.
Material:
Cost tier positioning separates commodity films from engineered barrier structures, with regulatory compliance costs reshaping procurement priorities.
- Polyethylene:Mono-material PE structures are displacing multi-layer laminates as Extended Producer Responsibility schemes impose recyclability quotas. Linear low-density polyethylene dominates dairy and beverage applications requiring cold-chain flexibility.
- Polypropylene:Cast and oriented PP films provide clarity and stiffness for retort applications. Japanese ready-meal producers specify PP-based laminates for curry and soup pouches replacing metal cans.
- Aluminum Foil:Ultra-high barrier metalized layers achieve oxygen transmission rates below 0.01 cc/m²/day for infant formula and pharmaceutical liquids. Recyclability limitations are forcing substitution in European consumer goods.
- Composites:Multi-layer coextrusion or adhesive lamination combines EVOH, nylon, and polyolefins to balance barrier, sealability, and cost. REACH restrictions on PFAS grease-resistant coatings are triggering reformulation toward silicon dioxide alternatives.
Polyethylene captures the highest placement volumes; aluminum foil faces steepest substitution pressure despite superior barrier performance.
End User:
Application-specific performance requirements create distinct specification clusters, with food safety compliance separating qualified suppliers from commodity converters.
- Food & Beverage:Retort, aseptic, and high-pressure processing compatibility demands validated adhesive systems and migration-tested barrier layers. FDA food contact notifications and EFSA migration limits govern laminate specifications.
- Healthcare:Sterile fill-finish operations and tamper-evident integrity requirements dominate oral vaccine and diagnostic reagent packaging. Unit-dose formats for tropical disease programs in sub-Saharan Africa represent emerging demand.
- Personal Care:Chemical resistance to surfactants and solvents shapes material selection, with sachet formats prevailing in travel-size and sample applications.
- Household Products:Cost minimization drives flat pouch and spouted formats for detergents and cleaning agents, with refill applications gaining traction.
Food and beverage commands the dominant placement volume; healthcare applications are climbing the fastest as pharmaceutical unit-dose formats expand.
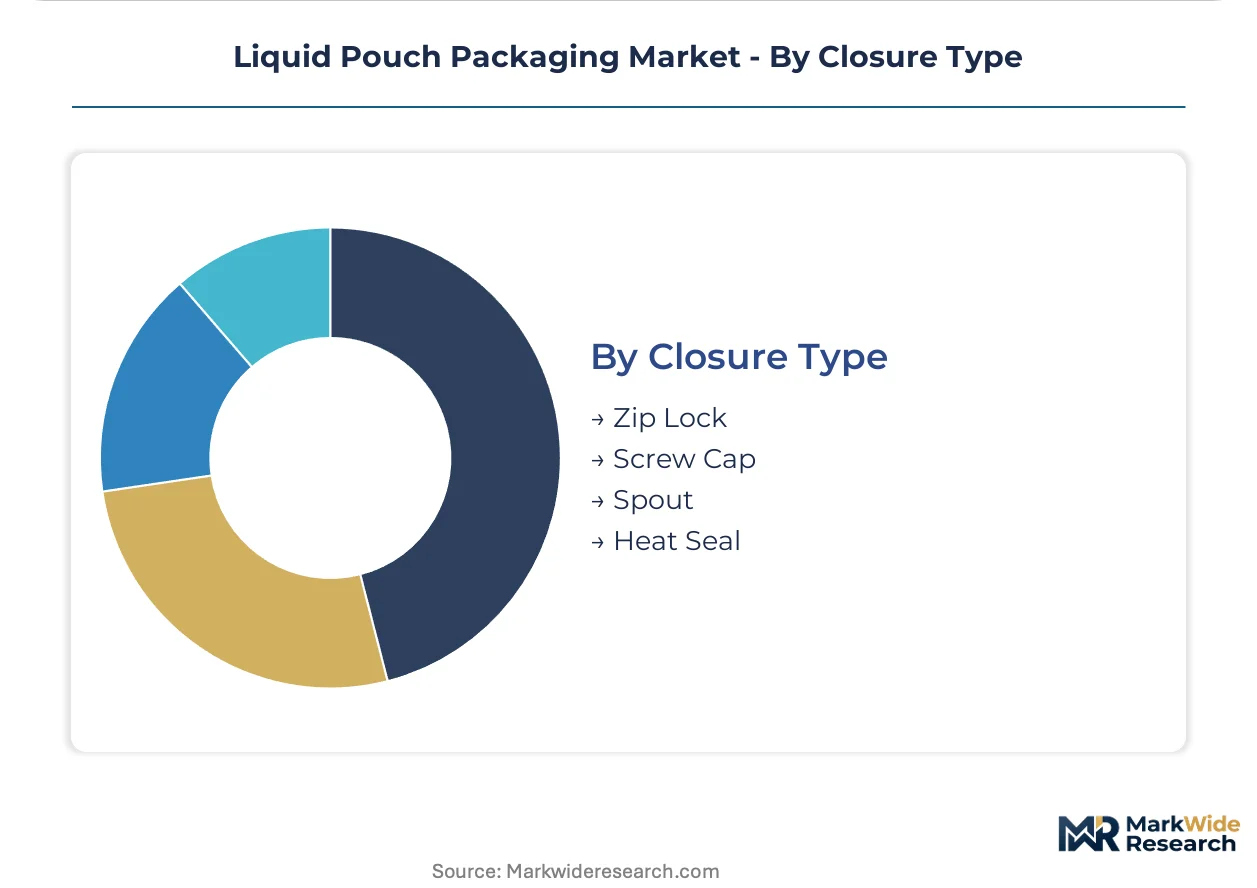
Closure Type:
Consumer convenience expectations and line speed economics create divergent engineering priorities across installation bases.
- Screw Cap:Injection-molded polypropylene closures with induction seals provide resealability and tamper evidence for beverages and condiments. German retailers mandate shelf-ready secondary packaging with pre-applied barcode labeling compatible with screw-cap handling.
- Spout:Integrated fitment welding requires specialized ultrasonic or heat-seal equipment. Aseptic spouted pouch technology enables ambient distribution of sensitive liquids.
- Zip Lock:Press-to-close interlocking profiles serve multi-serve food applications requiring repeated access. Slider mechanisms add cost for premium positioning.
- Heat Seal:Peelable or permanent seal layers optimize for either consumer convenience or child resistance. Retort applications require seal integrity validation through thermal cycling.
Heat seal dominates current placements; screw cap configurations are gaining share fastest as beverage producers convert from rigid bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene-vinyl alcohol resin production concentrates in Japan and Germany, anchoring high-barrier film supply chains that feed liquid pouch converters across three continents. Regional demand patterns diverge sharply between mature recycling infrastructures and emerging dairy markets.
China
Dairy and beverage producers in Hebei and Inner Mongolia are converting rigid bottle lines to flexible pouches for UHT milk distribution. SAMR's GB standards for food packaging materials mandate specific heavy metal thresholds that shape export-oriented supplier qualification. Shanghai and Guangzhou host the densest clusters of aseptic pouch converting capacity serving domestic brands.
Germany
Dairy processors face AGEC law mandates requiring fully recyclable packaging by 2025, accelerating polyethylene mono-material adoption for yogurt and cream. ECHA's REACH restrictions on PFAS substances force reformulation of grease-resistant coatings. The North Rhine-Westphalia corridor anchors European flexible packaging R&D for barrier layer engineering.
United States
Ready-to-drink beverage brands in California and Texas are expanding spouted pouch formats for functional drinks and condiments. FDA food contact substance notifications govern barrier layer approvals, creating 18-24 month validation timelines for new adhesive systems. Midwest dairy cooperatives are consolidating procurement decisions at regional level.
Japan
Ready-meal producers in Kanto and Kansai regions are shifting curry and soup production from metal cans to retort pouches. Kuraray and Nippon Gohsei control over 70 percent of global EVOH resin capacity, creating input cost volatility for oxygen-sensitive applications. Osaka-based converters specialize in ultra-high barrier laminates for infant formula.
Thailand
Fruit juice manufacturers in Bangkok and Rayong are retrofitting aseptic carton lines to produce ambient-stable spouted pouches. Domestic UHT milk pouch penetration exceeds 60 percent, creating reference specifications for neighboring markets. Chonburi province hosts Southeast Asia's densest concentration of high-barrier film extrusion assets.
Liquid Pouch Packaging Market Vendor Landscape
Global majors compete with regional champions across integrated film-to-pouch manufacturing networks. Market structure tilts toward consolidation at the barrier film level while converting remains fragmented across specialized equipment configurations. Three archetypes dominate: integrated resin-to-pouch conglomerates, specialized aseptic technology licensors, and regional dairy packaging specialists. Competitive moves center on backward integration into resin compounding and strategic partnerships with filling equipment OEMs.
Among integrated packaging conglomerates, Amcor Plc and Huhtamaki Oyj occupy positions that exemplify geographic specialization strategies—Australian-originated Amcor leveraging Southeast Asian film assets, Finnish-structured Huhtamaki anchoring European dairy supply through extrusion and printing capabilities. Tetra Laval International SA represents the aseptic technology archetype, extending carton expertise into spouted pouch formats. These three entities illustrate how scale, regional density, and processing technology differentiate competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Amcor Plc |
| Huhtamaki Oyj |
| Tetra Laval International SA |
| Evergreen Packaging LLC |
| Sealed Air Corporation |
| SIG Global Pte. Ltd |
| Mondi PLC |
| Greatview Aseptic Packaging Co. Ltd |
| Elopak AS |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging mandates and France's AGEC law recyclability requirements gate qualified supply access, reserving premium-tier pricing for converters with validated mono-material polyethylene structures and RecyClass certification. Buyers without compliant supplier relationships face stranded inventory risk and 18-24 month reformulation delays that compress their negotiating position.
Pricing Analysis
Warranty and validation service bundling separates pricing tiers, with FDA food contact notification support and migration study documentation commanding 15-25% premiums over unbundled film supply. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance certification and aseptic line compatibility. Price differentiation hinges on EVOH layer specification and retort validation status. Cost compression in standard-tier laminates is intensifying because German dairy cooperatives are consolidating procurement at regional level. Private-label beverage brands exhibit highest price sensitivity; pharmaceutical unit-dose programs show lowest sensitivity due to sterile fill-finish requirements.
Supply Chain Analysis
EVOH resin supply rests on Japanese and German specialty chemical producers, with Kuraray and Nippon Gohsei anchoring global high-barrier feedstock. Raw material dependencies center on ethylene-vinyl alcohol copolymers, linear low-density polyethylene, and silicon dioxide barrier coatings. Single-source vulnerability concentrates in oxygen-sensitive laminate formulations where alternative barrier technologies require modified heat-seal parameters and slower line speeds. Distribution runs through integrated film-to-pouch manufacturing networks across Southeast Asia and the North Rhine-Westphalia corridor, with regional dairy cooperatives in Germany and Poland consolidating direct-store-delivery procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH restrictions on per- and polyfluoroalkyl substances function as a cost-of-compliance moat, elevating barrier engineer scarcity and 18-24 month FDA validation timelines into structural barriers that protect qualified incumbents from commodity competition.
For Market Incumbents: Cement market position by acquiring specialized extrusion assets in the North Rhine-Westphalia corridor to capture German dairy cooperative consolidation. Deepen upstream control over EVOH compounding relationships to defend against Kuraray and Nippon Gohsei supply volatility. Invest in digital printing integration with HP Indigo or Xeikon systems to compress minimum order quantities and capture seasonal beverage promotion volumes from rigid bottle converters.
For New Entrants and Emerging Players: Begin with Indonesia's dairy expansion, where UHT milk pouch penetration remains below 15% against Thailand's 60% reference benchmark. Target pharmaceutical unit-dose formats for tropical disease programs in sub-Saharan Africa, where sterile tamper-evident pouch demand outpaces qualified supply. Pursue co-manufacturing partnerships with established aseptic converters to bypass 18-24 month FDA validation barriers.
For Investors and Strategic Acquirers: ECHA's proposal to classify all PFAS as substances of very high concern is the leading indicator that silicon dioxide and clay-based barrier coating capabilities will command acquisition premiums. The 5-10 year viability window favors converters with validated mono-material structures and integrated film-to-pouch manufacturing networks. Target acquisition candidates with RecyClass certification and established relationships with German dairy cooperatives. Watch for FDA food contact notification approvals for new adhesive systems as inflection signals for product launch pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Compounding | Captive supply of high-barrier resin reduces exposure to Kuraray and Nippon Gohsei pricing volatility. |
| Aseptic Spouted Pouch Line Retrofit | Thai and Vietnamese fruit juice producers seek ambient-stable formats with screw-cap dispensing functionality. |
| Digital Printing System Deployment | HP Indigo and Xeikon integration enables 10,000-unit minimum orders for seasonal beverage promotions. |
| RecyClass Certification Investment | Validated mono-material structures unlock German and French dairy procurement under AGEC law mandates. |
| Barrier Engineer Talent Acquisition | Formulation chemists capable of 0.1 cc/m²/day oxygen transmission rates command 40% salary premiums in Europe. |
Methodological Framework
Independent corroboration across primary interviews with flexible packaging plant managers, dairy procurement leads, barrier film R&D directors, and aseptic filling equipment OEMs underwrites the qualitative findings. Secondary validation draws from FDA food contact substance notification databases, ECHA REACH restriction proposals, RecyClass certification registries, and German dairy cooperative procurement disclosures. Bottom-up capacity assessments across Southeast Asian and European converting assets triangulate against top-down demand modeling from beverage and dairy processor expansion plans.
Historical reference periods spanning pre- and post-AGEC law implementation anchor the forecast window, with growth trajectory derivation calibrated to retrofit cycle timing for aseptic carton-to-pouch line conversions. Segmentation dimensions span product type, material composition, end-use application, and closure configuration, with regional regulatory cluster differentiation across EU REACH, FDA food contact, and China SAMR GB standard jurisdictions. Industry-specific inputs include EVOH resin capacity utilization rates and digital printing system installation trends.
Regulatory restriction acceleration, barrier raw material supply disruption, and aseptic validation timeline extension are the dominant revision risks. Forecasts embed assumptions regarding PFAS substitution pace and mono-material recyclability certification adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Self-Seal Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
Ziplock Products Market
Pouch
Foil Pouch Packaging Market
Pouch
Europe Pouch Packaging Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Recyclable PE Pouch Market
Pouch
Russia Pouch Packaging Market
Pouch
Retort Pouch Market
Pouch
Contour Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Utility Pouches Market
Pouch
Canada Pouch Packaging Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Dual-Chamber Pouches Market