
 Global Medical and Pharmaceutical Pouch Market | 2026-2036
Global Medical and Pharmaceutical Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical and Pharmaceutical Pouch Market Foresight
ISO 11607 compliance for sterile barrier systems is rotating the competitive landscape toward manufacturers with validated cleanroom operations and documented seal-strength protocols. ProAmpac leverages its multi-site North American footprint to sustain just-in-time supply contracts with large pharmaceutical distributors. Amcor Plc anchors global laminate film supply through backward integration into resin and substrate production.
Medical and pharmaceutical pouches are multi-layer flexible packages engineered from heat-sealable laminates—typically combining polyethylene, aluminum foil, and oriented polypropylene—to achieve oxygen transmission rates below 0.1 cc per square meter per day and maintain sterility assurance levels through distribution. Their primary purpose is to protect drugs, devices, and diagnostic components from moisture ingress, oxidation, and microbial contamination across shelf lives that often exceed 24 months. Blister pouches dominate unit-dose oral solid dosage formats where patient compliance and child-resistance requirements command premium laminate specifications. Barrier pouches represent the fastest-expanding product category as biologics and moisture-sensitive APIs proliferate across development pipelines.
FDA 21 CFR Part 211 and EU MDR impose validated seal-integrity testing and extractables-leachables documentation on all primary packaging materials, which elevates R&D costs but also locks out uncertified regional converters. The EPA and ECHA jointly scrutinize per- and polyfluoroalkyl substance content in barrier coatings, pushing material suppliers toward silicone-oxide and aluminum-oxide vapor-deposited alternatives. Stakeholders must monitor how FDA's evolving guidance on packaging suitability for complex generics reshapes qualification timelines and supplier switching costs.
Market Dynamics
The EU MDR transition is forcing pouch suppliers to revalidate sealing processes and migrate toward higher-barrier laminate constructions, compressing qualification timelines while elevating capital requirements for cleanroom infrastructure.
Growth Catalysts
- Biologics proliferation:Moisture-sensitive APIs and large-molecule drugs require oxygen transmission rates below 0.1 cc per square meter per day, pulling demand toward aluminum-oxide vapor-deposited barrier films.
- FDA 21 CFR Part 211:Validated seal-integrity testing mandates lock out uncertified regional converters, consolidating procurement toward ISO 11607-compliant manufacturers with documented seal-strength protocols.
- Hospital pharmacy expansion:Outpatient clinics and acute-care facilities are expanding unit-dose dispensing programs, driving pre-sterilized pouch formats for immediate clinical use.
Market Restraints
- Resin supply concentration:Backward integration into polyethylene and oriented polypropylene substrates limits supplier switching options when feedstock volatility strikes.
- ECHA PFAS scrutiny:Per- and polyfluoroalkyl substance restrictions in barrier coatings force costly reformulation toward silicone-oxide alternatives before patent-protected processes mature.
- Extractables-leachables documentation:FDA and EMA requirements for primary packaging materials extend R&D cycles and elevate qualification costs for new laminate constructions.
Strategic Opportunities
- Complex generics packaging:FDA's evolving guidance on packaging suitability for complex generics creates first-mover advantage for suppliers with validated stability data.
- India contract manufacturing:CDSCO-aligned packaging demand from pharmaceutical exporters remains underpenetrated by ISO 11607-certified converters.
- Sustainable barrier coatings:EU Green Deal procurement preferences favor aluminum-oxide and bio-based sealant innovations that maintain sterility assurance levels.
Industry Challenges
- Cleanroom operator scarcity:Validated aseptic processing technicians command wage premiums that compress margin structures for mid-cap converters.
- Multi-site audit coordination:Pharmaceutical distributors now require simultaneous ISO 11607 compliance across all manufacturing locations, straining quality management systems.
- Legacy heat-sealer retrofit:Existing equipment requires programmable logic controller upgrades to meet EU MDR traceability requirements for seal-parameter documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical and Pharmaceutical Pouch Market |
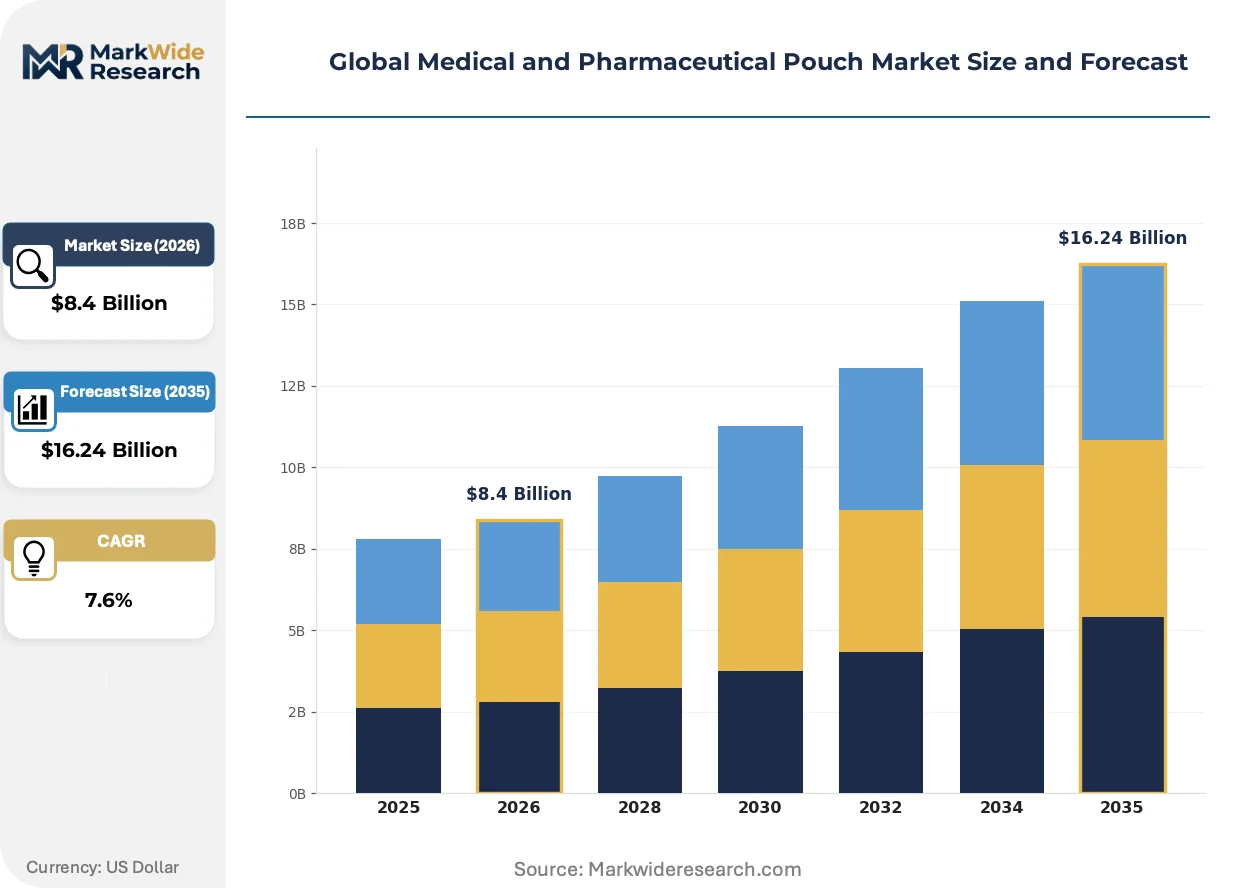
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Pouches, Sterile Pouches, Vacuum Pouches, Foil Pouches, Barrier Pouches Application: Drug Packaging, Medical Device Packaging, Sample Kits, Diagnostic Packaging, Nutraceutical Sealing End User: Pharmaceutical Manufacturers, Contract Packaging Organizations, Research Institutes, Biotechnology Firms, Clinical Trial Entities Material: Laminated Films, Polyethylene, Polypropylene, Aluminum Foil, Paperboard |
| Companies Covered | ProAmpac, Amcor Plc, Oliver Healthcare Packaging, Nelipak Corporation, Glenroy, GFR Pharma, American FlexPack, Terrapack, Ampac Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical and Pharmaceutical Pouch Market Shifts & Advancements
Barrier pouch engineering is splitting along two paths: ultra-high-barrier laminates for biologics and simplified mono-material constructions for recyclability, with both trajectories demanding new validation protocols.
Aluminum-oxide vapor-deposited films are replacing fluoropolymer coatings in sterile barrier systems. German contract packaging organizations are adopting these films at accelerated pace to preempt ECHA restrictions. The technology is bifurcating the supplier base between vapor-deposition-capable manufacturers and conventional extrusion converters facing obsolescence.
REACH restrictions on perfluorinated compounds are eliminating legacy barrier coatings from European pharmaceutical supply chains. Industrial consequence includes forced migration to silicone-oxide sealants with unproven 24-month stability data. Sterile barrier pouch manufacturers serving EU distribution are responding by front-loading extractables-leachables studies to defend qualification timelines.
Unit-dose dispensing contracts now bundle pouch supply with serialization and aggregation services. Hospital pharmacies and outpatient clinics are displacing traditional wholesale purchasing through direct agreements with certified converters. Germany exhibits the most visible compression of distribution layers, with contract packaging organizations capturing procurement authority from regional distributors.
Global Medical and Pharmaceutical Pouch Market Segmentation
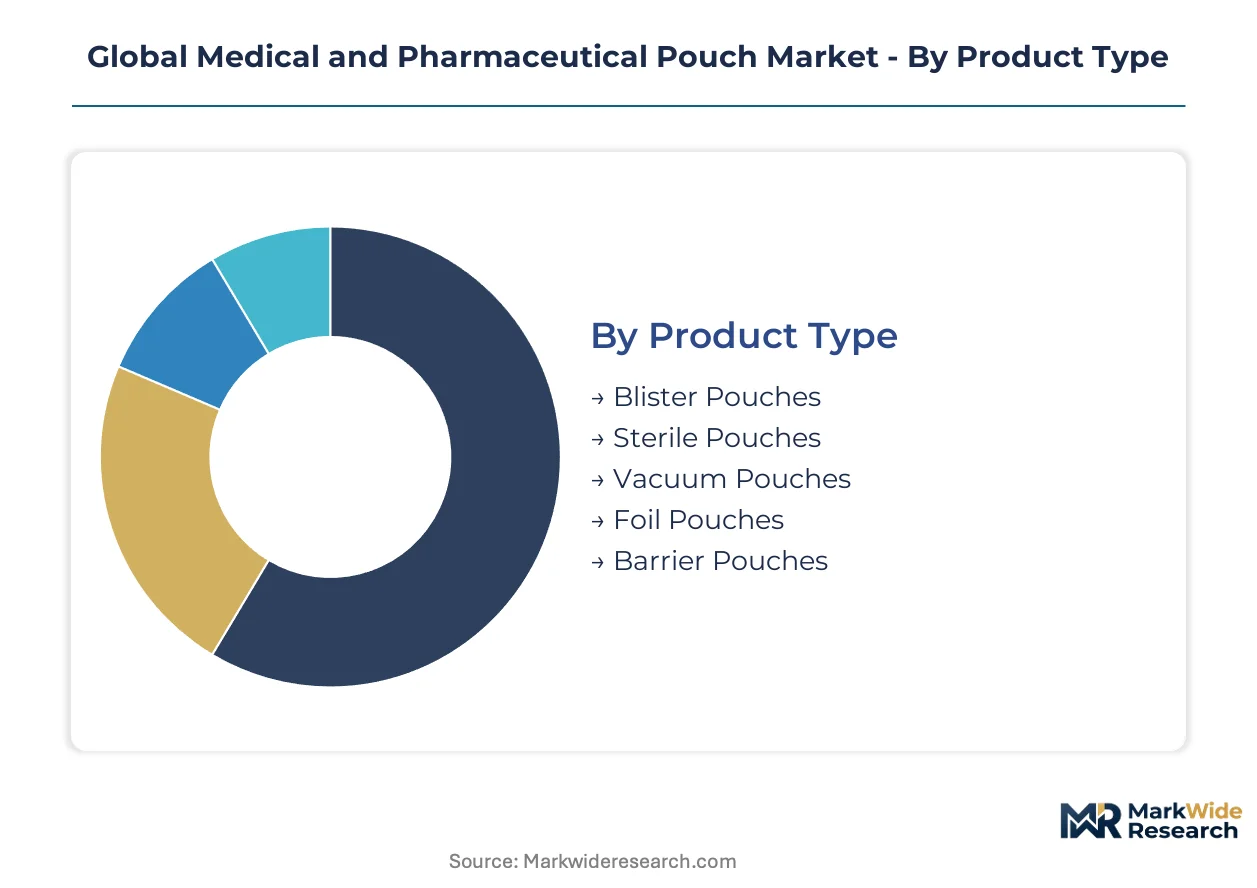
Segmentation in medical and pharmaceutical pouches separates margin capture from commodity supply. Laminate specification and sterility assurance level determine which converters command premium pricing versus competing on throughput.
Product Type:
Barrier pouches and sterile pouches concentrate margin pools at the high end, while blister pouches anchor volume throughput for oral solid dosage formats.
- Barrier Pouches:Multi-layer aluminum-oxide vapor-deposited laminates achieve oxygen transmission rates below 0.1 cc per square meter per day. Biologics manufacturers in Germany and Switzerland are pulling capacity toward these specifications as moisture-sensitive APIs proliferate across development pipelines.
- Sterile Pouches:ISO 11607-compliant heat-sealable systems maintain sterility assurance levels through validated seal-strength protocols. Hospital pharmacies in the United States are expanding pre-sterilized formats for unit-dose dispensing, compressing qualification timelines for converters.
- Blister Pouches:Unit-dose formats for tablets and capsules where child-resistance specifications command premium laminate engineering.
- Vacuum Pouches:Gas-flushable formats for oxygen-sensitive diagnostic components requiring extended shelf stability.
- Foil Pouches:Aluminum-laminate constructions for light-blocking protection of photosensitive APIs.
Sterile pouches hold installed capacity. Barrier pouches are rotating up the share rankings.
Application:
Drug packaging dominates procurement volume, though diagnostic packaging is climbing fastest as point-of-care testing expands.
- Drug Packaging:Primary containment for oral solids, injectables, and biologics requiring extractables-leachables documentation under FDA 21 CFR Part 211. Contract packaging organizations in Germany serve as the primary procurement channel for European pharmaceutical distribution.
- Diagnostic Packaging:Moisture-barrier systems for reagent strips, assay cartridges, and molecular testing consumables. Outpatient clinics in the United States are displacing traditional wholesale purchasing through direct agreements with certified converters.
- Medical Device Packaging:Sterile barrier systems for implants, surgical instruments, and single-use devices.
- Sample Kits:Multi-compartment pouches for specimen collection and transport media.
- Nutraceutical Sealing:Extended shelf-life formats for probiotic and omega-3 formulations.
Drug packaging commands the revenue base. Diagnostic packaging is expanding most quickly.
End User:
Contract packaging organizations capture procurement authority from regional distributors, while biotechnology firms drive specification innovation.
- Contract Packaging Organizations:Integrated serialization and aggregation services bundled with pouch supply. German CPOs are compressing distribution layers and mandating simultaneous ISO 11607 compliance across all manufacturing locations.
- Biotechnology Firms:Custom barrier engineering for monoclonal antibodies and cell therapies with unproven 24-month stability data. These end users front-load extractables-leachables studies to defend qualification timelines.
- Pharmaceutical Manufacturers:Large-volume procurement with backward integration into resin and substrate production limiting supplier switching options.
- Research Institutes:Small-batch sterile formats for preclinical and early-phase materials.
- Clinical Trial Entities:Temperature-stable packaging for investigational products with global distribution requirements.
Pharmaceutical manufacturers retain volume leadership. Contract packaging organizations are gaining procurement authority fastest.
Material:
Laminated films concentrate value capture, while polyethylene and polypropylene anchor cost-competitive supply for high-throughput formats.
- Laminated Films:Engineered combinations of polyethylene, aluminum foil, and oriented polypropylene achieving specified barrier performance. ECHA restrictions on perfluorinated compounds are forcing migration toward silicone-oxide sealants.
- Aluminum Foil:Ultra-high-barrier substrate for oxygen and moisture exclusion in biologics containment. Vapor-deposition-capable manufacturers are bifurcating from conventional extrusion converters facing obsolescence.
- Polyethylene:Heat-sealable sealant layers with feedstock volatility constraining margin stability.
- Polypropylene:Oriented substrates for puncture resistance in device packaging applications.
- Paperboard:Sustainable secondary containment with limited barrier performance for dry solid dosage formats.
Laminated films hold technical leadership. Aluminum foil is climbing the specification ladder fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 211 and EU MDR compliance mandates are concentrating procurement toward ISO 11607-certified manufacturers in Germany and the United States. Hospital pharmacy expansion and biologics proliferation are pulling capacity toward validated cleanroom operations in Switzerland and India.
United States
Outpatient clinics are displacing traditional wholesale purchasing through direct agreements with certified converters. FDA 21 CFR Part 211 mandates validated seal-integrity testing and extractables-leachables documentation, locking out uncertified regional converters. The Greater Boston biotechnology corridor is pulling demand toward aluminum-oxide vapor-deposited barrier films for monoclonal antibody containment.
Germany
Contract packaging organizations serve as the primary procurement channel for European pharmaceutical distribution, compressing qualification timelines. EU MDR transition forces pouch suppliers to revalidate sealing processes and migrate toward higher-barrier laminate constructions. The Rhine-Ruhr industrial cluster anchors sterile barrier system manufacturing for hospital pharmacy unit-dose programs.
Switzerland
Biologics manufacturers require oxygen transmission rates below 0.1 cc per square meter per day, pulling capacity toward vapor-deposition-capable suppliers. Swissmedic regulations align with EU MDR for sterile barrier validation, elevating documentation requirements. The Basel pharmaceutical hub is front-loading extractables-leachables studies to defend qualification timelines for moisture-sensitive APIs.
India
CDSCO-aligned packaging demand from pharmaceutical exporters remains underpenetrated by ISO 11607-certified converters. The country's national pharmaceutical regulator is tightening primary packaging material standards for complex generics export qualification. The Maharashtra-Gujarat pharmaceutical manufacturing belt is attracting contract packaging investment for sterile pouch conversion capacity.
China
NMPA is aligning domestic sterile barrier standards with ISO 11607 for medical device export qualification. The Yangtze River Delta biopharmaceutical cluster is expanding aluminum-oxide vapor-deposition capacity to serve domestic biologics pipelines. Shanghai-based contract packaging organizations are bundling pouch supply with serialization services for hospital pharmacy direct procurement.
Global Medical and Pharmaceutical Pouch Market Competitive Landscape
Player mix skews toward integrated laminate film suppliers and specialized sterile barrier converters with validated cleanroom footprints. Consolidation pressure concentrates procurement authority toward manufacturers with multi-site ISO 11607 compliance and documented seal-strength protocols. Two strategic archetypes dominate: backward-integrated resin producers commanding substrate supply security, and mid-cap converters with programmable logic controller-upgraded heat-sealers meeting EU MDR traceability requirements. Competitive moves center on cleanroom capacity expansion and strategic partnerships for extractables-leachables documentation services.
Among North American packaging specialists, ProAmpac and Amcor Plc exemplify contrasting scale positions within the supplier base. ProAmpac occupies a position representing multi-site regional footprint strategies for just-in-time pharmaceutical distribution contracts. Amcor Plc anchors the integrated laminate film supply archetype through captive resin and substrate production. Oliver Healthcare Packaging sits within the specialized sterile barrier tier, reflecting converter strategies focused on hospital pharmacy unit-dose format validation.
| Leading Market Players |
|---|
| ProAmpac |
| Amcor Plc |
| Oliver Healthcare Packaging |
| Nelipak Corporation |
| Glenroy |
| GFR Pharma |
| American FlexPack |
| Terrapack |
| Ampac Holdings |
| Others |
Supply & Pricing Matrix
Cleanroom capacity utilization above eighty percent in Germany and Switzerland establishes price floors that regional converters cannot undercut without sacrificing ISO 11607 compliance. Scale advantages in vapor-deposition equipment amortization create defensive moats for incumbent laminate suppliers while compressing margin structures for mid-cap heat-sealing operations.
Pricing Analysis
Certification level creates the primary spread between ISO 11607-validated sterile barrier systems and commodity polyethylene formats. Three-tier pricing structure separates FDA-grade laminates with full extractables-leachables documentation from CE-marked hospital pharmacy formats and economy blister pouches for oral solids. Cost compression in standard-tier laminates is intensifying because ECHA PFAS restrictions force premature equipment retrofit before amortization cycles complete. Contract packaging organizations exhibit the lowest price sensitivity due to bundled serialization requirements, while generic pharmaceutical distributors in India remain most sensitive to per-unit pouch costs.
Supply Chain Analysis
Germany and Switzerland anchor sterile barrier system manufacturing for European biologics distribution. China and India feed raw material supply for aluminum foil substrates and oriented polypropylene films. The supply chain draws from resin production concentrated in the US Gulf Coast and Middle Eastern feedstock hubs. Single-source vulnerability in vapor-deposition equipment creates chokepoint risk for barrier film qualification. Distribution runs through contract packaging organizations that have displaced traditional pharmaceutical wholesalers in Germany and are compressing layers in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ISO 11607 validation creates switching costs that lock pharmaceutical procurement into incumbent supplier relationships. Network effects in multi-site audit coordination further deepen defensive positioning.
For Market Incumbents: Fortify cleanroom footprints through programmable logic controller upgrades that satisfy EU MDR traceability mandates before qualification timelines compress further. Expand backward integration into aluminum-oxide vapor-deposition capacity to preempt fluoropolymer coating obsolescence driven by ECHA restrictions. Channel control through bundled serialization services represents the critical lever for displacing remaining regional distributors. For New Entrants and Emerging Players: Extractables-leachables documentation services present the most penetrable white-space where ISO 11607-certified incumbents under-serve biotechnology firms with unproven stability data. Target CDSCO-aligned packaging demand from Indian pharmaceutical exporters seeking complex generics export qualification. A go-to-market angle anchored in front-loaded regulatory documentation partnerships with contract manufacturing organizations bypasses direct cleanroom capital requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vapor-deposition-capable manufacturers with validated silicone-oxide barrier films over conventional extrusion converters facing stranded equipment risk. Long-term viability across the analysis window hinges on regulatory compliance depth rather than throughput scale. Acquisition target archetype: mid-cap converters with existing ISO 11607 certification and upgradeable heat-sealer infrastructure. The signal to watch is FDA guidance evolution on packaging suitability for complex generics, which would accelerate qualification timeline compression and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | Validated aseptic processing infrastructure locks in hospital pharmacy unit-dose contracts under EU MDR. |
| Backward Integration into Vapor-Deposition | Captive aluminum-oxide barrier film production defends margin against fluoropolymer coating obsolescence. |
| Extractables-Leachables Documentation Partnership | Front-loaded regulatory services compress qualification timelines for biotechnology firms with novel APIs. |
| Multi-Site ISO 11607 Compliance Coordination | Simultaneous audit readiness across manufacturing locations satisfies pharmaceutical distributor procurement mandates. |
| Sustainable Barrier Coating Transition | Silicone-oxide sealant innovation aligns with EU Green Deal procurement preferences for sterile systems. |
Research Methodology
Initial hypotheses were tested against primary input from sterile barrier engineering directors, pharmaceutical packaging procurement managers, regulatory affairs specialists at contract packaging organizations, and cleanroom operations technicians, then refined through secondary validation. FDA 21 CFR Part 211 guidance documents, EMA MDR implementation bulletins, ISO 11607 technical committee drafts, and customs trade data for laminate film imports provided foundational datasets. Bottom-up capacity estimates from vapor-deposition equipment installations were triangulated against top-down pharmaceutical packaging spend allocations.
Variance decomposition across product type, application, end-user archetype, and material specification dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling that weighted biologics pipeline expansion against resin feedstock volatility. Sterile pouch capacity utilization rates and barrier film oxygen transmission rate improvement curves served as industry-specific forecast inputs throughout the modeling period.
Material uncertainties — regulatory timeline slippage in ECHA PFAS restrictions, FDA complex generics packaging guidance revision, and cleanroom operator wage inflation — sit outside the modeled envelope. Forecasts reflect assumptions about laminate specification migration speed and contract packaging organization procurement authority consolidation. Recalibration cycles align with material shifts in EU MDR enforcement intensity and biologics approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Digital Printed Pouch Market
Pouch
Europe Pouch Packaging Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Paper Pouch Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Child Resistant Pouches Market
Pouch
South Africa Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Doy Pouch Packaging Market
Pouch
Kraft Pouch Market
Pouch
PCR Pouches Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Stand Up Paper Pouches Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market